
 Passive Fire Protection Materials Market | 2026-2036
Passive Fire Protection Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Fire Protection Materials Market Analysis
Mineral wool is consolidating share from traditional cementitious sprays in high-rise passive fire protection. Rockwool International leverages its vertical furnace capacity to anchor supply for European steel-frame projects. Sika AG competes through formulation chemistry that extends cure-speed advantage in intumescent coatings. Akzo Nobel N.V. dominates marine and offshore specification with solvent-free epoxy intumescent platforms.
Passive fire protection materials encompass chemically formulated substances engineered to insulate structural steel, seal penetrations, and compartmentalize flame spread through endothermic reaction, char formation, or thermal insulation with ratings from 30 to 240 minutes. These materials serve the essential commercial purpose of maintaining structural integrity during fire events to enable safe egress and limit property loss. Intumescent coatings command premium positioning in commercial buildings where architectural exposure of steel demands thin-film aesthetics alongside certified protection. Fire resistant boards sustain mature volume in residential retrofitting across multi-family housing stock where surface-mounted application reduces labor cost. Sprayed insulation occupies industrial facility niches requiring rapid coverage of complex duct and truss geometries where troweled or board solutions prove impractical.
Underwriters Laboratories (UL), the British Standards Institution (BSI), and the EU Construction Products Regulation (CPR) collectively define test protocols and CE marking requirements that gate market access across North America and Europe. The National Fire Protection Association (NFPA) 251 and ASTM E119 time-temperature curves shape product development priorities by mandating specific hourly ratings for load-bearing assemblies. Stakeholders must monitor evolving code harmonization between regional test standards as cross-border project contracting intensifies and specification portability becomes a procurement priority.
Market Dynamics
Urban densification across China, India, and Brazil is compressing construction timelines and forcing simultaneous upgrades to fire safety infrastructure in steel-frame high-rises, creating synchronized demand spikes that strain coating formulation capacity and certified installer availability.
Growth Catalysts
- EU Construction Products Regulation:CE marking mandates for reaction-to-fire classification are accelerating material replacement cycles in German and French commercial retrofits.
- Offshore wind installation:Solvent-free epoxy intumescent specifications for North Sea turbine jacket structures are pulling marine-grade formulations into adjacent energy infrastructure.
- Mineral wool furnace capacity:Rockwool International's vertical integration into high-temperature stone wool production is anchoring supply security for European steel-frame projects.
Market Restraints
- Petrochemical input volatility:Epoxy resin and polyisocyanurate precursor costs swing with crude-linked feedstock indices, compressing coating margin stability.
- Specialized applicator concentration:Certified intumescent spray contractors cluster in Western European and US coastal metros, creating bottleneck risk for emerging market project execution.
- Cementitious spray displacement ceiling:Mineral wool boards face thickness and fastening limitations in complex truss geometries where wet-applied cementitious materials retain structural adaptability.
Strategic Opportunities
- Brazilian building code enforcement:São Paulo and Rio de Janeiro municipal fire departments are implementing NFPA-aligned inspection protocols that open specification pathways for imported intumescent systems.
- Prefabricated modular construction:Factory-applied passive fire protection in controlled environments enables quality assurance and labor cost reduction for multi-family housing developers.
- EU Green Deal alignment:EPD-certified low-carbon mineral wool products qualify for public procurement preference under CSRD-linked sustainability criteria.
Industry Challenges
- Certified inspector scarcity:UL and BSI-qualified firestop system inspectors face training pipeline gaps that extend project commissioning timelines in fast-track developments.
- Legacy substrate compatibility:Existing steel structures with aged paint films require surface preparation protocols that add labor cost and schedule risk to retrofit specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Fire Protection Materials Market |
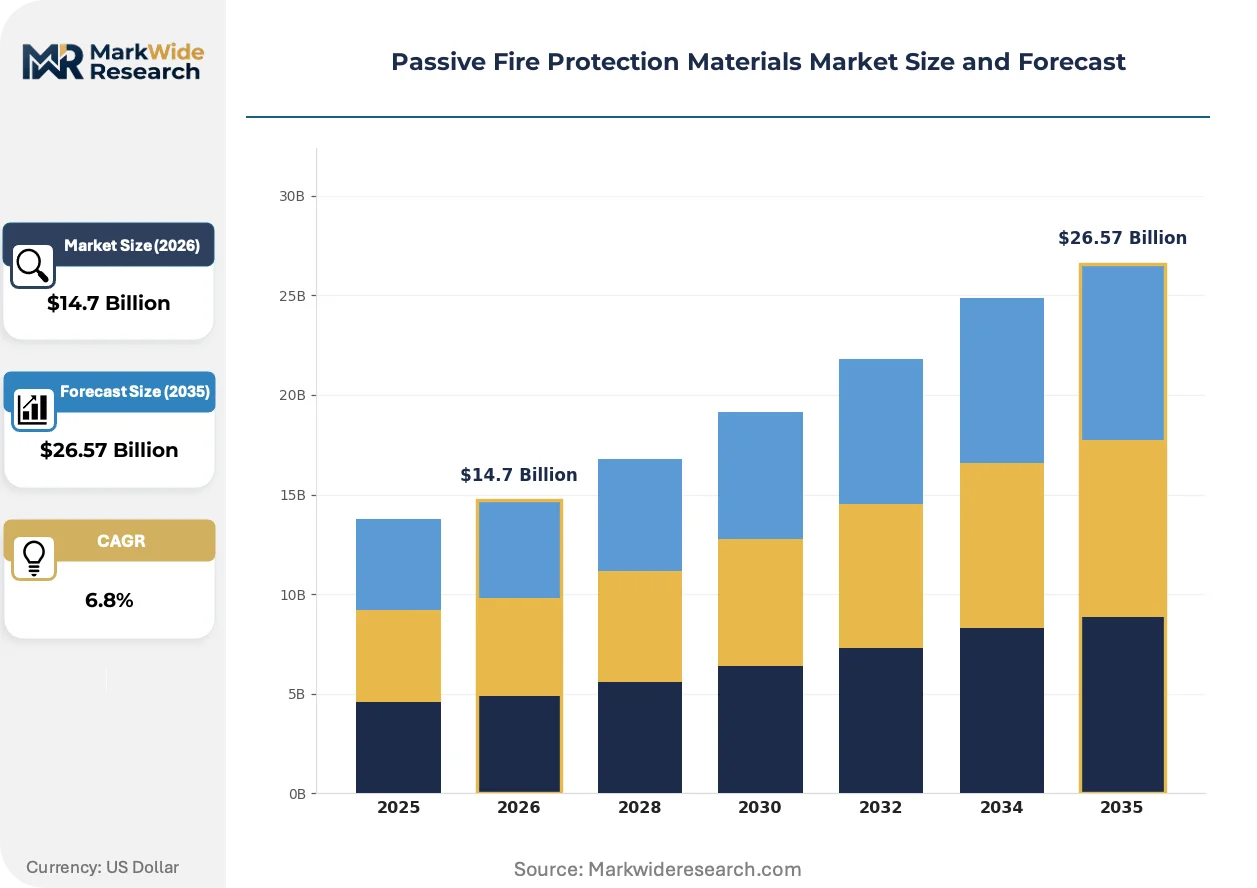
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Fire Stop Systems, Fire Resistant Boards, Sprayed Insulation Application: Commercial Buildings, Industrial Facilities, Residential Properties, Offshore Structures End User: Construction Companies, Architects, Building Owners, Regulatory Authorities Installation Method: New Construction, Retrofitting, Pre-Engineered Solutions, On-Site Applications |
| Companies Covered | 3M, Akzo Nobel N.V., Sika AG, Hilti Group, Rockwool International, PPG Industries, Inc., Hempel A/S, Sherwin-Williams Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Fire Protection Materials Market Emerging Trajectories
Formulation chemistry and application methodology are converging to address the tension between architectural visibility requirements and escalating fire resistance ratings in commercial steel construction.
Thin-film waterborne intumescent coatings are expanding into atrium and lobby structures where exposed steel aesthetics demand invisible protection. Museum and airport terminal developers in the United States and Netherlands specify these systems for 120-minute ratings at sub-3mm dry-film thickness. The technology is expanding into premium commercial segments previously reserved for solvent-borne epoxy platforms.
REACH restrictions on halogenated flame retardants are forcing reformulation of char-forming additives in European-manufactured intumescent systems. ECHA substance evaluation timelines are compressing R&D windows for coating suppliers serving EU export markets. German and French specification engineers now prioritize phosphorus-nitrogen synergist packages with established SVHC clearance.
Asset owner purchasing departments are consolidating fire protection specification authority under centralized procurement functions, displacing architect-driven material selection in repeat-tenant commercial developments. Third-party certified contractor networks are replacing traditional subcontractor bidding in UK and Australian commercial construction. This concentration is most visible in London and Sydney build-to-rent residential towers where single-source fire protection packages reduce interface risk.
Passive Fire Protection Materials Market Segmentation
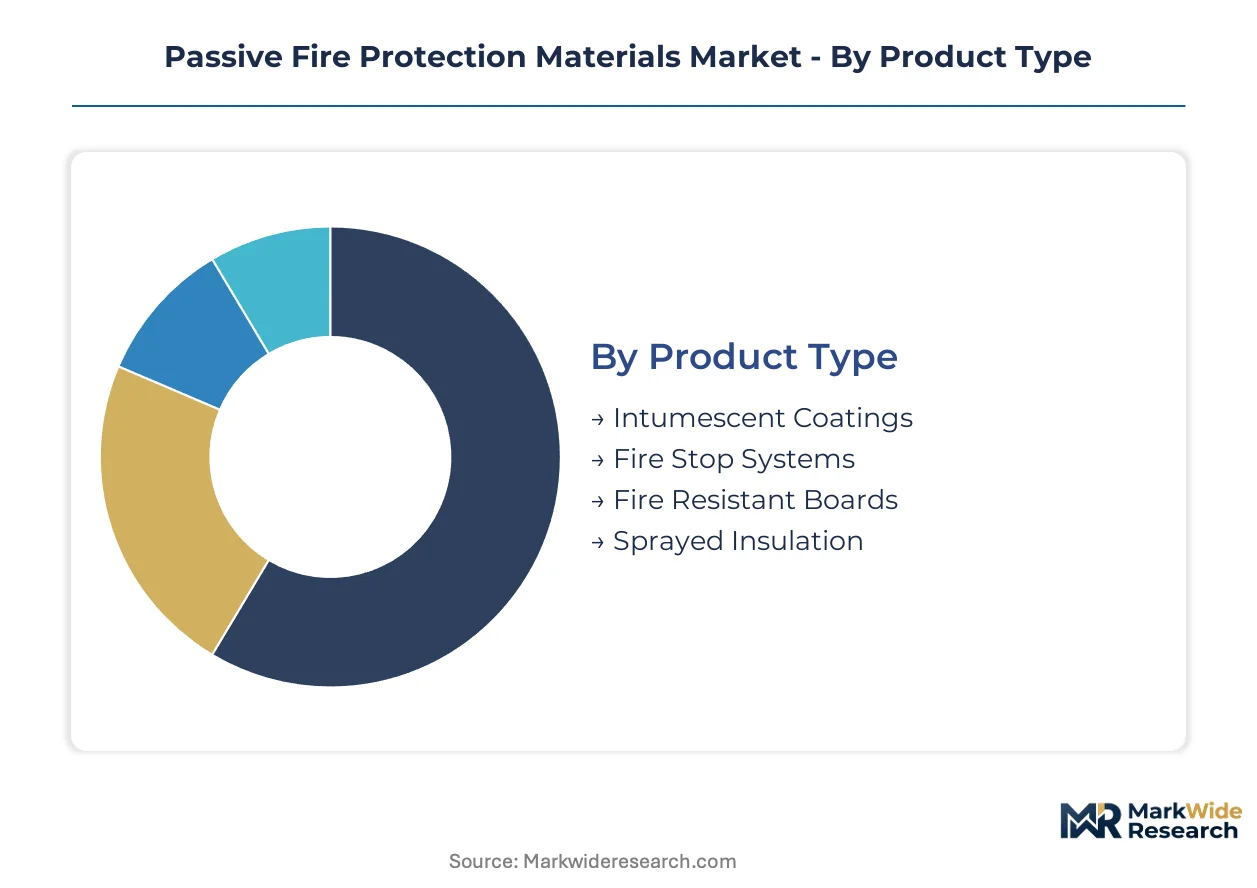
Segmentation in passive fire protection materials reveals divergent procurement logics across buyer types. Specification authority concentrates differently by project phase, driving material selection toward thin-film aesthetics in early design versus cost-optimized boards in late-stage retrofitting.
Product Type:
Architectural visibility requirements and fire resistance ratings jointly determine material selection, with premium positioning attaching to systems that reconcile exposed steel aesthetics with certified protection.
- Intumescent Coatings:Chemically formulated thin-film systems that expand into insulating char layers when heated, providing 30- to 240-minute ratings. Demand clusters in United States commercial atriums and Netherlands airport terminals where sub-3mm dry-film thickness preserves steel visibility. REACH restrictions on halogenated additives are forcing phosphorus-nitrogen reformulation cycles.
- Fire Stop Systems:Penetration sealing assemblies comprising intumescent putties, mineral wool plugs, and silicone foams that restore compartmentation integrity around cables and pipes. German and French commercial retrofits under EU Construction Products Regulation CE marking mandates are accelerating replacement demand for legacy installations.
- Fire Resistant Boards:Rigid mineral wool or calcium silicate panels surface-mounted to structural elements. Multi-family housing stock in United Kingdom and Australia favors these for residential retrofitting where labor cost reduction outweighs aesthetic considerations.
- Sprayed Insulation:Wet-applied cementitious or fibrous materials delivering rapid coverage of complex duct and truss geometries. Industrial facility niches in Brazil and India retain this method where board fastening proves impractical.
Volume sits with Fire Resistant Boards; growth tilts toward Intumescent Coatings.
Application:
Project scale and regulatory scrutiny intensity create tiered demand patterns, with offshore specifications pulling marine-grade formulations into adjacent energy infrastructure.
- Commercial Buildings:Steel-frame high-rises, atriums, and lobby structures requiring architectural exposure of protected elements. United States developers specify thin-film intumescent systems for 120-minute ratings in premium segments.
- Industrial Facilities:Manufacturing plants, warehouses, and power generation sites with complex mechanical penetrations. China and India urban densification is compressing construction timelines and synchronizing fire safety upgrades.
- Residential Properties:Multi-family housing and single-family retrofits where surface-mounted boards reduce skilled labor requirements. United Kingdom build-to-rent towers are consolidating specification authority under centralized procurement functions.
- Offshore Structures:North Sea wind turbine jackets and oil platform modules demanding solvent-free epoxy intumescent specifications. Marine-grade formulations are expanding into adjacent offshore wind installation demand.
Commercial Buildings anchor current specification volume; Offshore Structures are climbing the fastest.
End User:
Procurement authority migration from architects to asset owner purchasing departments is reshaping supplier relationship structures.
- Construction Companies:General contractors executing new-build and retrofit installations. Certified intumescent spray contractor scarcity in Western European and United States coastal metros creates bottleneck risk.
- Architects:Design-phase specifiers increasingly constrained by centralized owner procurement functions in repeat-tenant commercial developments. United States museum and airport terminal projects retain architect-driven material selection.
- Building Owners:Asset operators consolidating fire protection specification authority under centralized procurement. London and Sydney build-to-rent towers favor single-source packages reducing interface risk.
- Regulatory Authorities:Municipal fire departments and building code enforcement agencies. São Paulo and Rio de Janeiro are implementing NFPA-aligned inspection protocols opening specification pathways for imported systems.
Construction Companies process immediate volume; Building Owners are gaining specification control fastest.
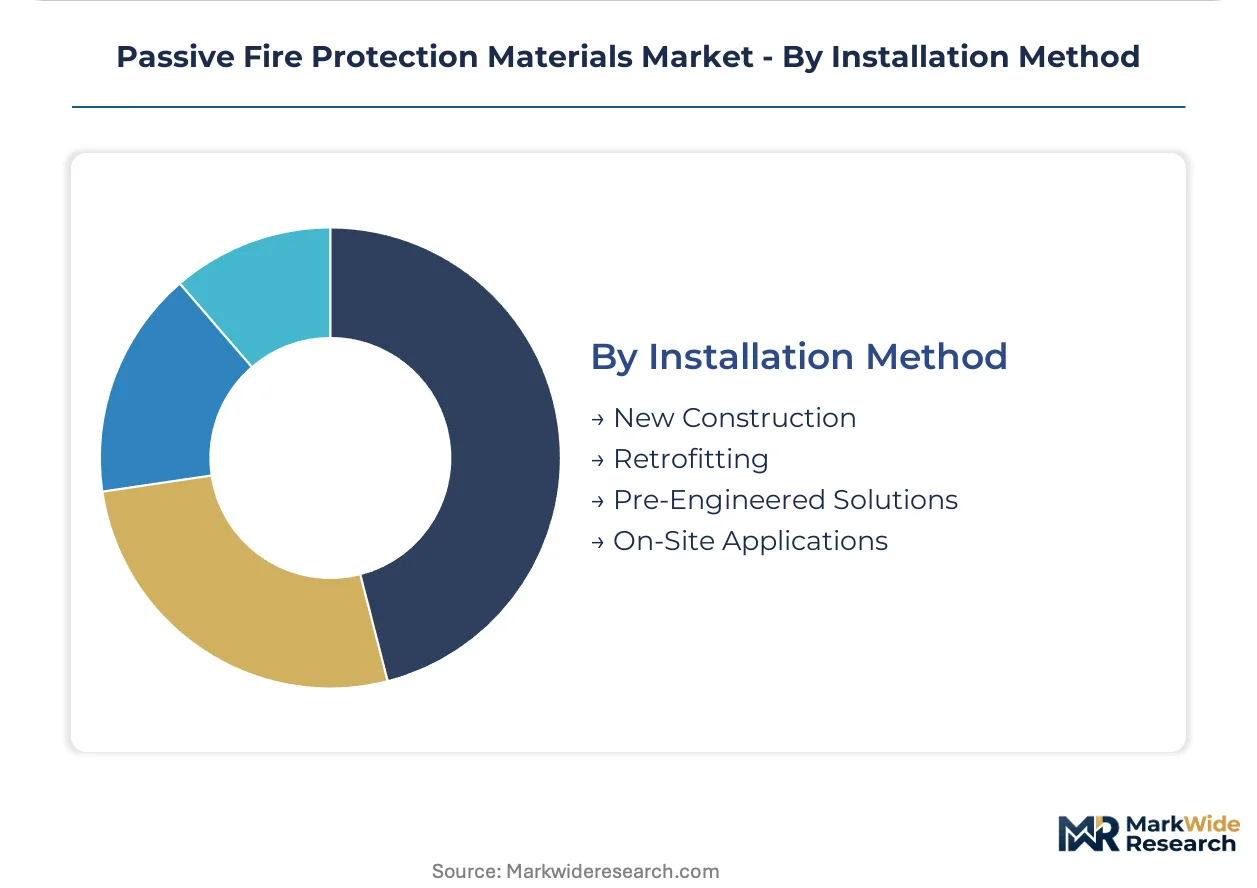
Installation Method:
Factory versus field application tradeoffs center on quality assurance, labor cost, and project timeline compression.
- New Construction:Greenfield projects integrating passive fire protection during primary structural erection. China steel-frame high-rise construction is straining coating formulation capacity.
- Retrofitting:Existing building upgrades responding to code enforcement strengthening or insurance mandates. Germany and France commercial retrofits under EU Construction Products Regulation accelerate material replacement.
- Pre-Engineered Solutions:Factory-applied protection in controlled environments for modular construction. Multi-family housing developers capture quality assurance and labor cost reduction.
- On-Site Applications:Field-installed wet and dry systems requiring certified applicator networks. Specialized contractor concentration in Western Europe and United States creates emerging market execution risk.
New Construction holds established volume; Pre-Engineered Solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building developers in the United States and tightening EU fire safety codes are concentrating demand for intumescent coatings and mineral wool systems. Steel-frame high-rise construction across China, India, and Brazil is synchronizing material procurement cycles.
United States
Museum and airport terminal developers specify thin-film waterborne intumescent systems for 120-minute ratings at sub-3mm thickness. NFPA 251 and ASTM E119 time-temperature curves mandate hourly ratings for load-bearing assemblies. UL-qualified firestop system inspectors face training pipeline gaps that extend commissioning timelines in fast-track developments.
Germany
EU Construction Products Regulation CE marking mandates accelerate material replacement cycles in commercial retrofits. ECHA substance evaluation timelines compress R&D windows for coating suppliers serving export markets. Frankfurt and Munich steel-frame projects anchor demand for phosphorus-nitrogen synergist packages with established SVHC clearance.
France
Specification engineers prioritize low-carbon mineral wool products qualifying for public procurement preference under CSRD-linked sustainability criteria. ANSM and CNIL-aligned enforcement structures shape compliance timelines. Paris commercial towers consolidate fire protection specification authority under centralized procurement functions.
China
Urban densification compresses construction timelines and strains coating formulation capacity for steel-frame high-rises. GB standards and MIIT industrial policy frameworks shape product certification pathways. Yangtze River Delta and Pearl River Delta construction clusters synchronize fire safety infrastructure upgrades.
Brazil
São Paulo and Rio de Janeiro municipal fire departments implement NFPA-aligned inspection protocols opening specification pathways for imported intumescent systems. ANVISA regulatory frameworks intersect with building code enforcement. Industrial facility niches retain sprayed cementitious insulation where board fastening proves impractical.
Passive Fire Protection Materials Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation chemistry leaders commanding premium positioning in visible steel applications while mineral wool producers anchor volume in concealed assemblies. The market structure tilts toward consolidated supply in furnace-dependent mineral wool alongside fragmented coating formulation tiers. Three archetypes dominate: vertically integrated mineral wool producers, specialty chemical formulators with cure-speed advantages, and marine-grade epoxy specialists. Capacity expansion in high-temperature stone wool production and strategic partnerships for certified installer networks represent the dominant competitive vectors.
Among European-based material producers, Rockwool International exemplifies furnace-anchored supply security for steel-frame projects, while Sika AG occupies a position within specialty chemical formulation tiers. Akzo Nobel N.V. represents the marine-grade specification segment serving offshore wind and platform infrastructure. These three entities collectively illustrate the geographic and technological segmentation governing competitive positioning across architectural, industrial, and energy infrastructure end-uses.
| Leading Market Players |
|---|
| 3M |
| Akzo Nobel N.V. |
| Sika AG |
| Hilti Group |
| Rockwool International |
| PPG Industries, Inc. |
| Hempel A/S |
| Sherwin-Williams Company |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
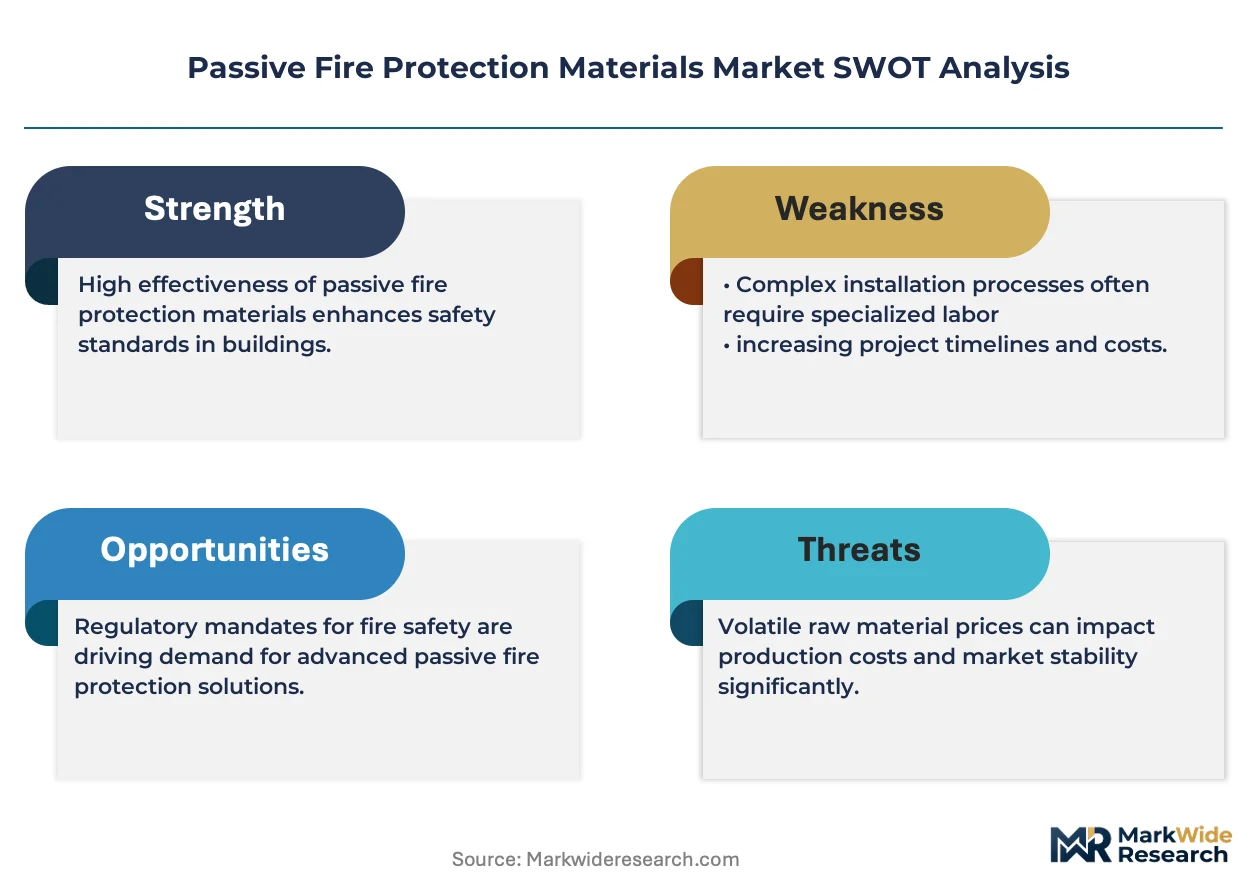
Certified intumescent spray applicator concentration in Western European and United States coastal metros widens pricing-tier spreads between premium architect-specified systems and economy-grade cementitious alternatives, as labor-cost differentials compound raw material volatility.
Pricing Analysis
Volume sits with fire-resistant boards while margins concentrate in intumescent coatings. Pricing stratifies across premium thin-film aesthetic systems, standard mineral wool assemblies, and economy cementitious sprays based on certification grade and installation complexity. Cost compression in standard tiers intensifies because epoxy resin and polyisocyanurate precursor costs swing with crude-linked feedstock indices. Industrial facility buyers exhibit highest price sensitivity; museum and airport terminal developers show lowest.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and re-certification of firestop systems create secondary material channels in mature European markets. Supply concentrates in Germany, France, and China for coating formulation; Denmark and the United States anchor mineral wool furnace capacity. Raw material dependencies center on epoxy resins, phosphorus-nitrogen synergist packages, and high-temperature stone wool feedstock. Single-source vulnerability runs through certified applicator networks. Distribution runs through specification-influencer channels: architects, UL-qualified inspectors, and centralized procurement functions at asset owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: vertical furnace capacity for high-temperature stone wool production props pricing power for incumbent mineral wool producers while coating formulation capacity strains under synchronized global demand.
For Market Incumbents: Cement supply security through captive furnace capacity additions in European steel-frame corridors. Lock in certified installer network exclusivity to defend against emerging modular construction entrants. Prioritize phosphorus-nitrogen formulation R&D to maintain EU market access under REACH substance evaluation timelines. For New Entrants and Emerging Players: Certified contractor networks represent the most penetrable channel wedge for imported intumescent systems in Brazilian municipal markets. Target São Paulo and Rio de Janeiro build-to-suit commercial towers where NFPA-aligned inspection protocols are newly implemented. Lead with factory-applied pre-engineered solutions to bypass field-applicator scarcity. For Investors and Strategic Acquirers: Re-rating potential sits with specialty chemical formulators possessing cure-speed advantages given offshore wind installation pull-through into adjacent energy infrastructure. Long-term viability favors players with SVHC-cleared additive packages and EPD-certified low-carbon product lines. Monitor EU Construction Products Regulation harmonization timelines with emerging market codes as inflection signal for specification portability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | UL and BSI-qualified contractor pipelines reduce project commissioning risk in fast-track developments. |
| Backward Integration into Additive Supply | In-house phosphorus-nitrogen synergist production secures REACH compliance and margin stability. |
| Pre-Engineered Modular Partnership | Factory-applied protection contracts with multi-family housing developers capture quality assurance premiums. |
| Offshore Wind Specification Entry | Solvent-free epoxy intumescent qualifications for North Sea turbine jackets open adjacent energy infrastructure. |
| EPD Certification Investment | Environmental Product Declaration credentials unlock EU Green Deal public procurement preference under CSRD-linked criteria. |
Methodological Framework
Document review covered EU Construction Products Regulation filings, UL certification directories, and ASTM E119 test protocol archives, complemented by interviews with passive fire protection specification engineers, certified intumescent spray contractors, mineral wool plant operations managers, and centralized procurement directors at commercial real estate asset owners. Secondary validation drew from SEC 10-K disclosures of listed coating formulators, trade customs data for epoxy resin imports, and fire safety code enforcement records from São Paulo and Rio de Janeiro municipal departments. Bottom-up project pipeline analysis and top-down construction spend triangulation anchored market sizing.
Segment-level demand outputs across product type, application, end user, and installation method dimensions were generated through the analytical framework, with CAGRs derived from time-series regression against construction permit volumes and regulatory enforcement intensity indices. Industry-specific forecast inputs incorporated steel-frame high-rise completion rates in Yangtze River Delta and Pearl River Delta clusters, plus offshore wind turbine installation schedules for North Sea developments.
Caveats apply where ECHA substance evaluation timelines, petrochemical feedstock volatility, or certified inspector training pipeline gaps could materially shift the outlook. Practitioners should monitor EU-CPR and NFPA code harmonization progress, REACH SVHC list updates, and modular construction adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Global Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Insulation Products Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market