
 Superhydrophobic Coatings Market | 2026-2036
Superhydrophobic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Superhydrophobic Coatings Market Intelligence
The bundling of application-specific formulations with proprietary spray coating equipment is consolidating buyer preference toward integrated system providers. P2i Ltd leverages its specialization in pulsed plasma deposition technology to offer complete solutions for electronics manufacturers. In contrast, PPG Industries competes on its vast distribution network and ability to scale production for automotive and aerospace clients. NEI Corporation differentiates through its focus on advanced nanoparticle-based materials for niche industrial applications.
Superhydrophobic coatings are surface treatments engineered for extreme water repellency, achieving water contact angles above 150 degrees. This effect arises from hierarchical surface structures, often created with fluoropolymers or nano coatings, that trap air to reduce liquid contact. Fluoropolymer coatings maintain a significant share in industrial uses, but nano coatings are advancing rapidly due to superior performance. The aerospace end-user segment commands high value for anti-icing, while electronics applications drive volume for moisture protection.
Regulatory scrutiny from bodies like Europe's ECHA on PFAS chemicals and the US EPA on volatile organic compounds (VOCs) influences formulation choices. In China, MEE directives on industrial emissions and water usage are pushing manufacturers toward more environmentally benign application processes like sol-gel. The critical decision for suppliers involves balancing the performance of fluorinated materials against the regulatory risks and the development costs of alternative chemistries.
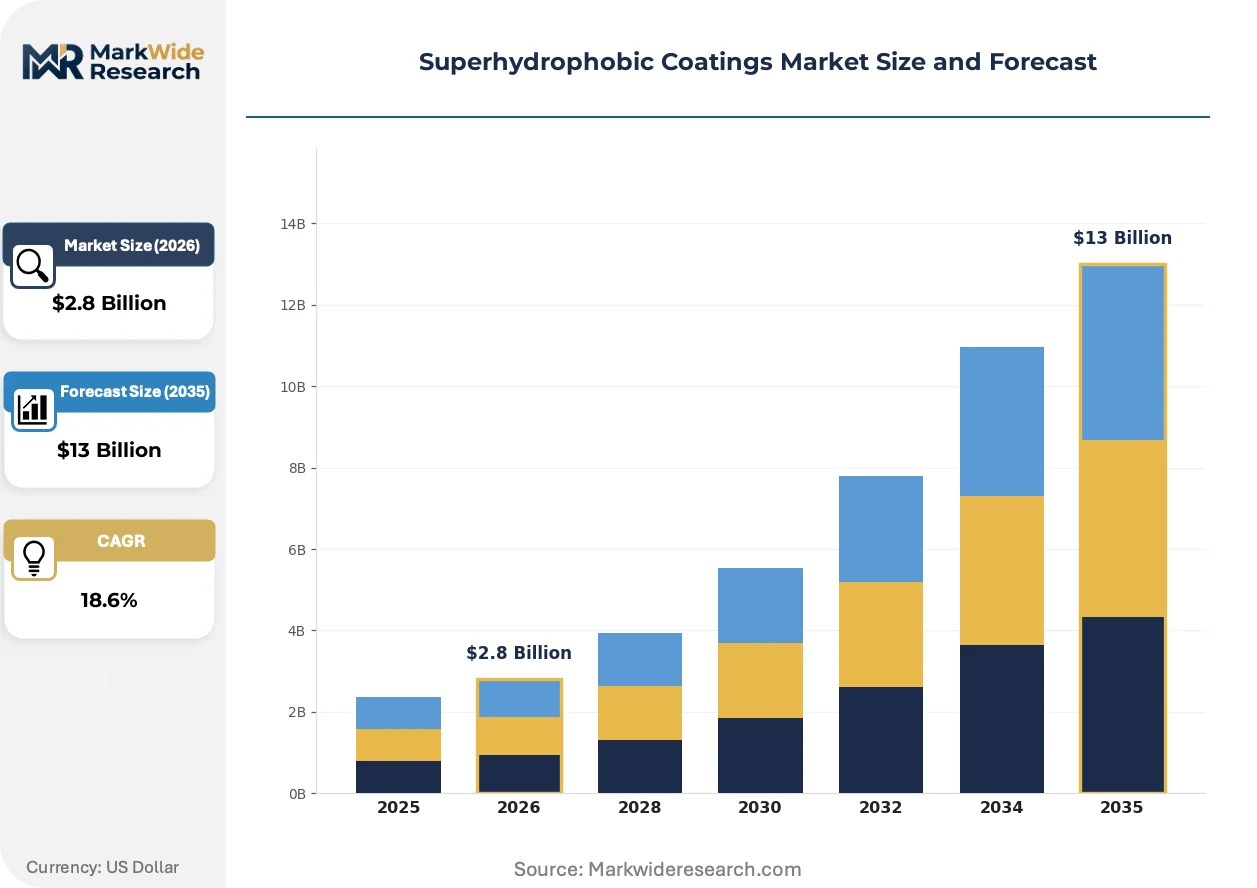
Market Dynamics
The market's central dynamic involves the conflict between the superior performance of traditional fluorinated chemistries and intensifying regulatory pressure from bodies like Europe's ECHA. This tension accelerates research and development into more durable, non-fluorinated nano-coating alternatives and sustainable application processes.
Growth Catalysts
- Nano-coating Durability:Advances in creating more abrasion-resistant nano coatings are expanding their viability beyond electronics into demanding sectors like aerospace, where long-term performance is critical for anti-icing functions.
- Electronics Miniaturization:Demand for effective moisture protection for densely packed components is rising, driven by advanced electronics manufacturing clusters in South Korea and Taiwan.
- Aerospace Anti-Icing:The non-negotiable requirement for reliable anti-icing solutions on aircraft surfaces to ensure operational safety sustains high-value demand for superhydrophobic coatings in the aerospace industry.
Market Restraints
- PFAS Regulation:Increasing scrutiny and restrictions on per- and polyfluoroalkyl substances (PFAS) by the US EPA and Europe's ECHA create significant compliance costs and formulation challenges for manufacturers.
- Mechanical Abrasion:The delicate, micro-structured surfaces essential for superhydrophobicity remain susceptible to physical wear, limiting the coating's effective lifespan in high-contact or abrasive environments.
- High Input Costs:The complex synthesis of advanced nanoparticles and specialized fluoropolymers requires substantial capital investment, translating to higher initial product costs for end-users compared to conventional coatings.
Strategic Opportunities
- Medical Device Coatings:The anti-fouling properties of superhydrophobic surfaces offer significant potential for coating surgical instruments, catheters, and implants to reduce biofilm formation and infection risk.
- Bio-Inspired Materials:Research into non-fluorinated, sustainable materials that mimic natural superhydrophobic surfaces, such as the lotus leaf, provides a pathway to develop high-performance, eco-friendly alternatives.
- Automotive Sector in Germany:Application on sensors, cameras, and windshields for self-cleaning properties in Germany's advanced automotive industry represents a significant, underpenetrated growth vector.
Industry Challenges
- Application Scalability:Adapting precise laboratory deposition methods, such as pulsed plasma, for large-scale, cost-effective industrial production remains a primary operational hurdle for coating applicators.
- Performance Metrology:The absence of universally accepted standards for testing long-term durability and abrasion resistance complicates product evaluation and slows procurement cycles for industrial buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superhydrophobic Coatings Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Coatings, Fluoropolymer Coatings, Nano Coatings, Water-Soluble Coatings End User: Aerospace, Automotive, Electronics, Textiles Application: Self-Cleaning Surfaces, Anti-Fogging, Anti-Icing, Oil Repellency Technology: Sol-Gel, Layer-by-Layer, Spray Coating, Dip Coating |
| Companies Covered | NEI Corporation, Aculon, P2i Ltd, UltraTech International Inc., Rust-Oleum, Cytonix, 3M, PPG Industries, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superhydrophobic Coatings Market Strategic Shifts & Innovations
A fundamental shift toward integrated solutions, which combine specialized material formulations with proprietary application equipment, is reconfiguring the competitive landscape. This evolution is amplified by regulatory pressures that favor more sustainable chemistries and contained, efficient application processes.
Advanced nanoparticle-based coatings create hierarchical surface topographies that achieve extreme water repellency through a combination of chemical composition and physical structure. Electronics manufacturers in South Korea and Taiwan are rapidly adopting these formulations to protect sensitive components from moisture ingress. The development of more durable nano coatings that resist abrasion is unifying performance requirements for both anti-icing in aerospace and moisture protection in electronics.
Europe's ECHA continues to tighten restrictions on PFAS chemistries under REACH, while China's MEE directives target industrial emissions and water usage. These dual pressures are forcing a re-evaluation of fluoropolymer-based formulations, which have long dominated the market. Consequently, suppliers are accelerating investment in non-fluorinated alternatives and environmentally benign application methods like sol-gel to maintain market access.
Buyers are increasingly favoring bundled solutions that include not just the coating material but also the specialized deposition equipment and process know-how. This disrupts the traditional model of selling coatings as a standalone chemical product, putting pressure on suppliers without integrated system capabilities. This trend is most visible within advanced electronics manufacturing, where process control and integration with existing production lines are critical procurement criteria.
Superhydrophobic Coatings Market Segmentation
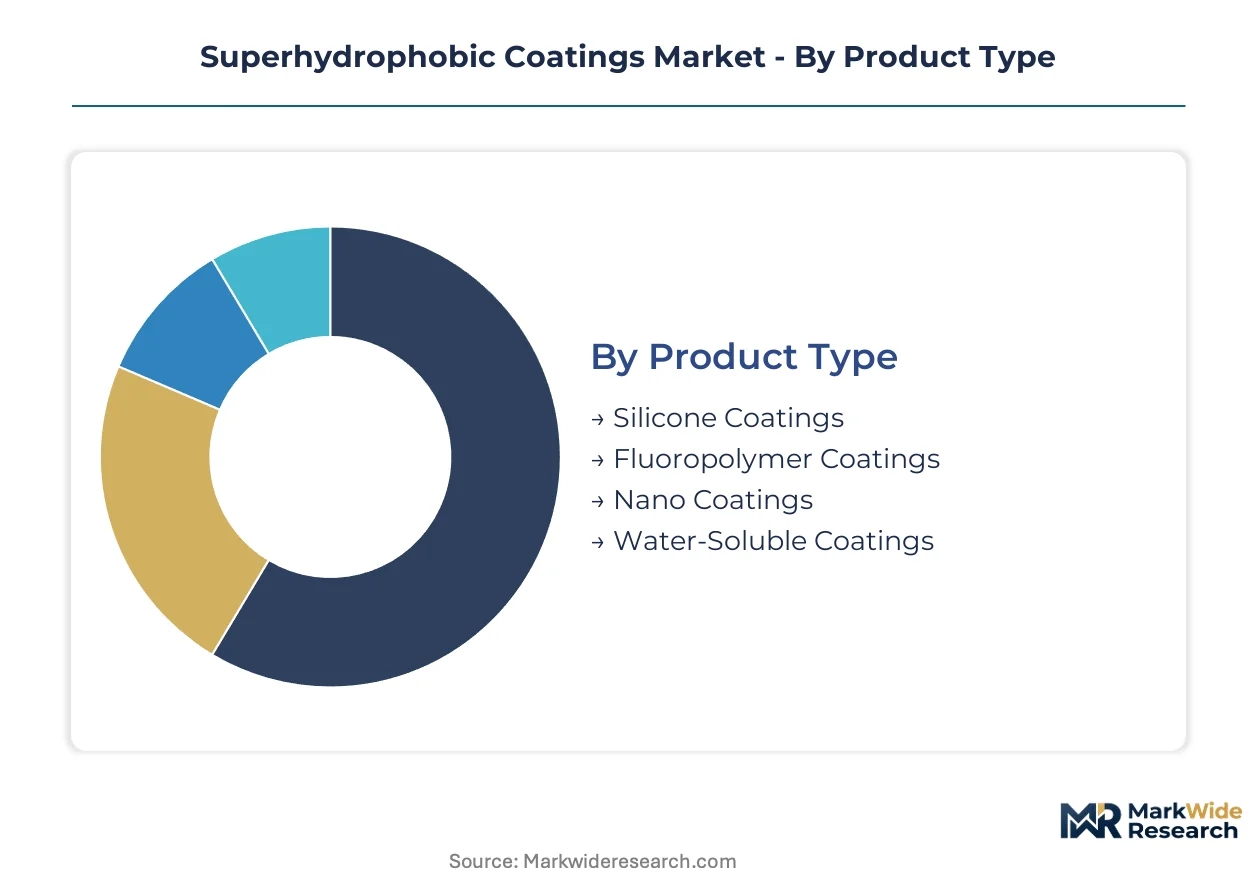
The superhydrophobic coatings market exhibits diverse segmentation, reflecting varied material science, end-user requirements, and application methodologies. Understanding these distinct segments illuminates the specific technological advancements and regulatory pressures influencing product development and market adoption. Each category reveals unique commercial dynamics and strategic opportunities for industry participants.
Product Type:
Supply concentration in product types reflects the established manufacturing capabilities for traditional materials alongside the specialized production of advanced formulations. Manufacturers are adapting their output to meet evolving performance and regulatory demands across diverse industries.
- Silicone Coatings:These coatings utilize silicone polymers to achieve water repellency, often employed for their flexibility and thermal stability in moderate industrial environments. Demand is observed in general industrial applications requiring basic moisture resistance.
- Fluoropolymer Coatings:These materials leverage the low surface energy of fluorinated compounds for extreme water repellency, maintaining a significant share in demanding industrial uses like aerospace. Regulatory scrutiny from Europe's ECHA on PFAS chemicals drives research into alternatives.
- Nano Coatings:These advanced formulations create hierarchical surface structures using nanoparticles, delivering superior performance and abrasion resistance. Demand is accelerating within advanced electronics manufacturing clusters in South Korea for sensitive component protection.
- Water-Soluble Coatings:Formulated for easier application and environmental compliance, these coatings offer a more benign alternative to solvent-based systems. Their adoption is growing in less demanding applications where environmental regulations are stringent.
Fluoropolymer Coatings absorb the bulk of installed capacity; Nano Coatings are expanding most quickly.
End User:
End-user segments define the specific performance requirements and value propositions for superhydrophobic coatings, with application criticality driving material selection. Each industry prioritizes distinct attributes, influencing product development and market penetration strategies.
- Aerospace:This segment commands high value for superhydrophobic coatings due to the non-negotiable requirement for reliable anti-icing functions on aircraft surfaces. Operational safety and performance in extreme conditions are paramount for aerospace clients.
- Automotive:Coatings in the automotive sector enhance visibility and reduce maintenance, particularly for self-cleaning surfaces on sensors, cameras, and windshields. Germany's advanced automotive industry represents a significant growth vector for these applications.
- Electronics:Miniaturization and component density drive demand for effective moisture protection in advanced electronics manufacturing. Clusters in Taiwan are rapidly adopting these coatings to safeguard sensitive components from ingress.
- Textiles:Superhydrophobic treatments for textiles create stain-resistant and waterproof fabrics without compromising breathability. This application targets performance apparel and protective gear.
The Aerospace sector consistently drives the highest value demand; Electronics applications are gaining share fastest.
Application:
Application types dictate the specific functional benefits delivered by superhydrophobic coatings, ranging from passive protection to active performance enhancement. The diversity of applications underscores the technology's versatility across industrial and consumer products.
- Self-Cleaning Surfaces:These coatings repel dirt and dust, allowing water to carry away contaminants, reducing maintenance needs for architectural glass and vehicle exteriors. Medical device coatings for surgical instruments also utilize this property.
- Anti-Fogging:Preventing condensation on optical surfaces, anti-fogging applications are critical for eyewear, camera lenses, and industrial sensors. This enhances clarity and operational reliability in humid environments.
- Anti-Icing:Superhydrophobic surfaces inhibit ice formation by reducing water adhesion, a critical function for aviation safety and wind turbine efficiency. The aerospace industry relies heavily on this specific application.
- Oil Repellency:Oleophobic properties, often combined with superhydrophobicity, prevent oil and grease adhesion, beneficial for industrial equipment and protective clothing. This extends material lifespan and reduces cleaning cycles.
Anti-Icing applications currently represent the largest segment by value; Self-Cleaning Surfaces are climbing the fastest.
Technology:
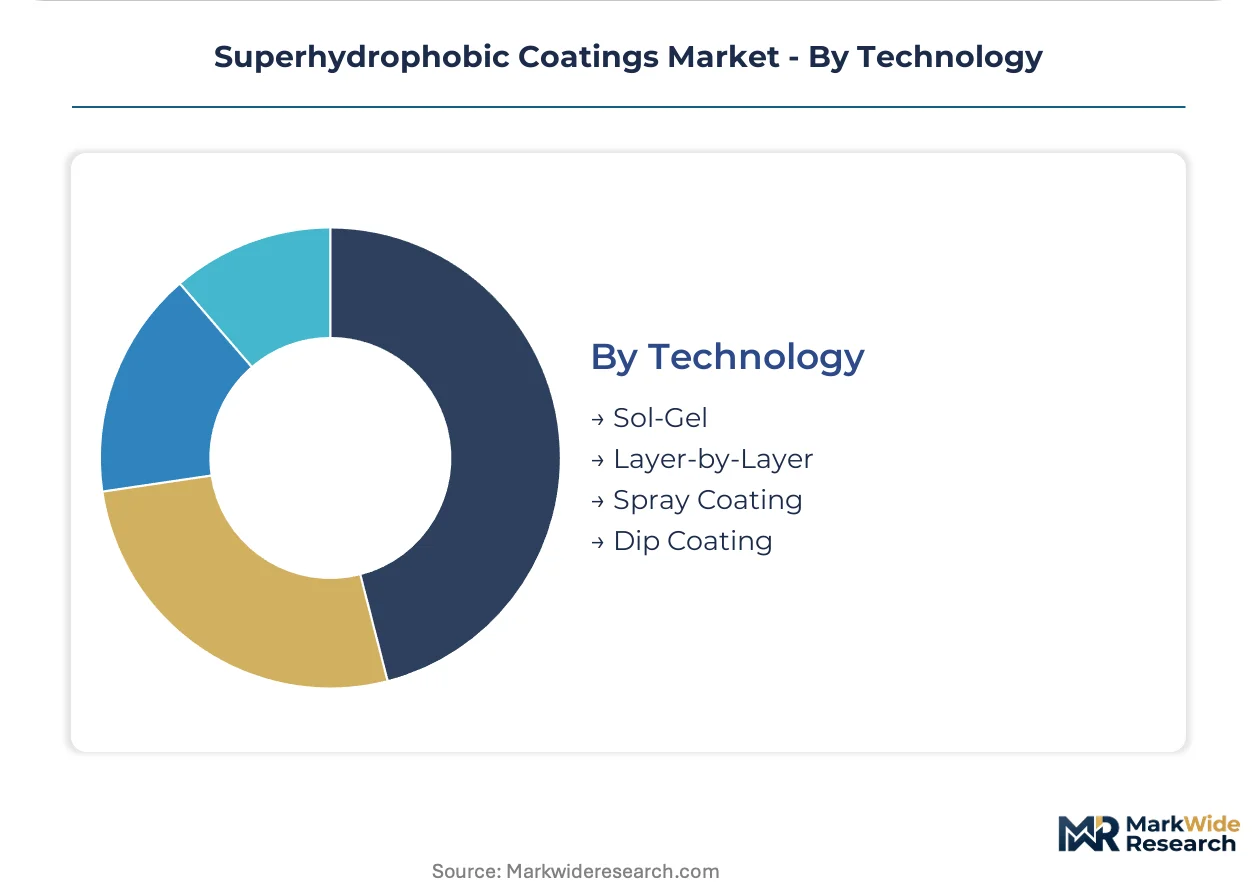
Technology segmentation reflects the diverse methods employed for depositing superhydrophobic layers, each offering distinct advantages in terms of precision, scalability, and material compatibility. Process innovation remains central to expanding market access and reducing application costs.
- Sol-Gel:This chemical process creates ceramic-like coatings at low temperatures, enabling environmentally benign application methods. China's MEE directives on industrial emissions promote sol-gel adoption.
- Layer-by-Layer:This deposition technique involves sequential adsorption of thin films, offering precise control over coating thickness and structure. It is often used for creating multi-functional surfaces in research settings.
- Spray Coating:A widely used and scalable method, spray coating applies liquid formulations onto various substrates, often bundled with proprietary equipment. This technology facilitates high-volume production for automotive and aerospace clients.
- Dip Coating:Substrates are immersed in a liquid coating solution, providing uniform coverage for complex geometries. This cost-effective method suits high-volume production of smaller components.
Spray Coating dominates industrial application volumes; Sol-Gel methods show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production and consumption patterns for superhydrophobic coatings are diverging across key global markets. Advanced manufacturing hubs in Asia specialize in high-volume electronics applications, while European and North American markets prioritize high-value aerospace and automotive segments.
South Korea
Demand for advanced superhydrophobic nano coatings is robust within South Korea's electronics sector. Miniaturization drives requirements for effective moisture protection for densely packed components. The country's environmental regulations push for more sustainable application processes in industrial manufacturing. The Seoul Capital Area and Gyeonggi Province concentrate advanced electronics manufacturing, rapidly adopting these protective formulations.
Taiwan
Taiwan's electronics manufacturing clusters represent a significant consumption center for superhydrophobic coatings. Sensitive components require superior moisture ingress protection to ensure device reliability. The Taiwanese Environmental Protection Administration (EPA) encourages reduced VOC emissions in coating applications. Hsinchu Science Park, a global semiconductor hub, integrates these coatings into its advanced production lines.
Germany
Germany's advanced automotive industry presents a substantial opportunity for superhydrophobic coatings, particularly for sensors, cameras, and windshields. European Union regulations, such as ECHA's scrutiny of PFAS chemicals, influence formulation choices. Automotive manufacturing centers in Bavaria and Baden-Württemberg are exploring self-cleaning and anti-fogging applications for enhanced vehicle safety.
United States
The United States aerospace sector sustains high-value demand for superhydrophobic coatings due to critical anti-icing requirements. US EPA regulations on volatile organic compounds (VOCs) and PFAS chemicals shape product development and material selection. Aerospace manufacturing hubs like Seattle integrate these coatings into aircraft production for operational safety and efficiency.
China
China's industrial sector is increasingly adopting superhydrophobic coatings, driven by demand for enhanced material performance and environmental compliance. MEE directives on industrial emissions and water usage promote the use of environmentally benign application methods like sol-gel. The Yangtze River Delta region, a major industrial and manufacturing powerhouse, sees rising adoption in diverse applications.
Superhydrophobic Coatings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a dynamic competitive environment within the superhydrophobic coatings market. The landscape includes large chemical companies, integrated system providers, and niche material science firms. Strategic archetypes range from broad-portfolio suppliers to highly specialized technology developers. Market participants are increasingly focusing on R&D for non-fluorinated alternatives and bundling material formulations with proprietary application equipment.
On the integrated solutions vector, P2i Ltd leverages its specialization in pulsed plasma deposition technology to offer complete systems for electronics manufacturers. Broad-line chemical suppliers like PPG Industries occupy a position based on vast distribution networks and high-volume production capabilities for automotive and aerospace clients. NEI Corporation exemplifies a material specialist, focusing on advanced nanoparticle-based formulations for niche industrial applications.
| Leading Market Players |
|---|
| NEI Corporation |
| Aculon |
| P2i Ltd |
| UltraTech International Inc. |
| Rust-Oleum |
| Cytonix |
| 3M |
| PPG Industries |
| The Sherwin-Williams Company |
Cost & Logistics Intelligence
Specialized chemical engineers in advanced manufacturing hubs influence pricing tiers, as their expertise drives higher labor costs and differentiates premium formulations. This dynamic shapes the competitive landscape for superhydrophobic coatings, impacting both upstream material costs and downstream application services.
Pricing Analysis
Cost-down pressure on standard industrial formulations accelerates because raw material synthesis remains capital-intensive. Pricing for high-value segments like aerospace typically involves contract-based long-term offtake, ensuring performance guarantees. Price differentiation stems from performance certification, such as aerospace-grade anti-icing, and customization for specific substrate adhesion. Aerospace buyers exhibit low price sensitivity for critical safety applications, while textile and general industrial applications are more price-sensitive.
Supply Chain Analysis
Domestic-content mandates in key automotive markets reshape sourcing strategies for coating components and application equipment. Geographic supply concentration for advanced nanoparticles resides in East Asia, while specialized fluoropolymers often originate from Europe and the United States. The market relies heavily on specific precursor chemicals and high-purity nanoparticles. A structural risk involves regulatory restrictions on PFAS chemicals, potentially disrupting established fluoropolymer supply lines. Distribution runs through direct sales channels for integrated system providers and through broad-line chemical distributors for commodity formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The superhydrophobic coatings market is becoming a vertical-integration race, with players aggressively pursuing proprietary application equipment as a key downstream lever. This strategic focus aims to capture more value across the entire solution delivery process.
For Market Incumbents: Lock in long-term supply agreements for non-fluorinated precursors to mitigate PFAS regulatory risks. Incumbents must also invest in advanced R&D for abrasion-resistant nano coatings, directly addressing the mechanical abrasion threat. Control over proprietary application equipment provides a critical lever for integrated solution providers.
For New Entrants and Emerging Players: Bio-inspired material science provides a technology-first wedge into the market, offering sustainable, non-fluorinated alternatives. Target medical device coatings for anti-fouling properties and automotive sensors for self-cleaning surfaces. The medical device segment presents the most penetrable application due to high-value, niche requirements. A direct-to-specialty-OEM go-to-market angle can bypass established distribution networks.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized nano-coating developers given the accelerating demand from electronics and aerospace. Long-term viability hinges on successful commercialization of durable, non-fluorinated solutions. Acquisition targets include firms with proprietary sol-gel application technologies or unique bio-inspired material patents. The signal to watch is the widespread adoption of non-fluorinated nano coatings in aerospace anti-icing applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces regulatory compliance costs and improves market access in environmentally conscious regions. |
| Product Launch (Non-fluorinated Nano-coatings) | Introduces advanced non-fluorinated nano-coatings for sensitive electronics components. |
| Joint Venture (with equipment manufacturer) | Secures proprietary spray coating equipment integration for complete system offerings. |
| Certification Investment (Aerospace Anti-icing) | Validates anti-icing performance for critical aerospace safety applications. |
| R&D for Bio-Inspired Materials | Develops sustainable alternatives mimicking natural superhydrophobic surfaces. |
Research Approach
ECHA reports, EPA publications, and MEE directives formed the secondary backbone for this market analysis. This analysis combined extensive primary interviews with rigorous secondary validation. R&D directors, procurement leads at OEMs, material scientists, and regulatory affairs specialists provided critical insights. Bottom-up data collection on application volumes and top-down market sizing ensured robust triangulation.
Historical trendline analysis established foundational growth trajectories across the analysis window. Segmentation dimensions modeled included product type, end-user, application, technology, and regional adoption. Compound annual growth rates were derived from projected shifts in technology preference and regulatory impact. Electronics miniaturization rates and aerospace production forecasts served as key industry-specific inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory bans on specific chemistries and rapid shifts in input material costs. Forecasts reflect assumptions regarding technological development and market acceptance of non-fluorinated alternatives. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Antiviral Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Global Graphite Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Europe Powder Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Coating Pigments Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Australia Industrial Coatings Market
Coatings
Sol-Gel Coatings Market