
 Global Sputter Coater Market | 2026-2036
Global Sputter Coater Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sputter Coater Market Foresight
Titanium nitride is broadening its displacement of traditional hard chrome across decorative finishing and tool coating applications, reducing reliance on hexavalent chromium processes. Oxford Instruments leverages cryogenic deposition expertise to anchor its position in research laboratory segments. ULVAC sustains dominance in inline sputter coater architectures for high-throughput electronics fabrication. Buhler competes through captive supply of vacuum components and in-house production of cathode assemblies.
A sputter coater is a vacuum deposition system that ejects material atoms from a solid target through ionized gas bombardment, typically operating at pressures between 0.1 and 10 Pa to form thin films with thickness precision below 10 nanometers. The equipment serves semiconductor fabrication, optical coatings, and magnetic storage industries where uniform adhesion and stoichiometric control determine device performance. Magnetron sputter coaters occupy the largest installed base due to their plasma density advantages and scalability to large-area substrates. High Power Impulse Magnetron Sputtering represents the fastest-growing technology segment as manufacturers seek denser film morphologies and reduced substrate heating. Semiconductor fabrication commands the deepest margin pools among applications, driven by node shrinkage and multi-layer stack complexity in advanced logic and memory devices.
EPA hazardous air pollutant standards and OSHA hexavalent chromium exposure limits constrain coating process choices in US manufacturing facilities, pushing fabricators toward closed-loop sputtering systems. REACH substance restrictions and the EU F-Gas Regulation govern process gas selections and equipment emissions profiles across European installations. China's MEE enforces dual carbon goals that elevate energy efficiency requirements for vacuum deposition equipment in domestic production facilities. Stakeholders must monitor evolving fluorinated gas phase-down schedules and their impact on reactive sputtering process economics.
Market Dynamics
Magnetron sputtering technology is concentrating demand among East Asian semiconductor fabricators as node shrinkage below 3nm demands atomic-scale thickness precision and multi-layer stack complexity.
Growth Catalysts
- High Power Impulse Magnetron Sputtering (HiPIMS):Semiconductor manufacturers in South Korea's Pyeongtaek cluster adopt HiPIMS for denser film morphologies and reduced substrate heating during advanced logic device fabrication.
- REACH substance restrictions:The EU F-Gas Regulation and hexavalent chromium limits under REACH accelerate displacement of traditional electroplating by titanium nitride sputter coatings across decorative finishing and tool coating applications.
- China's dual carbon goals:MEE enforcement of energy efficiency standards for vacuum deposition equipment drives replacement cycles in domestic electronics fabrication facilities.
Market Restraints
- High-purity target material costs:Tantalum, titanium, and noble metal sputtering targets face price volatility tied to mining concentration in conflict-affected regions and refining bottlenecks.
- Technical limitation in reactive sputtering:Process instability during oxide and nitride deposition requires closed-loop gas control systems that extend qualification timelines for new materials.
- Substitution threat from atomic layer deposition:ALD systems capture share in extreme ultraviolet lithography mask fabrication and 3D NAND vertical stack applications where conformality trumps deposition rate.
Strategic Opportunities
- India's semiconductor incentive scheme:PLI scheme allocations for domestic chip fabrication create greenfield demand for magnetron sputter coaters in Gujarat and Tamil Nadu greenfield fabs.
- Solid-state battery electrolyte deposition:Sulfide and oxide solid electrolyte sputtering emerges as a process route for next-generation lithium-metal battery manufacturing.
- Photonics integration in datacom:Silicon photonics foundries require precision tantalum pentoxide and silicon nitride sputtering for waveguide and modulator fabrication.
Industry Challenges
- Vacuum technician scarcity:Specialized skills in plasma diagnostics, residual gas analysis, and cryogenic pump maintenance command premium wages and extend hiring cycles.
- Cleanroom integration complexity:Sputter coater installation in Class 10 environments requires coordinated HVAC, vibration isolation, and electromagnetic interference mitigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sputter Coater Market |
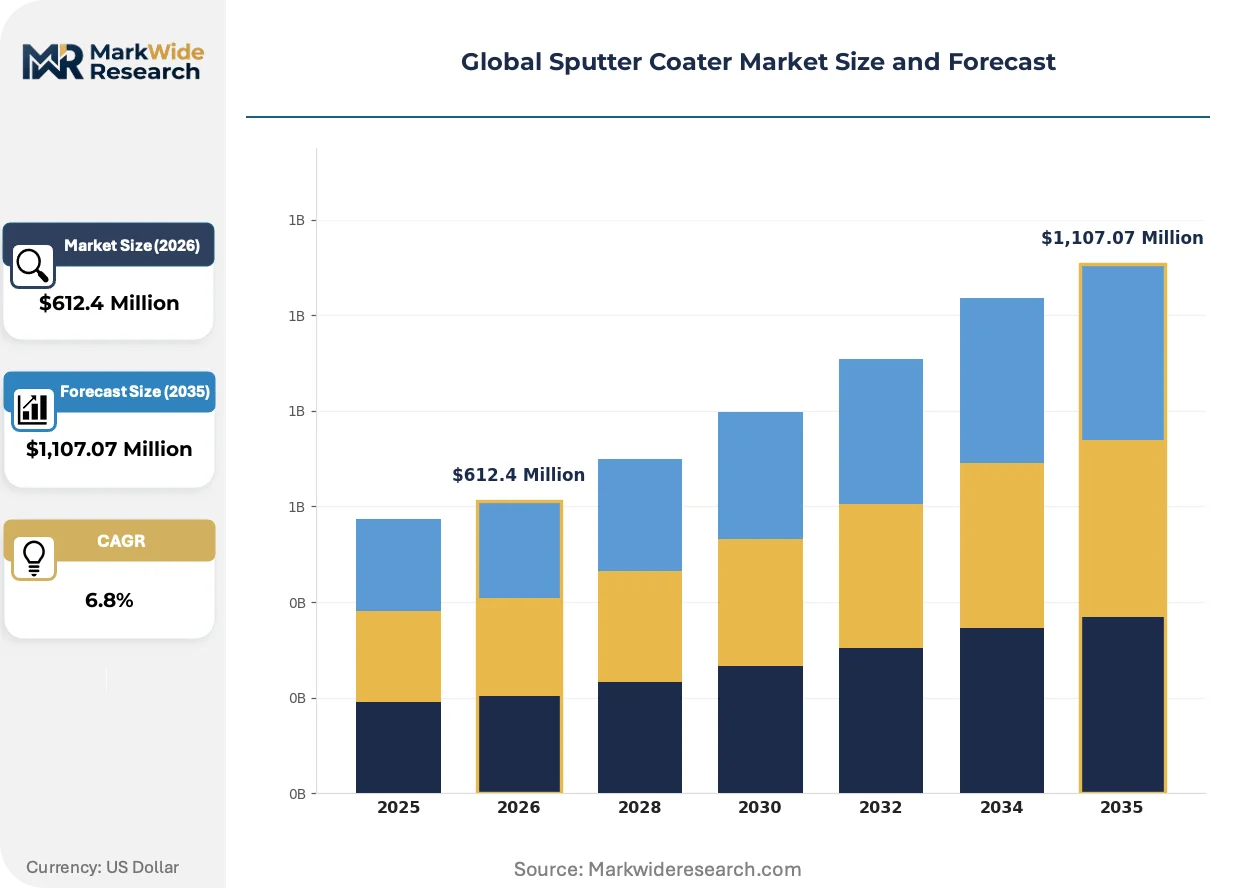
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Sputter Coaters, Inline Sputter Coaters, RF Sputter Coaters, DC Sputter Coaters, Magnetron Sputter Coaters Technology: Reactive Sputtering, Non-reactive Sputtering, Ion Beam Sputtering, High Power Impulse Magnetron Sputtering, Pulsed DC Sputtering Application: Semiconductor Fabrication, Optical Coatings, Magnetic Storage, Decorative Finishing, Solar Cell Manufacturing End User: Electronics Fabricators, Research Laboratories, Optical Manufacturers, Data Storage Firms, Photovoltaic Producers |
| Companies Covered | Buhler, Oxford Instruments, ULVAC, Semicore Equipment, Cressington Scientific Instruments, Veeco Instruments Inc., Quorum Technologies, PLASSYS Bestek, Hitachi High-Tech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sputter Coater Market Shifts & Advancements
Equipment architecture is pivoting toward modular cluster configurations that isolate process chambers for contamination control while enabling parallel processing of heterogeneous film stacks.
Rotatable cylindrical magnetron cathodes is overtaking planar magnetron geometries in architectural glass and display panel fabrication. Solar cell manufacturers in Southeast Asia deploy rotatable targets to maximize material utilization above 80 percent and reduce downtime from target changes. The technology is overtaking incumbent planar configurations in any application requiring film thickness exceeding 500 nanometers.
EPA hazardous air pollutant standards for perfluorinated compounds tighten emissions profiles across US semiconductor fabrication facilities. The regulations force adoption of abatement systems and process gas substitution in reactive sputtering operations. Memory device manufacturers in Idaho and Arizona retrofit existing lines with point-of-use scrubbers to maintain operating permits.
After-sales service unbundling accelerates as captive maintenance teams at major foundries internalize routine consumables replacement and plasma source refurbishment. Original equipment manufacturers respond with tiered service contracts separating hardware warranty from process engineering support. South Korean memory houses lead this transition, negotiating direct target procurement while retaining vendor support for chamber matching and particle reduction protocols.
Global Sputter Coater Market Segmentation
Sputter coater purchasing decisions hinge on throughput requirements, film precision specifications, and integration complexity with existing fabrication lines. Equipment architecture and deposition technology choices cascade through operational economics, maintenance cadence, and regulatory compliance obligations. End-user concentration in semiconductor and photovoltaics clusters shapes regional demand patterns and supplier qualification timelines.
Product Type:
Volume installations favor architectures minimizing chamber downtime, while premium configurations target atomic-scale precision applications.
- Magnetron Sputter Coaters:Dense plasma configurations enable deposition rates exceeding planar cathode designs by an order of magnitude. South Korean memory fabricators in Pyeongtaek deploy cluster magnetron architectures for copper barrier seed layers in 3D NAND manufacturing. Chamber matching protocols and particle reduction specifications dominate procurement negotiations.
- Inline Sputter Coaters:Continuous substrate transport through sequential process zones supports architectural glass and display panel fabrication at widths exceeding three meters. Southeast Asian solar cell manufacturers specify rotatable cylindrical cathodes within inline architectures to maximize target material utilization above 80 percent. ULVAC dominates this configuration through captive vacuum component supply.
- Batch Sputter Coaters:Single-chamber designs serve research laboratories and low-volume specialty coating operations requiring rapid process recipe changes.
- RF Sputter Coaters:Radio-frequency excitation enables dielectric target sputtering for oxide and nitride films in optical coating applications.
- DC Sputter Coaters:Direct-current power supplies anchor conductive metal deposition in magnetic storage head fabrication.
Today's leader: Magnetron Sputter Coaters. Tomorrow's challenger: Inline Sputter Coaters.
Technology:
Process selection balances film density requirements against thermal budget constraints and reactive gas handling complexity.
- High Power Impulse Magnetron Sputtering:Microsecond-duration pulses at peak power densities above 1 kW/cm² generate highly ionized metal fluxes. South Korean logic fabricators adopt HiPIMS for titanium nitride barrier layers in sub-3nm node devices where substrate heating must stay below 150°C. Process stability and arc suppression algorithms differentiate equipment suppliers.
- Reactive Sputtering:Oxygen or nitrogen process gas introduction forms compound films from metallic targets. Closed-loop gas control systems with optical emission spectroscopy feedback stabilize oxide and nitride stoichiometry. European decorative finishing operations displace hexavalent chromium electroplating with titanium nitride reactive sputtering under REACH substance restrictions.
- Non-reactive Sputtering:Inert argon plasma deposits elemental metal films without gas-phase chemistry complications.
- Ion Beam Sputtering:Directed ion fluxes from separate sources enable precision optical coatings with sub-nanometer thickness uniformity.
- Pulsed DC Sputtering:Mid-frequency polarity reversal suppresses arcing in reactive metal oxide deposition.
HiPIMS commands premium pricing for advanced logic. Reactive sputtering scales across the widest application base.
Application:
Margin concentration follows node complexity and layer count escalation in memory and logic devices.
- Semiconductor Fabrication:Copper interconnect barrier layers, tungsten contact plugs, and high-k gate dielectrics demand angstrom-level thickness control. Multi-layer stack complexity in 3D NAND exceeds 100 sequential deposition steps. South Korean and Taiwanese foundries drive equipment specification roadmaps.
- Solar Cell Manufacturing:Transparent conductive oxide and anti-reflection coatings on silicon wafers and thin-film substrates require large-area uniformity. Southeast Asian cell producers prioritize throughput and target utilization economics.
- Optical Coatings:Precision interference filters and anti-reflection stacks serve telecommunications and laser systems.
- Magnetic Storage:Perpendicular recording media and read sensor multilayers face demand pressure from solid-state storage substitution.
- Decorative Finishing:Wear-resistant titanium nitride coatings displace hard chrome in automotive and consumer hardware applications.
Semiconductor Fabrication extracts maximum equipment value per square meter. Solar Cell Manufacturing offers volume expansion potential.
End User:
Procurement sophistication separates captive maintenance operations from full-service equipment dependencies.
- Electronics Fabricators:Tier-one foundries internalize routine consumables replacement and target procurement while retaining vendor process engineering support. South Korean memory houses negotiate unbundled service contracts separating hardware warranty from chamber matching protocols.
- Research Laboratories:Academic and national laboratory installations prioritize deposition flexibility and multi-target capability over throughput. Oxford Instruments anchors this segment through cryogenic deposition expertise.
- Optical Manufacturers:Precision wavelength coating requirements favor ion beam and ion-assisted deposition configurations.
- Data Storage Firms:Magnetic media producers face capital allocation pressure from cloud storage demand shifts.
- Photovoltaic Producers:Cost-per-watt imperatives drive equipment selection toward high-throughput inline architectures with minimal downtime.
Electronics Fabricators set equipment performance standards. Research Laboratories test emerging process technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek's semiconductor cluster drives the most intensive sputter coater deployment globally, with equipment specifications cascading from South Korean memory and logic foundries to regional supply chains.
South Korea
Samsung Electronics and SK Hynix operate the world's densest concentration of advanced sputter coaters in Pyeongtaek and Yongin for 3D NAND and sub-3nm logic production. MFDS maintains equipment qualification standards that align with export control frameworks for semiconductor manufacturing tools. The Yongin cluster hosts specialized service providers for chamber matching and particle reduction protocols.
China
Domestic foundries in Shanghai and Beijing expand magnetron sputtering capacity for mature-node semiconductors and display panel fabrication. MEE enforcement of dual carbon goals accelerates replacement cycles for energy-intensive vacuum deposition equipment. The Yangtze River Delta concentration around Suzhou and Wuxi integrates sputter coater procurement with local target material refining operations.
United States
Memory device manufacturers in Idaho and Arizona retrofit existing fabrication lines with abatement systems to maintain EPA operating permits for perfluorinated compound emissions. OSHA hexavalent chromium exposure limits push decorative finishing operations toward closed-loop titanium nitride sputtering. Intel's Oregon and Arizona facilities anchor domestic demand for high-precision barrier layer deposition.
Japan
Tokyo Electron and Hitachi High-Tech supply sputter coater subsystems to global equipment integrators from Chubu and Kanto manufacturing bases. METI coordinates national R&D consortia for next-generation deposition technologies including solid-state battery electrolyte sputtering. The Nagoya-Tokyo industrial corridor concentrates ion beam and magnetron source engineering expertise.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg displace hard chrome electroplating with titanium nitride sputter coatings under REACH substance restrictions and EU F-Gas Regulation compliance requirements. Fraunhofer institutes in Dresden and Munich pilot HiPIMS process development for tool coating applications. Stuttgart's precision engineering cluster integrates decorative PVD finishing with captive automotive component supply chains.
Global Sputter Coater Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment suppliers align with foundry qualification timelines and captive maintenance team capabilities. The vendor base separates into three distinct tiers: integrated conglomerates with vacuum component captive supply, specialized deposition technology developers, and regional system integrators serving research and mid-volume production segments. Two competitive vectors define positioning: unbundled service contracts that separate hardware warranty from process engineering support, and modular cluster architectures enabling parallel processing of heterogeneous film stacks.
Within the integrated conglomerate tier, ULVAC and Buhler occupy positions shaped by backward integration into vacuum component and cathode assembly production. Oxford Instruments anchors the specialized technology tier through cryogenic deposition expertise serving research laboratory segments. These three companies exemplify divergent strategic archetypes: scale-driven inline system manufacturing, captive supply chain control, and premium research equipment positioning respectively.
| Leading Market Players |
|---|
| Buhler |
| Oxford Instruments |
| ULVAC |
| Semicore Equipment |
| Cressington Scientific Instruments |
| Veeco Instruments Inc. |
| Quorum Technologies |
| PLASSYS Bestek |
| Hitachi High-Tech Corporation |
| Others |
Supply & Pricing Matrix
Semiconductor fabricators in South Korea's Pyeongtaek cluster now mandate unbundled service contracts separating hardware warranty from process engineering support, forcing equipment suppliers to absorb target procurement risk while compressing upfront system pricing. This procurement shift concentrates margin pressure on cathode assembly and vacuum component suppliers who must recalibrate pricing models around captive maintenance capabilities.
Pricing Analysis
Input-cost pass-through from tantalum and noble metal target volatility anchors equipment pricing, with three-tier pricing structure across premium, standard, and economy levels differentiated by chamber matching precision and after-sales bundling. Premium HiPIMS configurations command substantial markups for sub-3nm logic applications where substrate heating constraints dominate procurement criteria. Cost compression in standard magnetron tiers intensifies because Southeast Asian solar cell manufacturers prioritize throughput economics over film density specifications. Photovoltaic producers exhibit highest price sensitivity due to cost-per-watt imperatives, while South Korean memory houses accept premium positioning for particle reduction protocols.
Supply Chain Analysis
Regional distribution centers in Nagoya and Stuttgart maintain hub-and-spoke patterns for vacuum component fulfillment, with final system integration concentrating in Japan, Germany, and South Korea. Sputter coater production draws from high-purity tantalum refining in Central Africa, titanium sponge processing in Japan, and specialized ceramic insulator manufacturing in Germany. Single-source vulnerability pervades rotatable cylindrical cathode supply where two Japanese specialists control critical magnet array configurations. Distribution runs through foundry-qualified service providers who manage chamber matching and particle reduction protocols at captive maintenance facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme allocations for domestic chip fabrication create greenfield demand at cost structures below East Asian cluster density, while REACH compliance costs in Europe elevate supplier qualification barriers that protect incumbent positioning.
For Market Incumbents: Acquire cryogenic pump maintenance capabilities to anchor unbundled service contracts as South Korean memory houses internalize routine consumables replacement. Backward integration into rotatable cylindrical cathode production defends against single-source magnet array vulnerability. Capacity addition in Gujarat addresses India's semiconductor incentive scheme before qualification timelines harden. For New Entrants and Emerging Players: Enter via solid-state battery electrolyte deposition equipment where sulfide and oxide sputtering process development remains pre-competitive. Photonics integration in datacom represents the most penetrable application, with silicon photonics foundries requiring precision tantalum pentoxide sputtering for waveguide fabrication. Partner with Fraunhofer institutes for HiPIMS process validation to bypass incumbent qualification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized deposition technology developers possessing cryogenic expertise or ion beam precision capabilities rather than integrated conglomerates facing margin compression from unbundling. Long-term viability favors equipment suppliers who control cathode assembly production or maintain captive vacuum component supply. Watch for MFDS alignment with export control frameworks as the inflection indicator for regional supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Assembly | Captive magnet array production mitigates single-source risk from Japanese specialists. |
| HiPIMS Process Development Partnership | Fraunhofer collaboration accelerates qualification for sub-3nm logic barrier layers. |
| Unbundled Service Contract Tiering | Separation of hardware warranty from chamber matching aligns with South Korean procurement preferences. |
| Rotatable Cylindrical Target Deployment | Material utilization above 80 percent addresses Southeast Asian solar cell manufacturer economics. |
| India Greenfield Fab Qualification | Early positioning in Gujarat and Tamil Nadu captures PLI scheme allocations before competition intensifies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment procurement managers at South Korean memory houses, vacuum technician supervisors at Southeast Asian solar cell facilities, and process engineering leads at European automotive suppliers with secondary validation from SEC filings of listed equipment manufacturers, customs records for tantalum target trade flows, and MFDS equipment qualification standards. Bottom-up installation tracking across Pyeongtaek and Yongin clusters triangulated against top-down market sizing from semiconductor capital expenditure disclosures.
Segment-weighting approaches distributed value across magnetron, inline, batch, RF, and DC architectures proportionally to their installed base and replacement cycle timing, with technology-level modeling for HiPIMS, reactive sputtering, and ion beam configurations across the projection horizon. CAGRs derived from equipment shipment correlations with foundry capacity expansion announcements and display panel fabrication buildouts. Forecast inputs incorporated REACH substance restriction phase-in schedules and China's MEE energy efficiency enforcement timelines as demand modifiers.
Inputs from equipment procurement managers and foundry process engineers were available through the study window; gaps in captive maintenance team capability assessments introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions regarding qualification timeline compression and unbundling adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global UV-Cured Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Glass Coatings Market
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Mold Release Coatings Market
Coatings
Polyester Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Coating Thickness Gauge Market
Coatings
Marine Nanocoating Market
Coatings
Anti Soiling Coating Market
Coatings
Germany Protective Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
Concrete Floor Coatings Market
Coatings
Wood Preservative Coatings Market