
 Pull Out and Down Kitchen Faucet Market | 2026-2036
Pull Out and Down Kitchen Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
Pull Out and Down Kitchen Faucet Market Intelligence
EPA WaterSense specifications is broadening the cost-of-entry calculus for manufacturers seeking North American distribution. Moen leverages ceramic disc valve manufacturing depth to sustain premium positioning across retail and trade channels. Kohler anchors its portfolio with magnetic docking systems that differentiate installation-grade offerings from mass-market alternatives. Delta Faucet competes through channel control, occupying dominant shelf space at home improvement retailers and maintaining contractor loyalty programs.
Pull out and down kitchen faucets integrate a retractable hose mechanism within a gooseneck or semi-professional spout body, typically constructed from brass or stainless steel with PVD or chrome finishing, enabling directional water delivery for sink basin coverage and spray-mode switching. The primary purpose centers on ergonomic cleaning efficiency in residential and commercial food preparation environments. Touchless technology leads residential growth as homeowners prioritize hygiene interfaces, while commercial grade fixtures command margin pools in food service applications where durability cycles justify premium pricing. Spray control functionality remains mature across standard lines, though water saving configurations are gaining specification share in institutional facilities facing utility cost pressures.
EPA WaterSense and ASME A112.18.1 standards govern flow performance and material safety in the United States, compelling redesign of cartridge and aerator assemblies to maintain functionality at reduced gallon-per-minute thresholds. The EU Green Deal and REACH chemical compliance frameworks in Europe restrict lead content and surface treatment chemistries, segmenting export-ready manufacturers from regionally focused suppliers. Stakeholders must monitor evolving state-level plumbing codes and building electrification mandates that could redefine installation requirements and compatibility standards for connected fixture ecosystems.
Market Dynamics
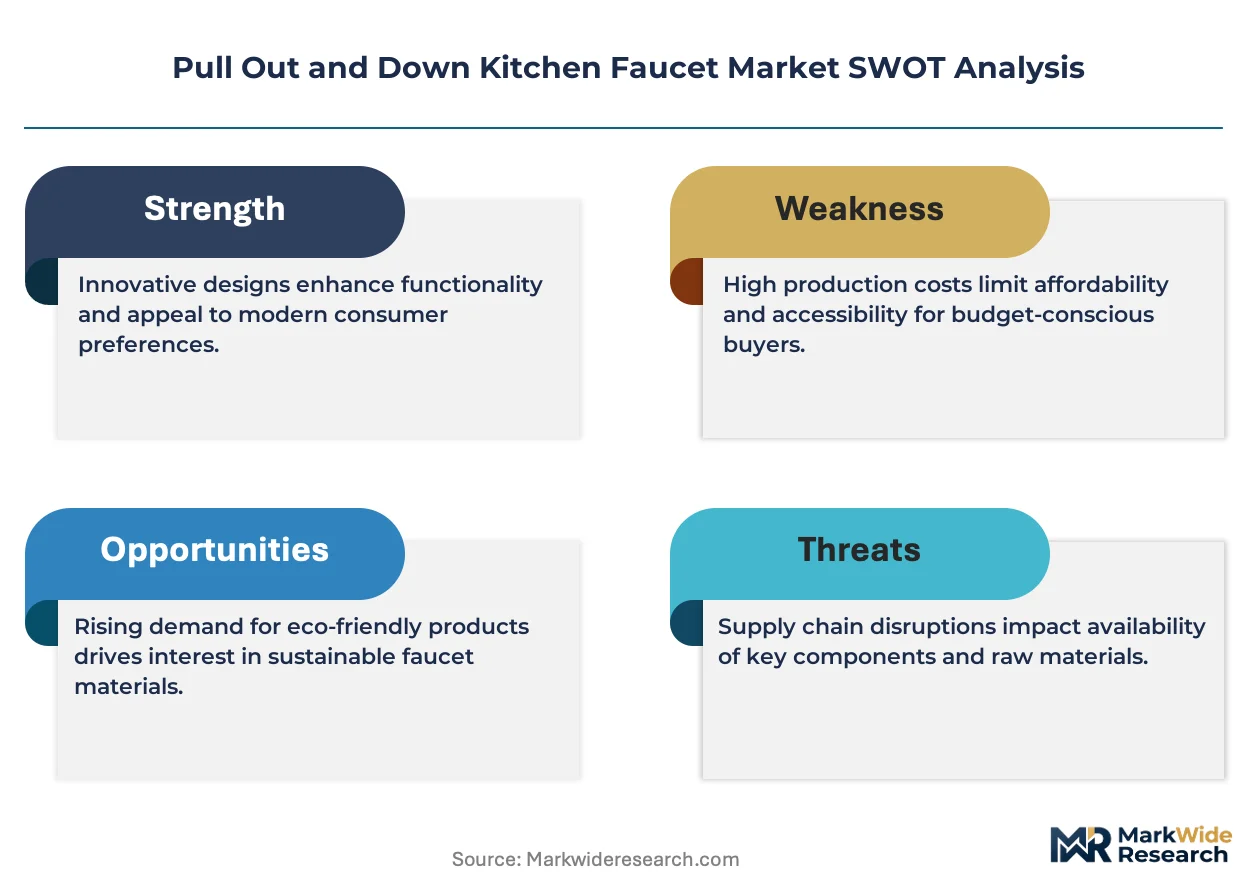
EPA WaterSense flow-rate mandates are compressing cartridge engineering tolerances and forcing aerator redesigns across North American supply chains, while residential renovation cycles accelerate fixture replacement velocity beyond traditional durability timelines.
Growth Catalysts
- Touchless sensor interfaces:Infrared and capacitive activation systems are penetrating residential kitchens as hygiene-conscious homeowners prioritize contamination-free operation during food preparation workflows.
- Commercial kitchen upgrade cycles:Food service operators in the United States are replacing legacy fixtures with pull-down configurations to meet NSF/ANSI 61 material safety requirements and reduce labor time on sink-based tasks.
- EU Green Deal chemical restrictions:REACH compliance deadlines are filtering out lead-containing brass alloys, creating specification advantages for manufacturers with certified low-lead metallurgy capabilities.
Market Restraints
- Brass alloy input volatility:Copper and zinc price swings compress margin stability for foundry-dependent producers without long-term concentrate offtake agreements.
- Cartridge supply concentration:Ceramic disc valve manufacturing clusters in Taiwan and mainland China create single-source vulnerability for mid-tier assemblers lacking dual-qualified vendors.
- Reduced flow-rate functionality trade-offs:EPA WaterSense 1.5 GPM maximums compromise spray pressure performance, generating end-user dissatisfaction and return rates in hard-water municipalities.
Strategic Opportunities
- Connected fixture ecosystems:Bluetooth and Wi-Fi-enabled faucets with usage monitoring and leak detection are opening specification channels with property management platforms and smart home integrators.
- Institutional water-saving mandates:California Title 24 and similar state-level building codes are creating compliance-driven demand for certified low-flow configurations in educational and healthcare facilities.
- Voice-activation convergence:Integration with Amazon Alexa and Google Home systems is overtaking traditional handle interfaces in premium residential new construction.
Industry Challenges
- Cross-threaded installation skill gaps:Contractor workforce turnover is elevating callback rates for magnetic docking misalignment and hose retraction failures.
- Multi-certification timeline compression:Simultaneous EPA WaterSense, NSF/ANSI 61, and state-level lead-free compliance testing extends product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pull Out and Down Kitchen Faucet Market |
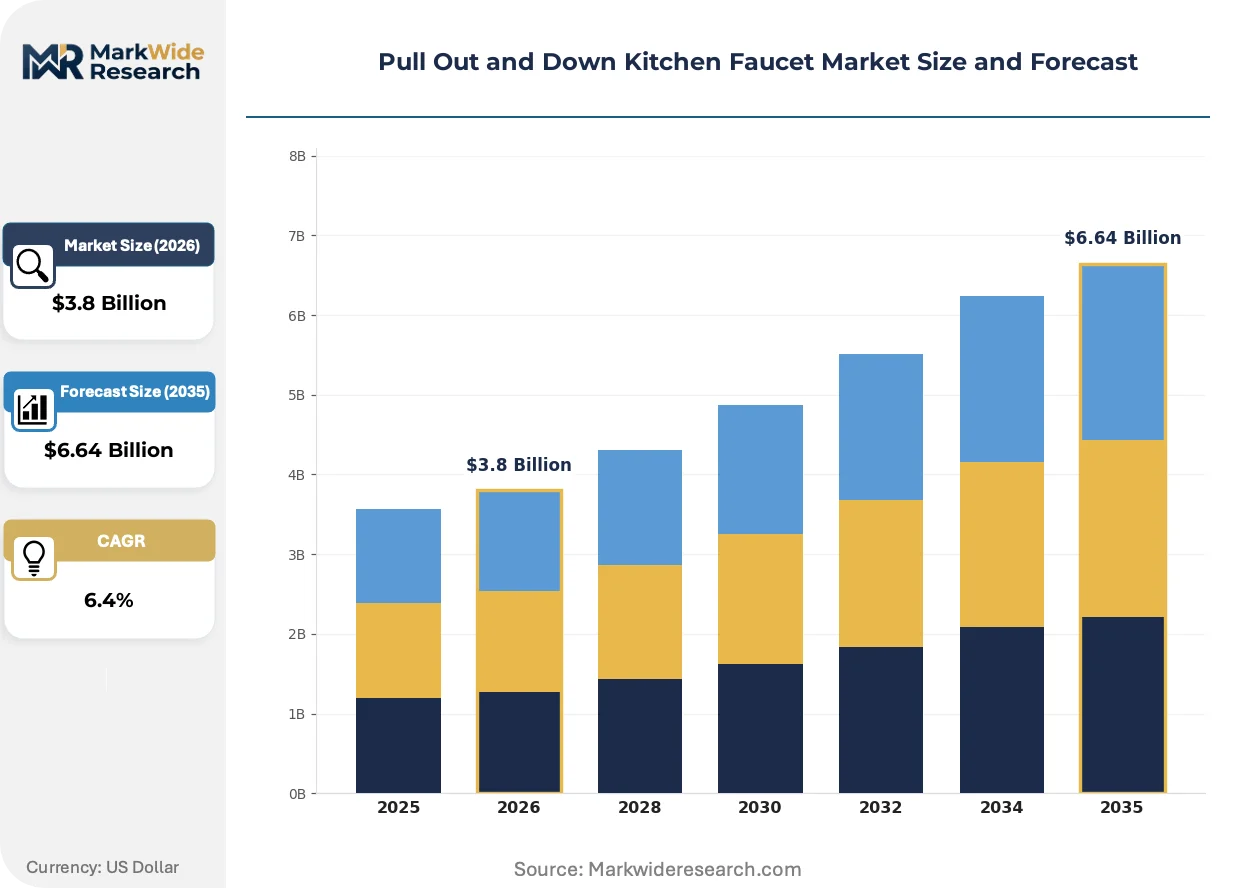
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Handle, Double Handle, Touchless, Wall Mounted, Commercial Grade Technology: Spray Control, Magnetic Docking, LED Indicators, Ceramic Disc Valve, Water Saving Application: Residential Kitchens, Food Service, Hospitality, Institutional Facilities, Commercial Laundries End User: Homeowners, Restaurant Chains, Hotel Operators, Educational Institutions, Healthcare Facilities |
| Companies Covered | Hansgrohe, Delta Faucet, Moen, Kohler, American Standard, Grohe, Pfister, Kraus USA, Fortune Brands Home & Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pull Out and Down Kitchen Faucet Market Strategic Shifts & Innovations
Magnetic docking mechanisms and ceramic cartridge precision are converging with connectivity protocols to redefine fixture reliability benchmarks and installation service expectations across residential and commercial channels.
Touchless capacitive sensors are overtaking manual lever interfaces in mid-market residential specifications. These proximity-activated systems eliminate cross-contamination vectors during raw protein handling. Homebuilders in Texas and Florida are specifying touchless configurations as standard in new construction. The technology is compressing differentiation timelines for traditional mechanical-only portfolios.
EPA WaterSense certification expansion is tightening flow-rate ceilings and aerator performance thresholds. Manufacturers must redesign internal waterways to maintain spray coverage at reduced gallon-per-minute outputs. California and New York municipal procurement codes are prioritizing certified fixtures in public housing retrofits. Suppliers are accelerating dual-certification strategies to maintain bid eligibility across overlapping jurisdictions.
Direct-to-consumer channel expansion is fragmenting traditional wholesale-distributor relationships. Homeowners are researching specifications online before engaging installers, compressing contractor influence over brand selection. Big-box retailers are capturing specification authority through exclusive finish options and extended warranty programs. This behavioral shift is most pronounced in suburban renovation markets where discretionary kitchen spending concentrates.
Pull Out and Down Kitchen Faucet Market Segmentation
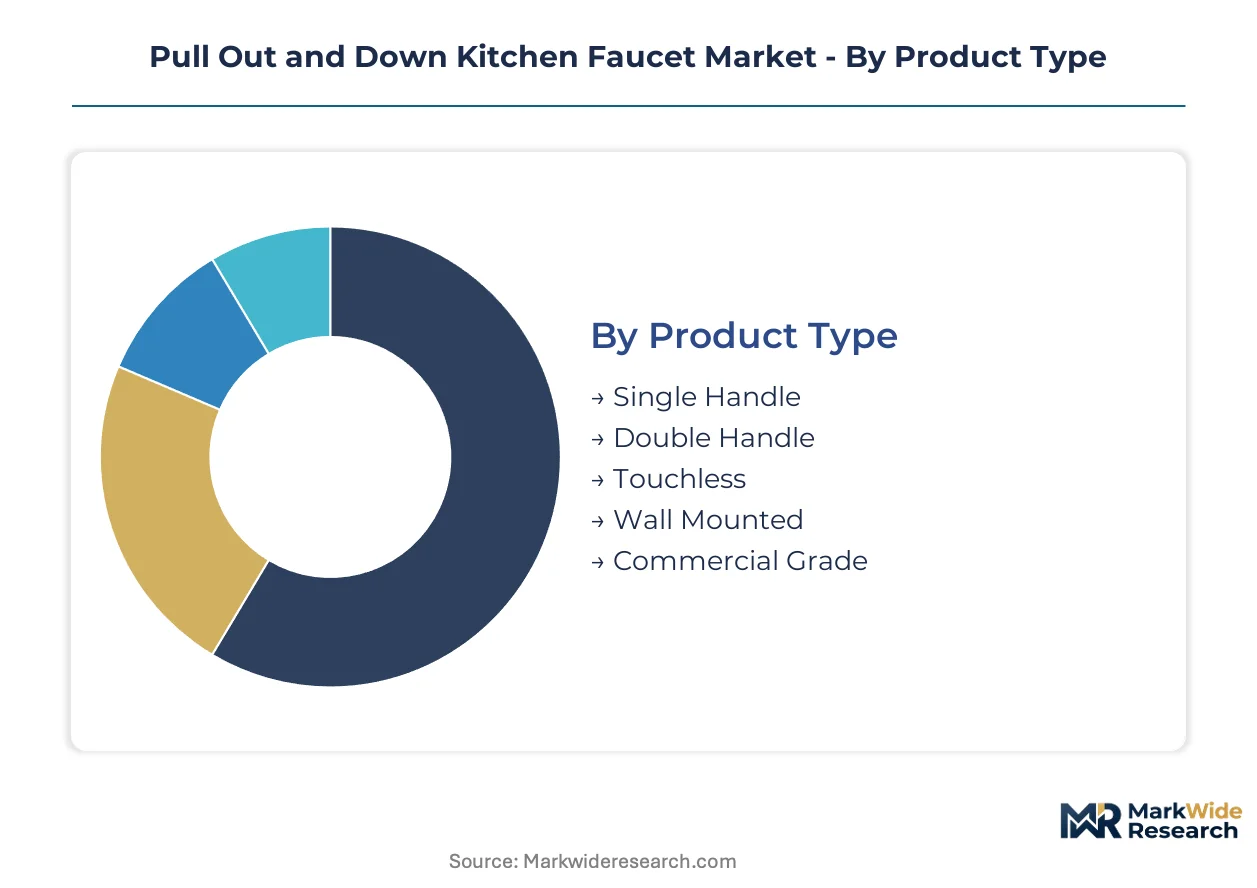
Segmentation in the Pull Out and Down Kitchen Faucet Market reveals divergent engineering requirements between residential renovation cycles and commercial durability specifications. Buyer priorities shift dramatically across touchless hygiene interfaces versus NSF-certified material safety mandates, forcing manufacturers to maintain parallel certification portfolios.
Product Type:
Installation configuration and handle mechanism drive replacement velocity and contractor preference in renovation versus new construction channels.
- Single Handle:Temperature and flow control through one lateral lever movement dominates residential retrofit specifications where deck drilling patterns limit modification options. Demand concentrates in suburban United States markets where homeowners prioritize familiar operation over interface learning curves.
- Touchless:Infrared or capacitive activation eliminates cross-contamination during raw protein preparation, commanding specification share in premium residential new construction across Texas and Florida. The segment is expanding most quickly as hygiene-conscious buyers retrofit existing kitchens.
- Double Handle:Separate hot and cold controls persist in traditionalist renovation segments and heritage property restorations requiring period-appropriate aesthetics.
- Wall Mounted:Deck-free installation suits compact galley kitchens and commercial pre-rinse applications where sink basin clearance takes priority.
- Commercial Grade:Brass forging thickness and ceramic cartridge durability ratings meet NSF/ANSI 61 material safety requirements for food service operators replacing legacy fixtures on accelerated cycles.
Single Handle leads on scale; Touchless leads on momentum.
Technology:
Component-level differentiation determines margin capture and channel positioning across retail, trade, and specification markets.
- Spray Control:Multi-function aerators delivering stream, spray, and pause modes represent baseline functionality across all price tiers. Volume concentrates in mass-market retail channels where feature parity drives selection.
- Magnetic Docking:Rare-earth magnet arrays securing spray head retraction differentiate installation-grade offerings from economy alternatives, commanding contractor loyalty in United States renovation markets where callback liability concentrates.
- Ceramic Disc Valve:Alumina ceramic sealing surfaces rated for 500,000+ cycles anchor premium positioning and warranty extension programs. The segment gains share fastest as EPA WaterSense flow-rate mandates compress engineering tolerances.
- LED Indicators:Temperature-responsive color signaling addresses scald risk in households with elderly occupants or childcare requirements.
- Water Saving:Aerator redesigns maintaining spray coverage at 1.5 GPM maximums target California Title 24 compliance and municipal procurement specifications.
Ceramic Disc Valve dominates margin capture; Water Saving configurations climb the fastest on regulatory tailwinds.
Application:
Usage intensity and regulatory exposure shape material specification and replacement cycle forecasting.
- Residential Kitchens:Ergonomic hose retraction and finish durability for daily food preparation tasks drive specification in United States housing stock turnover. Volume concentrates in suburban renovation markets where discretionary kitchen spending peaks.
- Food Service:NSF/ANSI 61 compliance and pre-rinse spray pressure requirements dominate commercial kitchen upgrade cycles, with operators prioritizing labor time reduction on sink-based tasks.
- Hospitality:Brand-standard finish consistency across property portfolios and guest-facing aesthetic requirements differentiate procurement from residential channels.
- Institutional Facilities:California Title 24 and similar state-level building codes create compliance-driven demand for certified low-flow configurations in educational and healthcare settings.
- Commercial Laundries:High-cycle durability and chemical resistance specifications diverge from food preparation applications.
Residential Kitchens leads on scale; Institutional Facilities leads on momentum.
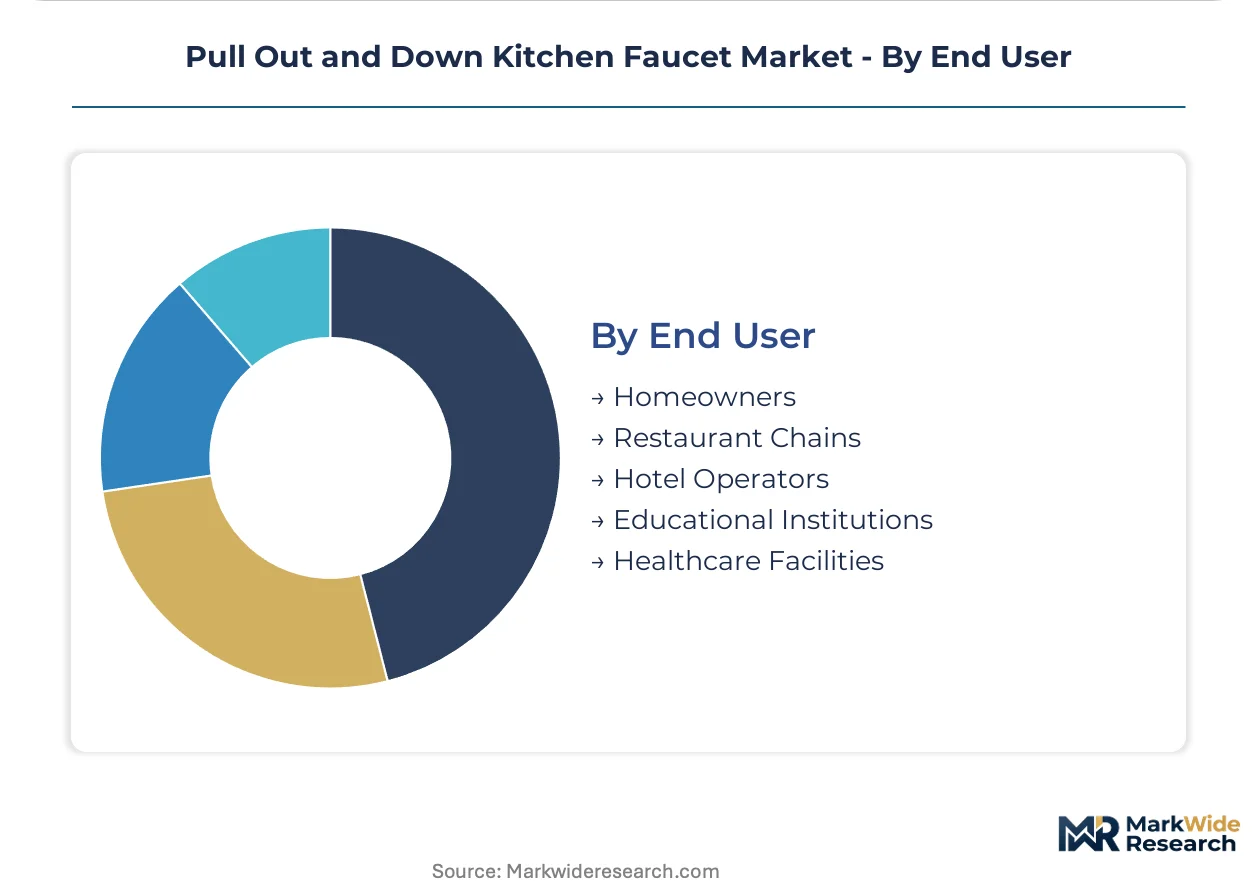
End User:
Procurement authority and technical specification capability fragment channel influence across consumer-direct and contractor-mediated transactions.
- Homeowners:Online research behavior preceding installer engagement compresses contractor brand influence, with big-box retailers capturing specification authority through exclusive finish options. The segment dominates volume in United States suburban renovation corridors.
- Restaurant Chains:Corporate facilities standards and multi-unit rollout schedules create concentrated demand for NSF-certified configurations with unified warranty administration.
- Hotel Operators:Brand consistency requirements and property management platform integration priorities distinguish procurement from independent restaurant decision-making.
- Educational Institutions:Municipal procurement codes and maintenance staff technical capacity constraints favor simplified cartridge replacement protocols.
- Healthcare Facilities:Infection control protocols and ADA accessibility requirements add specification layers beyond standard commercial applications.
Homeowners leads on scale; Healthcare Facilities leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pull out and down kitchen faucet industry traces its mass-market origins to post-war American suburbanization, when standardized plumbing fixtures enabled scalable residential construction across the United States. European brass-casting traditions in Germany and Italy subsequently elevated finish durability and design aesthetics. Asian manufacturing clusters in Taiwan and mainland China later consolidated component supply chains.
United States
Housing stock turnover and commercial kitchen upgrade cycles sustain the largest national fixture demand globally. EPA WaterSense certification mandates flow-rate ceilings that reshape product engineering priorities. The Chicago-Milwaukee corridor anchors domestic assembly operations for major brand portfolios.
Germany
Precision brass forging and ceramic cartridge engineering command specification share across European renovation markets. REACH chemical compliance deadlines filter lead-containing alloys from supply chains. The Black Forest region concentrates specialized valve manufacturing for export-ready producers.
China
Mass-market fabrication and OEM supply relationships dominate volume production for North American and European distributors. GB standards and dual carbon goals tighten environmental compliance for foundry operations. The Yangtze River Delta hosts the densest clustering of ceramic disc valve component suppliers.
Japan
Compact kitchen footprints and water-saving fixture preferences drive demand for space-efficient pull-down configurations. METI efficiency standards and JIS certification requirements elevate product quality thresholds. The Nagoya-Chubu region maintains specialized surface treatment capabilities for premium finish applications.
India
Rising residential construction and urban kitchen modernization expand addressable market for mid-tier fixture specifications. BIS plumbing standards and municipal water pressure variability create localized engineering requirements. Gujarat and Maharashtra industrial corridors attract brass component manufacturing investments.
Pull Out and Down Kitchen Faucet Market Key Industry Players
The competitive structure tilts toward brand-anchored portfolio diversification across retail and trade channels. Consolidation around established plumbing fixture conglomerates coexists with specialized component suppliers and regional assemblers. Three archetypes dominate: vertically integrated brass foundry operators, technology-licensing brand licensors, and private-label contract manufacturers. Capacity expansion in low-lead metallurgy and strategic partnerships with smart home platforms represent the dominant competitive vectors.
Among North American brand-anchored manufacturers, Moen, Kohler, and Delta Faucet exemplify distinct positioning strategies within the premium-to-mass market spectrum. Moen occupies a position emphasizing ceramic disc valve manufacturing depth across retail and trade channels. Kohler anchors installation-grade offerings through magnetic docking system differentiation. Delta Faucet sits within the channel-control archetype, leveraging dominant shelf space relationships and contractor loyalty programs. These three entities collectively represent the competitive intensity shaping specification authority in United States renovation markets.
| Leading Market Players |
|---|
| Hansgrohe |
| Delta Faucet |
| Moen |
| Kohler |
| American Standard |
| Grohe |
| Pfister |
| Kraus USA |
| Fortune Brands Home & Security |
| Others |
Cost & Logistics Intelligence
Captive brass foundry operations in Taiwan and mainland China anchor both supply security and margin control for fixture manufacturers serving North American and European distribution channels. EPA WaterSense certification costs and ceramic cartridge precision requirements compress pricing flexibility at the premium tier while commodity-grade alternatives face input volatility from unhedged copper and zinc positions.
Pricing Analysis
Bundled installation service and extended warranty programs separate premium offerings from unbundled mass-market transactions where contractors absorb callback liability. Three-tier pricing structure across premium, standard, and economy levels reflects ceramic cartridge cycle ratings, magnetic docking inclusion, and finish durability grades. Cost compression in the economy tier intensifies because brass alloy input volatility erodes foundry-dependent producers without long-term concentrate offtake agreements. Residential renovation homeowners exhibit highest price sensitivity; food service operators demonstrate lowest sensitivity due to NSF/ANSI 61 compliance mandates and labor-cost-justified durability premiums.
Supply Chain Analysis
Domestic-content thresholds in United States federal procurement and California state contracts are reshaping sourcing patterns toward Mexican and domestic assembly operations. Component supply concentrates in Taiwan, mainland China, and Germany, with ceramic disc valve manufacturing anchored in the Yangtze River Delta and Black Forest regions. Raw material dependencies span copper-zinc brass alloys, rare-earth magnets for docking systems, and alumina ceramic substrates. Single-source vulnerability from Taiwanese valve clusters creates structural risk for mid-tier assemblers lacking dual-qualified vendors. Distribution runs through big-box retail chains, wholesale plumbing distributors, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pull out and down kitchen faucet market reads as a late-cycle quality story where touchless specification share and EPA WaterSense dual-certification demands concentrate procurement authority with manufacturers possessing integrated metallurgy and sensor engineering capabilities.
For Market Incumbents: Anchor premium positioning through captive low-lead brass foundry investments and magnetic docking patent portfolios that block mid-tier replication. Defensive consolidation should prioritize ceramic cartridge manufacturing depth in Taiwan and mainland China to offset supply concentration risk from emerging smart-home platform entrants. Channel control investments in contractor loyalty programs and exclusive retail finish options preserve specification authority against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Smart home integrators and property management platforms represent the most accessible channel partners for voice-activation and leak-detection feature bundles. White-space targets include institutional facilities facing California Title 24 compliance deadlines and healthcare settings requiring infection-control protocols. The penetrable segment centers on mid-market touchless retrofits where established brands carry premium pricing overhead. A go-to-market angle emphasizing simplified cartridge replacement protocols for educational institution maintenance staff bypasses incumbent contractor relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized ceramic valve manufacturers and low-lead metallurgy foundries because EPA and REACH compliance timelines are filtering out sub-scale operators unable to absorb certification costs. Long-term viability favors vertically integrated entities with captive component supply and smart-home platform partnerships. Acquisition target archetypes include Taiwan-based ceramic disc valve specialists and regional assemblers with established NSF/ANSI 61 testing infrastructure. The signal to watch is state-level building electrification mandates that could redefine installation requirements and compatibility standards for connected fixture ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Lead Metallurgy Foundry Investment | REACH and EPA compliance deadlines filter out lead-containing alloys, creating specification advantages for certified producers. |
| Smart Home Platform Partnership | Amazon Alexa and Google Home integration opens specification channels with property management platforms and new construction developers. |
| Dual-Certification Acceleration | Simultaneous EPA WaterSense and NSF/ANSI 61 testing maintains bid eligibility across overlapping municipal procurement jurisdictions. |
| Direct-to-Consumer Channel Expansion | Online research behavior preceding installer engagement captures specification authority from traditional wholesale-distributor relationships. |
| Ceramic Cartridge Manufacturing Scale-Up | Alumina ceramic sealing surfaces rated for extended cycles anchor premium positioning and warranty extension programs. |
Research Approach
Direct dialogue with product development executives at fixture manufacturers, procurement managers at restaurant chains and hotel operators, plumbing contractors in United States renovation markets, and regulatory compliance officers shaped qualitative grounding for demand and specification trends. Secondary validation drew from EPA WaterSense certification databases, NSF/ANSI 61 product listings, customs and trade data on brass alloy imports, and SEC filings from publicly traded plumbing fixture conglomerates. Bottom-up channel volume estimates and top-down housing stock turnover projections were triangulated against commercial kitchen upgrade cycle reporting from food service operators.
Bottom-up modeling segmented volume and value across product type, technology tier, application intensity, and end-user procurement authority, then aggregated through the projection horizon. Top-down analysis calibrated total addressable market against residential construction permits, commercial food service establishment counts, and institutional facility building stock. CAGRs were derived from regression analysis of replacement cycle acceleration, regulatory compliance adoption curves, and technology penetration patterns. Industry-specific forecast inputs included EPA WaterSense certification expansion timelines and state-level plumbing code adoption schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to brass alloy commodity price volatility, trade policy shifts affecting Taiwanese component supply, and building electrification mandates that could redefine installation requirements. Forecasts reflect assumptions around housing stock turnover velocity, commercial kitchen upgrade cycle timing, and regulatory compliance adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Europe Kitchen Furniture Market