
 GCC Modular Kitchen Market | 2026-2036
GCC Modular Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Modular Kitchen Market Intelligence
Specialty retail and direct-to-developer channels is fragmenting as e-commerce platforms and experience centers capture specification-stage buyers. Hafele sustains its position through captive hardware ecosystems that lock in cabinet OEMs. Danube Home leverages its hypermarket footprint across the UAE and Saudi Arabia to control last-mile delivery and installation scheduling. Inter Ikea Group competes on flat-pack logistics density, anchoring volume in entry-level segments across Gulf urban corridors.
Modular kitchens comprise standardized cabinet carcasses, countertops, and hardware assemblies designed for rapid on-site configuration, typically specifying 18mm melamine-faced particleboard or MDF substrates with HPL or acrylic surfacing for humidity resistance. Their primary commercial purpose is to reduce construction-phase labor and enable post-occupancy reconfiguration in multi-unit residential and hospitality developments. Base cabinets and kitchen islands anchor current revenue pools, as these units command the highest per-linear-foot material intensity and appliance integration complexity. MDF and acrylic surfaces are gaining specification share over solid wood in coastal GCC cities, where salt-laden air degrades natural timber finishes and maintenance clauses in service contracts favor synthetic substrates.
SFDA material safety notifications, UAE Civil Defense fire-rating requirements, and Saudi Building Code thermal performance standards collectively shape product compliance costs and import clearance timelines for cabinet assemblies. Municipality-level fit-out permitting in Dubai and Riyadh now requires third-party certification of formaldehyde emission levels from panel substrates, filtering out uncertified Asian suppliers. Stakeholders must monitor how Saudi Arabia's local content mandates under Vision 2030 industrial programs redirect procurement toward domestic fabricators and away from long-standing Turkish and European supply relationships.
Market Dynamics
Saudi Arabia's Vision 2030 local content mandates are redirecting procurement flows from Turkish and European fabricators toward domestic assembly operations, compressing import clearance timelines and reshaping supplier relationships across the Gulf.
Growth Catalysts
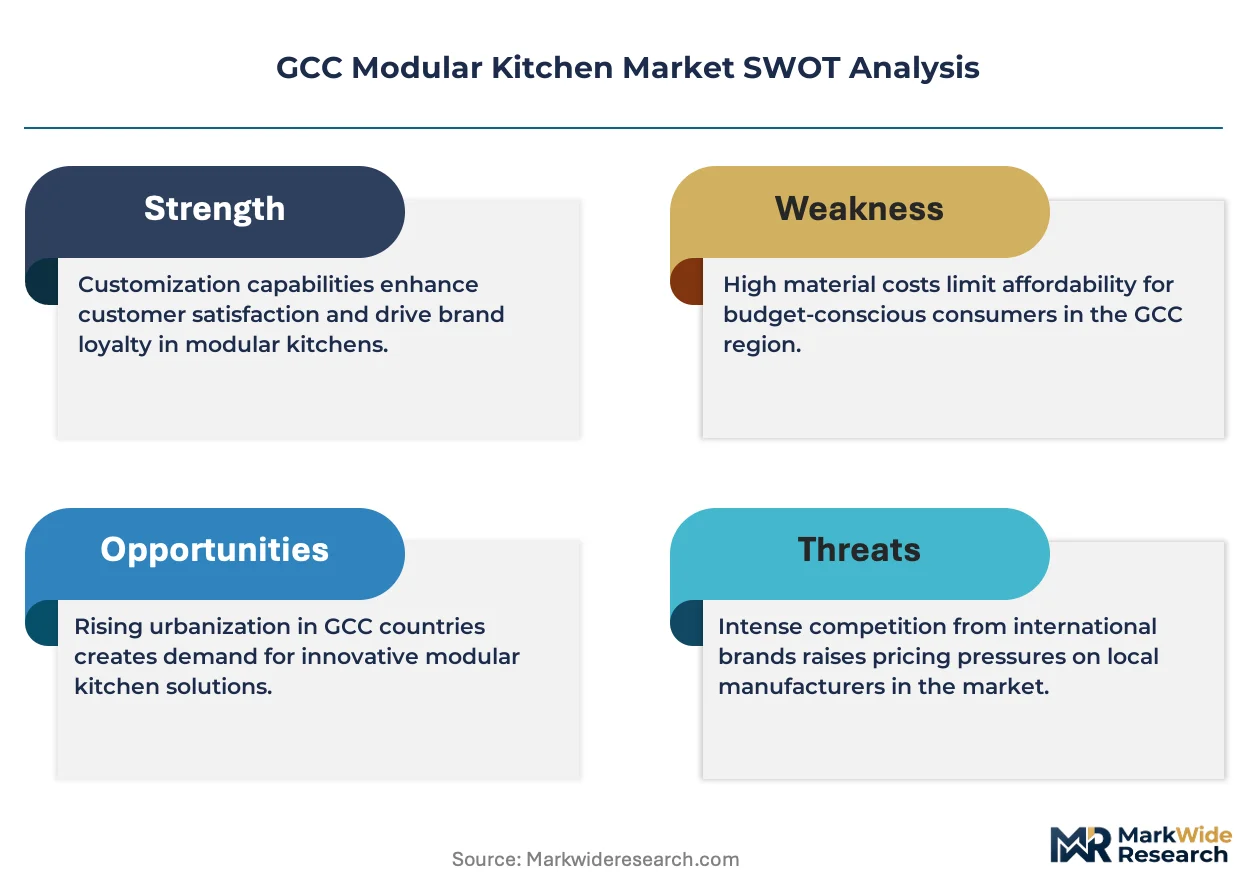
- SFDA Fire-Retardant Mandates:Saudi Arabia's building codes now require fire-retardant surface materials in high-density housing, forcing specification upgrades that favor certified modular kitchen suppliers with tested substrate portfolios.
- High-Rise Residential Construction:Dubai and Riyadh tower developments are driving contractor demand for prefabricated kitchen systems that reduce on-site labor hours and accelerate handover schedules.
- Humidity-Resistant Substrates:Salt-laden coastal air in Abu Dhabi and Doha is degrading natural timber finishes, pushing developers toward 18mm melamine-faced particleboard and acrylic surfacing with lower maintenance clauses.
Market Restraints
- Formaldehyde Certification Bottlenecks:Dubai and Riyadh municipality permitting now requires third-party emission testing, filtering out uncertified Asian panel suppliers and extending procurement cycles by 4-8 weeks.
- Turkish Supply Concentration:Long-standing fabrication relationships with Turkish cabinet OEMs face disruption as Saudi local content thresholds rise, creating transition risk for developers with locked-in supplier contracts.
- Solid Wood Substitution Pressure:Natural timber finishes face displacement from synthetic substrates in coastal markets, eroding premium positioning for hardwood-focused product lines.
Strategic Opportunities
- Kuwait and Bahrain Penetration:These markets show lower modular kitchen saturation than the UAE and Saudi Arabia, offering first-mover positioning for suppliers with GCC-wide logistics networks.
- Experience Center Channels:Specification-stage buyers are migrating from traditional retail toward immersive showrooms in Dubai Design District, creating direct-to-developer bypass opportunities.
- UAE-Saudi Thermal Performance Alignment:Converging building code standards across Dubai Civil Defense and Saudi Building Code requirements enable product platform standardization across the two largest markets.
Industry Challenges
- Installation Workforce Scarcity:Skilled technicians for appliance integration and countertop sealing are concentrated in Dubai and Riyadh, creating scheduling bottlenecks for projects in secondary cities.
- Multi-Jurisdiction Compliance:Cabinet assemblies must simultaneously satisfy SFDA material safety notifications, UAE Civil Defense fire-ratings, and municipality-level fit-out permitting, multiplying documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Modular Kitchen Market |
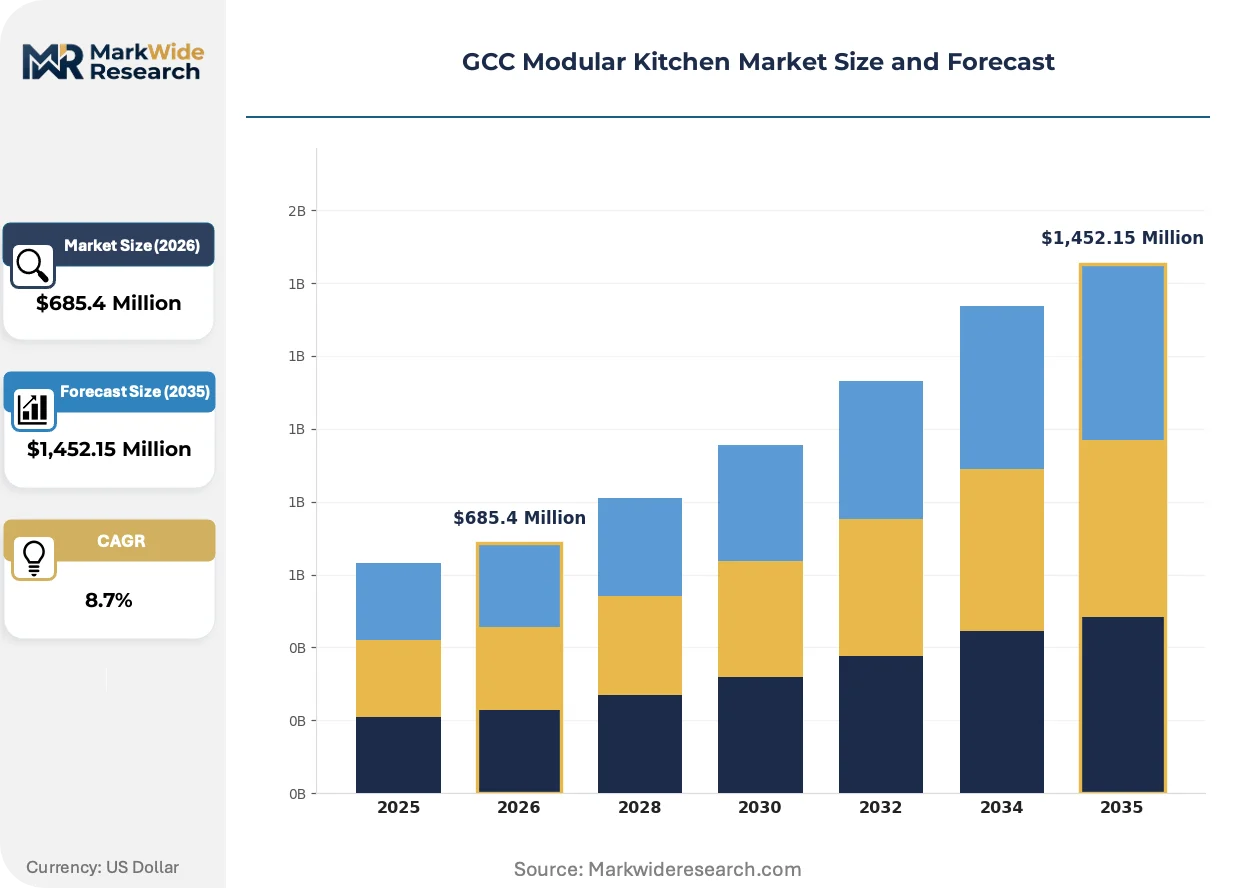
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Cabinets, Wall Cabinets, Kitchen Islands, Pantry Units Material: Wood, MDF, Plywood, Acrylic Style: Modern, Contemporary, Traditional, Rustic Installation Type: Custom, Prefabricated, Modular, Knock-Down |
| Companies Covered | Danube Home, Hafele, Inter Ikea Group, International Kitchens, Al Marri Metal Kitchen Factory, Kitchen Line, Hacker Kitchens, Al Marhaba Kitchen, Kitchen King, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Modular Kitchen Market Strategic Shifts & Innovations
Specification-stage buyer behavior is fragmenting traditional channel structures, with digital platforms and immersive showrooms capturing decision-makers before they reach conventional retail touchpoints.
Acrylic surfacing technology is migrating from premium hospitality projects toward mid-rise residential towers in Dubai and Abu Dhabi. Developers specify these finishes for salt-air durability and lower lifecycle maintenance costs. The shift is compressing demand for solid wood veneers in coastal GCC cities.
UAE Civil Defense fire-rating requirements and Saudi Building Code thermal performance standards are converging toward stricter substrate certification. This regulatory alignment is elevating compliance costs for uncertified imports. Pan-Asian suppliers are responding by establishing Dubai-based testing partnerships to maintain market access.
Developer procurement teams are consolidating vendor relationships around full-service providers capable of design, fabrication, delivery, and installation. This bundling preference is marginalizing standalone cabinet OEMs without captive hardware ecosystems or last-mile capabilities. The pattern is most visible in Riyadh's high-rise residential pipeline.
GCC Modular Kitchen Market Segmentation
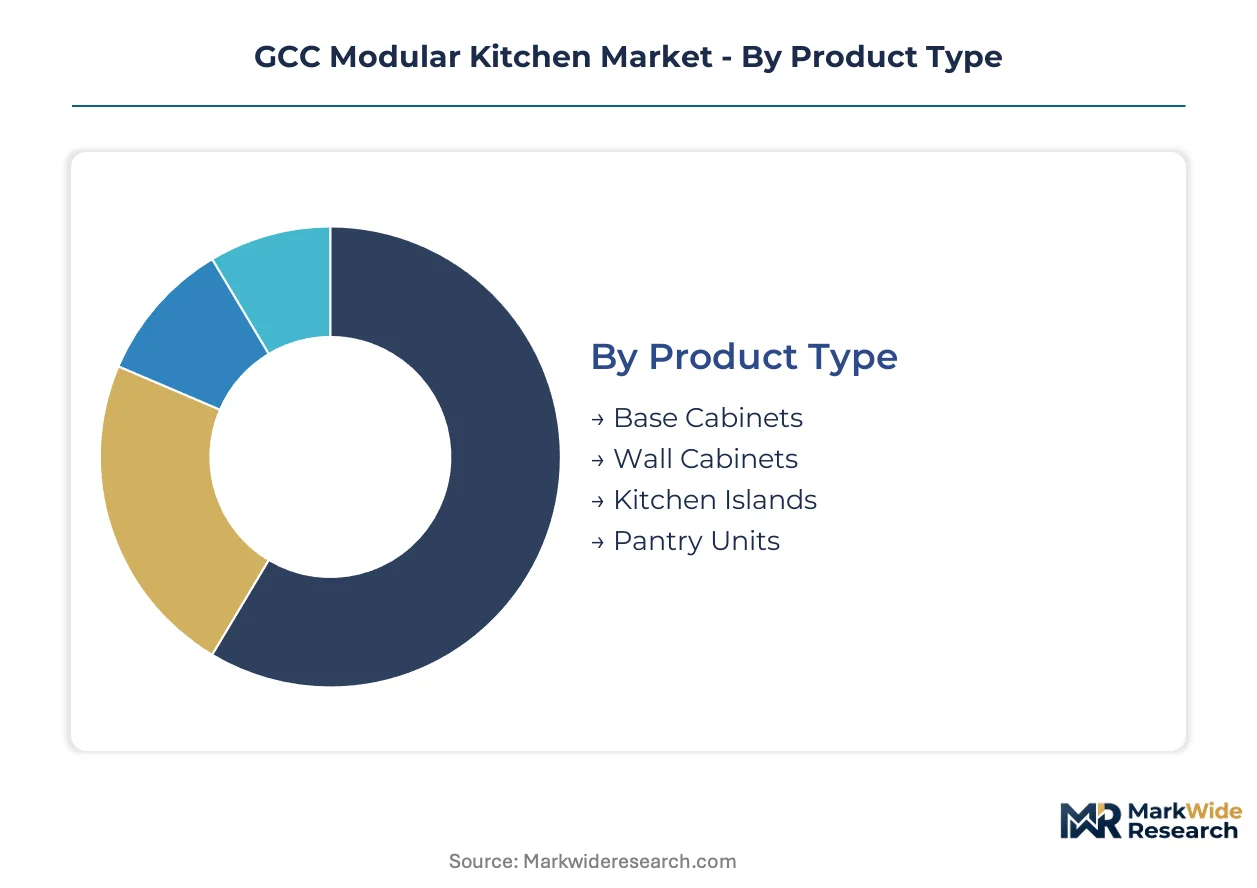
Segmentation in the GCC modular kitchen market reveals distinct procurement patterns across product architectures, substrate technologies, aesthetic positioning, and assembly methodologies. Each dimension carries implications for project cycle times, compliance burden, and margin structure in high-rise residential developments across Dubai, Riyadh, and Doha.
Product Type:
Base cabinets and kitchen islands command the longest production lead times due to appliance integration complexity, while wall cabinets and pantry units turn faster through standardized dimensioning.
- Base Cabinets:These floor-mounted units incorporate sink basins, cooktop cutouts, and dishwasher housings within 18mm melamine-faced particleboard carcasses. Dubai's high-rise residential towers specify these most heavily, where SFDA fire-retardant mandates for high-density housing elevate material certification requirements.
- Kitchen Islands:Freestanding central units with countertop overhangs for seating integrate electrical and plumbing rough-ins through steel reinforcement channels. Riyadh's luxury residential pipeline favors these for open-plan layouts, though installation workforce scarcity in secondary Saudi cities creates scheduling bottlenecks.
- Wall Cabinets:Overhead storage units mount on concealed suspension rails with 32mm system drilling patterns.
- Pantry Units:Full-height pull-out larder systems with soft-close hardware maximize vertical storage in compact UAE apartments.
Base cabinets anchor the volume base while kitchen islands gain share at the steepest rate.
Material:
Substrate selection correlates directly with coastal proximity and maintenance contract terms, with synthetic materials commanding premium positioning in salt-air environments.
- MDF:Medium-density fiberboard with melamine or acrylic surfacing offers uniform density for precision machining of handle-less cabinet doors. Abu Dhabi and Doha developers specify these for humidity resistance, where salt-laden air degrades natural timber finishes and service contracts favor lower-maintenance synthetic substrates.
- Acrylic:High-gloss thermoformed surfaces provide seamless, non-porous finishes with superior UV stability. This specification is climbing fastest in Dubai's premium residential segment as developers prioritize lifecycle maintenance cost reduction over initial material outlay.
- Wood:Solid timber and wood veneer finishes face displacement pressure in coastal GCC cities.
- Plywood:Cross-laminated veneer construction offers structural integrity for load-bearing cabinet applications.
MDF dominates current specification volumes while acrylic is expanding most quickly through premium residential channels.
Style:
Aesthetic positioning stratifies across developer tier and end-buyer demographic, with contemporary and modern styles aligning to institutional procurement preferences.
- Modern:Clean-lined, handle-less cabinetry with integrated appliances and minimalist hardware. This style concentrates in Abu Dhabi's Al Reem Island developments, where specification-stage buyers at experience centers prioritize visual continuity with open-plan living spaces.
- Contemporary:Transitional aesthetics blending flat-panel doors with subtle decorative elements. Kuwait and Bahrain show rising specification here as first-mover suppliers target underpenetrated markets with differentiated styling.
- Traditional:Raised-panel doors with ornamental molding and classic hardware profiles.
- Rustic:Distressed finishes and visible grain patterns mimicking reclaimed timber.
Modern styling holds the largest installed base while contemporary is climbing the fastest among new developments.
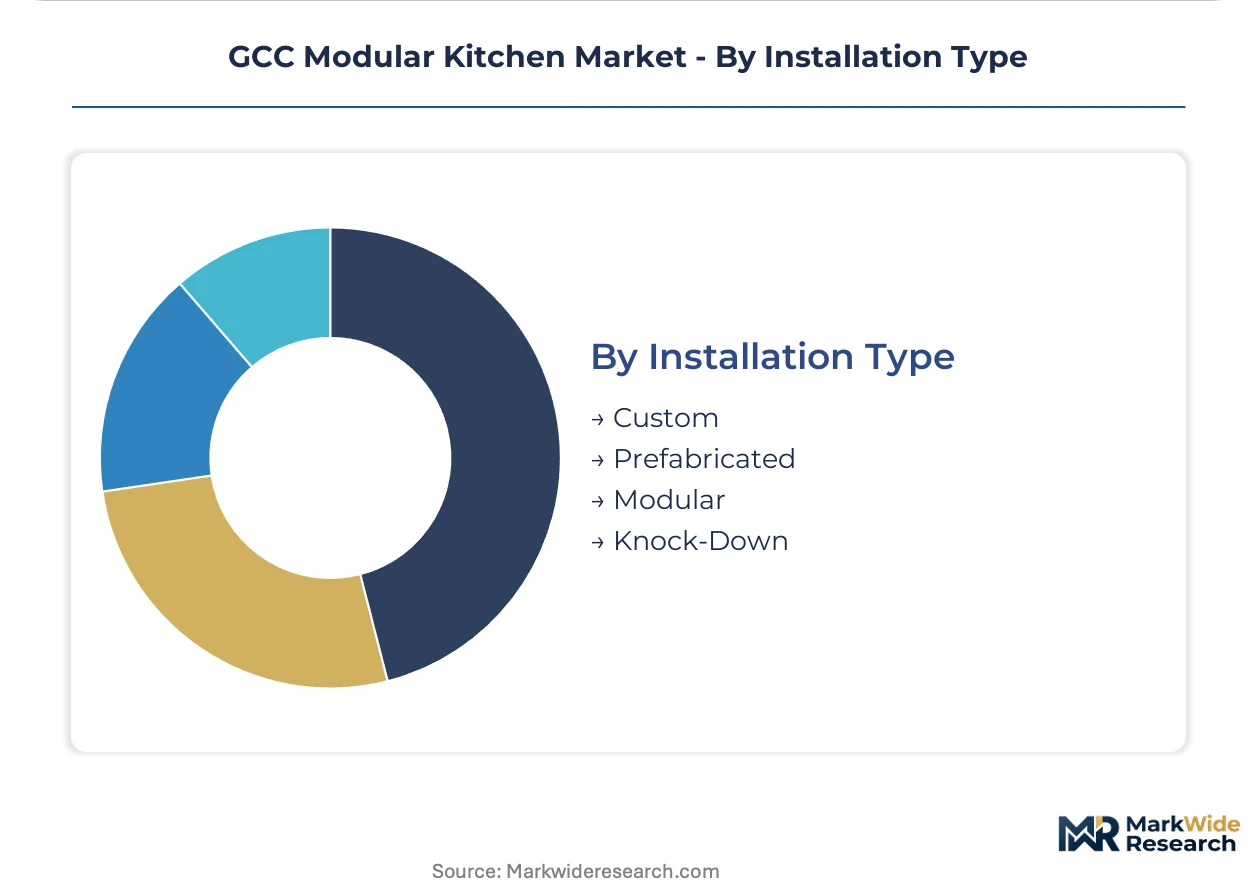
Installation Type:
Assembly methodology determines on-site labor intensity and project handover velocity, with prefabricated systems compressing construction schedules in tower developments.
- Prefabricated:Factory-complete cabinet assemblies with pre-installed countertops and hardware arrive for drop-in placement. Riyadh's high-rise residential pipeline favors these for schedule acceleration, where Saudi Building Code thermal performance standards are converging with UAE Civil Defense requirements to enable cross-border product platform standardization.
- Modular:Standardized carcass dimensions with interchangeable fronts enable post-occupancy reconfiguration. Dubai contractors specify these for rental apartment portfolios, where tenant turnover drives demand for adaptable kitchen layouts.
- Custom:Site-measured, bespoke fabrication for irregular spatial configurations.
- Knock-Down:Flat-pack components for end-user assembly, concentrated in entry-level segments.
Prefabricated systems anchor the volume base while modular configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Vision 2030 local content mandates are redirecting procurement flows toward domestic fabricators, compressing import timelines and reshaping supplier relationships across the Gulf. Dubai's high-rise residential pipeline and Abu Dhabi's coastal developments anchor volume demand. Municipality-level permitting requirements in Riyadh and Dubai now mandate third-party certification, filtering supplier bases and extending procurement cycles.
United Arab Emirates
Dubai's Design District and Abu Dhabi's Al Reem Island host the region's densest cluster of premium modular kitchen showrooms, driving specification-stage buyer concentration. MOHAP and UAE Civil Defense fire-rating requirements mandate tested substrate portfolios for high-density housing approvals. Salt-laden coastal air across Abu Dhabi and Dubai is degrading natural timber finishes, pushing developers toward acrylic surfacing with lower maintenance clauses.
Saudi Arabia
Riyadh's high-rise residential pipeline favors prefabricated kitchen systems for schedule acceleration and reduced on-site labor hours. SFDA building codes now require fire-retardant surface materials in high-density housing, forcing specification upgrades toward certified suppliers. The Eastern Province's industrial zones are attracting domestic assembly operations as local content thresholds rise under Vision 2030 programs.
Qatar
Doha's coastal developments specify humidity-resistant substrates as salt-laden air accelerates natural timber degradation in service contracts. The country's national building regulator mandates thermal performance standards that converge with UAE and Saudi requirements. Lusail City and West Bay clusters concentrate specification activity for premium residential towers.
Kuwait
Kuwait City and surrounding governorates show lower modular kitchen saturation than UAE and Saudi markets, offering first-mover positioning for suppliers with GCC-wide logistics networks. Municipality fit-out permitting requires compliance with Gulf Standardization Organization specifications for panel substrates. The Salmiya and Sharq districts host emerging specification activity for mid-rise residential developments.
Bahrain
Manama's residential construction pipeline remains underpenetrated relative to regional peers, creating opportunities for experience center channel establishment. The country's national regulator aligns fire-safety and material emission standards with Saudi SFDA and UAE Civil Defense frameworks. Seef and Juffair districts concentrate developer procurement activity for tower developments.
GCC Modular Kitchen Market Key Industry Players
On the supply side, the industry is consolidating around full-service providers capable of design-through-installation bundling, marginalizing standalone cabinet OEMs without captive hardware ecosystems or last-mile capabilities. Three strategic archetypes dominate: European-origin specialists with tested substrate portfolios, regional hypermarket operators controlling delivery scheduling, and flat-pack logistics players anchoring entry-level segments. Competitive moves concentrate on geographic expansion into underpenetrated Gulf markets and backward integration into hardware supply.
Within the European-origin specialist tier, Hafele and Hacker Kitchens exemplify positioning around certified substrate portfolios and captive hardware ecosystems that lock in cabinet OEM relationships. Among regional fabricators, Danube Home occupies a position leveraging hypermarket footprint across the UAE and Saudi Arabia to control last-mile delivery and installation scheduling. At the scale-driven end, Inter Ikea Group anchors volume in entry-level segments across Gulf urban corridors through flat-pack logistics density.
| Leading Market Players |
|---|
| Danube Home |
| Hafele |
| Inter Ikea Group |
| International Kitchens |
| Al Marri Metal Kitchen Factory |
| Kitchen Line |
| Hacker Kitchens |
| Al Marhaba Kitchen |
| Kitchen King |
| Others |
Cost & Logistics Intelligence
Overcapacity in Turkish cabinet fabrication is compressing margins for European-origin suppliers while creating procurement leverage for Dubai and Riyadh developers negotiating volume contracts. This utilization imbalance rewards full-service providers with captive hardware ecosystems and punishes standalone OEMs exposed to raw material volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified fire-retardant substrates from conventional melamine-faced particleboard and entry-level knock-down kits. Price differentiation hinges on SFDA certification status and volume scale, with project-based developers commanding steepest discounts. Pricing pressure stems from Saudi Vision 2030 local content mandates redirecting procurement toward domestic fabricators. Economy-tier buyers in Bahrain and Kuwait show highest price sensitivity, while premium-segment purchasers in Abu Dhabi's Al Reem Island prioritize lifecycle maintenance cost reduction over upfront outlay.
Supply Chain Analysis
Export-control regimes limiting specialty hardware and fire-retardant coating technology flows from Germany and Italy are forcing GCC fabricators toward alternative certification pathways. Supply concentrates in Turkey, China, and domestic Saudi assembly operations, with 18mm melamine-faced particleboard and acrylic surfacing as critical inputs. Single-source vulnerability runs through Turkish cabinet OEMs facing displacement by Saudi local content thresholds. Distribution runs through hypermarket operators controlling last-mile delivery scheduling and experience centers capturing specification-stage buyers before retail touchpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA fire-retardant mandates and converging UAE-Saudi building codes are reshaping competitive positioning by elevating compliance costs and compressing procurement timelines for uncertified suppliers.
For Market Incumbents: Pre-empt margin erosion from domestic Saudi fabricators by securing backward integration into hardware supply and establishing Dubai-based testing partnerships for pan-Asian panel suppliers. Lock in developer relationships through full-service bundling that captures specification-stage buyers at experience centers before competitor reach.
For New Entrants and Emerging Players: Build out presence in Kuwait and Bahrain where modular kitchen saturation lags UAE and Saudi benchmarks, targeting mid-rise residential developments with contemporary styling differentiated from entrenched modern aesthetics. Penetrate through direct-to-developer channels bypassing fragmented retail structures.
For Investors and Strategic Acquirers: Capital is best deployed toward full-service providers with captive hardware ecosystems and GCC-wide logistics networks capable of design-through-installation bundling. Long-term viability centers on compliance infrastructure for multi-jurisdiction certification. Watch for Saudi local content threshold acceleration as inflection signal for Turkish supplier displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Experience Center Channel Establishment | Captures specification-stage buyers in Dubai Design District before retail fragmentation accelerates. |
| Backward Integration into Hardware Supply | Hafele's captive ecosystem model locks in cabinet OEM relationships and defends margin structure. |
| Dubai-Based Testing Partnership Formation | Enables pan-Asian panel suppliers to maintain market access under SFDA emission certification requirements. |
| Kuwait and Bahrain Geographic Expansion | First-mover positioning in underpenetrated markets with lower competitive density than UAE-Saudi corridor. |
| Full-Service Provider Consolidation | Marginalizes standalone OEMs without last-mile capabilities as developer procurement teams consolidate vendor relationships. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and municipal permitting records across Dubai, Riyadh, and Doha. Primary interviews engaged procurement directors at high-rise residential developers, showroom operators in Dubai Design District, and compliance officers at panel substrate suppliers. Secondary sources included SFDA material safety notifications, UAE Civil Defense fire-rating specifications, Saudi Building Code thermal performance standards, and municipality fit-out permitting databases. Bottom-up project pipeline assessment triangulated against top-down construction spend forecasts.
Forecast inputs span product architecture segmentation by base cabinet, kitchen island, wall cabinet, and pantry unit configurations; substrate technology tiers across MDF, acrylic, wood, and plywood; aesthetic positioning across modern, contemporary, traditional, and rustic styling; and assembly methodology across prefabricated, modular, custom, and knock-down systems. CAGRs derive from regression analysis against residential construction permit volumes and hospitality development pipelines. Industry-specific inputs incorporate SFDA certification timeline compression and Vision 2030 local content threshold trajectories.
Practitioners should monitor Saudi local content mandate acceleration, UAE-Saudi building code convergence velocity, and formaldehyde certification bottleneck duration for early signals of supply chain restructuring. Forecasts reflect assumptions regarding regulatory stability and construction pipeline execution. Material shifts in Vision 2030 industrial program intensity or municipality permitting requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Dining Table Market