
 US Faucet Market | 2026-2036
US Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
US Faucet Market Intelligence
The substitution of traditional brass with lead-free stainless steel alloys is rebalancing product cost structures across the US faucet market. Kohler Co. sustains its position through extensive brand recognition and a diversified product portfolio. Moen Inc. differentiates with its focus on smart home integration and electronic faucet technologies. Masco Corporation leverages its multi-brand strategy, including Delta and Brizo, to control significant shelf space in key retail channels.
A faucet is a valve-controlled device that delivers water from a plumbing system. These fixtures regulate flow rates, typically between 1.0 and 2.2 gallons per minute, and are constructed from materials like brass, stainless steel, or zinc alloys. Kitchen faucets, particularly pull-down and pull-out installation types, represent a high-value product category driven by feature innovation. While the residential end-user segment constitutes the largest volume, the commercial sector offers higher margins for specialized, durable fixtures.
The EPA's WaterSense program sets voluntary standards for water efficiency, influencing product design and consumer choice. Concurrently, mandates under the Safe Drinking Water Act (SDWA) strictly limit the lead content in plumbing fixtures, requiring manufacturers to use certified lead-free materials. Future competitive advantage will hinge on integrating smart technology for water monitoring and control while navigating evolving state-level water conservation mandates.
Market Dynamics
The US faucet market's evolution is defined by the requirement to balance water conservation with consumer demand for performance and luxury. Federal and state-level water efficiency mandates, led by the EPA, create a baseline for innovation in flow-rate technology.
Growth Catalysts
- Hospitality Sector Expansion:Growth in hotel and resort construction fuels demand for premium, aesthetically differentiated fixtures that enhance the guest experience and align with brand standards for luxury and sustainability.
- New Residential Construction:A primary locus of demand is concentrated in high-growth states, such as Texas and Florida, where new single-family and multi-family housing projects require large volumes of fixtures.
- EPA WaterSense Program:The voluntary WaterSense certification acts as a powerful market driver, encouraging consumers and builders to select water-efficient models through utility rebates and a clear labeling standard.
Market Restraints
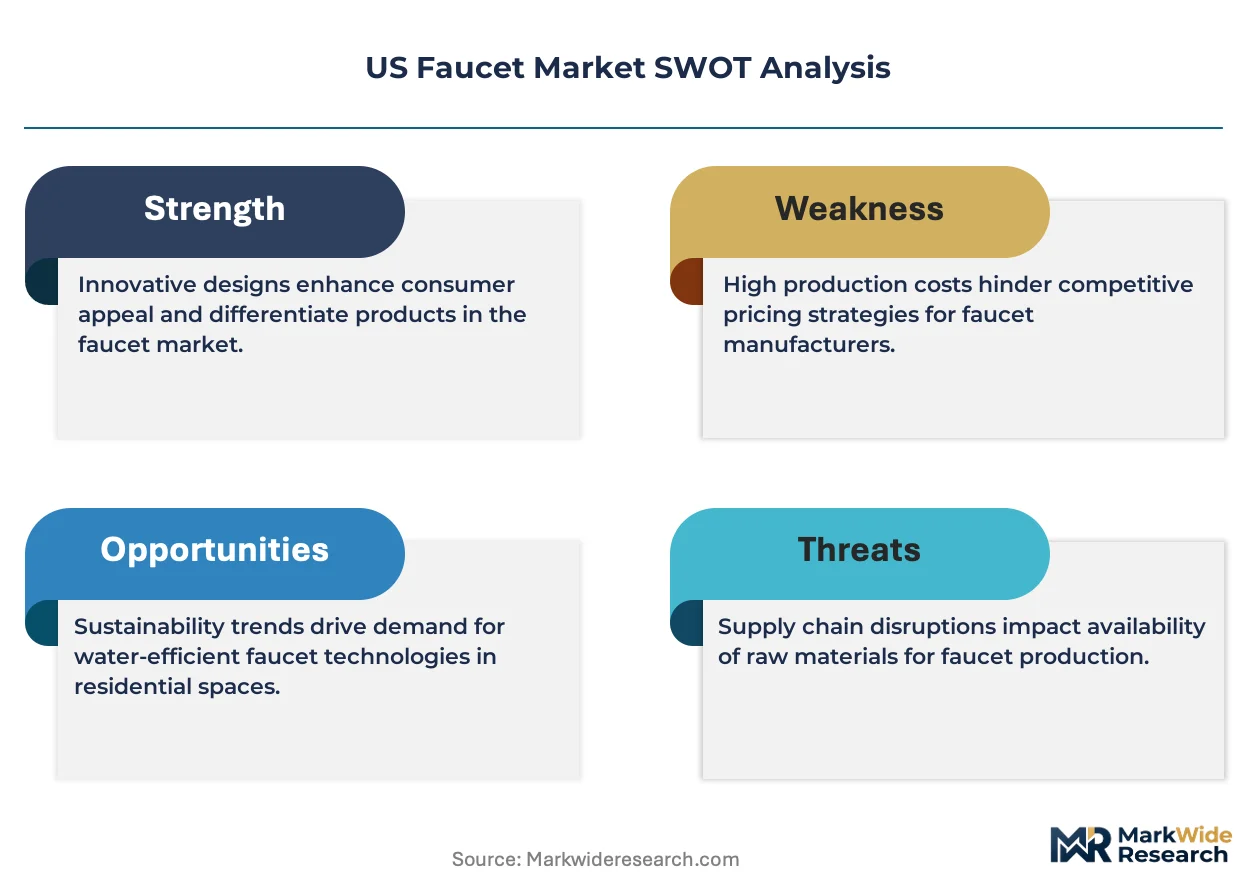
- Input Cost Volatility:Fluctuations in the price of raw materials, particularly certified lead-free brass and stainless steel alloys, directly impact manufacturing costs and create pricing pressure for finished goods.
- Regulatory Compliance Burden:The Safe Drinking Water Act (SDWA) imposes strict, non-negotiable limits on lead content, requiring rigorous testing and certification processes that add complexity and expense to the supply chain.
- Channel Consolidation:The significant market power of large home improvement retailers creates margin pressure on manufacturers and limits shelf space for smaller or emerging brands.
Strategic Opportunities
- Smart Home Integration:There is a significant opening for faucets with integrated IoT capabilities for water monitoring, leak detection, and voice activation, catering to the tech-forward residential segment.
- Water-Stressed Regions:Evolving state-level conservation mandates, especially in western states, create a dedicated market for ultra-high-efficiency fixtures that exceed current federal WaterSense standards.
- Multi-Family Development:The build-to-rent and large-scale apartment sectors represent a distinct opportunity for durable, standardized, and easily serviceable faucet designs that offer a low total cost of ownership.
Industry Challenges
- Fragmented State Regulations:Manufacturers face complexity in managing product portfolios to comply with a patchwork of state-specific water efficiency and material content laws that go beyond federal minimums.
- Skilled Labor Shortages:A lack of trained plumbers proficient in installing and servicing advanced electronic and software-integrated faucets can limit the adoption rate of these higher-margin products.
- Certification Timelines:The time and cost associated with obtaining necessary certifications, such as NSF/ANSI 61 for material safety and WaterSense for efficiency, can delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Faucet Market |
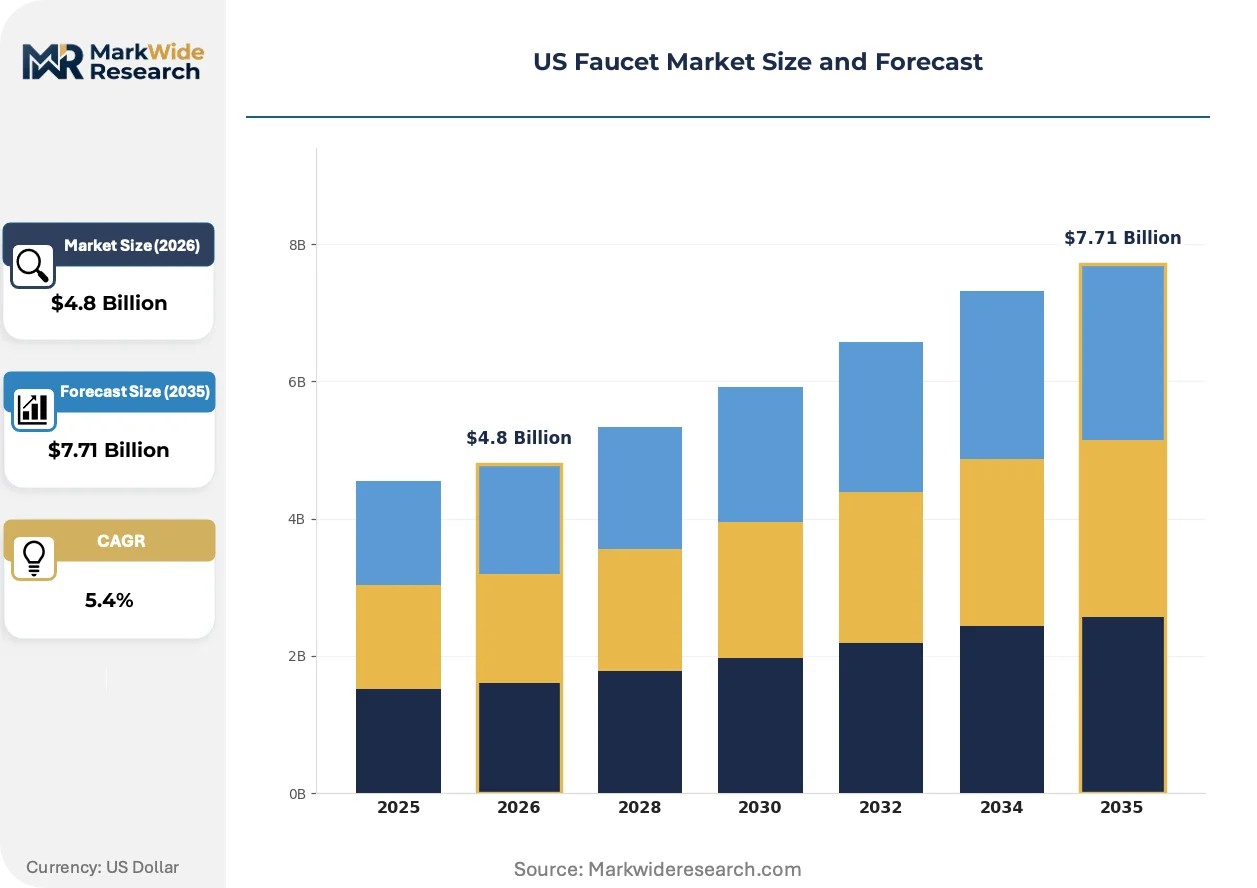
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Faucets, Bathroom Faucets, Utility Faucets, Bar Faucets Installation Type: Wall-Mounted, Deck-Mounted, Pull-Down, Pull-Out Material: Stainless Steel, Brass, Plastic, Bronze End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Delta Faucet Company, American Standard, Fortune Brands Home & Security, Inc., Kraus, Pfister, Kohler Co., Moen Inc., Brizo, Masco Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Faucet Market Strategic Shifts & Innovations
Product innovation in the US faucet market is reshaping the fixture from a purely mechanical device into an integrated component of the smart and health-conscious home. This evolution is driven by advances in sensor technology and a greater consumer focus on hygiene and resource management.
Electronic and touchless faucet technology, which utilizes infrared or capacitive sensors to automate water delivery, is a key product evolution. The commercial sector, particularly in healthcare and hospitality settings, remains the primary adopter for hygiene reasons, but residential adoption is accelerating in high-end kitchens. This technology is rewriting user expectations for convenience and cleanliness, establishing a new standard for hands-free operation in both public and private environments.
The EPA's WaterSense program continues to be a powerful regulatory influence on product design. The program's voluntary standards for water efficiency compel manufacturers to engineer faucets that reduce flow rates without a noticeable degradation in performance. The residential segment is the most affected, as utility rebate programs and prominent retail marketing of WaterSense-labeled products guide consumer purchasing decisions toward certified, water-saving models.
A distinct shift in buyer behavior is the growing emphasis on achieving a cohesive design aesthetic across all plumbing fixtures within a home. This trend disrupts the traditional one-off replacement purchase, favoring manufacturers that offer broad product families with matching styles and finishes like matte black or brushed gold. This pattern is most visible in the residential renovation market, where creating a unified visual theme is a primary project objective.
US Faucet Market Segmentation
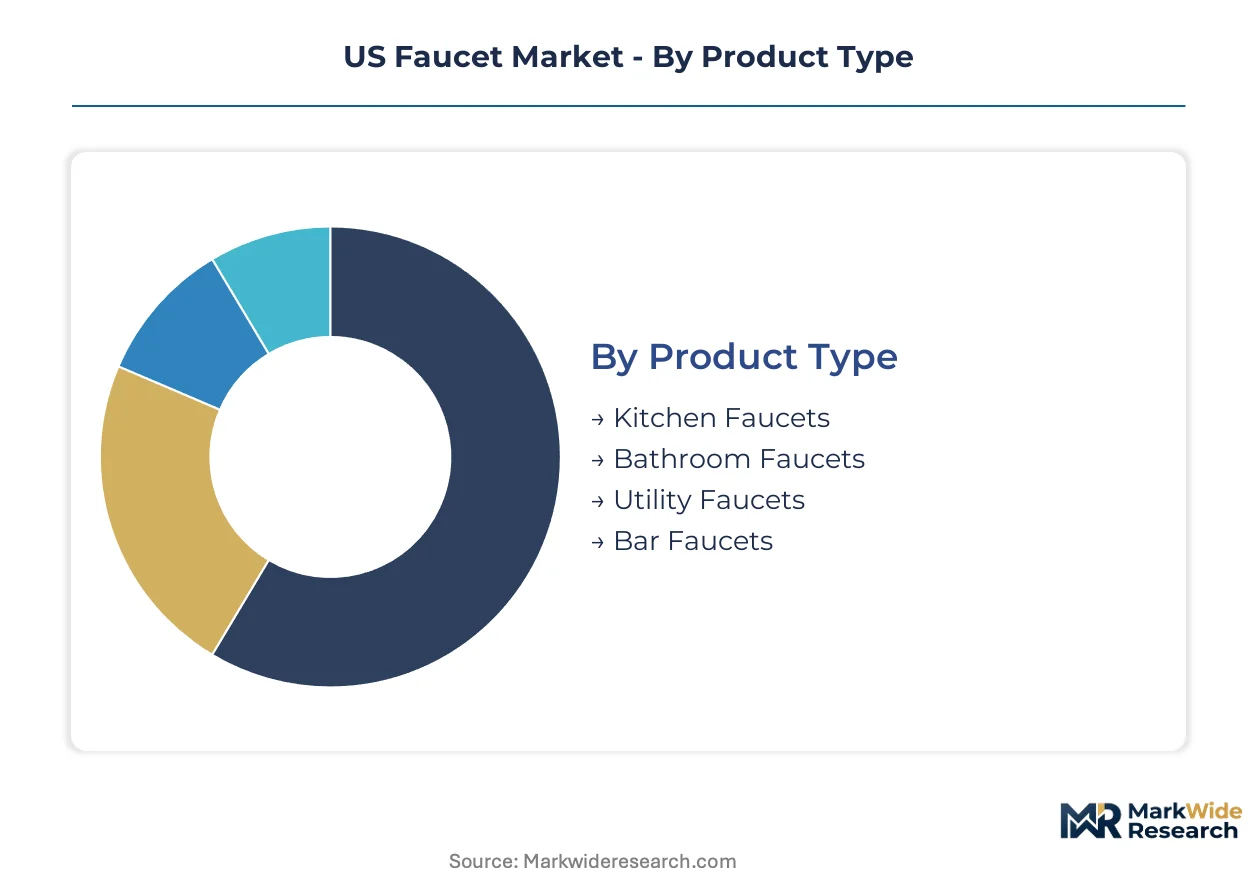
The US faucet market segmentation reveals how diverse product attributes, installation methods, material compositions, and end-user applications influence demand dynamics and competitive positioning. Understanding these distinct segments is crucial for manufacturers and distributors to tailor product development and market strategies effectively.
Product Type:
The integration depth of faucet products ranges from standalone mechanical devices to units with embedded electronic controls for enhanced functionality.
- Kitchen Faucets:These fixtures are designed for food preparation and cleaning tasks, often incorporating pull-down or pull-out spray heads for added convenience. Demand concentrates in the US residential renovation market, driven by feature innovation and consumer desire for high-performance, aesthetically pleasing designs.
- Bathroom Faucets:Primarily used for handwashing and personal hygiene, these faucets emphasize aesthetic design, water efficiency, and a variety of finishes. The hospitality sector and new residential construction in states like Texas significantly drive demand for models that align with modern interior design trends and water conservation goals.
- Utility Faucets:These robust, functional fixtures are typically found in laundry rooms, garages, or basements, prioritizing durability and basic water delivery over aesthetics. Commercial and industrial end-users account for consistent demand, requiring fixtures that withstand heavy use.
- Bar Faucets:Smaller in scale and often decorative, bar faucets serve secondary sink areas in kitchens or dedicated entertainment spaces. Luxury residential projects and high-end hospitality venues in the US frequently incorporate these specialized fixtures.
Volume placements concentrate in Bathroom Faucets; the faster expansion belongs to Kitchen Faucets.
Installation Type:
Installation methods for US faucets reflect diverse functional requirements across residential and commercial settings.
- Wall-Mounted:These faucets are installed directly into the wall, offering a minimalist aesthetic and freeing up counter space, particularly in smaller bathrooms or commercial restrooms. Modern residential designs and high-end commercial projects increasingly specify wall-mounted options for their clean lines.
- Deck-Mounted:The most common installation type, these faucets are mounted directly onto the sink or countertop, accommodating a wide range of designs and configurations. New residential construction in states like Florida consistently relies on deck-mounted fixtures due to their versatility and ease of installation.
- Pull-Down:Featuring a spray head that pulls directly down into the sink, these kitchen faucets offer extended reach and versatility for washing large pots and pans. Residential consumers prioritize these models for their convenience and ergonomic benefits, especially in busy kitchens.
- Pull-Out:Similar to pull-down, pull-out faucets have a spray head that extends horizontally, offering flexibility for various kitchen tasks. This installation type is popular in residential kitchens where users value a more compact and direct spray function.
Traditional deck-mounted units secure the largest volume share, while pull-down installations command premium pricing.
Material:
Material choices for US faucets are increasingly dictated by health regulations and raw material cost volatility.
- Stainless Steel:Valued for its lead-free composition, corrosion resistance, and modern aesthetic, stainless steel is gaining prominence as a premium material in both residential and commercial applications. Compliance with the Safe Drinking Water Act mandates drives adoption in new construction and renovation projects across the US.
- Brass:Traditionally the most common material due to its durability and malleability, brass alloys are now subject to strict lead content limits under federal regulations. Manufacturers primarily use lead-free brass for residential and commercial fixtures, balancing cost and regulatory compliance.
- Plastic:Lightweight and cost-effective, plastic faucets are typically found in utility applications or budget-conscious installations where high durability or aesthetic appeal are not primary concerns. Industrial and basic commercial settings utilize plastic for specific non-potable water uses.
- Bronze:Often used for its distinctive appearance and antique or rustic aesthetic, bronze faucets are typically found in luxury residential and hospitality projects. These fixtures emphasize design and finish quality.
Lead-free brass remains a foundational material, though stainless steel is gaining traction for its durability and regulatory compliance.
End User:
Demand patterns for US faucets are shaped by distinct operational requirements and aesthetic preferences across various user groups.
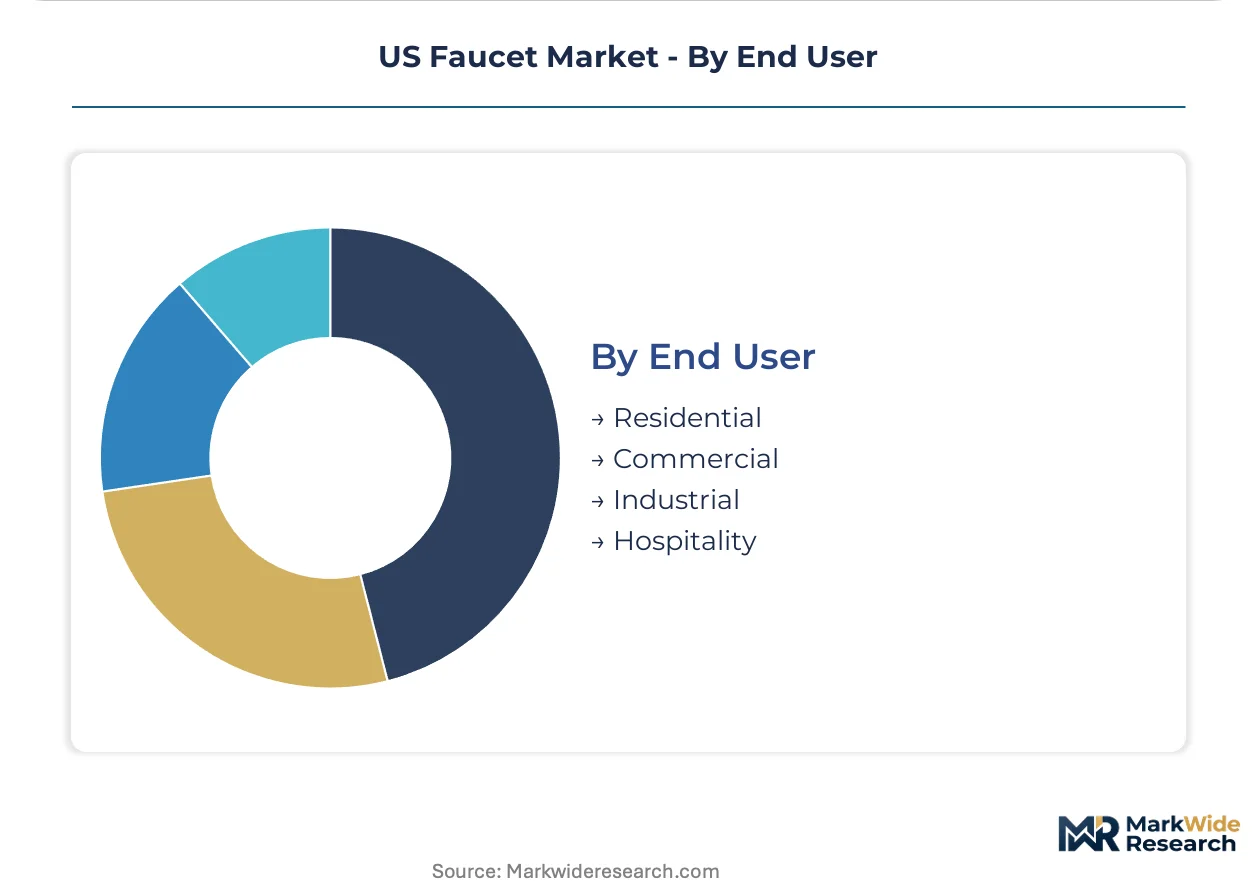
- Residential:This segment includes single-family homes and multi-family dwellings, representing the largest volume of faucet consumption. New residential construction and renovation projects, particularly in high-growth states, drive demand for a wide range of styles and water-efficient models.
- Commercial:Encompassing office buildings, public facilities, and retail spaces, the commercial sector demands durable, high-traffic fixtures that meet specific ADA compliance and hygiene standards. Facilities management teams prioritize longevity and ease of maintenance for these installations.
- Industrial:Industrial end-users, such as manufacturing plants and laboratories, require highly specialized and robust faucets designed for specific functional needs, often involving chemical resistance or high-pressure applications. These environments prioritize performance and safety over aesthetic considerations.
- Hospitality:Hotels, resorts, and restaurants require aesthetically pleasing, highly durable, and water-efficient faucets that align with brand standards and enhance guest experience. The expansion of the US hospitality sector directly fuels demand for premium fixtures in this segment.
The residential sector accounts for the largest volume consumption, while the hospitality segment offers higher margins for specialized fixtures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US faucet market experiences demand concentration in regions offering significant construction incentives and high population growth. States like Texas and Florida benefit from favorable business environments and continuous housing development. These areas drive substantial fixture volumes for both residential and commercial applications, alongside renovation activities.
Texas
New residential construction across Texas fuels substantial demand for a wide array of faucet types. The Safe Drinking Water Act strictly mandates lead-free materials for all plumbing fixtures installed throughout the state. Houston and Dallas see robust multi-family housing starts, requiring large volumes of standardized units.
California
Water conservation mandates in California significantly influence faucet design and consumer choice. State regulations, including CALGreen, actively promote the adoption of ultra-low flow fixtures. The San Francisco Bay Area leads in adopting smart, water-monitoring faucet technologies for high-end residential upgrades.
Florida
Hospitality sector expansion in Florida consistently drives demand for premium, aesthetically pleasing bathroom fixtures. The EPA's WaterSense program encourages the selection of water-efficient models through utility rebates. Orlando's tourism growth and Miami's luxury residential market require high-end, durable, and stylish faucets.
New York Metro
Renovation projects within the dense New York Metropolitan Area create consistent demand for stylish kitchen and bathroom faucets. Local building codes often exceed federal efficiency standards, pushing manufacturers towards advanced designs. Manhattan and Brooklyn brownstone renovations frequently specify designer fixtures with unique finishes.
Pacific Northwest
A strong emphasis on sustainability in the Pacific Northwest influences consumer preference for eco-friendly faucets. Regional policies in Washington and Oregon promote stringent water efficiency standards. Seattle's tech-driven residential market adopts advanced water-saving and smart faucet technologies.
US Faucet Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The US faucet market exhibits a consolidation among established brands, while numerous smaller players often serve niche segments or private label needs for retailers. Strategic archetypes include innovation-driven premium brands, value-focused mass-market suppliers, and specialized commercial fixture providers. Portfolio diversification across product categories and strategic partnerships represent dominant competitive moves among larger entities seeking to expand their market footprint.
On the premium-tier vector, Kohler Co. exemplifies a brand sustained by extensive recognition and a diversified product portfolio catering to various aesthetic and functional needs. Moen Inc. represents a player differentiating through smart home integration and electronic faucet technologies, targeting tech-forward consumers. Masco Corporation, leveraging its multi-brand strategy including Delta Faucet Company and Brizo, controls significant shelf space in key retail channels. These entities collectively influence product innovation, distribution strategies, and consumer preferences within the competitive market.
| Leading Market Players |
|---|
| Delta Faucet Company |
| American Standard |
| Fortune Brands Home & Security, Inc. |
| Kraus |
| Pfister |
| Kohler Co. |
| Moen Inc. |
| Brizo |
| Masco Corporation |
| Others |
Cost & Logistics Intelligence
The London Metal Exchange (LME) copper price directly influences lead-free brass costs, cascading through the US faucet market into varied pricing tiers. This volatility impacts manufacturing expenses and consumer pricing across product categories.
Pricing Analysis
Short lead-time availability for specialized fixtures commands a premium, while standard models often see discounts for high-volume spot inventory. The dominant pricing model is per-unit transactional, with project-based contracts common for large construction. Price differentiation stems from brand premium, material quality (stainless steel versus lead-free brass), and WaterSense certification. Pricing softness stems from input cost volatility for lead-free alloys and channel consolidation by large home improvement retailers. Residential consumers, particularly in the basic segment, exhibit the highest price sensitivity; luxury hospitality projects are less sensitive.
Supply Chain Analysis
Reverse logistics for faucet components, particularly for electronic and smart models, primarily manages warranty returns and refurbishment programs. Supply concentration for raw materials like lead-free brass and stainless steel is global, while finished goods often source from China and Mexico for cost efficiency. The market relies on electronic components for smart faucet integration. Commodity price volatility for key metals represents a significant structural risk. Distribution runs through large home improvement retailers and specialized plumbing wholesalers, with direct-to-builder channels for new construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US faucet market is navigating a technology-transition phase, with electronic and touchless faucet technology steadily displacing traditional mechanical devices. This shift redefines user expectations for convenience and hygiene.
For Market Incumbents: To counter the threat of rapidly evolving smart home integration, incumbent manufacturers must accelerate R&D in IoT-enabled water monitoring and control. Consolidating supply chain relationships for certified lead-free materials reduces input cost volatility. Expanding product portfolios across all aesthetic trends, like matte black finishes, reinforces brand loyalty. Strategic partnerships with smart home platform providers secure future market relevance.
For New Entrants and Emerging Players: Enter via specialized niches such as ultra-high-efficiency fixtures for water-stressed regions or standardized, durable designs for multi-family developments. The tech-forward residential segment offers a penetrable entry point for IoT-enabled faucets with leak detection and voice activation. Go-to-market strategies should emphasize seamless smart home ecosystem integration and clear total cost of ownership benefits. Partnering with smart home installers and property developers can accelerate adoption.
For Investors and Strategic Acquirers: Distressed-cycle entries favor agile technology specialists in high-growth states like Texas and Florida. The long-term viability of the faucet market remains robust, driven by essential infrastructure and continuous construction. Acquisition targets should prioritize mid-sized firms with strong intellectual property in smart water technology or established channels in the multi-family sector. A key signal to watch is the accelerated adoption rate of WaterSense-certified smart fixtures in new construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (Smart Faucet Line) | Introduces advanced water monitoring and control features for residential consumers. |
| Strategic Partnership (Smart Home Platforms) | Integrates faucets into broader home automation ecosystems, enhancing user convenience. |
| Distribution Channel Expansion (Multi-Family Developers) | Secures high-volume contracts for durable, standardized fixtures in new projects. |
| Green Certification Program (Ultra-Efficient Models) | Targets water-stressed regions with products exceeding federal conservation standards. |
| Manufacturing Scale-Up (Lead-Free Materials) | Ensures compliance with SDWA and reduces reliance on volatile external suppliers. |
Research Approach
Multi-period observation of new construction starts and renovation spending anchored the trend analysis, supplemented by interviews with plumbing contractors, residential developers, and hospitality procurement managers. This primary input was validated against secondary data from EPA WaterSense certifications, state building codes, and industry association publications. A rigorous bottom-up and top-down triangulation approach ensured data coherence.
The input-output matrix framing modeled market dynamics across the analysis window, segmenting by product type, installation method, material, and end-user. Compound annual growth rates were derived through regression analysis on historical data and market share projections. Key forecast inputs included residential housing starts and hospitality sector expansion rates for premium fixtures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant raw material price shocks or unforeseen state regulatory shifts. Forecasts reflect documented assumptions regarding construction activity and consumer adoption rates. Practitioners should monitor new state-level water conservation mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Toilet Partition Market