
 Global Wooden Tableware Market | 2026-2036
Global Wooden Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wooden Tableware Market Outlook
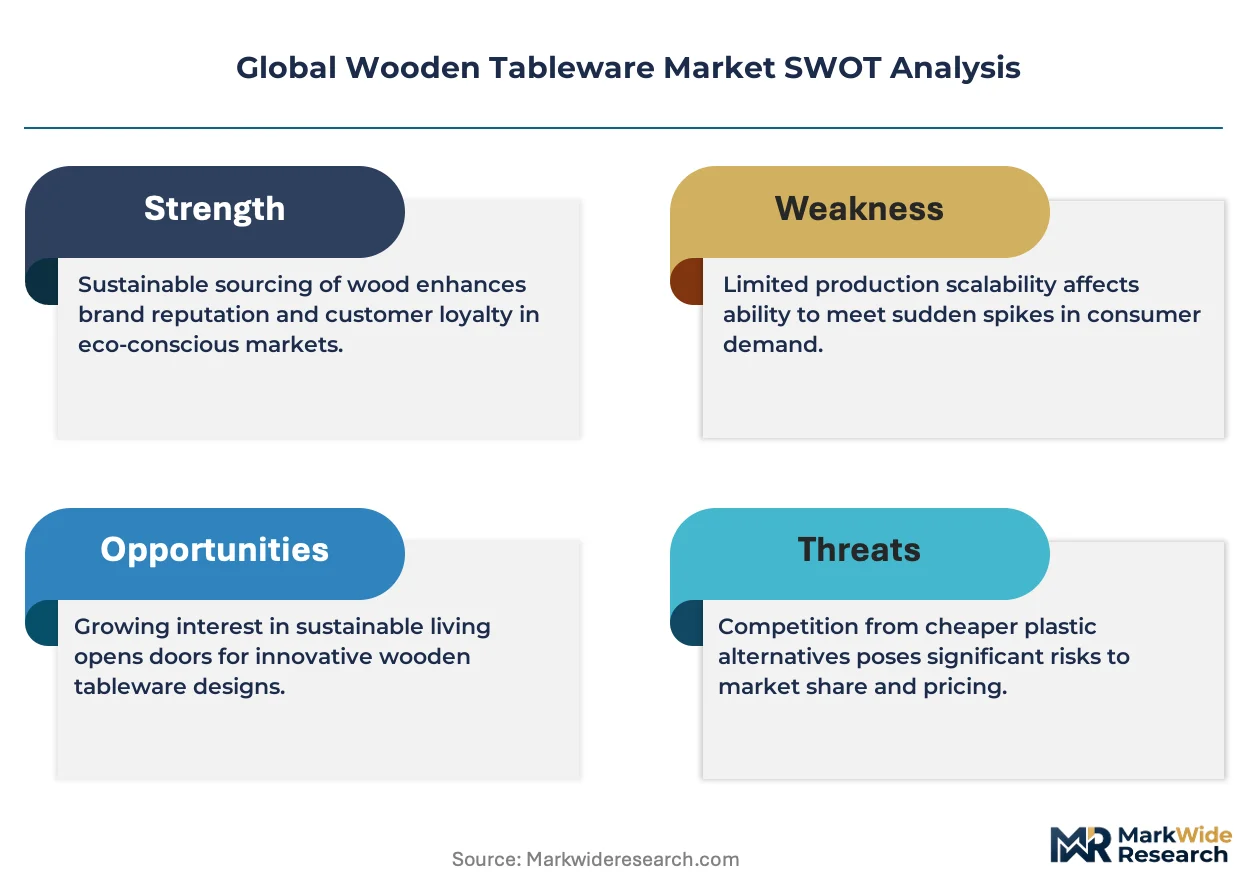
The EU Single-Use Plastics Directive is expanding addressable demand for compostable serviceware across European foodservice. Huhtamaki leverages its molded fiber and wood-pulp manufacturing footprint to supply quick-service chains with FSC-certified wooden cutlery. Biotrem anchors its position through patented wheat bran and wood-composite technology that extends beyond traditional birch offerings. Eco-Products, Inc. controls distribution through direct partnerships with North American institutional catering buyers.
Wooden tableware comprises disposable and semi-durable eating and serving implements manufactured from hardwood, bamboo, birch, or pine through processes including rotary cutting, hot pressing, and CNC shaping for dimensional precision. These products serve commercial foodservice and household segments seeking biodegradable alternatives to petroleum-based disposables. Birch plates and bowls occupy the mature volume core of the market, while bamboo cutlery registers the fastest expansion due to tensile strength properties that rival conventional plastics. Hardwood cups command premium positioning in specialty retail channels where grain aesthetics support higher price realization.
The EU Green Deal and REACH chemical safety frameworks govern surface treatment standards for wooden food-contact articles across Europe, while the FDA regulates coating migration limits in the United States. Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS standards for imported wooden goods that affect market access for Southeast Asian suppliers. Stakeholders must monitor evolving compostability certification requirements and raw material traceability mandates that will determine which suppliers retain foodservice contract eligibility.
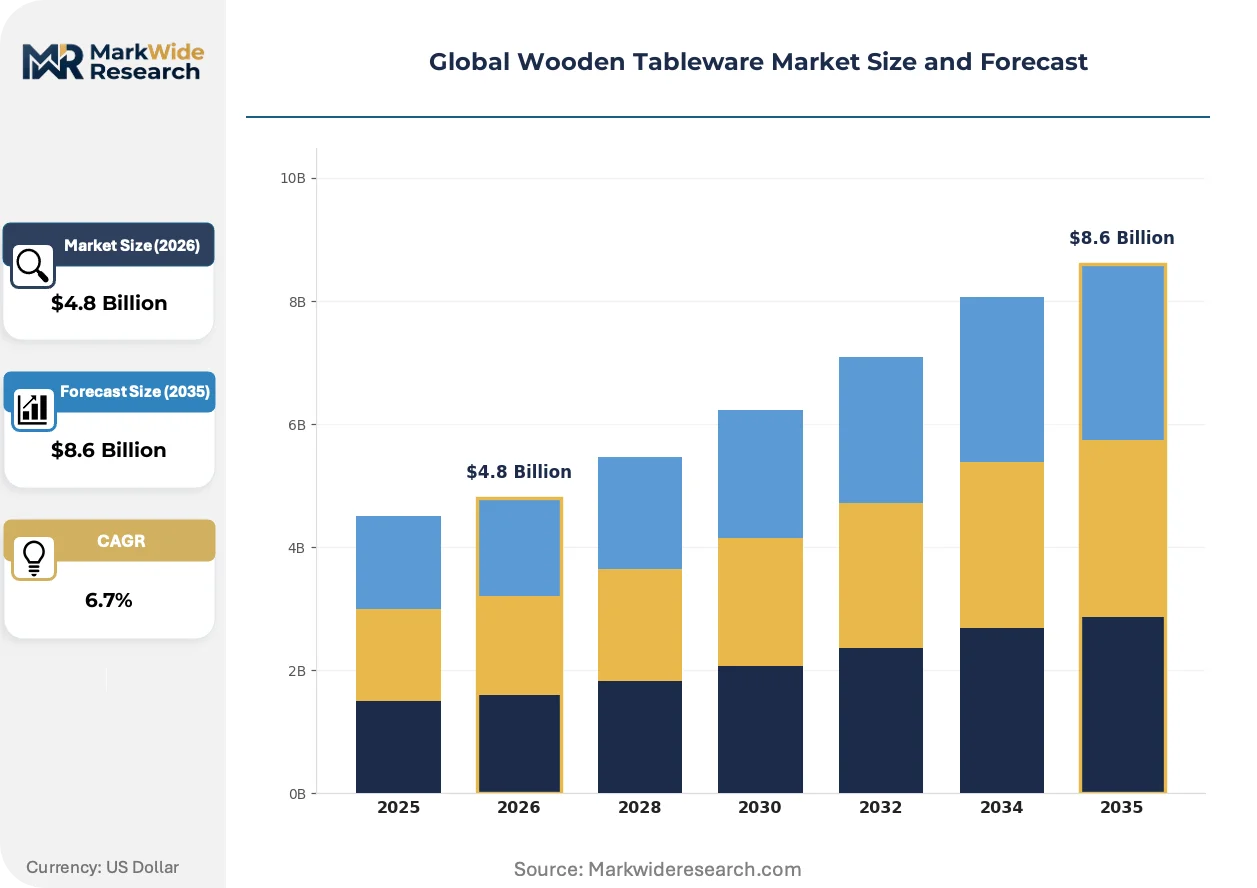
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for petroleum-based serviceware while redirecting foodservice procurement toward certified biodegradable alternatives, creating a structural pull that reshapes raw material sourcing and manufacturing scale across the value chain.
Growth Catalysts
- EU Green Deal implementation:The framework mandates sustainable food-contact materials across member states, forcing institutional buyers to source FSC-certified wooden alternatives for compliance.
- Bamboo tensile engineering:Process innovations in steam-compression and resin-free binding deliver cutlery performance rivaling conventional plastics, accelerating adoption in quick-service chains.
- Municipal plastic bans:Cities including Vancouver, San Francisco, and Paris have enacted prohibitions on single-use petroleum serviceware, creating localized demand spikes for birch and pine substitutes.
Market Restraints
- Birch supply concentration:Rotary-cut veneer production clusters in Nordic and Baltic regions, exposing manufacturers to weather-driven harvest volatility and freight cost spikes.
- Surface treatment compliance costs:REACH migration limits for coatings and FDA indirect food additive rules require specialized testing that elevates unit economics for smaller producers.
- Molded fiber substitution:Bagasse and agricultural residue alternatives compete on price in institutional catering, pressuring wooden tableware's share in volume-driven contracts.
Strategic Opportunities
- India foodservice expansion:Quick-service chain growth in tier-2 cities creates first-mover potential for compostable cutlery suppliers before local manufacturing scales.
- Carbon labeling convergence:EU CSRD disclosure requirements and corporate net-zero commitments position cradle-to-grave certified wooden goods as premium procurement options.
- Direct-to-hotel distribution:Bypassing traditional foodservice distributors through B2B platforms reduces margin compression and captures boutique hospitality segments.
Industry Challenges
- CNC programming specialization:Precision shaping for dimensional consistency in high-speed foodservice applications requires scarce technical talent in manufacturing regions.
- Compostability certification timelines:TÜV OK Compost and BPI validation processes extend product launch cycles, delaying revenue recognition for new material formulations.
- Forest chain-of-custody integration:FSC and PEFC traceability systems must interface with legacy ERP platforms, creating data reconciliation burdens across multi-tier supply networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wooden Tableware Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cutlery, Cups End User: Households, Restaurants, Cafés, Catering Services Material: Hardwood, Bamboo, Birch, Pine Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Huhtamaki, Dart Container Corporation, Biotrem, Eco-Products, Inc., Yash Pakka Limited, Georgia-Pacific, Pappco Greenware, Natural Tableware, DOpla SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wooden Tableware Market Strategic Shifts
Laser-sintered surface finishing and bio-based coating chemistries are compressing the performance gap between wooden disposables and petroleum alternatives, while procurement platforms consolidate buyer power and reshape how specifications travel through foodservice supply chains.
Steam-explosion fiber refinement is electrifying bamboo pulp processing by breaking lignin bonds without chemical delignification, yielding higher tensile strength in formed cutlery. Quick-service chains in Germany and the Netherlands are specifying these grades for heavy-duty applications. The technology is electrifying capacity expansion decisions as manufacturers weigh dedicated lines against hybrid pulp systems.
Japan's METI has tightened JIS S 2053 standards for wooden food-contact articles, mandating specific migration testing for heat-resistant coatings used in ramen and hot-pot service. Exporters from Vietnam and Indonesia face extended certification timelines. Specialty birch bowl producers are reformulating lacquer systems to meet the revised thermal stability thresholds.
Corporate sustainability officers now mandate compostability certification as a gate criterion before price negotiation, reversing traditional procurement sequences. Foodservice management companies in France and California have embedded BPI or TÜV OK Compost requirements into RFP templates. This specification-first behavior concentrates contract eligibility among pre-certified suppliers and compresses qualification windows for new market entrants.
Global Wooden Tableware Market Segmentation
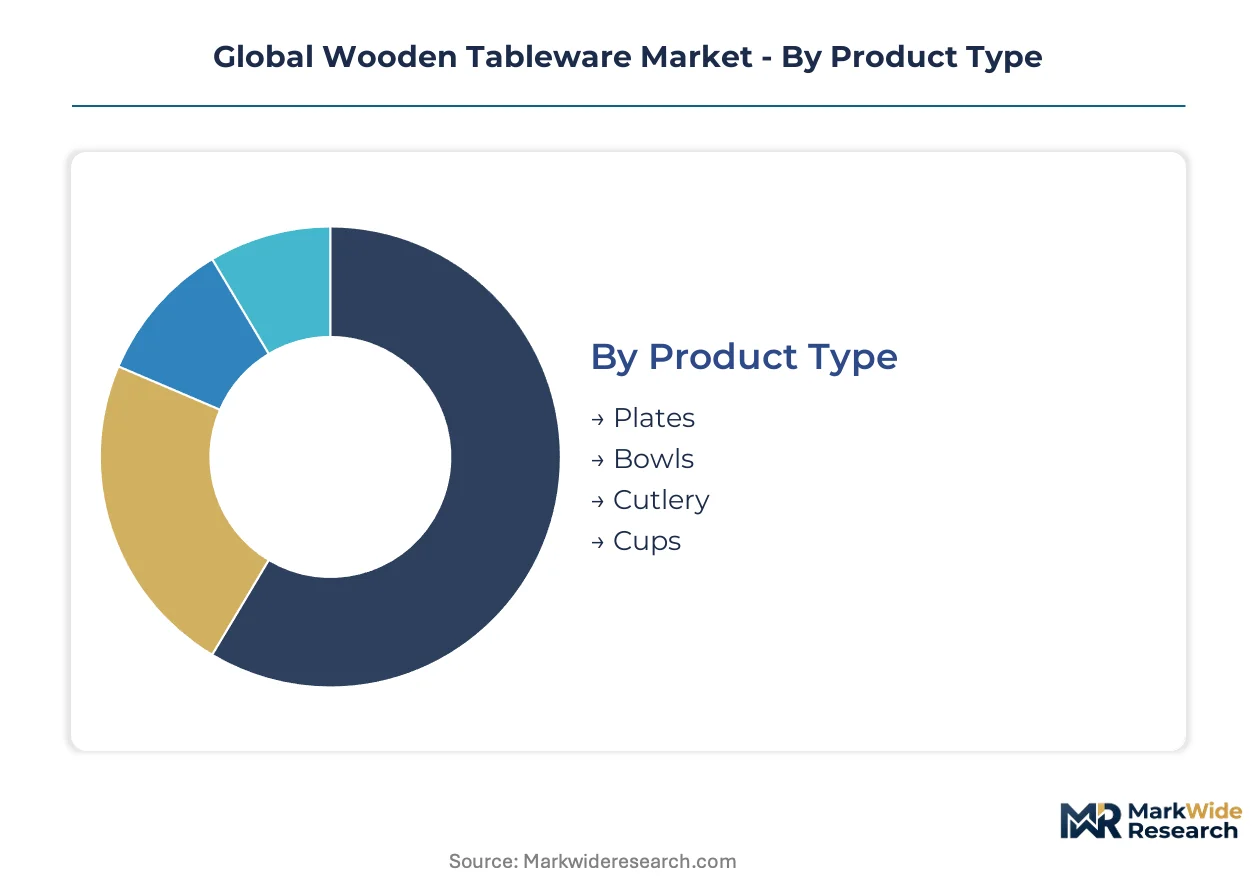
Segmentation in wooden tableware reveals how material sourcing constraints, certification requirements, and channel economics partition the market into distinct competitive arenas. Understanding these divisions exposes where procurement power concentrates and which specifications command premium positioning.
Product Type:
Rotary-cut veneer capacity clusters in Nordic and Baltic regions, concentrating supply for formed tableware while CNC machining networks serve precision-cutlery demand across dispersed manufacturing bases.
- Plates:Rotary-cut birch veneer forms the volume core through hot-pressing into shallow dish geometries. Quick-service chains in Germany and France specify FSC-certified grades for EU Green Deal compliance, absorbing Baltic mill capacity.
- Cutlery:Steam-compressed bamboo pulp delivers tensile strength rivaling conventional plastics through resin-free binding. Quick-service adoption in the Netherlands and California accelerates most rapidly where municipal plastic bans apply.
- Bowls:Deep-drawn birch or pine laminates serve soup and grain applications with moisture-resistant coatings. Institutional catering contracts in Japan drive specification tightening under revised METI thermal stability standards.
- Cups:Hardwood grain aesthetics command specialty retail premiums. Boutique hospitality in Paris and San Francisco sources figured maple and walnut for service presentation.
Plates absorb the bulk of installed capacity; cutlery is expanding most quickly.
End User:
Procurement authority fragments across buyer types with divergent specification priorities—households respond to retail shelf price while foodservice operators embed compostability certification into contract templates.
- Restaurants:Corporate sustainability officers mandate BPI or TÜV OK Compost certification before price negotiation. Chain operators in Vancouver and San Francisco specify wooden alternatives under municipal single-use plastic prohibitions.
- Cafés:Smaller format operations prioritize aesthetic differentiation through grain-visible hardwood serveware. Independent operators in Paris source through direct B2B platforms bypassing traditional distributors.
- Catering Services:Volume-driven contracts face substitution pressure from bagasse and agricultural residue alternatives. Institutional buyers in California embed compostability requirements into RFP templates.
- Households:Retail channel purchases respond to visible sustainability labeling and price positioning. Online retail penetration concentrates in tier-2 Indian cities ahead of local manufacturing scale.
Restaurants command specification-setting authority; cafés are gaining share fastest as boutique hospitality procurement decentralizes.
Material:
Forest certification traceability requirements and regional harvest economics stratify material sourcing into distinct supply chain configurations with divergent compliance burdens.
- Birch:Rotary-cut veneer production dominates volume output through Baltic and Nordic mill networks. Weather-driven harvest volatility exposes manufacturers to freight cost spikes and supply interruption.
- Bamboo:Steam-explosion fiber refinement yields higher tensile strength without chemical delignification. German and Dutch quick-service chains specify these grades for heavy-duty cutlery applications.
- Hardwood:Figured grain aesthetics support premium positioning in specialty retail and boutique hospitality. Maple and walnut command price realization multiples above commodity grades.
- Pine:Softwood laminates serve cost-sensitive institutional segments with adequate performance for dry applications. Nordic supply clusters align with EU Green Deal traceability mandates.
Birch absorbs the bulk of installed capacity; bamboo is climbing the fastest as tensile engineering closes the performance gap with petroleum alternatives.
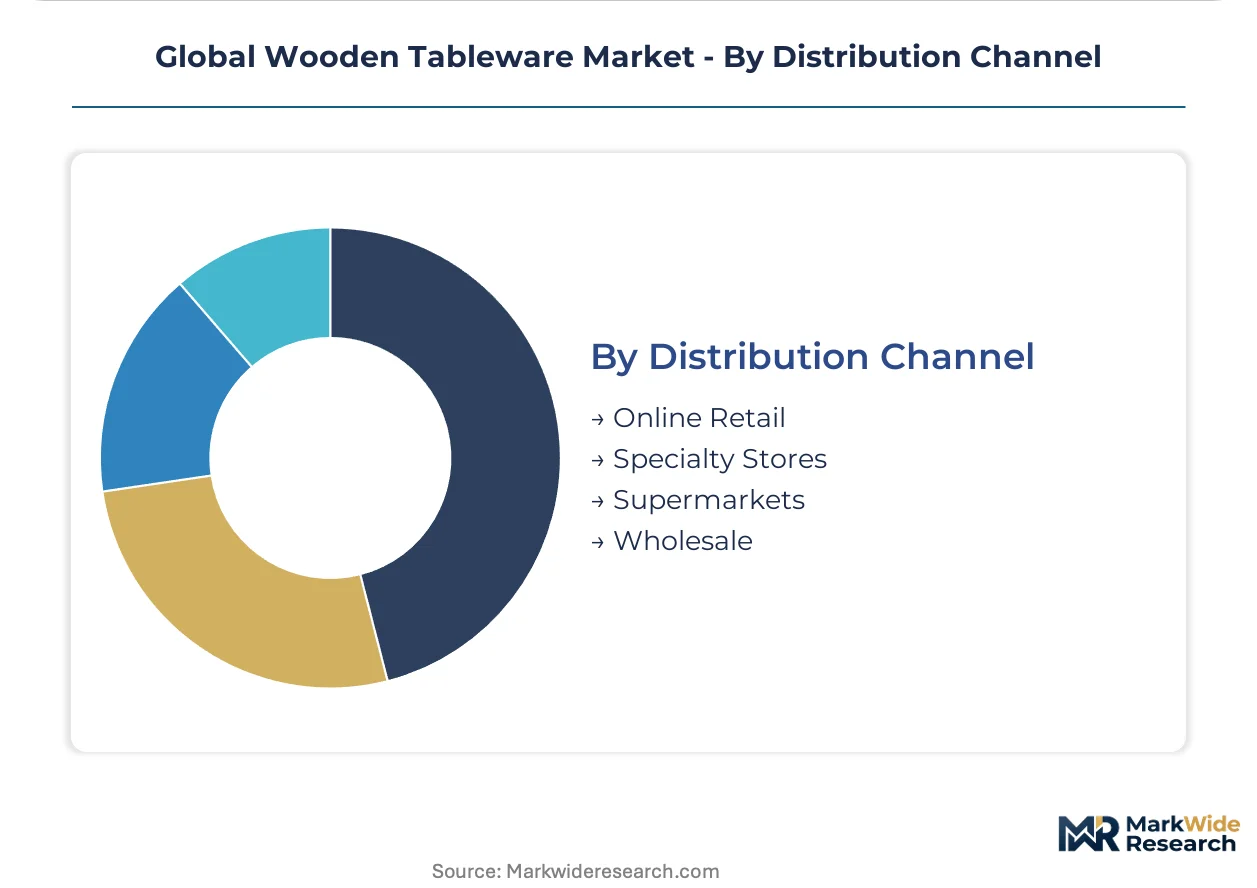
Distribution Channel:
Channel economics determine margin capture and specification control, with direct platforms compressing distributor markups while wholesale retains volume contract leverage.
- Wholesale:Traditional foodservice distributors retain institutional catering contract access. Multi-tier supply networks create FSC chain-of-custody data reconciliation burdens.
- Online Retail:Direct-to-hotel platforms reduce margin compression and capture boutique hospitality segments. Specialty birch and hardwood grades reach household buyers through sustainability-focused marketplaces.
- Supermarkets:Mass retail channels prioritize price positioning and visible certification labeling. Compostability badges influence shelf placement decisions.
- Specialty Stores:Curated assortment and staff consultation support premium hardwood positioning. Grain aesthetics and origin stories justify price multiples in urban centers.
Wholesale retains the bulk of foodservice volume; online retail is gaining share fastest as B2B procurement platforms consolidate buyer power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baltic and Nordic mills supply the bulk of rotary-cut birch veneer, while consumption concentrates in German quick-service chains and California's municipal ban zones. This production-consumption divide shapes freight economics and certification arbitrage across the value chain.
Germany
Quick-service chains specify FSC-certified birch plates under EU Green Deal procurement mandates. The country's national packaging regulator enforces extended producer responsibility rules that elevate compostable serviceware premiums. Hamburg and Berlin foodservice clusters absorb Baltic mill capacity through direct distributor relationships.
United States
California and Washington municipal plastic bans create localized demand spikes for bamboo cutlery alternatives. FDA coating migration limits govern surface treatment standards for wooden food-contact articles. San Francisco's boutique hospitality sector sources figured hardwood cups through direct B2B platforms bypassing traditional distributors.
Japan
Revised METI JIS S 2053 standards tighten thermal stability requirements for heat-resistant coatings in ramen service. Tokyo and Osaka institutional catering contracts drive specification upgrading for deep-drawn birch bowls. Vietnamese and Indonesian exporters face extended certification timelines under the revised framework.
France
Paris cafés prioritize aesthetic differentiation through grain-visible hardwood serveware for boutique hospitality positioning. The EU Single-Use Plastics Directive redirects corporate procurement toward certified biodegradable alternatives. Île-de-France foodservice management companies embed BPI compostability requirements into RFP templates.
India
Quick-service chain expansion in tier-2 cities creates first-mover potential for compostable cutlery suppliers. The country's food safety regulator enforces FSSAI packaging material standards for imported wooden goods. Bangalore and Hyderabad hospitality clusters source through sustainability-focused online retail platforms ahead of local manufacturing scale.
Global Wooden Tableware Market Competitive Environment
The competitive structure tilts toward diversified packaging conglomerates with molded fiber and wood-pulp manufacturing footprints. Tiered specialization separates FSC-certified volume suppliers from wheat bran composite technology holders and direct-distribution specialists. Consolidation pressure concentrates among Baltic birch processors facing weather-driven harvest volatility. Dominant competitive moves include backward integration into captive veneer supply and technology licensing for steam-explosion fiber refinement.
Within the diversified packaging tier, Huhtamaki and Georgia-Pacific occupy positions anchored by multi-material manufacturing scale. Eco-Products, Inc. exemplifies the direct-distribution archetype through North American institutional catering relationships. Biotrem represents patented composite technology differentiation extending beyond traditional birch offerings.
| Leading Market Players |
|---|
| Huhtamaki |
| Dart Container Corporation |
| Biotrem |
| Eco-Products, Inc. |
| Yash Pakka Limited |
| Georgia-Pacific |
| Pappco Greenware |
| Natural Tableware |
| DOpla SpA |
| Others |
Value Chain & Pricing Dynamics
Captive veneer supply in Estonia and Latvia anchors pricing power for Baltic mill operators, while outsourced bamboo pulp sourcing in Vietnam and Indonesia exposes cutlery specialists to freight cost volatility and margin compression. This integration divergence separates FSC-certified volume leaders from resin-free binding technology holders competing on performance premiums.
Pricing Analysis
Margin tightening in economy-tier pine laminates reflects bagasse substitution pressure from institutional catering buyers in California and France. Three-tier pricing structure across premium hardwood cups, standard birch plates, and economy pine bowls tracks certification grade and grain aesthetics. Cost-down pressure on bamboo cutlery accelerates because steam-explosion fiber refinement capacity expansion lags Dutch and German quick-service specification upgrades. Quick-service chains exhibit highest price sensitivity; boutique hospitality in Paris and San Francisco shows lowest.
Supply Chain Analysis
Single-source vulnerability sits with rotary-cut birch veneer production clustering in Estonia, Latvia, and Finland. Raw material dependencies center on Nordic forest harvest cycles, FSC chain-of-custody documentation systems, and heat-resistant coating formulations for Japan METI compliance. Tariff exposure looms for Vietnamese bamboo pulp exporters facing extended JIS S 2053 certification timelines. Distribution runs through traditional foodservice wholesalers retaining institutional contract access, though direct-to-hotel B2B platforms compress markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Wooden Tableware Market sits in a materials-transition phase where steam-explosion fiber refinement displaces conventional chemical delignification, reshaping competitive positioning around tensile performance and compostability certification speed.
For Market Incumbents: Anticipate molded fiber substitution threats by securing captive birch veneer supply in Baltic mill networks and accelerating TÜV OK Compost validation for resin-free bamboo binding formulations. Backward integration into forest certification management systems defends contract eligibility as EU CSRD disclosure requirements harden procurement gate criteria. For New Entrants and Emerging Players: Launch via sustainability-focused online retail platforms targeting tier-2 Indian city hospitality clusters ahead of local manufacturing scale. India's quick-service expansion in Bangalore and Hyderabad presents the most penetrable white space; lead with FSSAI-compliant compostable cutlery positioned for municipal plastic ban preemption. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified packaging conglomerates seeking FSC-certified volume capacity and patented composite technology holdings. Long-term viability favors suppliers with integrated chain-of-custody systems and steam-explosion processing assets. Watch German quick-service chain specification upgrades as the inflection signal for tensile-grade bamboo pulp demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Veneer Supply | Baltic mill ownership secures FSC-certified volume against weather-driven harvest volatility. |
| Steam-Explosion Fiber Refinement Licensing | Technology transfer accelerates resin-free bamboo cutlery performance parity with petroleum plastics. |
| Direct-to-Hotel B2B Platform Launch | Bypassing wholesale distributors captures margin in Paris and San Francisco boutique hospitality. |
| TÜV OK Compost Certification Investment | Pre-certification reverses procurement sequences and concentrates contract eligibility among qualified suppliers. |
| India Tier-2 City Distribution Partnership | First-mover positioning ahead of local manufacturing scale captures quick-service chain expansion. |
Study Parameters
Multi-period observation of municipal plastic ban implementation, FSC certification adoption curves, and quick-service chain specification upgrades anchored the trend analysis, supplemented by interviews with Baltic mill operations managers, EU foodservice procurement directors, Japanese institutional catering contractors, and Indian quick-service supply chain heads. Secondary validation drew from EU ECHA REACH filings, FDA indirect food additive guidance, Japan METI JIS standard revisions, and customs trade data for birch veneer and bamboo pulp movements. Bottom-up segment sizing triangulated against top-down macro demand modeling.
Input-output matrices mapped rotary-cut veneer capacity, steam-explosion processing throughput, and compostability certification velocity against foodservice contract award flows across the projection horizon. Segmentation dimensions spanned product type, material sourcing configuration, end-user procurement authority, and distribution channel control. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal compliance deadlines and municipal ban phase-in schedules. Forecast inputs included Baltic harvest yield variability and coating reformulation timelines for revised METI thermal stability thresholds.
The model assumes a particular technology adoption path; alternative pathways for resin-free binding chemistry or agricultural residue composite breakthroughs would alter the outlook. Forecasts reflect assumptions regarding EU Single-Use Plastics Directive enforcement consistency, FSC chain-of-custody system interoperability, and quick-service chain specification upgrade cadence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Accent Tables Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
US Tableware Market