
 United States Bed and Bath Linen Market | 2026-2036
United States Bed and Bath Linen Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bed and Bath Linen Market Analytics
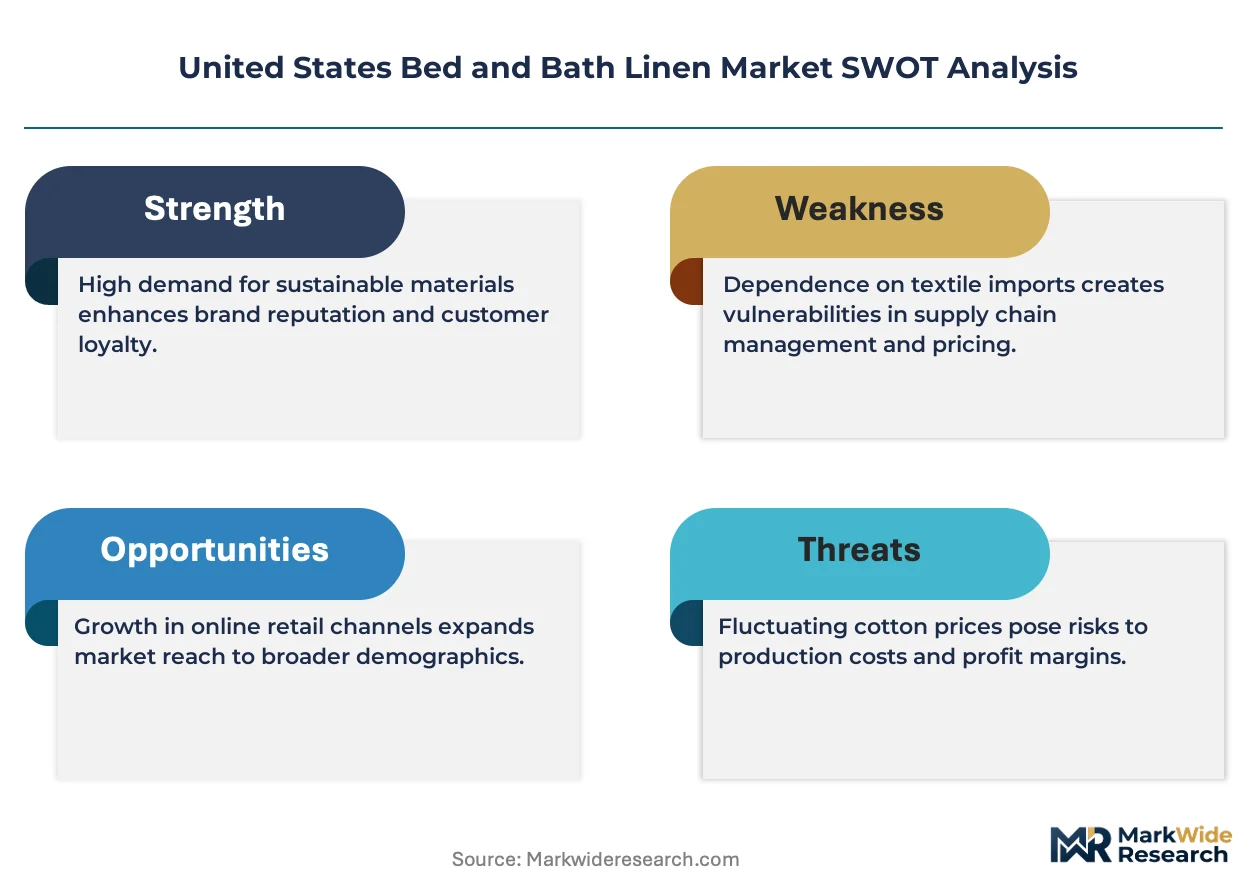
Domestic textile mills in Georgia and the Carolinas is realigning output toward performance-grade cotton sheeting after years of offshore migration. Tempur Sealy International Inc. leverages its mattress ecosystem to bundle coordinated linen sets through retail partners. Welspun Group anchors North American supply with integrated spinning and finishing operations in Georgia. Ralph Lauren Corp. differentiates through licensed home collections that command premium positioning in department store channels.
United States bed and bath linen encompasses woven and knitted textile goods designed for sleep surfaces and hygiene routines, typically constructed from cotton percales, sateen weaves, or terry-loop pile with thread counts ranging from 200 to 800 for residential grades. These products serve dual commercial and consumer purposes: hotels require industrial-launderable constructions with reinforced hems, while households prioritize tactile softness and aesthetic coordination. Cotton bed sheets occupy the largest revenue pool given replacement frequency and premiumization potential, though bamboo-derived viscose represents the fastest-expanding material segment as moisture-wicking properties attract wellness-oriented buyers. The hospital end-user segment sustains above-average contract values through anti-microbial finishing requirements and bulk procurement protocols.
The Federal Trade Commission enforces fiber content labeling under the Textile Fiber Products Identification Act, compelling accurate disclosure of cotton, linen, and synthetic blends. The Consumer Product Safety Commission monitors flammability standards for children's sleepwear and bedding accessories, affecting comforter construction methods. State-level regulations in California under Proposition 65 require warning labels for formaldehyde traces in wrinkle-resistant finishes, pushing manufacturers toward alternative cross-linking chemistries. Stakeholders must monitor evolving chemical disclosure mandates and the pace of recycled fiber integration as procurement criteria tighten across institutional buyers.
Market Dynamics
Hospitality procurement teams are compressing linen refresh cycles while residential buyers extend replacement intervals, creating divergent demand pulses across the United States bed and bath linen market. The FTC's Textile Fiber Products Identification Act enforcement tightens as bamboo-derived viscose claims proliferate, forcing mills to revalidate fiber content documentation.
Growth Catalysts
- Sun Belt Migration:Population inflows into Texas, Florida, and Arizona accelerate new hotel construction and residential turnover, expanding replacement demand for sheeting and terry products beyond national averages.
- Textile Fiber Products Identification Act:FTC labeling mandates create compliance barriers that favor domestic mills with integrated testing labs, concentrating contract awards toward Georgia and Carolina-based suppliers.
- Anti-Microbial Finishing:Hospital and extended-stay hospitality segments specify silver-ion or chitosan treatments, opening premium price tiers for technical textile converters with in-house finishing capacity.
Market Restraints
- Cotton Price Volatility:New York futures contract swings and drought conditions in Texas High Plains compress margin predictability for spinners without forward contracting discipline.
- Asian Supply Concentration:Pakistan and India retain dominant positions in open-end cotton yarn, exposing United States weavers to freight rate spikes and letter-of-credit friction.
- Formaldehyde Disclosure:California Proposition 65 warning requirements for wrinkle-resistant chemistries limit retail placement options for mills relying on traditional DMDHEU cross-linking systems.
Strategic Opportunities
- Recycled Fiber Integration:Post-consumer cotton recovery and textile-to-textile recycling infrastructure creates feedstock arbitrage for mills with mechanical shredding and fiber reconstitution capabilities.
- Extended-Stay Hospitality:Apartment-style hotel formats with in-unit laundry demand higher thread-count residential-grade sheeting rather than institutional constructions, opening margin expansion for premium-positioned suppliers.
- State-Level Green Procurement:New York and Massachusetts state purchasing guidelines increasingly specify recycled content thresholds, creating preferential access for certified suppliers in institutional bid processes.
Industry Challenges
- Dyehouse Wastewater Compliance:EPA pretreatment standards for color and chemical oxygen demand force capital-intensive effluent system upgrades at finishing facilities, particularly impacting smaller converters in the Carolinas.
- SKU Proliferation Complexity:Retail channel demands for seasonal color palettes and size variations strain loom scheduling efficiency, requiring advanced demand-forecasting software investments that mid-tier mills struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bed and Bath Linen Market |
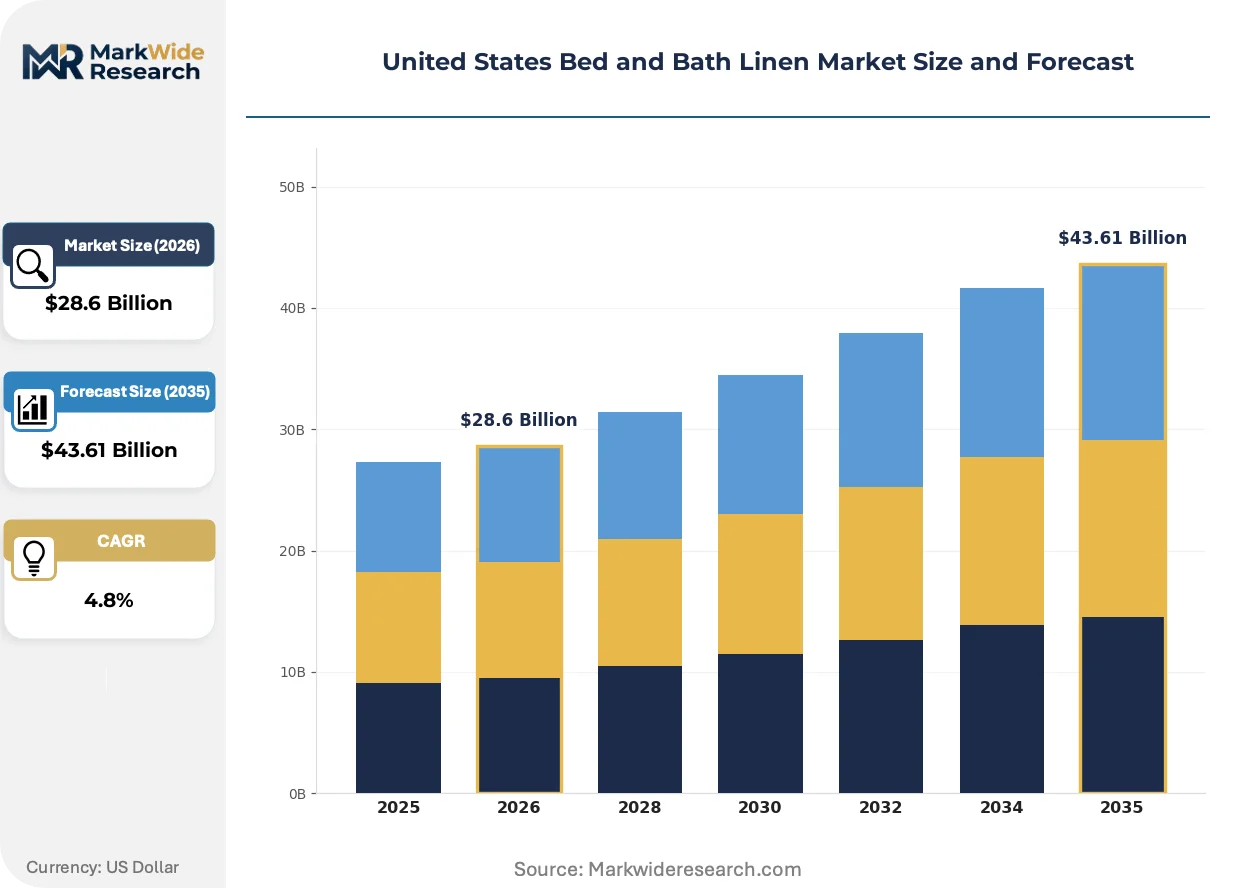
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Sheets, Pillowcases, Comforters, Towels Material: Cotton, Linen, Polyester, Bamboo End User: Households, Hotels, Hospitals, Spas Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Serta Simmons Bedding LLC, Welspun Group, Tempur Sealy International Inc., Sleep Number Corp., Brooklinen, Ralph Lauren Corp., Crane and Canopy Inc., Dunelm Group plc, Williams Sonoma Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bed and Bath Linen Market Evolving Landscape
Bamboo-derived viscose is absorbing market attention as wellness-positioned retailers reclassify bedding as a health category. Three concurrent developments are restructuring competitive advantage: material science advances, regulatory disclosure tightening, and procurement model bifurcation between institutional and residential channels.
Lyocell production from sustainably harvested eucalyptus pulp is absorbing capital allocation from conventional viscose lines as closed-loop solvent recovery reduces water intensity. Boutique hotel chains in California and Colorado specify Tencel blends for moisture-management claims, compressing adoption timelines that previously spanned decades into single contract cycles.
The FTC's Textile Fiber Products Identification Act enforcement is absorbing staff resources as bamboo labeling investigations multiply. Domestic mills with in-house spectroscopy testing are capturing contract renewals from retailers seeking liability insulation, while importers face detention rates at ports of entry for fiber content discrepancies.
Direct-to-consumer subscription models for sheet replacement are absorbing growth that department store channels previously captured. Millennial household formation in Austin, Nashville, and Raleigh drives visibility for digitally native brands, compressing traditional wholesale markups and forcing legacy suppliers to build captive e-commerce fulfillment infrastructure.
United States Bed and Bath Linen Market Segmentation
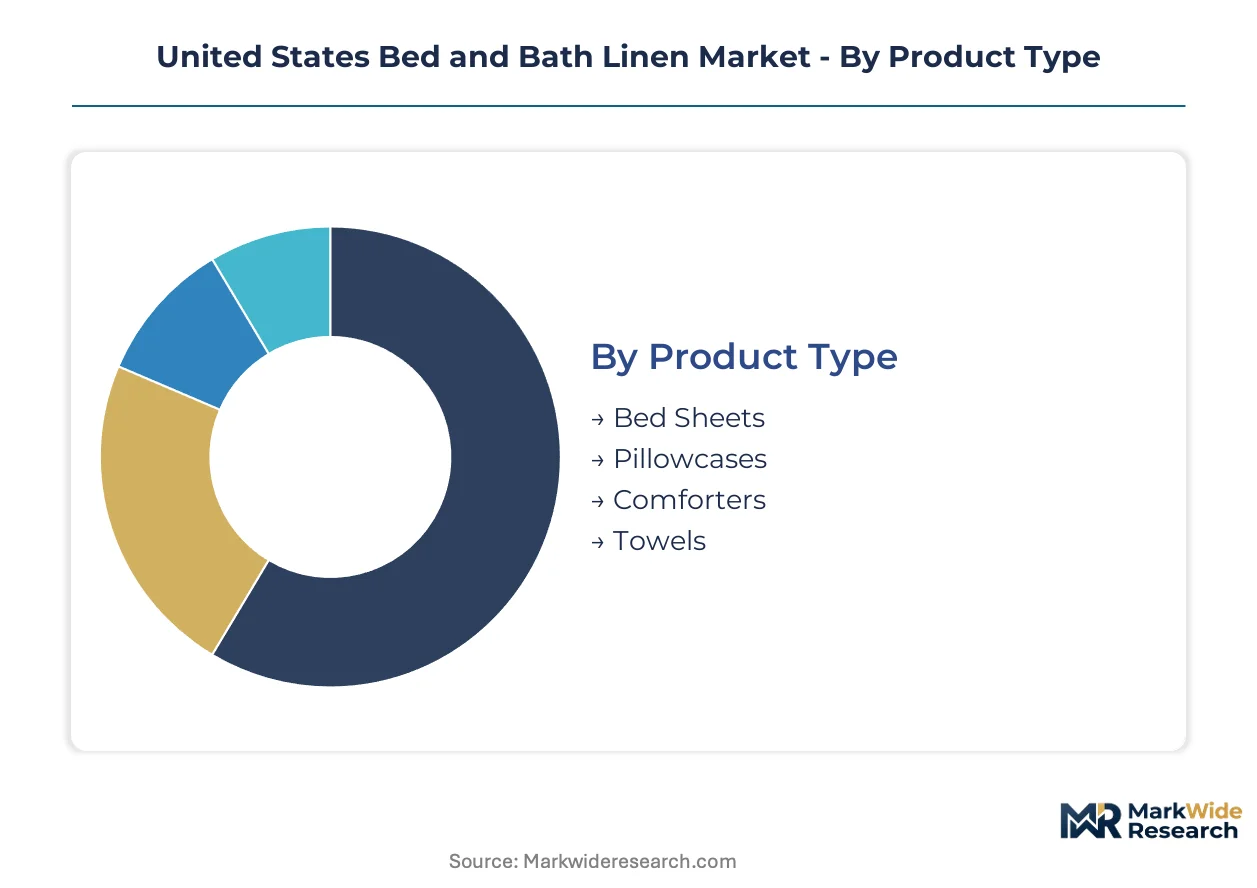
Segmentation in the United States bed and bath linen market reveals divergent procurement logics across residential and institutional buyers. Cotton sheeting commands the largest revenue pool through replacement frequency, while anti-microbial specifications in healthcare and hospitality create premium tiers inaccessible to commodity suppliers.
Product Type:
Replacement cycles and laundering durability drive purchasing decisions across sleep and hygiene categories.
- Bed Sheets:Woven constructions from percale or sateen weaves with thread counts between 200 and 800 dominate residential spend. Sun Belt household formation in Texas and Florida accelerates refresh demand as new homeowners establish linen inventories.
- Towels:Terry-loop pile constructions with GSM ratings from 400 to 700 absorb institutional procurement volume. Extended-stay hospitality properties in Arizona and Nevada specify higher-weight constructions for in-unit laundry compatibility.
- Pillowcases:Envelope or hemmed closures in standard and king dimensions follow sheet purchasing patterns.
- Comforters:Down-alternative or cotton-filled batting with baffle-box construction serves seasonal temperature regulation needs.
Volume sits with bed sheets; growth tilts toward towels as hospitality construction outpaces residential turnover.
Material:
Fiber selection determines laundering performance, tactile positioning, and regulatory compliance burden.
- Cotton:Upland and Pima varieties processed through ring-spinning or open-end systems supply the baseline for institutional and residential markets. Georgia and Carolina mills with integrated ginning operations capture contract awards from retailers seeking FTC compliance insulation.
- Bamboo:Viscose derived from bamboo pulp undergoes chemical processing that triggers heightened FTC Textile Fiber Products Identification Act scrutiny. Wellness-oriented retailers in California and Colorado reclassify bedding as a health category to justify moisture-wicking claims.
- Linen:Flax fiber from European or domestic sources commands artisanal positioning in boutique hospitality.
- Polyester:Microfiber constructions offer wrinkle resistance and cost compression for budget hospitality procurement.
Procurement weight rests with cotton; expansion concentrates in bamboo as fiber disclosure enforcement reshapes competitive access.
End User:
Application environment dictates construction specifications, finishing requirements, and contract value structures.
- Hotels:Industrial-launderable sheeting with reinforced hems and colorfast dyes sustains above-average contract values through bulk replacement protocols. Boutique and extended-stay formats in the Sun Belt compress refresh cycles to match guest expectation elevation.
- Hospitals:Anti-microbial finishing with silver-ion or chitosan treatments creates technical barriers to entry for commodity converters. EPA pretreatment compliance for dyehouse effluent concentrates contract awards toward larger finishing facilities.
- Households:Tactile softness and aesthetic coordination drive replacement decisions with extended intervals between purchases.
- Spas:Premium terry and robe specifications serve experiential positioning in wellness tourism destinations.
Contract value concentrates in hotels; technical specification expansion favors hospitals as infection control protocols tighten.
Distribution Channel:
Channel selection determines margin structure, SKU complexity burden, and customer data access.
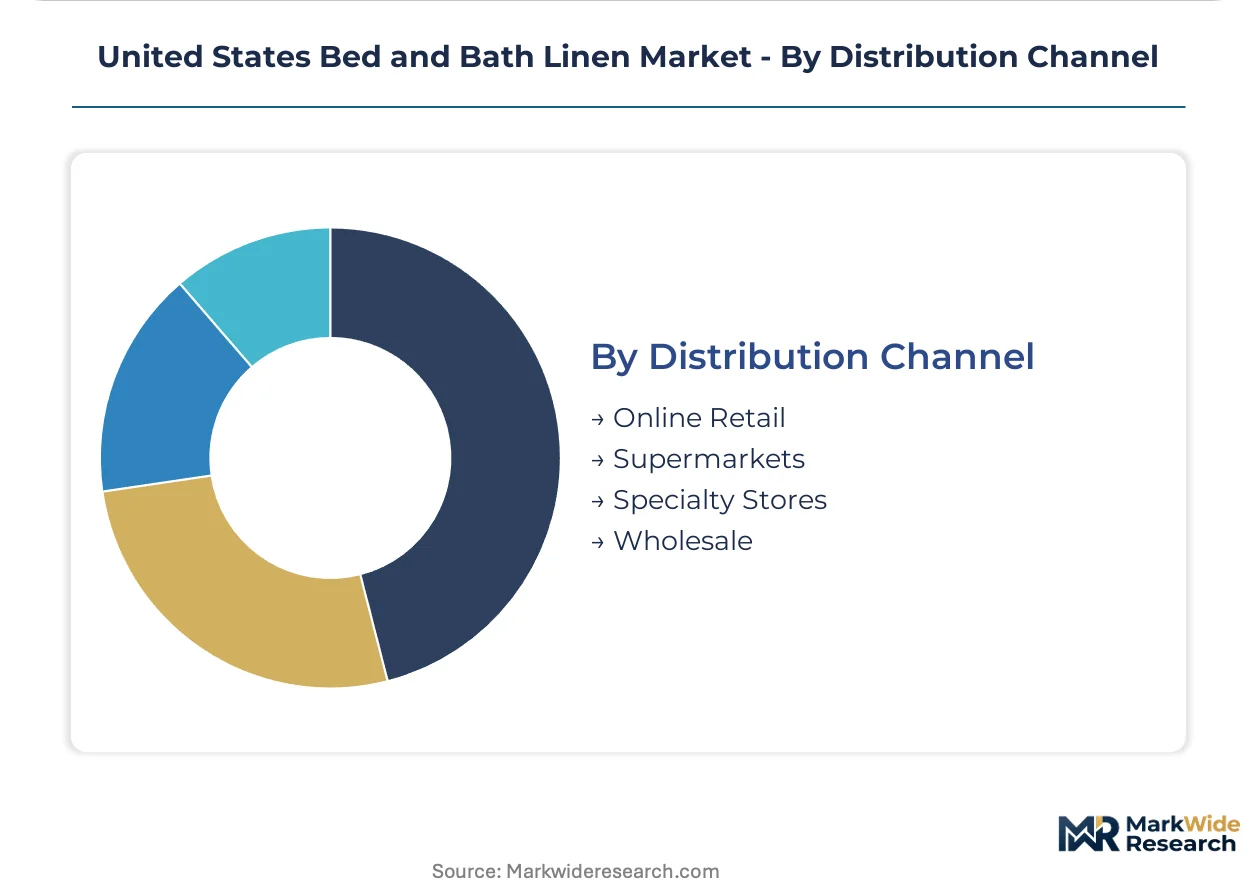
- Online Retail:Direct-to-consumer subscription models for sheet replacement compress traditional wholesale markups. Millennial household formation in Austin, Nashville, and Raleigh drives visibility for digitally native brands with captive fulfillment infrastructure.
- Wholesale:Institutional procurement through hospitality supply aggregators sustains volume concentration for domestic mills with Georgia and Carolina production bases.
- Supermarkets:Mass-market cotton sheeting serves emergency replacement and value-conscious residential demand.
- Specialty Stores:Department store licensed collections command premium positioning through brand association.
Revenue generation tilts toward online retail; contract stability remains with wholesale as hospitality procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cotton cultivation in the Texas High Plains anchors domestic fiber sourcing for United States bed and bath linen production. Georgia and the Carolinas concentrate spinning, weaving, and finishing infrastructure that supplies institutional and retail channels nationwide.
Sun Belt States
Population migration into Texas, Florida, and Arizona accelerates hotel construction and residential turnover, expanding replacement demand for sheeting and terry products. The FTC's Textile Fiber Products Identification Act enforcement tightens labeling compliance for bamboo-derived viscose claims. Georgia-based mills with integrated testing laboratories capture contract renewals from retailers seeking liability insulation.
Southeast
North Carolina and South Carolina host legacy textile finishing facilities serving hospitality procurement with industrial-launderable constructions. EPA pretreatment standards for dyehouse effluent force capital-intensive wastewater system upgrades. Charlotte-area converters specialize in anti-microbial treatments for hospital and extended-stay segments.
Pacific Coast
California's Proposition 65 mandates warning labels for formaldehyde traces in wrinkle-resistant finishes, pushing manufacturers toward alternative cross-linking chemistries. Boutique hotel chains in Los Angeles and San Francisco specify Tencel blends for moisture-management positioning. West Coast wellness retailers reclassify bedding as a health category to justify premium pricing.
Northeast Corridor
New York and Massachusetts state purchasing guidelines specify recycled content thresholds for institutional procurement, creating preferential access for certified suppliers. Millennial household formation in Boston and Philadelphia metro areas drives direct-to-consumer subscription models for sheet replacement. Mid-Atlantic distribution hubs serve compressed delivery timelines for hospitality refresh cycles.
Mountain West
Colorado and Nevada extended-stay properties demand higher thread-count residential-grade sheeting rather than institutional constructions. Denver-based digitally native brands build captive e-commerce fulfillment infrastructure to bypass traditional wholesale markups. Regional population growth in Austin, Nashville, and Raleigh spillover markets expands addressable household formation.
United States Bed and Bath Linen Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channels and wellness-positioned materials. The vendor base stratifies across integrated domestic mills, specialty retailers with licensed collections, and digitally native brands with subscription fulfillment infrastructure. Three archetypes dominate: vertically integrated textile manufacturers with captive spinning capacity, premium lifestyle licensors leveraging brand equity, and technology-enabled direct brands compressing wholesale markups. Competitive intensity centers on fiber content compliance documentation and recycled feedstock integration capabilities.
Among domestic integrated producers, Welspun Group anchors North American supply with Georgia-based spinning and finishing operations. Tempur Sealy International Inc. leverages its mattress ecosystem to bundle coordinated linen sets through retail partners. Ralph Lauren Corp. occupies licensed home collections positioning that commands premium placement in department store channels. These three exemplify distinct strategic vectors: manufacturing scale, cross-category bundling, and brand-licensed premiumization.
| Leading Market Players |
|---|
| Serta Simmons Bedding LLC |
| Welspun Group |
| Tempur Sealy International Inc. |
| Sleep Number Corp. |
| Brooklinen |
| Ralph Lauren Corp. |
| Crane and Canopy Inc. |
| Dunelm Group plc |
| Williams Sonoma Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up hospitality linen specialists concentrate contract negotiation leverage through pooled procurement volumes, compressing margin buffers for Georgia and Carolina mills while reinforcing pricing discipline across institutional tiers. This ownership consolidation reshapes both upstream cotton contracting behavior and downstream subscription-model pricing experiments in direct-to-consumer channels.
Pricing Analysis
Warranty and refresh-cycle bundling separates hospitality procurement contracts from unbundled residential transactions, with institutional buyers negotiating inclusive industrial-laundering service tiers. Three-tier pricing structure across premium, standard, and economy levels tracks thread-count thresholds and anti-microbial finishing specifications. Pricing pressure stems from Asian yarn import competition eroding open-end cotton spinning margins in the Carolinas. Budget hospitality chains exhibit acute price sensitivity, while boutique extended-stay properties absorb premium positioning for residential-grade constructions.
Supply Chain Analysis
Domestic-content mandates in New York and Massachusetts state procurement guidelines are reshaping sourcing patterns toward certified recycled-fiber suppliers with Georgia-based mechanical shredding capabilities. Raw cotton feedstock draws from Texas High Plains cultivation and imported Pakistani open-end yarn, with lyocell pulp sourcing from sustainably harvested eucalyptus plantations. Single-source vulnerability concentrates in Asian viscose fiber supply for bamboo-derived claims facing heightened FTC enforcement. Distribution runs through hospitality supply aggregators anchoring contract stability, while digitally native brands build captive e-commerce fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic finishing capacity constraints in the Carolinas prop pricing power for EPA-compliant dyehouses, sustaining margin premiums as institutional procurement tightens chemical disclosure requirements.
For Market Incumbents: Anticipate accelerated FTC fiber-content enforcement by investing in captive spectroscopy testing laboratories at Georgia spinning facilities, insulating contract renewals from port detention risks. Consolidate backward integration into Texas cotton ginning operations to buffer New York futures volatility. Prioritize anti-microbial finishing certifications for hospital segment retention against emerging technical textile converters. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel wedge, with millennial household formation in Austin and Nashville driving visibility for digitally native brands bypassing wholesale markups. Target extended-stay hospitality in Colorado and Nevada with residential-grade thread-count positioning. Lead with wellness-category reclassification and moisture-wicking material claims to justify premium pricing. For Investors and Strategic Acquirers: Georgia-based mills securing state-level green procurement certifications is the leading indicator that recycled-fiber integration capabilities will concentrate contract awards. Long-term viability favors integrated producers with mechanical shredding and fiber reconstitution infrastructure over commodity converters. Watch for EPA pretreatment compliance upgrades at Carolina dyehouses as inflection signal for consolidation-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Fiber Integration | Post-consumer cotton recovery infrastructure captures New York and Massachusetts state procurement preference. |
| Anti-Microbial Finishing Capacity | Silver-ion and chitosan treatment capabilities open hospital and extended-stay hospitality premium tiers. |
| Direct-to-Consumer Subscription Launch | Captive e-commerce fulfillment bypasses wholesale markups in millennial household formation markets. |
| FTC Compliance Laboratory Investment | In-house spectroscopy testing insulates contract renewals from fiber-content detention at ports. |
| Extended-Stay Hospitality Positioning | Residential-grade sheeting specifications match apartment-format hotel in-unit laundry compatibility. |
Research Methodology
Independent corroboration across hospitality procurement directors, textile mill operations managers, and state purchasing officers underwrites the qualitative findings presented in this study. Primary fieldwork engaged spinning facility engineers, dyehouse compliance officers, and retail category buyers. Secondary validation drew from FTC enforcement records, EPA pretreatment standard filings, and cotton futures exchange data. Bottom-up demand modeling across end-user segments triangulates against top-down supply-side capacity assessments.
Comparable historical reference periods anchored the projection framework to observed replacement cycle compression in hospitality and interval extension in residential channels. The analysis window spans product type, material composition, end-user application, and distribution channel dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporate Sun Belt migration patterns, hotel construction permits, and recycled fiber adoption curves.
Caveats apply where cotton price volatility, Asian supply disruption, or accelerated chemical disclosure mandates could materially shift the outlook. Forecasts reflect documented assumptions about institutional procurement centralization and wellness-category retail repositioning. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles and Linens
Duvets Market
Textiles and Linens
Bed Sheets Market
Textiles and Linens
Global Textiles Home Decor Market
Textiles and Linens
Organic Bedding Market
Textiles and Linens
US & Europe Bed Linen and Curtains Market
Textiles and Linens
Table Linen Market
Textiles and Linens
Organic Bed Linen Market
Textiles and Linens
Asia-Pacific Bed and Bath Linen Market
Textiles and Linens
Bed Linen Market
Textiles and Linens
Global High Temperature Curtains Market
Textiles and Linens
Europe Bed and Bath Linen Market
Textiles and Linens
Bed and Bath Linen Market
Textiles and Linens
Kitchen Linens Market
Textiles and Linens
Bedroom Linen Market
Textiles and Linens
India Bed and Bath Linen Market
Textiles and Linens
United Kingdom Bed and Bath Linen Market