
 United States Kitchen Furniture Market | 2026-2036
United States Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Kitchen Furniture Market Analytics
Modular manufacturing systems is narrowing the cost gap between custom and stock kitchen cabinets across domestic production lines. Wood-Mode leverages its Pennsylvania manufacturing base to sustain long lead-time custom orders. Fortune Brands Home & Security anchors mass-market distribution through big-box retail partnerships. Omega Cabinetry differentiates through frameless construction technology aimed at contemporary residential specifications.
United States kitchen furniture encompasses fixed and movable storage, preparation, and dining fixtures engineered from engineered wood substrates, solid hardwoods, steel framing, and synthetic surfaces, with primary commercial purpose centered on optimizing residential food preparation workflows and property resale value. Cabinets dominate product type revenue due to their structural role in kitchen fit-outs and replacement cycle frequency. Wood material grades command margin concentration in the semi-custom tier, while metal and glass accents gain share within modern and contemporary style segments targeting urban condominium markets.
EPA formaldehyde emission standards under TSCA Title VI shape panel substrate compliance costs for domestic cabinet manufacturers. California Air Resources Board ATCM requirements extend binding precedent for low-emitting composite wood products sold into the nation's largest state economy. USDA BioPreferred program labeling influences federal procurement and hospitality sector purchasing criteria. Stakeholders must monitor evolving state-level PFAS restrictions on surface treatments and the pace of HUD-adopted green building specifications that could redirect multifamily developer procurement toward certified product tiers.
Market Dynamics
Modular manufacturing systems are compressing lead times for semi-custom cabinetry while EPA formaldehyde standards under TSCA Title VI restructure panel sourcing economics across domestic production networks.
Growth Catalysts
- California Title 24 energy codes:Binding efficiency mandates for residential construction are accelerating demand for low-emission finishes and certified wood substrates in the nation's largest state economy.
- Single-family residential builders:Renovation-driven cabinet replacement cycles are expanding order volumes for premium and semi-custom product tiers in suburban markets.
- Southeast housing starts:Texas and Florida absorption rates are concentrating demand for frameless and contemporary cabinet specifications in high-growth metropolitan corridors.
Market Restraints
- Hardwood lumber input volatility:Domestic sawmill capacity constraints and Canadian softwood tariff exposure are compressing margins for solid wood product lines.
- CARB ATCM compliance layering:California's precedent-setting emission rules create duplicative testing burdens for manufacturers selling across state lines.
- Stock cabinet substitution:Big-box retail distribution networks are capturing price-sensitive renovation demand with accelerated delivery timelines.
Strategic Opportunities
- USDA BioPreferred federal procurement:Labeling requirements for government and hospitality sector contracts are creating certified product tier premiums.
- Urban condominium frameless adoption:Contemporary aesthetic specifications in dense metropolitan markets favor European-style construction methods.
- PFAS restriction anticipation:State-level surface treatment bans are positioning early-compliant manufacturers for specification preference in multifamily developer procurement.
Industry Challenges
- CAD-to-CNC programming talent scarcity:Modular production lines require specialized technicians to bridge design software with automated cutting operations.
- HUD green specification integration:Evolving multifamily housing criteria demand recertification of existing product lines for affordable housing project eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Kitchen Furniture Market |
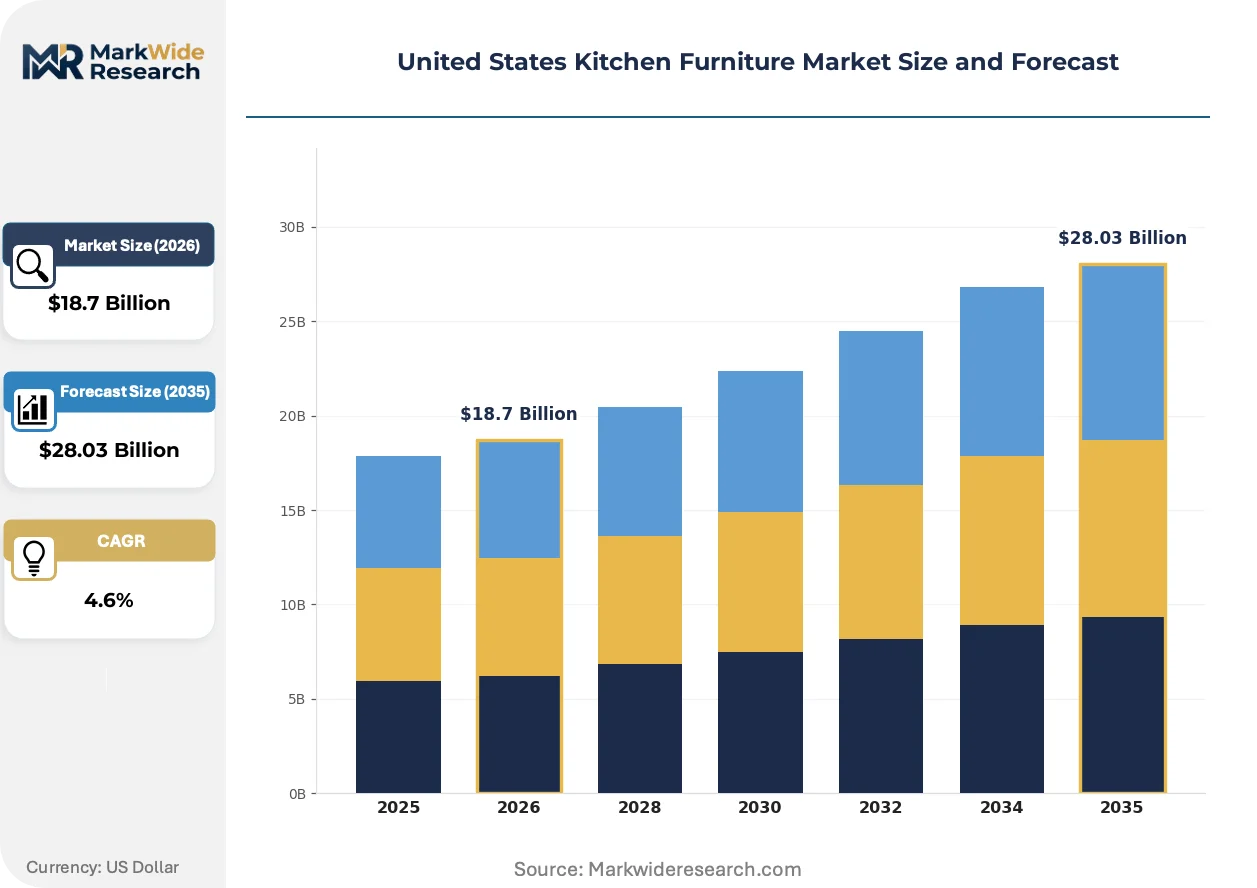
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Tables, Chairs Material: Wood, Metal, Glass, Plastic Style: Modern, Traditional, Rustic, Contemporary End User: Residential, Commercial, Hospitality, Institutions |
| Companies Covered | Wood-Mode, Omega Cabinetry, Fortune Brands Home & Security, Thomasville Cabinetry, Starmark Cabinetry, American Woodmark Corp, Diamond Cabinets, Plain & Fancy Cabinetry, KraftMaid Cabinets, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Kitchen Furniture Market Evolving Landscape
Digital fabrication and material science advances are reconfiguring how kitchen furniture is specified, produced, and certified across residential construction value chains.
Thermally fused laminate surfaces are hybridizing with high-pressure decorative overlays to deliver scratch-resistant aesthetics at engineered wood price points. Production-scale cabinet manufacturers in the Southeast are adopting these hybrid substrates for volume semi-custom lines. The technology is hybridizing traditional laminate economics with solid surface performance expectations in mid-market renovation specifications.
EPA formaldehyde emission standards under TSCA Title VI are mandating third-party certification for composite wood panel substrates used in domestic cabinet manufacturing. Compliance costs are restructuring supplier relationships toward certified particleboard and medium-density fiberboard sources. Semi-custom manufacturers serving California and Northeast markets are absorbing the highest certification burden while stock producers leverage exempt product categories.
Builder-direct specification channels are consolidating procurement authority for new construction cabinet packages away from traditional distributor networks. National production homebuilders are centralizing material selection through captive purchasing agreements with certified manufacturers. This channel compression is most visible in Texas and Florida metropolitan markets where housing start volumes support dedicated supply contracts.
United States Kitchen Furniture Market Segmentation
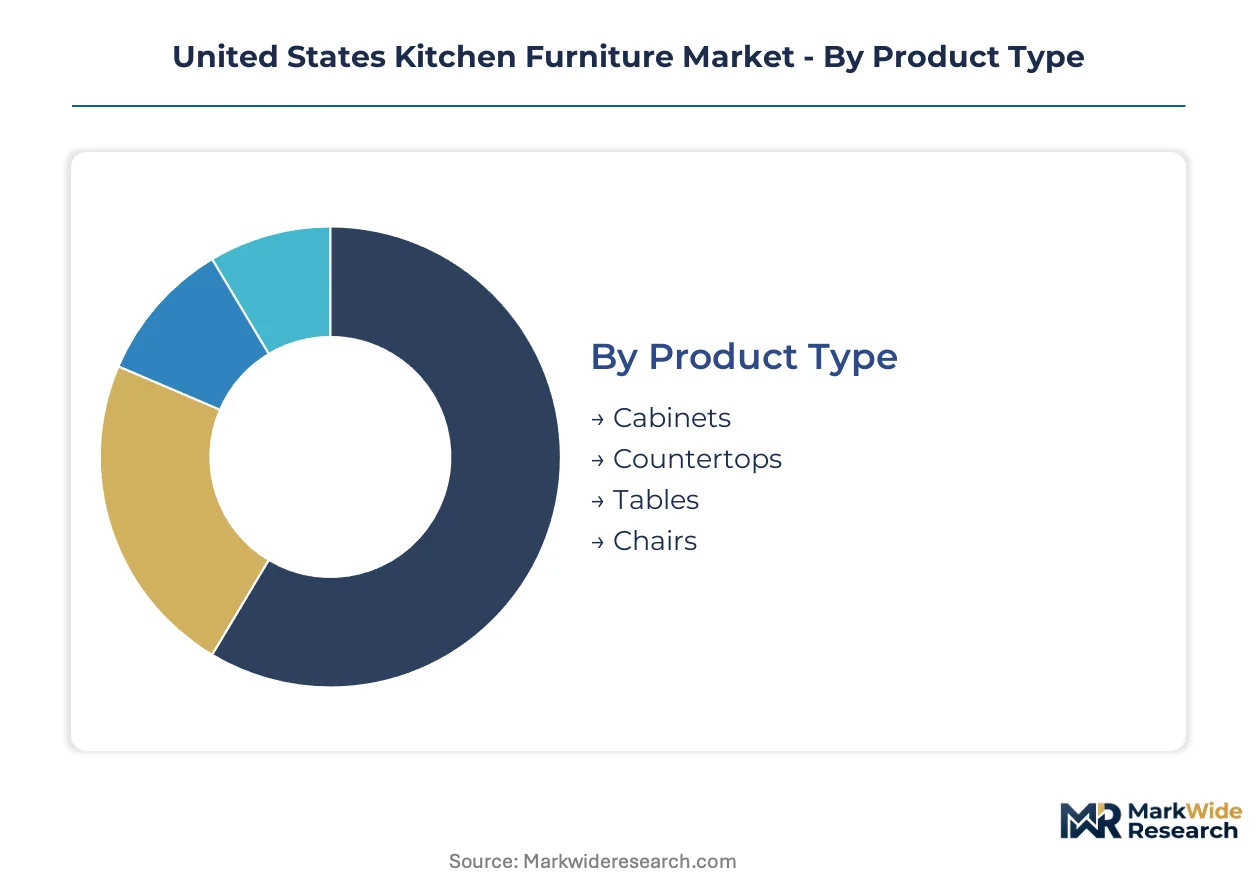
Cabinet replacement cycles and material specification trends create distinct revenue profiles across kitchen furniture segments. Understanding how product type, material grade, and end-use channel interact clarifies where procurement authority concentrates and where margin compression risks emerge.
Product Type:
Cabinets compress replacement timelines to 10-15 years for stock products and 20-25 years for custom installations, while freestanding furniture extends toward 30-year cycles. This turnover differential shapes inventory strategies and service attachment rates.
- Cabinets:Engineered wood and solid hardwood enclosures anchor kitchen fit-outs with the highest per-project expenditure and most frequent replacement demand. Residential renovation activity in Texas and Florida metropolitan corridors drives premium and semi-custom order expansion.
- Countertops:Laminate, quartz, and natural stone surfaces carry 15-20 year functional lifespans with aesthetic-driven earlier replacement. Builder-direct specification channels in new construction are consolidating procurement authority for countertop packages away from traditional distributor networks.
- Tables:Freestanding dining surfaces span casual to formal specifications with longer replacement cycles tied to household formation patterns.
- Chairs:Seating units attach to table sets or island configurations with the lowest individual price points and highest style-driven turnover volatility.
Cabinets dominate installed base. Countertops are where expansion concentrates.
Material:
Cost tier stratification runs from commodity particleboard to certified solid hardwood, with synthetic and metal alternatives capturing specification share in urban condominium markets.
- Wood:Engineered substrates and solid hardwood grades command margin concentration in semi-custom tiers, with EPA TSCA Title VI certification requirements restructuring panel sourcing economics. California CARB ATCM compliance layers duplicative testing burdens for cross-border manufacturers.
- Metal:Steel framing and aluminum accents gain share within modern and contemporary segments targeting dense metropolitan condominium specifications.
- Glass:Tempered and decorative surface treatments accent cabinet doors and shelving units in high-aesthetic renovation projects.
- Plastic:Thermoformed and molded components serve economy-tier stock cabinet lines with accelerated delivery timelines through big-box retail networks.
Wood commands specification authority. Metal is climbing the fastest in share gain.
Style:
Customer type alignment separates traditional suburban homeowners from urban condominium buyers, with distinct manufacturing and distribution requirements for each aesthetic cluster.
- Modern:Clean lines and minimal ornamentation favor frameless construction technology and European-style hardware systems. Omega Cabinetry targets this specification through contemporary residential engineering.
- Traditional:Raised-panel doors and decorative molding sustain demand in established suburban markets with longer replacement cycles and higher custom order attachment.
- Rustic:Distressed finishes and reclaimed material aesthetics concentrate in vacation property and secondary home markets.
- Contemporary:Transitional styling bridges modern and traditional elements with the broadest demographic appeal across renovation and new construction channels.
Traditional styling dominates installed base. Modern specifications are gaining share fastest in metropolitan corridors.
End User:
Procurement authority fragments across direct consumer, builder-captive, and institutional purchasing systems with divergent certification and volume requirements.
- Residential:Single-family builders and renovation contractors drive the largest volume concentration, with USDA BioPreferred labeling influencing federal-adjacent procurement criteria.
- Commercial:Multi-tenant food service and workplace kitchen specifications demand durability certification and accelerated replacement timelines.
- Hospitality:Hotel and restaurant chains centralize purchasing through national accounts with sustainability certification requirements and standardized installation protocols.
- Institutions:Educational and healthcare facilities operate under HUD green building specifications that redirect procurement toward certified product tiers for affordable housing project eligibility.
Residential channels dominate order volume. Hospitality represents the steepest expansion trajectory for certified product tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian softwood lumber flows into US cabinet manufacturing networks, while Mexican assembly operations feed cross-border renovation demand in southwestern states. This trade corridor shapes raw material availability and finished goods distribution across North American kitchen furniture supply chains.
Southeast
Texas and Florida housing starts absorb premium and semi-custom cabinet volumes at accelerating rates. EPA TSCA Title VI formaldehyde standards bind manufacturers sourcing composite wood panels across state lines. Atlanta and Charlotte distribution hubs concentrate inventory for builder-direct procurement channels serving metropolitan corridors.
California
Low-emission finishes and certified wood substrates command specification preference under Title 24 energy code mandates. California Air Resources Board ATCM requirements extend binding precedent for cross-border manufacturers selling into the nation's largest state economy. Los Angeles and Bay Area renovation contractors drive demand for frameless contemporary specifications in dense urban condominium markets.
Northeast
Established suburban markets sustain traditional styling preferences with longer replacement cycles and higher custom order attachment. USDA BioPreferred program labeling influences federal procurement criteria for institutional and hospitality sector purchasing. Boston and New York metropolitan corridors concentrate specification authority among design-build firms and renovation contractors.
Midwest
Domestic sawmill capacity constraints and Canadian softwood tariff exposure compress margins for solid wood product lines serving traditional styling segments. Pennsylvania manufacturing bases sustain long lead-time custom orders through captive production networks. Chicago and Detroit metropolitan markets balance renovation-driven replacement cycles with new construction absorption in surrounding suburban corridors.
Southwest
Cross-border assembly operations from Mexican manufacturing zones feed price-sensitive renovation demand with accelerated delivery timelines. HUD green building specifications redirect multifamily developer procurement toward certified product tiers for affordable housing project eligibility. Phoenix and Las Vegas construction activity concentrates demand for stock and semi-custom cabinet specifications in high-volume production homebuilder channels.
United States Kitchen Furniture Market Competitive Landscape
On the supply side, the industry is structured around three distinct manufacturing tiers with divergent lead-time and customization capabilities. Large-scale producers anchor mass-market distribution through big-box retail partnerships, while mid-cap specialists occupy semi-custom segments with modular production systems. Small-batch custom fabricators sustain premium positioning through extended lead-time craftsmanship. Competitive moves concentrate on backward integration into panel substrate sourcing and geographic expansion into high-growth metropolitan corridors.
Within the custom fabrication tier, Wood-Mode exemplifies Pennsylvania-based manufacturing persistence through captive production networks. Omega Cabinetry occupies a position representing frameless construction technology specialization for contemporary residential specifications. Fortune Brands Home & Security anchors the mass-market vector through big-box retail distribution scale. These three archetypes illustrate how supply-side segmentation maps to divergent customer procurement systems across renovation and new construction channels.
| Leading Market Players |
|---|
| Wood-Mode |
| Omega Cabinetry |
| Fortune Brands Home & Security |
| Thomasville Cabinetry |
| Starmark Cabinetry |
| American Woodmark Corp |
| Diamond Cabinets |
| Plain & Fancy Cabinetry |
| KraftMaid Cabinets |
| Others |
Value Network & Pricing Analysis
Pennsylvania manufacturing clusters anchor custom cabinet production capacity, constraining premium-tier pricing power as lead times extend and buyers absorb scarcity premiums. This geographic concentration shapes how semi-custom and stock tiers compete on delivery speed versus craftsmanship positioning.
Pricing Analysis
Prior-generation laminate surfaces face current-generation thermally fused laminate pricing pressure as hybrid substrates deliver solid-surface performance at engineered wood cost points. Three-tier pricing structure across premium, standard, and economy levels separates custom hardwood fabrication from semi-custom modular lines from stock big-box retail. Price differentiation rests on EPA TSCA Title VI certification burden and California CARB ATCM compliance layering. Cost compression in semi-custom tiers is intensifying because modular manufacturing narrows the gap with custom craftsmanship. Big-box retail channels exhibit highest price sensitivity; institutional buyers under USDA BioPreferred criteria show lowest sensitivity.
Supply Chain Analysis
Domestic panel manufacturers and Southeast assembly operations hold concentrated capacity for certified composite wood substrates under EPA formaldehyde standards. Geographic supply concentration centers on Pennsylvania custom fabrication networks, Southeast semi-custom modular plants, and Mexican cross-border assembly zones feeding southwestern states. Raw material dependencies draw from Canadian softwood lumber flows, domestic engineered panel production, and imported hardware systems. Single-source vulnerability runs through Canadian sawmill capacity exposed to tariff fluctuations. Distribution runs through builder-direct procurement channels consolidating away from traditional distributor networks in Texas and Florida metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates where Title 24 energy codes and EPA formaldehyde standards bifurcate compliant from non-compliant supply tiers, creating specification niches for certified manufacturers.
For Market Incumbents: Pre-empt stock cabinet substitution by accelerating backward integration into certified panel substrate sourcing. Capture USDA BioPreferred procurement premiums through federal and hospitality sector certification investment. Modular manufacturing technology from emerging entrants threatens semi-custom positioning; defend through captive Pennsylvania production networks sustaining custom craftsmanship differentiation. For New Entrants and Emerging Players: Southwestern multifamily corridors under HUD green specifications represent penetrable white-space where certified product tier demand outruns incumbent capacity. Frameless construction technology for urban condominium markets offers specification entry point against traditional styling dominance. Builder-direct channel partnerships in Texas and Florida metropolitan markets provide fastest go-to-market velocity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because modular manufacturing economics favor scaled semi-custom specialists over fragmented custom fabricators. Target acquisition archetype: mid-cap manufacturers with EPA TSCA Title VI certification infrastructure and Southeast distribution positioning. Signal to watch is pace of HUD green specification adoption redirecting multifamily procurement toward certified tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Substrates | EPA TSCA Title VI certification costs favor in-house composite wood production over supplier dependence. |
| Modular Manufacturing Scale-Up | Automated cutting systems bridge design software with production, compressing semi-custom lead times. |
| USDA BioPreferred Certification Program | Federal procurement and hospitality sector labeling creates premium tier pricing authority. |
| Builder-Direct Channel Partnerships | National production homebuilders in Texas and Florida centralize cabinet procurement through captive agreements. |
| Frameless Construction Technology Investment | European-style specifications capture urban condominium renovation demand in Los Angeles and Bay Area corridors. |
Research Methodology
The analysis maps cabinet, countertop, table, and chair sub-sectors, each validated through primary interviews with single-family residential builders, kitchen renovation contractors, distributor procurement managers, and EPA compliance officers. Secondary validation draws from EPA TSCA Title VI filings, California Air Resources Board certification databases, USDA BioPreferred product registries, and HUD green building specification documents. Bottom-up installation base modeling triangulates against top-down construction spending allocations.
Forecast assumptions hold California Title 24 energy code stringency, EPA formaldehyde emission standards, and Canadian softwood tariff exposure within observed trajectories across the analysis window. Segmentation dimensions modeled include product type, material grade, styling preference, and end-use channel. CAGRs derive from replacement cycle frequency analysis cross-referenced with housing start absorption patterns. Industry-specific inputs include CAD-to-CNC programming labor availability and modular manufacturing adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Southeast semi-custom specialists or accelerated PFAS restriction timelines would shift outcomes. Quarterly review of EPA enforcement patterns, CARB ATCM amendment proposals, and HUD green specification adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Rainbow Flatware Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Qatar Kitchen Hood Market