
 United States Commercial Vinyl Floor Covering Market | 2026-2036
United States Commercial Vinyl Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Vinyl Floor Covering Market Insights
Buyer concentration across healthcare facility networks is broadening as hospital procurement groups consolidate flooring contracts under national GPO frameworks. Tarkett North America leverages its broad resin compounding capabilities to serve these consolidated buyers with specification-grade sheet goods. Mohawk Industries anchors its position through captive PVC resin sourcing and dense distribution center coverage across the Midwest and Southeast. Mannington Mills differentiates via design-led luxury vinyl plank collections targeting hospitality renovation cycles.
United States commercial vinyl floor covering comprises multi-layer synthetic flooring systems built from PVC resin, plasticizers, stabilizers, and printed wear layers with urethane or ceramic bead surface treatments, manufactured through calendering or extrusion processes for high-traffic durability and moisture resistance. Luxury vinyl tile and vinyl plank categories lead specification value as architects prioritize dimensional stability and rapid installation in occupied building retrofits. Glue-down and click-lock installation methods dominate volume in healthcare and educational end uses where subfloor preparation standards and moisture mitigation protocols remain stringent.
California Air Resources Board (CARB) Phase 2 formaldehyde standards and EPA TSCA Title VI compliance frameworks govern resin system emissions, while OSHA workplace exposure limits influence installer product selection and adhesive specification. The Federal Trade Commission's Green Guides constrain environmental marketing claims, pressuring manufacturers toward third-party FloorScore or NSF 332 certifications. Stakeholders must monitor evolving state-level extended producer responsibility proposals and bio-based plasticizer substitution timelines to align capital allocation with regulatory trajectory.
Market Dynamics
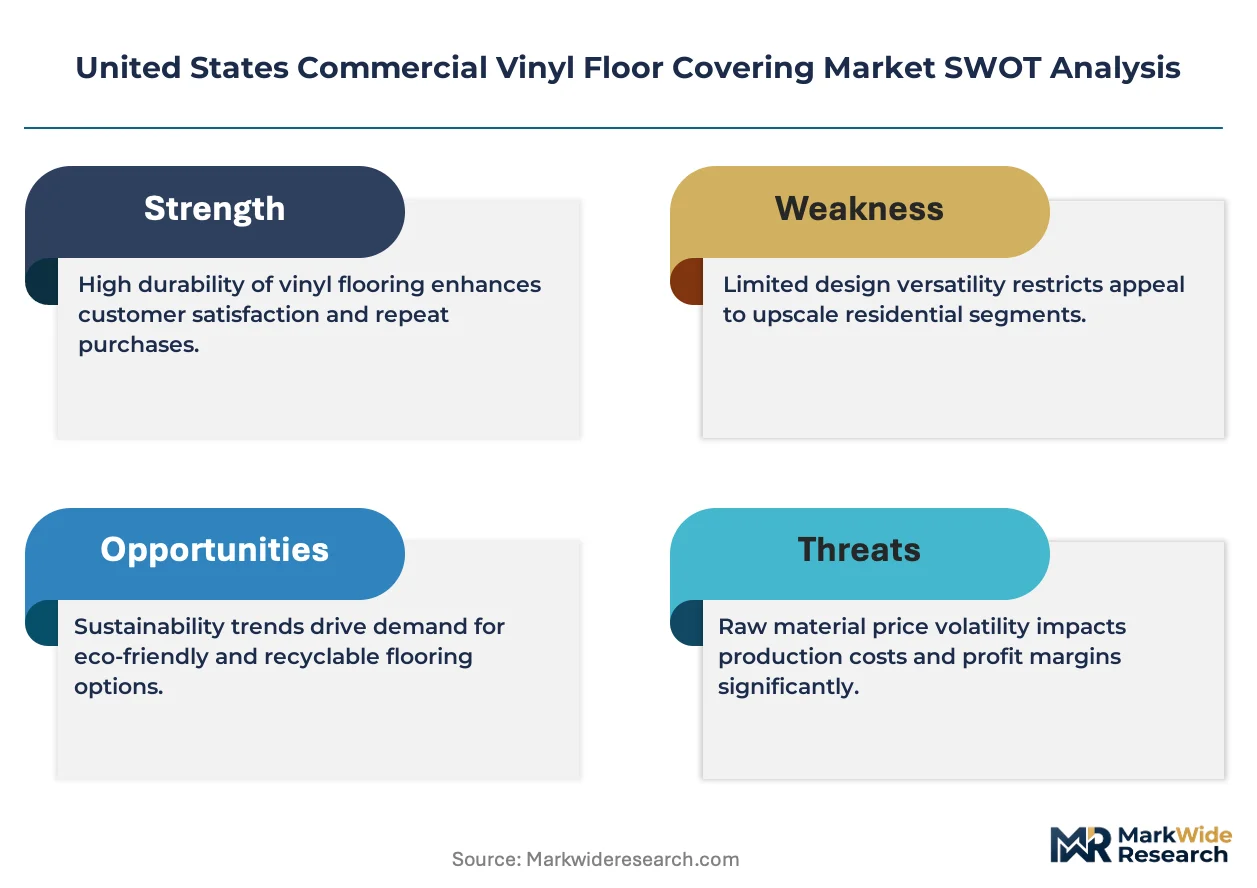
Hospital procurement consolidation under national GPO frameworks is compressing supplier margins while elevating specification-grade requirements for infection-control surfaces across acute care networks.
Growth Catalysts
- Healthcare Facility Modernization:Hospital renovation cycles prioritize moisture-resistant sheet goods with welded seams for sterile environment maintenance. The EPA's persistent organic pollutant screening drives specification toward low-emission resin systems.
- Low-VOC Regulatory Momentum:California Air Resources Board Phase 2 formaldehyde standards and New York State low-VOC mandates force product reformulation toward compliant plasticizer chemistries, creating first-mover advantages for certified manufacturers.
- Southeast Construction Corridor:Medical office and retail buildout permits across Georgia, Florida, and Texas concentrate demand for rapid-installation luxury vinyl plank systems in occupied building retrofits.
Market Restraints
- Petrochemical Input Volatility:PVC resin and phthalate plasticizer pricing fluctuates with ethylene and chlorine feedstock markets, compressing margin predictability for calendering operations.
- Upstream Concentration Risk:Domestic PVC resin production concentrates along the Gulf Coast, exposing compounders to hurricane-related supply interruptions and force majeure events.
- Substitution Pressure:Bio-based linoleum and rubber flooring gain specification share in LEED-targeted projects where renewable content thresholds exclude conventional vinyl systems.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Pending state-level EPR proposals for flooring waste create closed-loop service revenue streams through take-back and mechanical recycling infrastructure.
- Bio-Plasticizer Substitution:Epoxidized soybean oil and citrate-based plasticizers offer compliance pathways ahead of anticipated phthalate restrictions in pediatric and senior living specifications.
- Digital Specification Platforms:Architect and designer procurement through BIM-integrated product libraries reduces friction in healthcare and hospitality project workflows.
Industry Challenges
- Installation Certification Bottlenecks:Moisture mitigation and welding seam protocols require specialized contractor training, constraining project velocity in healthcare retrofits.
- Multi-Jurisdiction Compliance Complexity:FloorScore, NSF 332, and state-level emission standards demand parallel testing regimes, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Vinyl Floor Covering Market |
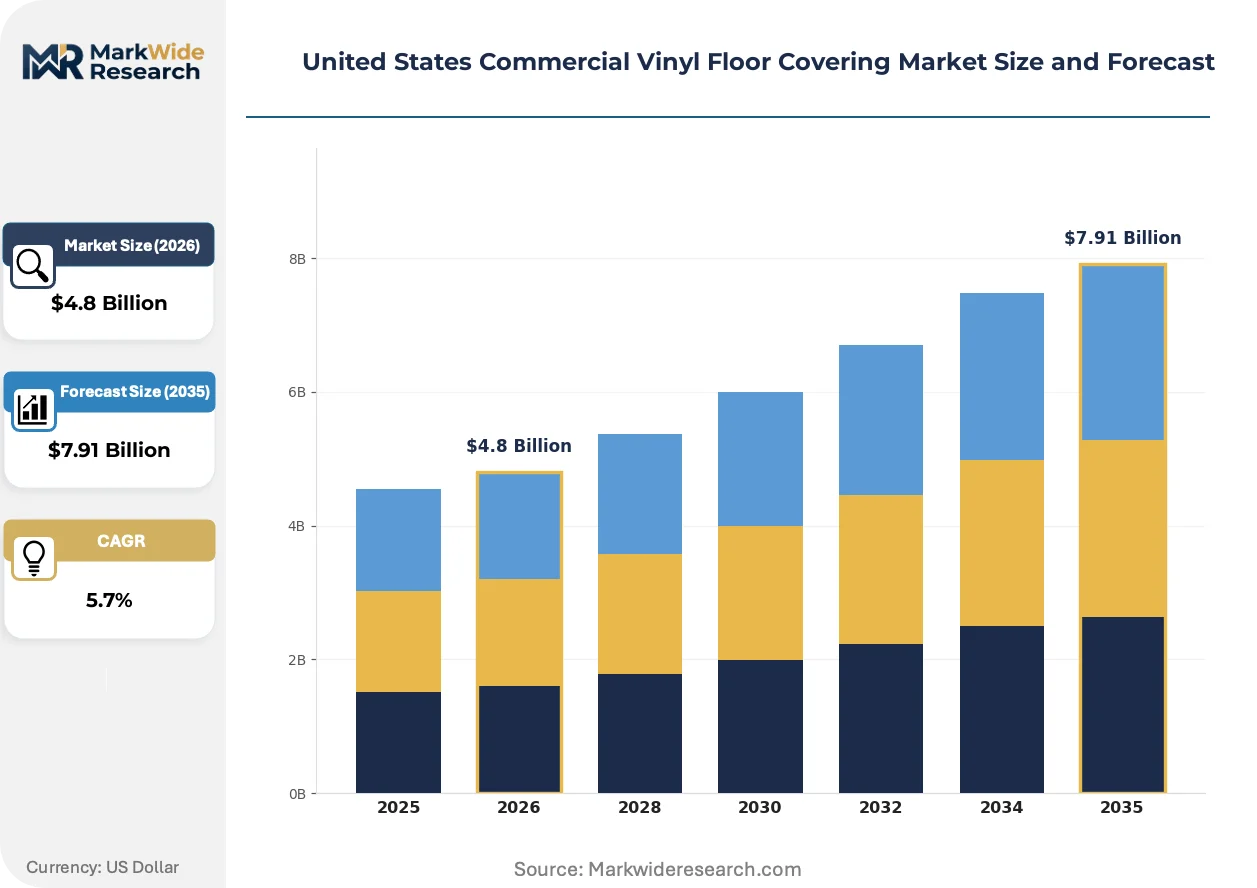
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Vinyl Plank, Vinyl Sheet, Vinyl Composite Tile Installation Method: Glue Down, Loose Lay, Click Lock, Heat Weld End User: Healthcare Facilities, Educational Institutions, Retail Spaces, Hospitality Design Pattern: Wood Look, Stone Look, Abstract, Geographic |
| Companies Covered | Tarkett North America, Interface, Mohawk Industries, Forbo Flooring Systems, Gerflor USA, Shaw Industries Group, Mannington Mills, Roppe Corporation, Armstrong Flooring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Vinyl Floor Covering Market Trends and Innovations
Surface engineering and digital manufacturing are compressing product development cycles while elevating performance thresholds for commercial durability specifications.
Ceramic bead-enhanced urethane wear layers is electrifying specification value in high-traffic healthcare corridors. Hospital facilities managers specify these surfaces for 20-year lifecycle performance guarantees. The technology is compressing replacement frequency and shifting capital planning toward premium first-cost outlays.
OSHA workplace exposure limits for adhesive solvents are forcing water-based and pressure-sensitive installation system adoption. Flooring contractors face respiratory protection mandates during occupied building renovations. Educational and senior living retrofits in the Northeast and California lead specification shifts toward low-odor, zero-VOC attachment methods.
Architects increasingly bundle flooring specification within national GPO contracts rather than project-by-project selection. Healthcare facility networks consolidate procurement under Premier and Vizient frameworks, reducing distributor influence. This concentration is most visible across IDN-affiliated hospital systems in the Southeast and Midwest corridors.
United States Commercial Vinyl Floor Covering Market Segmentation
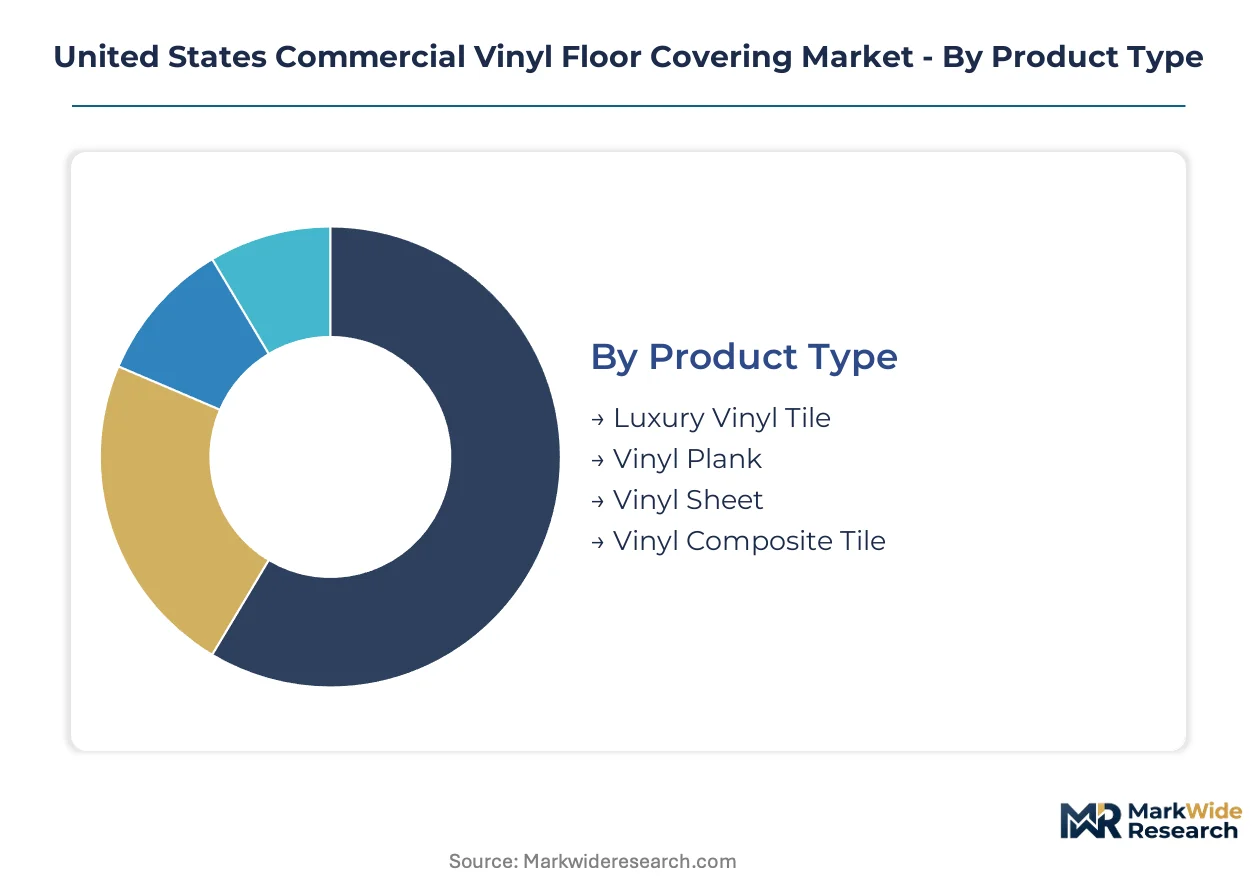
Segmentation in the United States commercial vinyl floor covering market reveals how specification requirements fragment across installation constraints, regulatory exposure, and aesthetic demands. Procurement patterns diverge sharply between acute care networks prioritizing welded seam sheet goods and retail developers favoring rapid-install plank systems.
Product Type:
Resin compounding capacity and calendering line investments concentrate supply-side leverage among manufacturers with captive PVC sourcing and multi-layer lamination expertise.
- Luxury Vinyl Tile:Multi-layer rigid core construction with printed visual layers and ceramic bead-enhanced wear surfaces delivers dimensional stability for high-traffic corridors. Hospital networks across the Southeast corridor specify these systems for 20-year lifecycle guarantees in acute care renovation cycles.
- Vinyl Plank:Click-lock and glue-down formats with SPC or WPC cores target occupied building retrofits where moisture mitigation and rapid installation compress project timelines. Retail buildouts in Texas and Florida drive specification volume for floating floor systems with minimal subfloor preparation.
- Vinyl Sheet:Homogeneous or heterogeneous multi-layer constructions with welded seam capability serve sterile environment protocols in surgical suites and patient care zones.
- Vinyl Composite Tile:Through-pattern vinyl chips bonded under heat and pressure offer economical replacement cycles for educational facilities and light commercial applications.
Vinyl sheet and luxury vinyl tile absorb the bulk of installed capacity; vinyl plank is expanding most quickly.
Installation Method:
Adhesive chemistry and subfloor preparation standards create tiered contractor certification requirements that filter market access.
- Glue Down:Pressure-sensitive and epoxy adhesive systems bond flooring directly to prepared concrete or plywood substrates. OSHA workplace exposure limits for solvent-based adhesives force water-based formulation adoption in Northeast and California educational retrofits.
- Click Lock:Angled edge profiles enable floating floor installation without adhesive, reducing project duration in occupied healthcare and hospitality renovations. Georgia and Florida medical office buildouts favor this method for minimal disruption to active clinical operations.
- Loose Lay:Friction-backed systems rely on weight and perimeter anchoring for stability, limiting application to low-moisture environments with stable substrates.
- Heat Weld:Hot-air welding of seam edges creates monolithic surfaces mandatory for infection control in hospital surgical suites and pharmaceutical clean rooms.
Glue down methods dominate current specification volume; click lock systems are climbing the fastest.
End User:
Procurement consolidation under national GPO frameworks compresses supplier margins while elevating compliance documentation requirements.
- Healthcare Facilities:Acute care networks and outpatient clinics specify low-emission resin systems with welded seams for sterile maintenance. EPA persistent organic pollutant screening drives FloorScore-certified product selection across IDN-affiliated hospital systems.
- Educational Institutions:K-12 districts and university facilities balance first-cost constraints with 30-year replacement cycles, favoring through-pattern vinyl composite tile for corridor durability.
- Retail Spaces:Big-box and specialty retail chains prioritize rapid installation and brand-aligned visual merchandising through wood-look luxury vinyl plank systems.
- Hospitality:Hotel renovation cycles emphasize design-led specification with stone-look and abstract patterns for lobby and guest room refresh programs.
Healthcare facilities absorb the bulk of specification-grade capacity; hospitality is gaining share fastest.
Design Pattern:
Digital printing and surface embossing technologies enable pattern replication at cost points that displace natural materials in commercial specification.
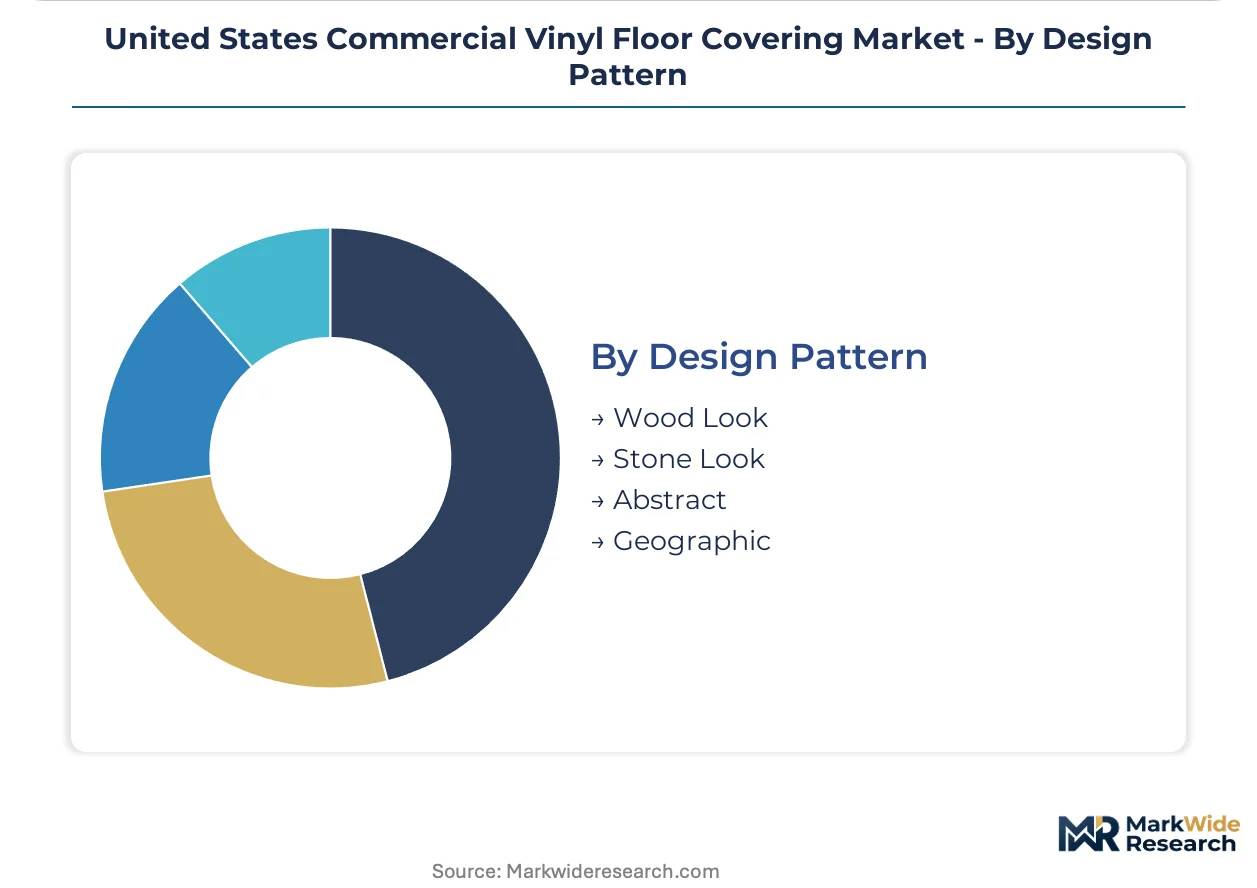
- Wood Look:Oak, maple, and walnut visual reproductions with registered embossing target hospitality and retail environments seeking warm residential aesthetics.
- Stone Look:Marble, slate, and travertine patterns serve healthcare and corporate lobbies where premium material appearance must reconcile with maintenance protocols.
- Abstract:Non-representational visuals and custom color fields support wayfinding and brand identity applications in educational and corporate environments.
- Geographic:Region-specific or culturally referenced patterns address themed hospitality and entertainment venue requirements.
Wood look patterns absorb the bulk of current production volume; stone look applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation and commercial construction permits concentrate demand across distinct state corridors, with regulatory pressure from California and New York reshaping formulation requirements nationwide.
Southeast Corridor
Medical office buildouts across Georgia, Florida, and Texas drive specification volume for rapid-installation luxury vinyl plank systems. State environmental agencies in Florida enforce indoor air quality protocols that align with EPA persistent organic pollutant screening. Atlanta and Dallas-Fort Worth anchor distribution networks serving acute care networks with welded seam sheet goods for sterile environments.
California
Healthcare facility renovations in Los Angeles and San Francisco prioritize FloorScore-certified products under CARB Phase 2 formaldehyde standards. The California Air Resources Board mandates low-VOC thresholds that force plasticizer chemistry reformulation. Manufacturing compounders in the Central Valley adjust resin systems to maintain specification access across West Coast hospital networks.
New York Metro
Educational institution retrofits across New York State accelerate water-based adhesive adoption under low-VOC mandates. The state Department of Environmental Conservation enforces emissions limits that exceed federal OSHA workplace exposure guidelines. Brooklyn and Queens manufacturing districts host specification-grade sheet goods production serving Northeast healthcare IDNs.
Midwest Manufacturing Belt
Captive PVC resin sourcing and dense distribution center coverage concentrate supply-side leverage across Ohio, Michigan, and Illinois. State procurement offices in these jurisdictions specify NSF 332-certified products for public school construction bonds. Chicago and Cleveland serve as logistics hubs calibrating inventory to GPO contract fulfillment cycles.
Southwest Growth Markets
Retail buildout permits in Arizona and Nevada favor click-lock floating floor systems with minimal subfloor preparation requirements. State building codes in these jurisdictions emphasize rapid project completion for occupied building renovations. Phoenix and Las Vegas construction markets absorb volume from national hospitality renovation programs.
United States Commercial Vinyl Floor Covering Market Competitive Landscape
Southeast-based producers anchor one tier; Midwest resin compounders hold supply-side leverage through captive sourcing and distribution density. The vendor structure consolidates around manufacturers with multi-layer lamination expertise and national GPO contract access. Three archetypes dominate: integrated resin-to-finished-goods operators, design-led specification specialists, and regional fabrication houses serving local contractor networks. Competitive maneuvering centers on welding seam certification programs and BIM-integrated product libraries that reduce architect specification friction.
Within the integrated manufacturing tier, Tarkett North America and Mohawk Industries exemplify scale-driven positioning through broad resin compounding capabilities and dense distribution infrastructure. Mannington Mills occupies a design-led specialization vector targeting hospitality renovation cycles with luxury vinyl plank collections. These three anchors demonstrate how procurement consolidation under Premier and Vizient frameworks rewards manufacturers with parallel compliance documentation and national service coverage.
| Leading Market Players |
|---|
| Tarkett North America |
| Interface |
| Mohawk Industries |
| Forbo Flooring Systems |
| Gerflor USA |
| Shaw Industries Group |
| Mannington Mills |
| Roppe Corporation |
| Armstrong Flooring |
| Others |
Pricing and Supply Chain Analysis
Ethylene feedstock costs cascade through PVC resin pricing tiers, compressing margins for compounders without captive Gulf Coast cracker capacity while elevating premiums for specification-grade sheet goods with FloorScore certification.
Pricing Analysis
Volume splits between commodity-grade vinyl composite tile and premium luxury vinyl plank systems, with the latter commanding 40-60% markups for ceramic bead-enhanced wear layers and welded seam capability. Price differentiation hinges on certification grade (FloorScore vs. NSF 332) and volume scale under national GPO contracts. Cost compression in the standard tier is intensifying because hospital procurement consolidation squeezes supplier margins. Educational institutions exhibit highest price sensitivity; acute care networks prioritize lifecycle performance over first cost.
Supply Chain Analysis
Domestic-content thresholds in public school construction bonds reshape sourcing toward Ohio, Michigan, and Illinois manufacturing clusters. PVC resin production concentrates along the Texas and Louisiana Gulf Coast, with plasticizer compounding anchored in the Midwest and Southeast. The supply chain draws from ethylene crackers, chlorine caustic soda operations, and imported titanium dioxide pigments. Single-source vulnerability concentrates around hurricane-exposed resin production. Distribution runs through manufacturer-direct GPO fulfillment and regional distributor networks serving contractor installation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calendering line capacity constraints prop pricing power for integrated manufacturers with in-house resin sourcing, as hospital GPO contracts absorb available specification-grade output.
For Market Incumbents: Cement specification-grade positioning through captive PVC resin sourcing and multi-layer lamination expertise. Expand welding seam certification programs to lock out regional fabrication houses. Bio-based linoleum substitution in LEED-targeted projects threatens volume in the educational segment; counter with epoxidized soybean oil plasticizer pilots ahead of anticipated pediatric facility restrictions.
For New Entrants and Emerging Players: Launch via BIM-integrated product libraries targeting Southeast corridor medical office buildouts where architect specification friction remains high. White-space exists in rapid-install click-lock systems for occupied healthcare renovations in Georgia and Florida. Partner with regional distributors lacking national GPO contract access to bypass incumbent fulfillment networks.
For Investors and Strategic Acquirers: Pending state-level extended producer responsibility legislation is the leading indicator that closed-loop recycling infrastructure will separate winners from commodity compounders. Five-to-ten year viability favors integrated resin-to-finished-goods operators with dense distribution center coverage. Monitor bio-plasticizer substitution timelines as the signal for portfolio reallocation away from phthalate-dependent assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin | Gulf Coast cracker access insulates margin from ethylene volatility and force majeure events. |
| FloorScore Certification Investment | CARB Phase 2 alignment secures specification access across West Coast hospital networks. |
| Bio-Plasticizer Pilot Programs | Epoxidized soybean oil trials preempt phthalate restrictions in pediatric and senior living segments. |
| Take-Back Infrastructure Buildout | Mechanical recycling capabilities position for pending state extended producer responsibility mandates. |
| BIM Library Integration | Digital specification platforms reduce architect friction in healthcare and hospitality project workflows. |
Research Methodology
Multi-period observation of commercial construction permits, hospital GPO contract awards, and resin pricing indices anchored the trend analysis, supplemented by interviews with flooring procurement managers at integrated delivery networks, calendering operations directors, distributor branch managers, and architect specification writers. Secondary validation drew from EPA TSCA filings, CARB emission standard updates, SEC 10-K disclosures by listed flooring manufacturers, and customs data on PVC resin imports. Bottom-up project pipeline analysis triangulated against top-down spending forecasts from healthcare construction databases.
Input-output matrices mapped resin feedstock costs through compounding, calendering, and distribution stages across product type, installation method, end user, and design pattern segments. CAGRs were derived from regression analysis of historical permit volumes and procurement cycle timing. Forecast inputs included hospital renovation cycle frequency, state-level low-VOC mandate adoption curves, and Gulf Coast hurricane disruption probabilities.
The model assumes a particular technology adoption path for ceramic bead-enhanced wear layers; alternative pathways for bio-based surface treatments would alter the outlook for premium specification share. Forecasts reflect assumptions about GPO consolidation velocity and plasticizer chemistry regulatory timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Europe Laminate Flooring Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market