
 United States Modular Kitchen Market | 2026-2036
United States Modular Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
United States Modular Kitchen Market Analytics
Project finance and kitchen leasing models are narrowing the competitive field for mid-tier suppliers. IKEA US leverages its flat-pack logistics network to sustain price positioning across mass-market segments. Eggersmann USA anchors its presence through bespoke German cabinetry craftsmanship in high-end metropolitan markets. Häfele America Co. competes on hardware and fitting ecosystems that differentiate modular systems from conventional built-in alternatives.
United States modular kitchens comprise prefabricated cabinet carcasses, standardized countertop substrates, and coordinated appliance housings designed for site-assembly with dimensional tolerances of 1/8 inch or tighter. Laminate surfaces dominate volume production for their cost efficiency and moisture resistance, while solid wood and metal finishes command premium positioning in designer-specified installations. Homeowners represent the largest end-user pool, though contractor and builder channels are capturing faster growth as production homebuilders adopt modular specifications for speed-to-close. Custom installation types retain the highest margin pools, whereas DIY and modular-ready formats are expanding access for first-time buyers and renovation platforms.
EPA TSCA Title VI formaldehyde standards and OSHA workplace exposure limits shape composite wood sourcing decisions for domestic manufacturers. California Air Resources Board (CARB) Phase 2 compliance functions as a de facto national benchmark for low-emission substrates, effectively raising baseline product standards across state lines. Stakeholders must monitor evolving Department of Energy appliance efficiency mandates and state-level building electrification codes that will redefine specification requirements for integrated kitchen systems.
Market Dynamics
Suburban renovation cycles are compressing replacement timelines as homeowners accelerate kitchen refreshes ahead of anticipated material cost escalations and tightening EPA formaldehyde standards for composite substrates.
Growth Catalysts
- EPA TSCA Title VI formaldehyde limits:Low-emission substrate mandates are pulling forward replacement demand as homeowners seek pre-compliant inventory.
- Production homebuilder adoption:Speed-to-close requirements are driving modular specifications into new construction pipelines across Texas, Florida, and California metro corridors.
- Moisture-resistant laminate surfaces:Cost-efficient countertop substrates are expanding addressable market penetration among first-time buyers and renovation platforms.
Market Restraints
- Composite wood input volatility:Particleboard and medium-density fiberboard pricing fluctuates with resin and timber feedstock availability.
- California CARB Phase 2 de facto nationalization:Stringent emission benchmarks raise compliance costs for manufacturers serving multi-state distribution networks.
- Dimensional tolerance requirements:Site-assembly demands of 1/8 inch or tighter limit viable contractor pools and increase installation failure rates.
Strategic Opportunities
- Department of Energy appliance efficiency mandates:Integrated kitchen system specifications will favor suppliers with pre-certified appliance housing designs.
- State-level building electrification codes:Gas-to-electric conversion incentives create specification windows for induction-ready cabinetry configurations.
- DIY and modular-ready formats:Flat-pack logistics networks are opening access segments previously served only by custom installation channels.
Industry Challenges
- Skilled installer scarcity:Precision assembly requirements exceed capabilities of generalist contractor labor pools in secondary metro markets.
- Multi-jurisdiction compliance complexity:Divergent state adoption timelines for federal formaldehyde standards fragment inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Modular Kitchen Market |
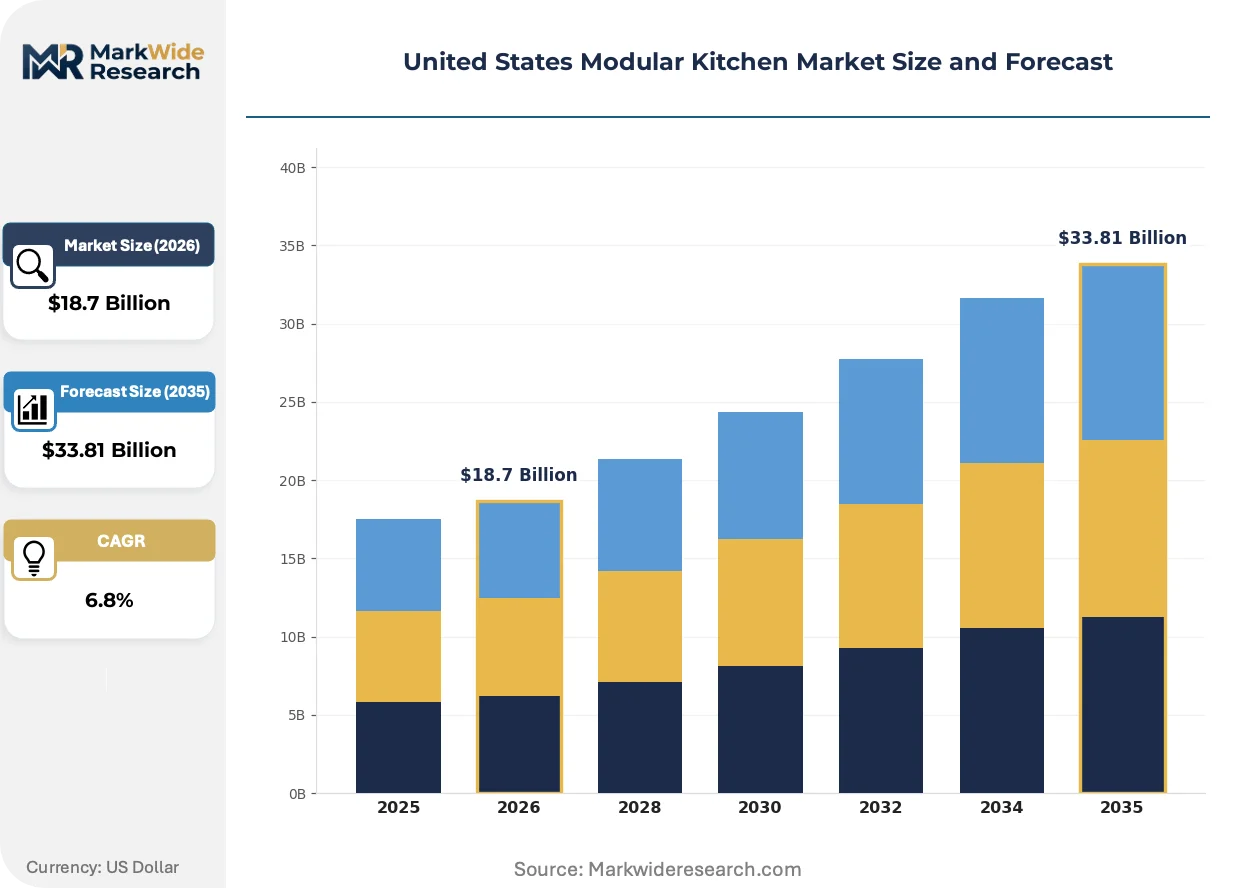
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Shelving, Appliances Material: Wood, Laminate, Metal, Glass End User: Homeowners, Contractors, Designers, Builders Installation Type: DIY, Professional, Modular, Custom |
| Companies Covered | Lineadecor USA LLC, Eggersmann USA, IKEA US, Snaidero USA, Pedini USA, Häfele America Co., Hettich America L.P., Hacker Greenwich, Boston Cabinets Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Modular Kitchen Market Evolving Landscape
Digital configuration tools and connected appliance integration are redefining how kitchen systems are specified, sold, and serviced across residential channels.
Smart kitchen ecosystems are digitizing how homeowners interact with storage, lighting, and appliance interfaces. High-end metropolitan buyers are specifying voice-activated hardware and sensor-driven inventory management at accelerating rates. This convergence is digitizing traditional cabinetry from static furniture into dynamic home infrastructure.
OSHA workplace exposure limits for formaldehyde are tightening manufacturing facility requirements. Composite wood processors must upgrade ventilation and monitoring systems to retain operational licenses. Domestic manufacturers serving California, Texas, and Florida distribution nodes are absorbing the steepest compliance capital burdens.
Builder-direct procurement is consolidating specification authority away from traditional dealer networks. Production homebuilders in Arizona, Nevada, and Georgia are establishing captive supplier relationships with modular kitchen fabricators. This channel compression is most visible in Sun Belt markets where housing starts outpace national permitting rates.
United States Modular Kitchen Market Segmentation
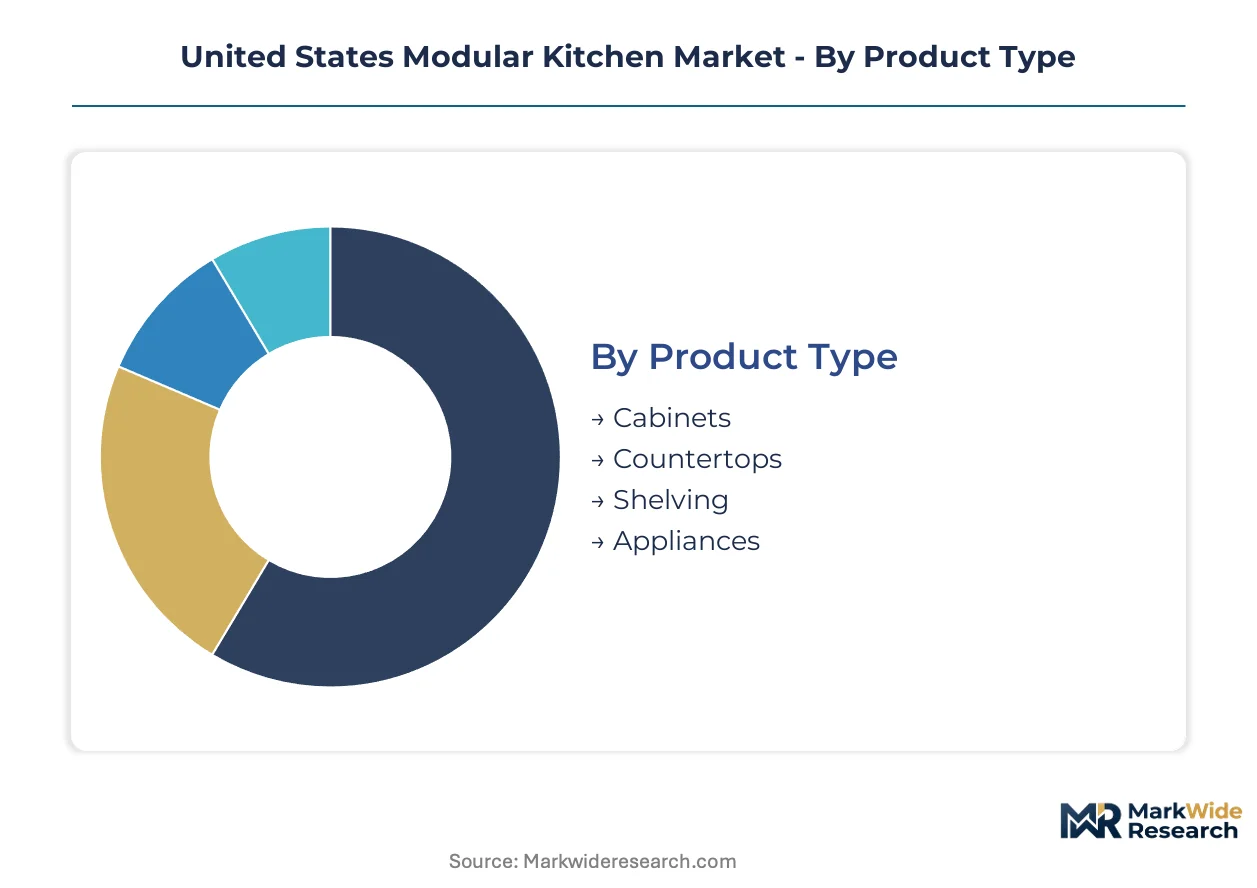
Modular kitchen procurement patterns diverge sharply across customer types and installation methods, with replacement cycles ranging from 5-year appliance refreshes to 20-year cabinet overhauls. Understanding these velocity differentials helps suppliers align inventory turns with demand timing.
Product Type:
Cabinets and countertops turn over on decade-long cycles, while appliances and shelving refresh every 5-7 years as technology and storage needs evolve.
- Cabinets:Prefabricated carcasses with standardized hinge boring patterns and adjustable leg systems. Demand concentrates among Texas and Florida production homebuilders seeking speed-to-close advantages, though EPA TSCA Title VI formaldehyde compliance is pulling forward replacement timelines among suburban renovators.
- Countertops:Laminate substrates dominate volume production for moisture resistance and cost efficiency, while solid surface and quartz command premium positioning. California metro corridors show strongest specification intensity as homeowners accelerate kitchen refreshes ahead of anticipated material cost escalations.
- Shelving:Adjustable rail systems and pull-out organizers integrate with standard cabinet widths.
- Appliances:Integrated housings for cooktops, refrigeration, and ventilation systems coordinate with cabinet dimensions.
Cabinets dominate installed base. Appliances are where expansion concentrates.
Material:
Cost tiers separate premium positioning from mass-market penetration, with compliance costs creating additional stratification around emission standards.
- Wood:Solid hardwood and veneer-wrapped composite substrates deliver bespoke aesthetics for high-end metropolitan markets. California CARB Phase 2 compliance functions as de facto national benchmark, raising baseline costs for domestic manufacturers serving multi-state distribution networks.
- Laminate:Thermally fused melamine surfaces on particleboard or MDF cores offer cost-efficient moisture resistance. First-time buyers and renovation platforms in Sun Belt markets drive volume uptake where housing starts outpace national permitting rates.
- Metal:Stainless steel and aluminum finishes serve commercial-influenced residential specifications.
- Glass:Tempered and back-painted panels accent upper cabinetry and display shelving.
Laminate dominates installed base. Wood is climbing the fastest as emission standards tighten.
End User:
Procurement authority is shifting from individual decision-makers to consolidated builder-direct channels, compressing dealer network relevance.
- Homeowners:Individual purchasers drive custom installation specifications and premium material selections. Suburban renovation cycles are compressing replacement timelines as EPA formaldehyde standards for composite substrates create pre-compliance demand windows.
- Contractors:Generalist and specialist installers serve renovation platforms and insurance restoration channels. Skilled installer scarcity limits viable contractor pools in secondary metro markets where dimensional tolerance requirements exceed generalist capabilities.
- Designers:Interior design professionals specify coordinated systems for high-end residential projects.
- Builders:Production homebuilders in Arizona, Nevada, and Georgia are establishing captive supplier relationships with modular kitchen fabricators, consolidating specification authority away from traditional dealer networks.
Homeowners dominate installed base. Builders are gaining share fastest through channel compression.
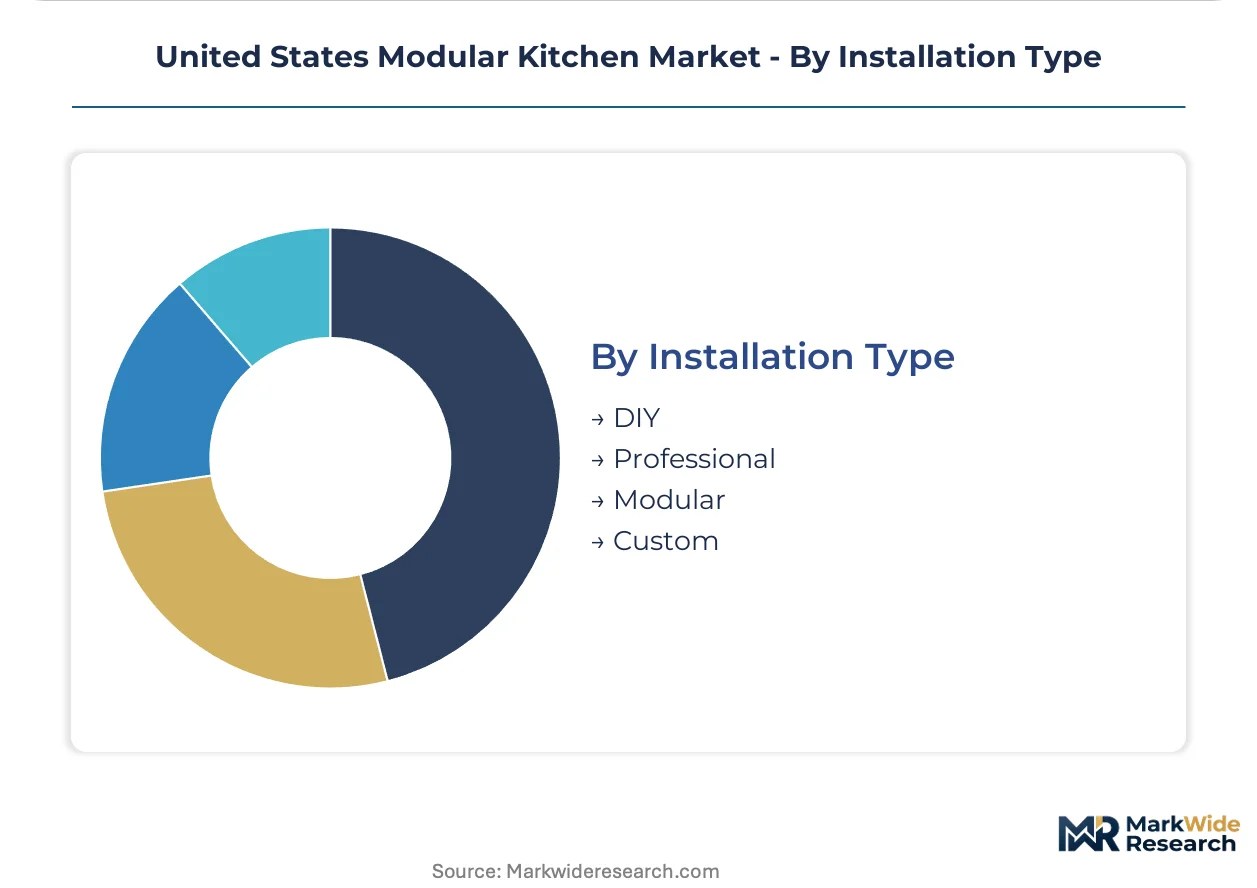
Installation Type:
Margin structures and access barriers vary dramatically, with precision requirements filtering contractor participation and flat-pack formats democratizing entry.
- Custom:Site-measured and shop-built components tailored to non-standard dimensions and architectural constraints. High-end metropolitan buyers specify these installations at accelerating rates, generating the highest margin pools in the market.
- Professional:Certified installers execute modular systems with dimensional tolerances of 1/8 inch or tighter. Installation failure rates and limited skilled labor constrain expansion in secondary markets despite strong demand in Texas, Florida, and California corridors.
- DIY:Flat-pack logistics networks enable homeowner assembly of standardized cabinet and shelving units.
- Modular:Pre-configured cabinet runs and appliance housings designed for rapid site-assembly with minimal customization.
Custom dominates installed base. DIY is expanding most quickly as flat-pack logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a modest export surplus in finished cabinetry while importing specialized hardware components and premium surface materials from European and Asian suppliers. Regional demand concentrates in Sun Belt metropolitan corridors where housing formation rates outpace national averages. EPA TSCA Title VI formaldehyde standards and California CARB Phase 2 benchmarks create compliance cost differentials that favor domestic fabricators with integrated substrate processing capabilities.
California
Los Angeles and San Francisco Bay Area metro corridors drive premium specification intensity as homeowners accelerate kitchen refreshes ahead of anticipated material cost escalations. California Air Resources Board Phase 2 compliance functions as the de facto national emission benchmark, raising baseline product standards that propagate across state lines through multi-state distribution networks. San Diego and Sacramento fabrication clusters absorb the steepest compliance capital burdens for ventilation and monitoring system upgrades.
Texas
Dallas-Fort Worth and Houston production homebuilders are establishing captive supplier relationships with modular kitchen fabricators to compress speed-to-close timelines. State-level building electrification codes in Austin and progressive municipal jurisdictions are creating specification windows for induction-ready cabinetry configurations. San Antonio and El Paso secondary markets face skilled installer scarcity as dimensional tolerance requirements exceed generalist contractor capabilities.
Florida
Miami and Tampa metro areas show strongest moisture-resistant laminate surface uptake among first-time buyers and renovation platforms. Florida building codes for wind resistance and moisture management intersect with federal EPA formaldehyde standards to create multi-jurisdiction compliance complexity for inventory management. Orlando and Jacksonville distribution nodes serve as consolidation points for Southeast regional supply chains.
Northeast Corridor
New York Metro and Greater Boston high-end metropolitan buyers specify custom installations with solid wood and metal finishes at accelerating rates. Historic preservation requirements and stringent local building codes layer additional specification constraints onto federal substrate emission standards. Philadelphia and Washington DC contractor channels capture faster growth as production homebuilders adopt modular specifications for infill development projects.
Pacific Northwest
Seattle and Portland homeowners drive demand for sustainable material certifications and low-emission substrate alternatives that exceed baseline EPA requirements. Oregon and Washington state-level environmental regulations anticipate federal formaldehyde standard trajectories, positioning regional fabricators ahead of compliance curves. Boise and Spokane secondary markets experience installation failure rate elevation due to limited pools of precision-capable contractors.
United States Modular Kitchen Market Competitive Landscape
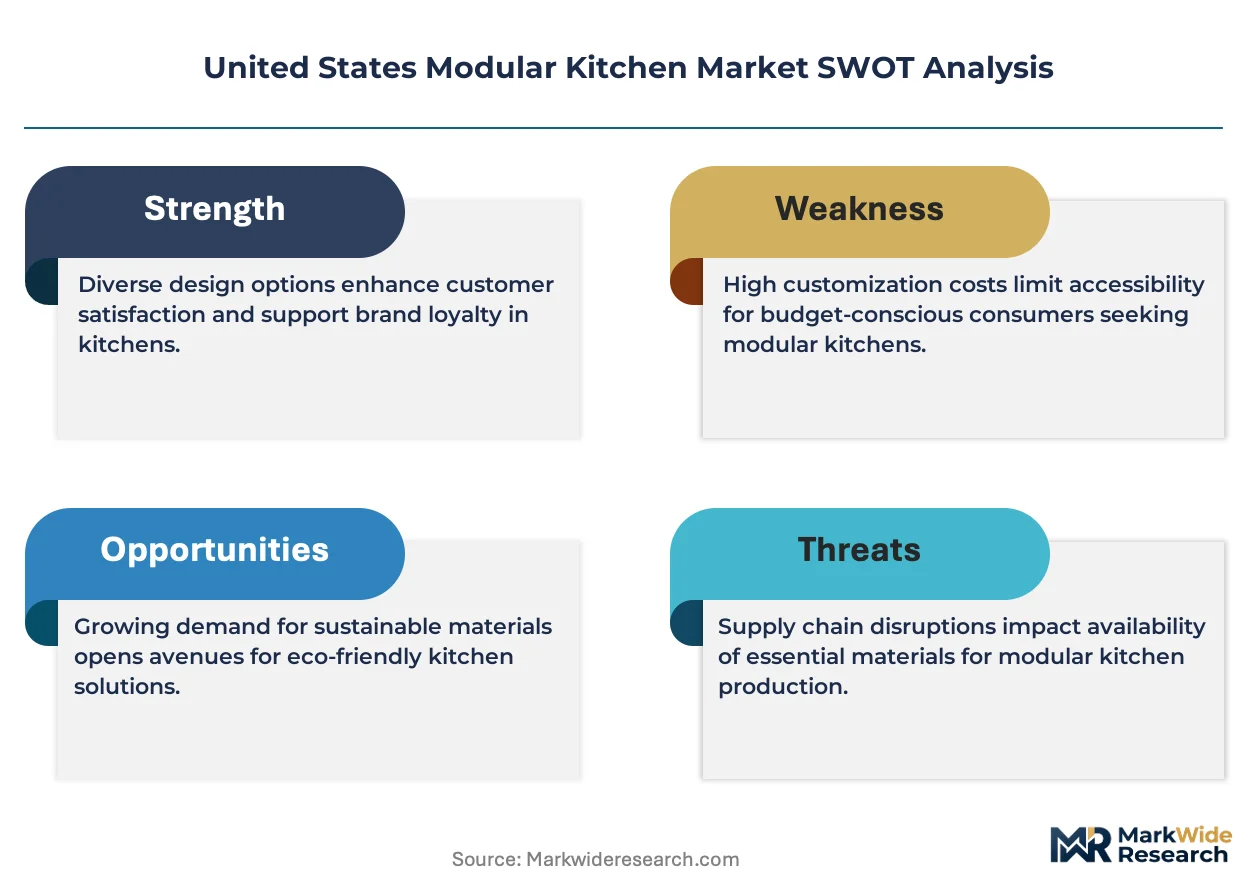
On the supply side, the industry is tiered across mass-market flat-pack distributors, mid-tier regional fabricators, and premium bespoke specialists. The vendor base separates into three strategic archetypes: logistics-scale players leveraging centralized distribution networks, craftsmanship-oriented ateliers emphasizing German and Italian design heritage, and hardware-centric suppliers differentiating on fitting ecosystems. Dominant competitive moves include backward integration into substrate processing to secure EPA compliance cost advantages, and strategic partnerships with production homebuilders to capture builder-direct procurement consolidation.
Within the premium craftsmanship tier, Eggersmann USA and Snaidero USA exemplify European-origin positioning that commands specification authority in high-end metropolitan markets. IKEA US occupies the mass-market archetype through flat-pack logistics networks that sustain price positioning across standardized product ranges. Häfele America Co. represents the hardware-specialist vector, anchoring competitive differentiation on fitting and accessory ecosystems that modular systems require for functional separation from conventional built-in alternatives.
| Leading Market Players |
|---|
| Lineadecor USA LLC |
| Eggersmann USA |
| IKEA US |
| Snaidero USA |
| Pedini USA |
| Häfele America Co. |
| Hettich America L.P. |
| Hacker Greenwich |
| Boston Cabinets Inc. |
| Others |
Value Network & Pricing Analysis
EPA TSCA Title VI formaldehyde compliance costs determine both pricing tier spreads and supply chain shape, forcing domestic fabricators to absorb ventilation upgrades while importers face exclusion from California distribution networks. Laminate substrate producers pass resin volatility through to mid-tier buyers, while solid wood specialists capture premium positioning through CARB Phase 2 certification.
Pricing Analysis
Production homebuilder buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on emission certification grade and customization depth, with CARB Phase 2 verified systems commanding substantial premiums over baseline EPA-compliant alternatives. Cost compression in the standard tier is intensifying because particleboard resin costs fluctuate with petrochemical feedstock availability. Renovation platforms and first-time buyers exhibit highest price sensitivity, whereas high-end metropolitan homeowners prioritize craftsmanship over unit economics.
Supply Chain Analysis
Particleboard and MDF feedstock draws from domestic timber processors in the Pacific Northwest and Southeast, with specialty hardware sourcing from Germany and Italy. Composite wood substrates hinge on resin chemistry tied to natural gas derivatives, while premium veneer supplies center on European sustainable forestry certifications. Single-source vulnerability concentrates in German hinge and drawer slide manufacturers serving high-end fabricators. Distribution runs through builder-direct procurement channels consolidating in Texas, Florida, and California metro corridors, bypassing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where installation, configuration, and extended warranty layers expand faster than cabinet hardware sales. Recurring revenue from smart kitchen ecosystem subscriptions and precision maintenance contracts outpaces unit shipment growth.
For Market Incumbents: Insulate margin pools by securing captive substrate processing capabilities ahead of OSHA formaldehyde exposure limit tightening. Backward integration into particleboard manufacturing secures EPA compliance cost advantages against import-dependent competitors. Channel control through exclusive production homebuilder partnerships in Arizona and Nevada defends against flat-pack logistics specialists displacing mid-tier positioning.
For New Entrants and Emerging Players: Pursue DIY and modular-ready format penetration in secondary Sun Belt markets where skilled installer scarcity constrains incumbent expansion. The most penetrable segment comprises first-time buyers in San Antonio and El Paso seeking moisture-resistant laminate systems with flat-pack delivery. A direct-to-renovator platform model bypasses dealer network establishment costs while capturing compressed replacement cycle demand.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fabricators with captive California distribution nodes. Long-term viability over the next decade rests on emission-compliant substrate control and builder-direct channel relationships. The acquisition target archetype combines regional manufacturing scale with EPA-certified processing capabilities. The signal to watch is Department of Energy appliance efficiency mandate timing, which will reshape specification requirements for integrated kitchen housing designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Processing | EPA TSCA Title VI compliance costs favor in-house particleboard production over import dependency. |
| Builder-Direct Procurement Partnerships | Production homebuilders in Texas and Florida consolidate specification authority away from dealer networks. |
| Smart Kitchen Ecosystem Development | Voice-activated hardware and sensor-driven inventory management digitize static cabinetry into dynamic infrastructure. |
| Flat-Pack Logistics Network Expansion | IKEA's distribution model opens access segments previously served only by custom installation channels. |
| Induction-Ready Cabinetry Configuration | State-level building electrification codes in Austin and progressive municipal jurisdictions create specification windows. |
Research Methodology
Initial hypotheses were tested against primary input from production homebuilder procurement directors, modular kitchen fabricator operations heads, certified installation contractors, and EPA compliance officers at composite wood processors, then refined through secondary validation. Primary fieldwork combined structured interviews with trade show reconnaissance at KBIS and IBS events. Secondary sources encompassed EPA TSCA Title VI filing databases, California Air Resources Board certification registries, Department of Energy appliance efficiency dockets, and SEC 10-K disclosures from publicly traded building products companies. Bottom-up shipment data triangulated against top-down housing start and renovation spend estimates.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled encompass installation type, material grade tier, end-user channel, and regional regulatory cluster intensity. CAGRs derived from historical trajectory analysis adjusted for regulatory pull-forward effects and channel compression dynamics. Industry-specific forecast inputs included production homebuilder adoption curves and EPA formaldehyde standard implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in mortgage rate trajectories and single-family housing permit volumes would shift the trajectory materially. Forecasts reflect documented assumptions regarding suburban renovation cycle compression and skilled labor availability constraints. Cross-checking against Census Bureau housing completion data and Harvard Joint Center for Housing Studies renovation expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
Kitchen Hand Tools Market