
 Online Home Decor Market | 2026-2036
Online Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
Online Home Decor Market Outlook
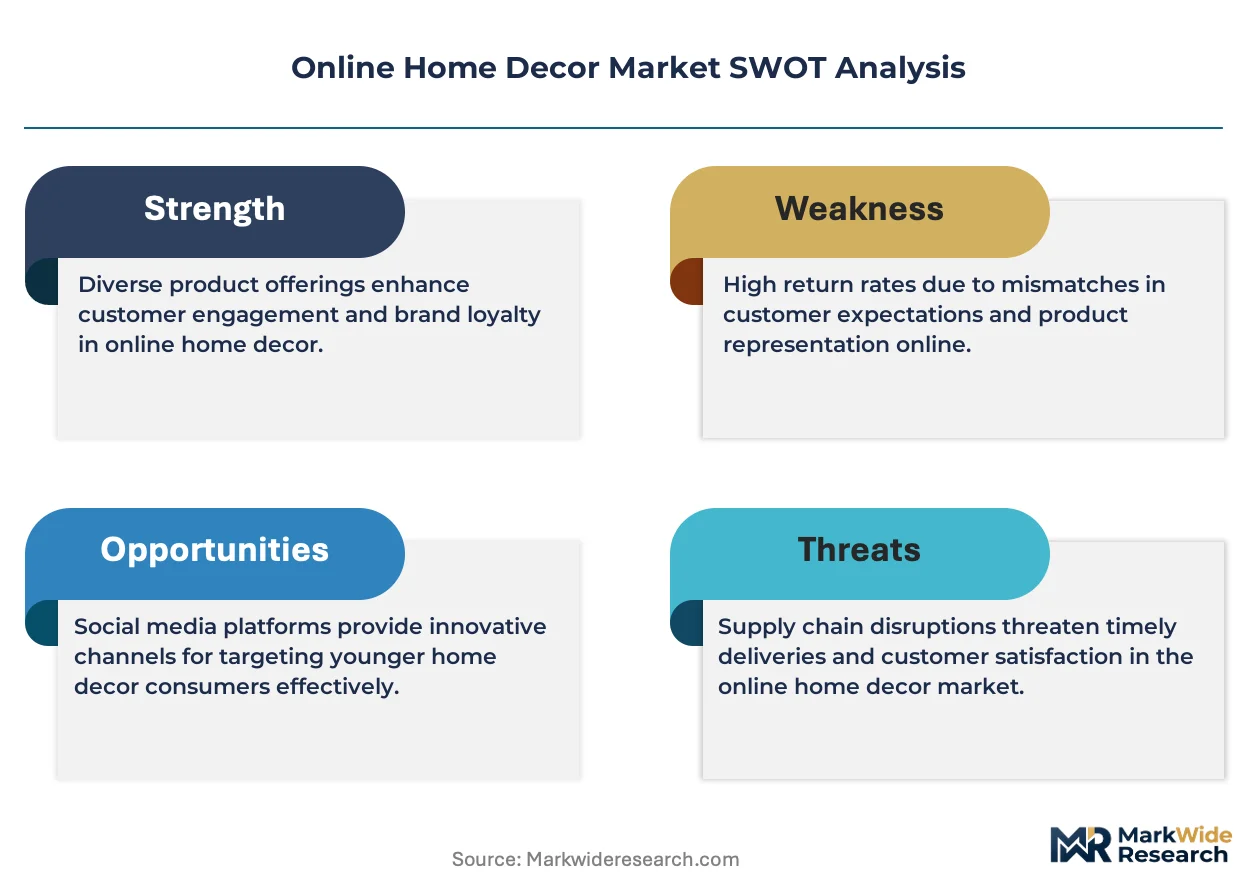
Generative AI visualization tools is rewriting how consumers preview furniture in spatial contexts before purchase. Wayfair Inc. leverages proprietary 3D rendering infrastructure to reduce return rates on bulky items. Amazon anchors marketplace dominance through logistics density and same-day delivery corridors in metropolitan zones. Inter IKEA Systems B.V. competes via flat-pack modularity that compresses last-mile costs while sustaining circular material flows.
Online home decor encompasses digitally retailed furnishings, lighting, textiles, and wall art designed for residential interior environments, typically specified by dimensions, material composition, and assembly requirements for direct-to-consumer shipment. The category serves both functional living needs and aesthetic personalization, with augmented reality compatibility now a baseline technical parameter for conversion optimization. Furniture commands the largest absolute revenue pool within product type segmentation, though wall art delivers superior margin density per unit shipped. Online marketplaces capture disproportionate traffic volume among distribution channels, while direct-to-consumer brands extract higher lifetime value through subscription styling services and repeat textile purchases.
The EU Green Deal and REACH chemical standards constrain textile and finish material sourcing for sellers accessing European consumers, while the US EPA formaldehyde emission regulations govern composite wood furniture imports. California's Proposition 65 labeling mandates create de facto national compliance benchmarks for warning disclosures on decorated glassware and coated metal fixtures. Stakeholders must monitor evolving extended producer responsibility frameworks across Germany, France, and the United Kingdom, as deposit and recycling fee structures threaten to erode price competitiveness for mass-market upholstery and lighting categories.
Market Dynamics
Generative AI visualization is compressing the purchase funnel for spatially complex categories, forcing retailers to rebuild conversion infrastructure around 3D asset pipelines rather than static photography.
Growth Catalysts
- EU Green Deal extended producer responsibility:Circular economy mandates are accelerating material traceability investments across upholstery and lighting supply chains, creating compliance-driven upgrade cycles.
- Suburban renovation cycles:United States homeowners are triggering replacement demand for furnishings as remote work persists and residential square footage utilization shifts.
- AR-enabled mobile commerce:Spatial computing capabilities embedded in iOS and Android ecosystems are reducing perceived risk in bulky furniture purchases without physical inspection.
Market Restraints
- Last-mile density economics:Bulky item delivery costs concentrate margin pressure on sellers without owned logistics networks or metropolitan fulfillment node density.
- REACH chemical compliance:ECHA substance restrictions on flame retardants and formaldehyde-releasing resins are constraining textile and composite wood sourcing options for European market access.
- Return rate asymmetry:Dimensional mismatches between digital previews and physical delivery generate disproportionate reverse logistics costs relative to unit economics.
Strategic Opportunities
- Subscription textile replenishment:Direct-to-consumer brands can capture recurring revenue through curated seasonal soft goods replacement programs.
- India urban housing stock:Metropolitan apartment construction in Mumbai and Bangalore is creating first-time buyer populations without established furniture ownership patterns.
- Digital product passport integration:EU Green Deal alignment offers positioning advantage for sellers embedding material provenance and end-of-life instructions into QR-linked metadata.
Industry Challenges
- 3D asset pipeline talent scarcity:Photogrammetry and real-time rendering specialists command premium compensation, constraining in-house visualization capability buildout.
- Multi-jurisdiction labeling harmonization:California Proposition 65 warning requirements diverge from EU CLP hazard communication standards, forcing SKU-level customization for cross-border listings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Home Decor Market |
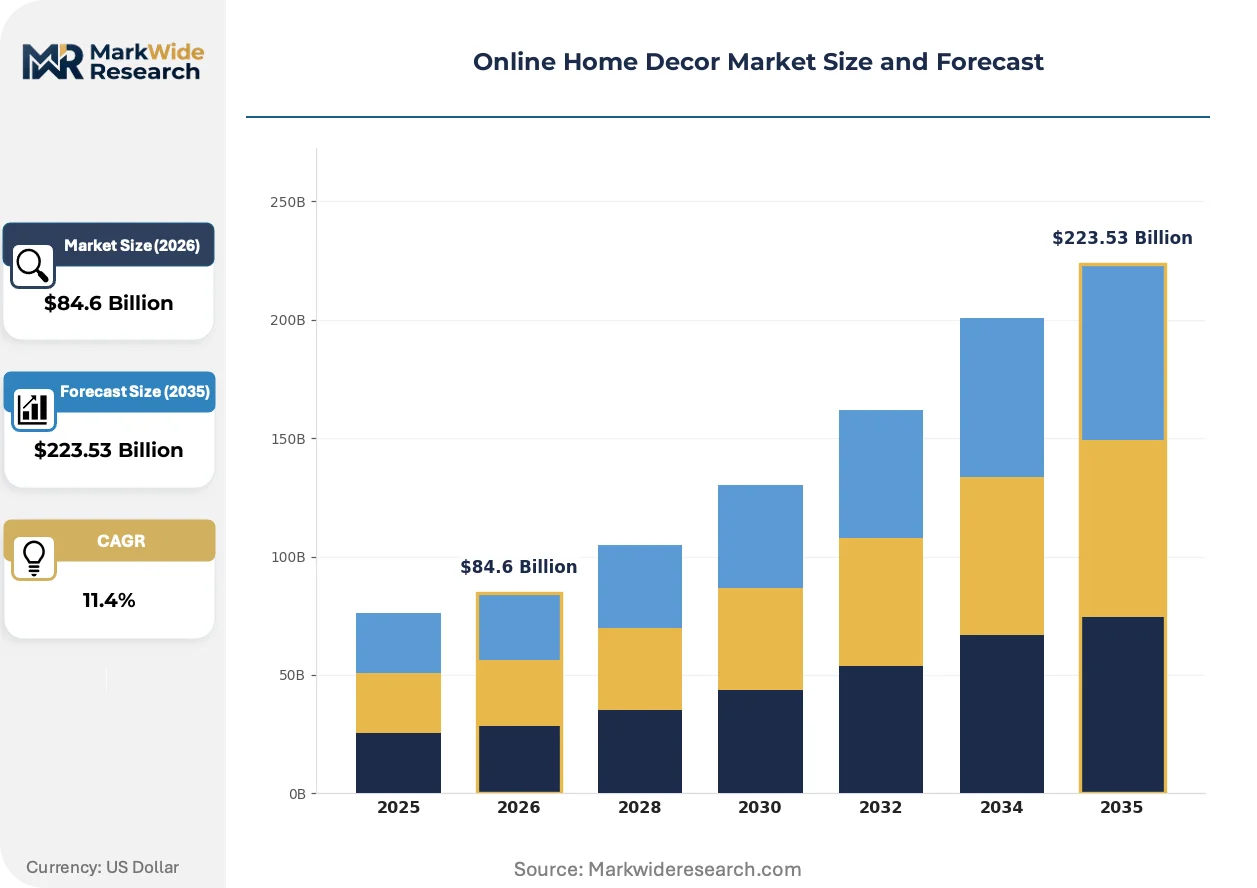
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $223.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Lighting, Wall Art, Textiles Customer Type: Homeowners, Renters, Interior Designers, Contractors Distribution Channel: Direct-to-Consumer, Online Marketplaces, Social Media, E-commerce Websites Style: Modern, Rustic, Minimalist, Vintage |
| Companies Covered | Wayfair Inc., Inter IKEA Systems B.V., Amazon, Williams-Sonoma Inc., Ashley Furniture Industries, The TJX Companies Inc., Overstock, Otto GmbH and Co. KG, Ethan Allen Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Home Decor Market Strategic Shifts
Spatial commerce infrastructure is converging with sustainability verification layers, creating new technical requirements for product data management and customer experience design.
Photorealistic 3D rendering is hybridizing static catalog photography with interactive configuration tools. Millennial and Gen Z buyers now expect real-time material swaps and dimensional scaling prior to checkout. This capability compression is collapsing the traditional inspiration-to-purchase timeline from weeks to single sessions.
REACH substance restriction expansions are forcing reformulation of upholstered furniture foams and textile finishes. Manufacturers serving European consumers must recertify supply chains against SVHC candidate list updates. Composite wood furniture imports face heightened scrutiny at Rotterdam and Hamburg port entries.
Rental and resale platform integration is fragmenting traditional ownership models. Urban consumers in London and Berlin increasingly treat furnishings as temporary service subscriptions rather than durable investments. This behavioral pivot pressures traditional retailers to build reverse logistics and refurbishment capabilities.
Online Home Decor Market Segmentation
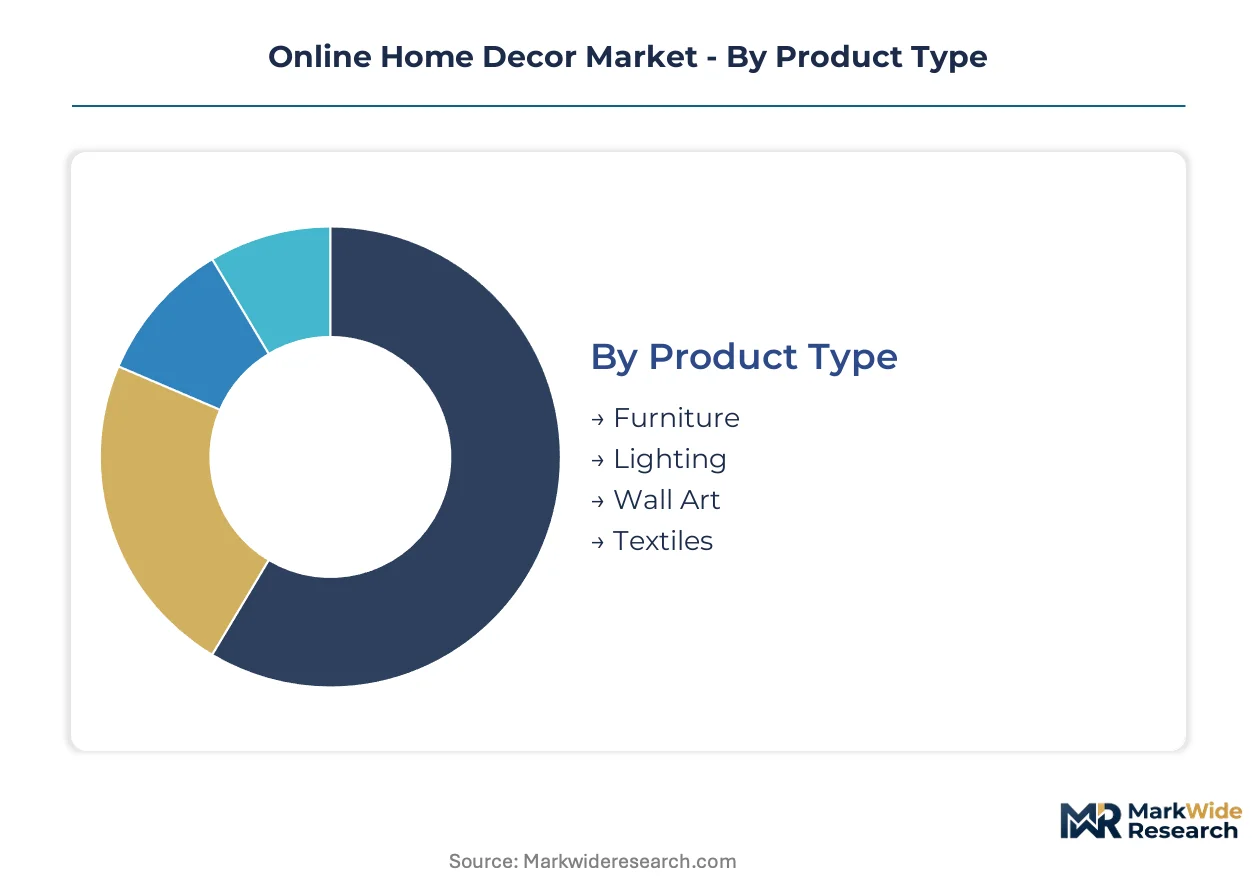
Segmentation in online home decor reveals how purchase behavior fragments across living situations, professional involvement, and aesthetic preferences. Understanding these divides matters because AR visualization investments, logistics infrastructure, and subscription service design must align with distinct decision-making rhythms and margin profiles.
Product Type:
Furniture anchors the highest absolute revenue pool while wall art delivers superior margin density per shipment, creating divergent investment priorities across fulfillment networks.
- Furniture:Encompasses seating, storage, and surface products specified by dimensional constraints and assembly complexity. Demand concentrates in United States suburban markets where remote work has triggered renovation cycles and room reconfiguration. Bulky item logistics and elevated return rates from dimensional mismatches compress net margins despite high ticket values.
- Lighting:Includes pendant, floor, and table fixtures with electrical certification requirements varying by destination jurisdiction. European demand is accelerating under EU Green Deal circular economy mandates that prioritize energy-efficient LED platforms and recyclable material construction. Extended producer responsibility frameworks threaten price competitiveness through deposit and recycling fee structures.
- Wall Art:Digitally retailed decorative pieces spanning prints, canvas, and sculptural formats with minimal dimensional risk in fulfillment. United States millennial and Gen Z homeowners drive discretionary spending toward curated digital-native collections.
- Textiles:Covers soft goods including rugs, curtains, and upholstery fabrics with seasonal refresh potential. Direct-to-consumer brands extract recurring revenue through subscription styling services and repeat purchase programs.
The dominant share belongs to Furniture, while Textiles is closing the gap fastest through subscription replenishment models.
Customer Type:
Cost tier differentiation separates one-time transactional buyers from relationship-driven professional channels with distinct lifetime value profiles.
- Homeowners:Permanent residents making durable investment decisions with extended replacement cycles. United States suburban renovation activity concentrates demand for full-room furnishing packages with AR-enabled preview expectations.
- Renters:Transitory residents prioritizing portability, modularity, and damage-free installation solutions. Urban clusters in London and Berlin increasingly treat furnishings as temporary service subscriptions rather than durable investments.
- Interior Designers:Professional specifiers managing multi-unit projects with volume pricing negotiations and white-glove delivery requirements. Procurement concentrates through direct-to-consumer brand partnerships bypassing traditional wholesale channels.
- Contractors:Construction professionals sourcing finish furnishings for new build and renovation projects with timeline-critical logistics needs. Metropolitan apartment construction in Mumbai and Bangalore creates first-time buyer populations without established furniture ownership patterns.
Homeowners command the largest absolute volume, though Interior Designers are expanding most quickly as direct-to-consumer brands build professional portal infrastructure.
Distribution Channel:
Volume concentration in marketplace platforms contrasts with margin capture in owned-channel relationships, reshaping customer acquisition economics.
- Direct-to-Consumer:Brand-controlled websites with full margin retention and first-party data accumulation. Wayfair Inc. and Inter IKEA Systems B.V. leverage proprietary infrastructure to reduce return rates and compress last-mile costs.
- Online Marketplaces:Aggregator platforms capturing disproportionate traffic volume through logistics density and same-day delivery corridors in metropolitan zones. Amazon anchors dominance through fulfillment network penetration.
- Social Media:Discovery-driven commerce embedded in content consumption flows with impulse purchase mechanics. Instagram and TikTok shopping integrations are rewriting how consumers preview furniture in spatial contexts before platform redirection.
- E-commerce Websites:Traditional multi-brand retailers with editorial curation and category breadth positioning. Generative AI visualization tools are forcing rebuild of conversion infrastructure around 3D asset pipelines rather than static photography.
Online Marketplaces hold the dominant traffic position, while Direct-to-Consumer channels are climbing the fastest as subscription services deepen retention.
Style:
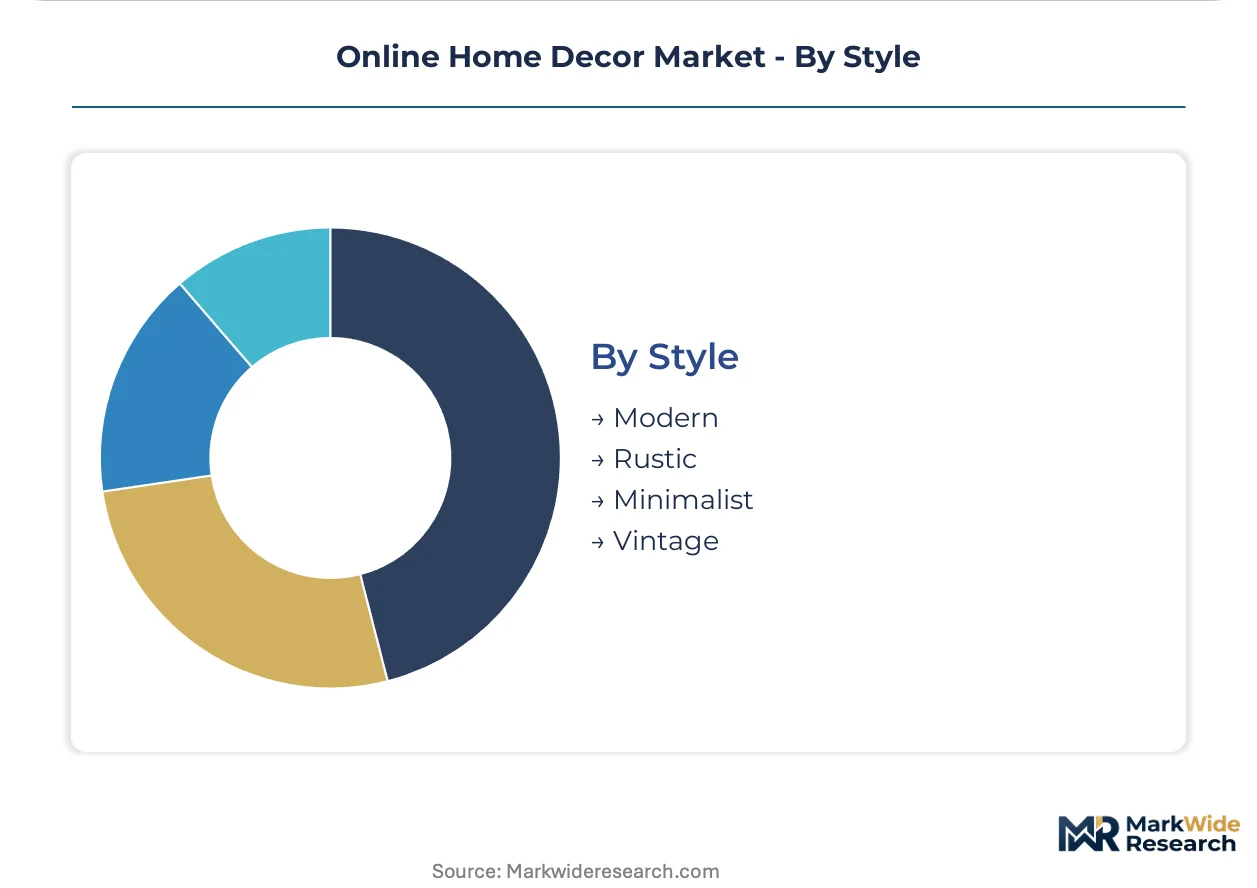
Customer type alignment with aesthetic movements determines inventory risk and markdown exposure across seasonal collection cycles.
- Modern:Clean-lined contemporary forms emphasizing material innovation and manufacturing precision. Millennial and Gen Z buyers expect real-time material swaps and dimensional scaling prior to checkout.
- Rustic:Weathered finishes and natural material emphasis with regional craft associations. Demand concentrates in United States exurban markets with farmhouse renovation aesthetics.
- Minimalist:Reduced form vocabulary prioritizing spatial efficiency and multifunctionality. Metropolitan apartment dwellers in India and European capitals drive specification for compact living solutions.
- Vintage:Period-referenced or authentic secondhand pieces with provenance storytelling. Rental and resale platform integration is fragmenting traditional ownership models and pressuring refurbishment capability buildout.
Modern styling retains the dominant share position, though Vintage is gaining share fastest through circular economy positioning and resale platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z homeowners in the United States drive the largest absolute demand concentration, while regulatory divergence between EU chemical standards and US state-level labeling mandates creates cross-border compliance complexity for sellers.
United States
Suburban renovation cycles and remote work-driven room reconfiguration sustain replacement demand for furnishings across metropolitan corridors. California's Proposition 65 labeling mandates create de facto national compliance benchmarks for warning disclosures on decorated glassware and coated metal fixtures. Wayfair Inc. leverages proprietary 3D rendering infrastructure in Boston to reduce return rates on bulky items.
Germany
Extended producer responsibility frameworks under the EU Green Deal accelerate material traceability investments across upholstery and lighting supply chains. ECHA substance restrictions on flame retardants and formaldehyde-releasing resins constrain textile and composite wood sourcing options for market access. Berlin and Hamburg anchor port entry scrutiny for furniture imports facing heightened compliance verification.
United Kingdom
Urban consumers in London increasingly treat furnishings as temporary service subscriptions rather than durable investments, fragmenting traditional ownership models. Evolving extended producer responsibility frameworks threaten price competitiveness through deposit and recycling fee structures for mass-market categories. Rental and resale platform integration pressures refurbishment capability buildout across metropolitan logistics networks.
India
Metropolitan apartment construction in Mumbai and Bangalore creates first-time buyer populations without established furniture ownership patterns. Bureau of Indian Standards certification requirements govern electrical safety for lighting fixtures and upholstered furniture fire resistance. Direct-to-consumer brands target contractor procurement relationships for timeline-critical new build and renovation projects.
France
Millennial discretionary spending concentrates in curated digital-native collections with AR-enabled preview expectations. ANSM and CNIL oversight intersects with product safety and data protection requirements for connected home devices and smart lighting platforms. Paris-based design studios drive aesthetic specification influence across EU cross-border e-commerce corridors.
Online Home Decor Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base fragments between logistics-anchored marketplaces, flat-pack modularity specialists, and direct-to-consumer styling services. Three archetypes dominate: platform aggregators with fulfillment density, modular systems manufacturers with circular material flows, and curated brands with subscription retention mechanics. Competitive moves concentrate on M&A for 3D asset pipeline capabilities and strategic partnerships for last-mile compression.
Within the platform-aggregator tier, Amazon anchors marketplace dominance through logistics density and same-day delivery corridors in metropolitan zones. Wayfair Inc. and Inter IKEA Systems B.V. occupy positions as direct-to-consumer infrastructure builders, with the former leveraging proprietary 3D rendering and the latter competing via flat-pack modularity that compresses last-mile costs. These three exemplify how channel control and product-system integration separate market positions.
| Leading Market Players |
|---|
| Wayfair Inc. |
| Inter IKEA Systems B.V. |
| Amazon |
| Williams-Sonoma Inc. |
| Ashley Furniture Industries |
| The TJX Companies Inc. |
| Overstock |
| Otto GmbH and Co. KG |
| Ethan Allen Global |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Vietnamese textile finishing capacity is compressing upholstery fabric pricing while simultaneously accelerating supplier consolidation toward vertically integrated mills with REACH certification capabilities.
Pricing Analysis
Cost-plus contracts with cotton futures indexation dominate raw material procurement for textile suppliers serving European markets. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels separates AR-enabled visualization bundles from static catalog offerings. Pricing pressure stems from last-mile density economics eroding margins on bulky furniture shipments to exurban United States markets. Contractors and new build developers exhibit highest price sensitivity due to timeline-critical procurement volumes, while interior designers demonstrate lowest sensitivity given project fee structures that absorb furnishing premiums.
Supply Chain Analysis
Upstream feedstock for engineered wood composites draws from Baltic birch veneer suppliers in Latvia and Estonia alongside medium-density fiberboard mills in Germany and Poland. Flame-retardant textile chemistry sources from specialty chemical producers in Switzerland and the Netherlands. Single-source vulnerability concentrates in LED driver chip supply from Taiwanese semiconductor foundries. Distribution runs through Rotterdam and Hamburg port hubs for European market access, with regional fulfillment nodes in Dallas and Chicago serving United States demand corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription textile replenishment services attach recurring revenue layers expanding faster than one-time furniture transactions, converting transactional buyers into multi-year relationship accounts with predictable cash flow profiles.
For Market Incumbents: Entrench market position through proprietary 3D asset pipeline acquisition and in-house photogrammetry capability buildout. Extend backward integration into certified sustainable textile mills to preempt REACH compliance disruption. Channel control through owned logistics networks defends against marketplace aggregator margin compression.
For New Entrants and Emerging Players: India's metropolitan apartment construction in secondary cities offers white-space penetration without established incumbent relationships. Berlin and London rental market service-subscription models present template for furniture-as-a-service launch. Direct-to-consumer styling algorithms paired with AR visualization deliver differentiated go-to-market positioning against catalog-era retailers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with subscription textile programs and professional interior designer portal infrastructure. Long-term viability across the analysis window favors acquisition targets with circular material flows and EU Green Deal digital passport integration. Monitor extended producer responsibility fee structure announcements across Germany, France, and the United Kingdom as inflection indicator for mass-market upholstery profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| 3D Asset Pipeline Acquisition | Photogrammetry specialists command premium compensation, constraining in-house visualization buildout for Wayfair-scale competitors. |
| Subscription Textile Launch | Seasonal soft goods replenishment captures recurring revenue and elevates lifetime value beyond one-time furniture transactions. |
| EU Digital Passport Integration | QR-linked material provenance metadata aligns with EU Green Deal mandates and positions premium sustainability credentials. |
| Professional Portal Development | Interior designer procurement relationships bypass wholesale channels and extract volume pricing with white-glove delivery terms. |
| Reverse Logistics Buildout | Rental and resale platform integration in London and Berlin requires refurbishment capabilities for circular economy participation. |
Study Parameters
A standing panel of e-commerce operations directors, 3D visualization pipeline managers, sustainable materials sourcing leads, and last-mile logistics coordinators provided ongoing calibration throughout the study period. Primary interviews with direct-to-consumer brand executives and marketplace platform category managers combined with secondary validation from SEC 10-K filings, customs trade data, and EU ECHA substance restriction databases. Bottom-up demand modeling across customer segments triangulated with top-down market sizing from retail audit data.
Scenario-bracketing around regulatory implementation timelines and AR adoption curves bounded volume projections across the modeling period. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and aesthetic style preference. CAGRs derived from regression analysis of historical growth patterns adjusted for technology diffusion rates and compliance-driven replacement cycles. Forecast inputs incorporated suburban renovation cycle intensity and EU extended producer responsibility fee structure evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Asian manufacturers or hyperscaler marketplace entrants would shift outcomes beyond modeled ranges. Cross-checking against Bureau of Indian Standards certification timelines and BIS upholstery fire resistance enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Smart Curtain Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
Window Covering Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Bookends Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Home Decor Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
Hearth Market
Homecare and Decor
Wall Decor Market