
 Serveware Market | 2026-2036
Serveware Market Size, Share, and Industry Trends Forecast 2026-2036
Serveware Market Intelligence
Customization services, offering bespoke designs and branding for hospitality clients, is consolidating the value proposition beyond physical products. This trend allows restaurants and hotels to create unique tabletop experiences that reinforce their brand identity. Steelite International USA leverages its extensive portfolio to serve large-scale hotel and restaurant chains with comprehensive solutions. Villeroy & Boch differentiates through its strong brand heritage and premium positioning, while Libbey Inc. competes on the basis of its wide distribution network and diverse glass and ceramic offerings.
Serveware encompasses vessels and utensils, including platters, bowls, and serving implements, used for the functional and aesthetic presentation of food. Technical specifications define the category, such as the vitrification of ceramics to ensure non-porosity or the use of 18/10 stainless steel for corrosion resistance. The ceramic material segment holds a significant market share, valued for its design flexibility and thermal properties. In terms of distribution, the online retail channel is reshaping procurement patterns previously dominated by specialty and home goods stores.
Regulations for food contact materials govern market access and product composition, creating a complex compliance landscape for manufacturers. In the United States, the FDA sets standards under its Food Contact Substance program. In Europe, Regulation (EC) No 1935/2004 and REACH compliance dictate material safety, particularly concerning heavy metals in glazes. Future competitive advantage depends on navigating these diverse international standards while innovating in sustainable materials and efficient manufacturing.
Market Dynamics
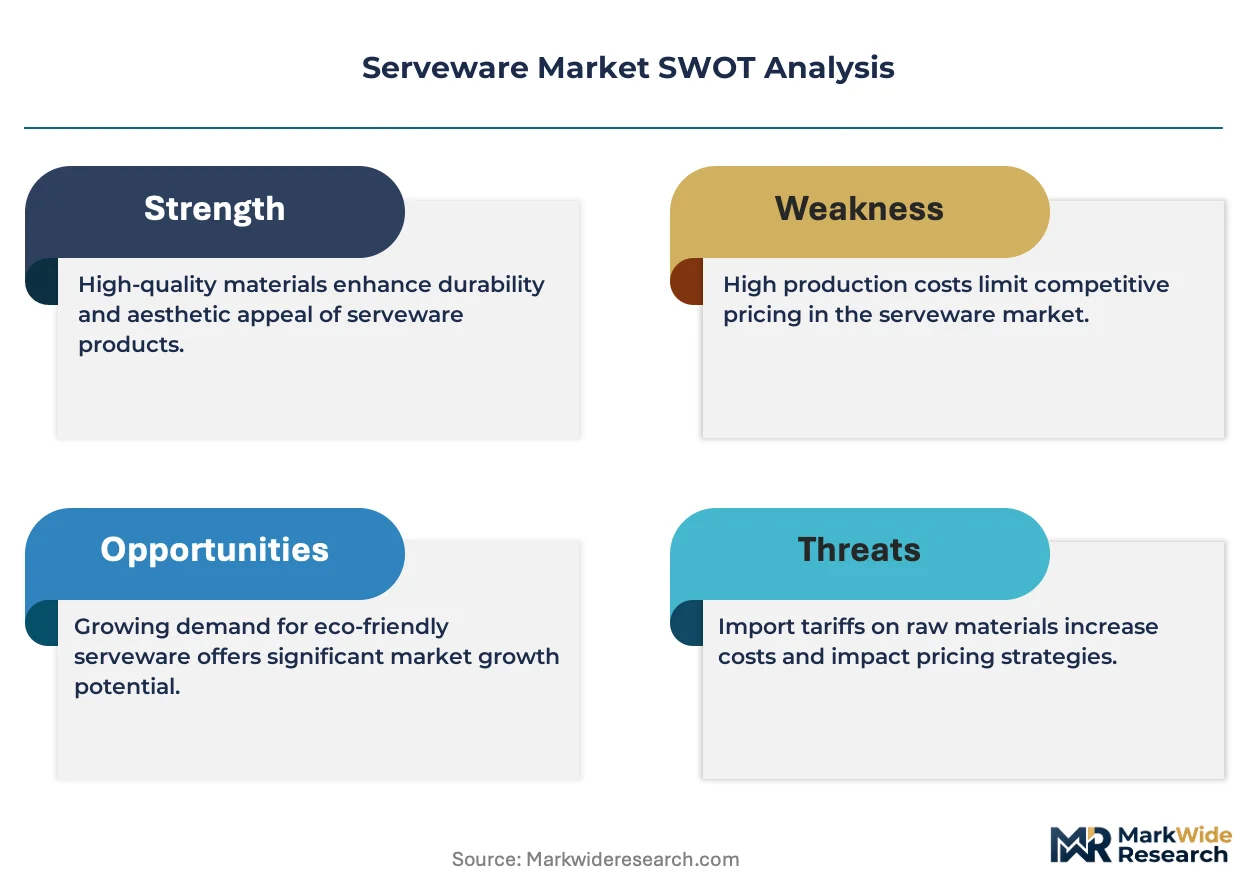
The serveware market is shaped by intense pressure from the premium hospitality sector to deliver unique dining experiences. This demand for aesthetic differentiation is the primary force driving innovation in materials, customization services, and product design.
Growth Catalysts
- Premium Hospitality Demand:Fine dining establishments and luxury hotels in cities like London and Tokyo drive demand for unique, aesthetically differentiated serveware as a competitive tool.
- Material Innovation:The development of durable and sustainable materials, particularly advanced ceramics and wood composites, opens new avenues for design and functional performance.
- Channel Evolution:The expansion of online B2B platforms is reshaping procurement, allowing direct sourcing and displacing traditional specialty and home goods store channels.
Market Restraints
- Raw Material Volatility:Price fluctuations for 18/10 stainless steel and specialized ceramic clays create margin pressure and complicate cost planning for manufacturers.
- Regulatory Complexity:Disparate food contact safety rules from the FDA and the EU's REACH framework create significant compliance overhead, slowing innovation.
- Substitution Pressure:Low-cost, mass-produced imports with less stringent safety compliance pose a constant threat to premium and mid-market segments.
Strategic Opportunities
- Emerging Hospitality Hubs:Rapid growth in tourism and luxury hospitality sectors in regions like the Middle East presents significant untapped geographic expansion opportunities for serveware suppliers.
- Customization as a Service:Offering bespoke design and branding services allows manufacturers to move beyond physical products, creating unique tabletop experiences for hospitality clients.
- Digital Prototyping:The convergence of digital design tools like CAD with artisanal production methods enables faster development and customization of complex forms.
Industry Challenges
- Sustainable Sourcing Logistics:Reconfiguring supply chains to accommodate new sustainable or locally sourced materials introduces significant logistical complexity and potential cost increases for manufacturers.
- Multi-Jurisdictional Compliance:Managing the distinct testing protocols and lengthy approval timelines for new materials under both FDA and REACH regulations is a major operational hurdle.
- Artisanal Skill Scarcity:A shortage of skilled artisans capable of producing unique, high-quality pieces at scale challenges the ability to fulfill large custom orders from hotel chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serveware Market |
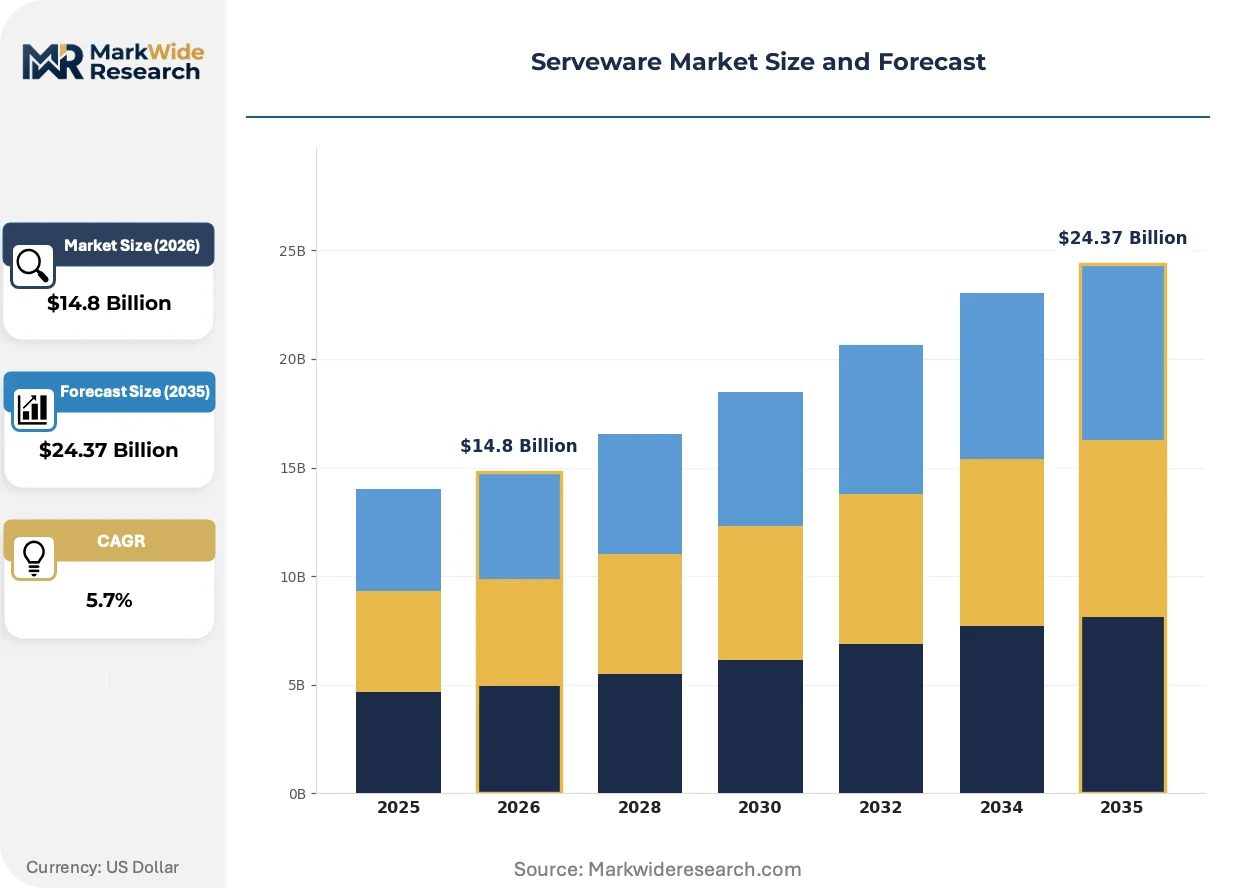
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Platters, Serving Utensils Material: Wood, Glass, Ceramic, Stainless Steel Design Style: Modern, Rustic, Traditional, Elegant Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Home Goods Stores |
| Companies Covered | Oneida Hospitality Group, Cardinal (Arc Cardinal USA), Libbey Inc., Front of the House, Tuxton China Inc., Villeroy & Boch, Steelite International USA, Denby Pottery, Le Creuset, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serveware Market Strategic Shifts & Innovations
Materiality and manufacturing agility define the competitive edge in serveware. The interplay of sustainable materials, digital fabrication, and stringent food safety regulations creates a more complex, value-added market landscape.
Digital fabrication technologies, including 3D printing for molds, enable rapid prototyping of bespoke serveware. Boutique hotels and independent fine-dining establishments are the primary adopters for creating signature pieces. This technology is decentralizing design capabilities away from large manufacturers, allowing smaller venues to compete on unique tabletop aesthetics.
European Union regulations, specifically REACH, impose stringent controls on heavy metals like lead and cadmium within ceramic glazes. This mandate forces manufacturers to invest in R&D for compliant formulations and extensive testing protocols. The ceramic serveware segment is most impacted, requiring costly reformulation to maintain access to the European market.
Collaborative procurement models are replacing transactional, volume-based purchasing within the hospitality sector. This shift sees hotel groups and restaurant chains engaging directly with manufacturers for co-developed, exclusive serveware collections, bypassing traditional distributors. This direct-sourcing trend is most advanced in luxury hospitality markets like Dubai and Singapore.
Serveware Market Segmentation
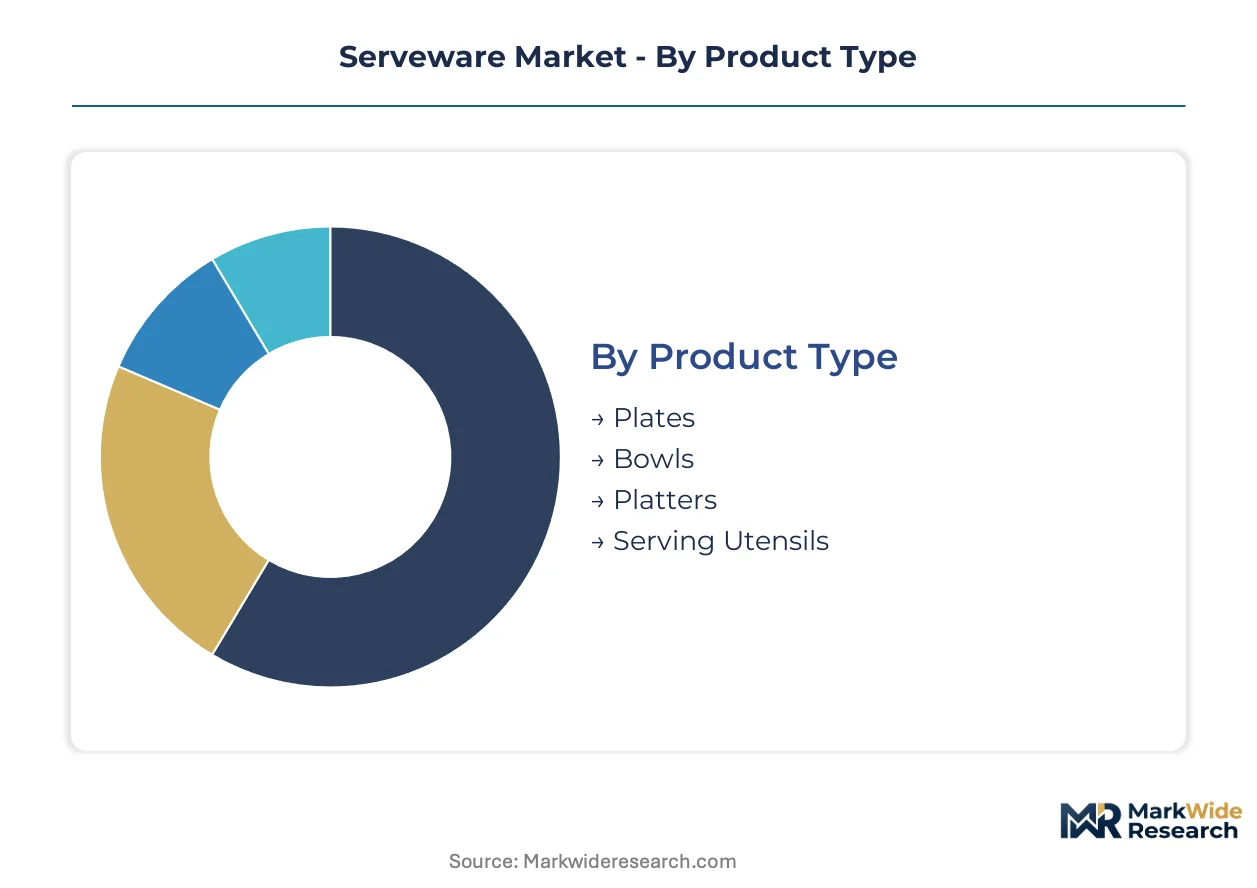
Serveware market segmentation provides a granular view of product types, materials, design aesthetics, and procurement channels. This detailed classification helps stakeholders understand specific demand drivers, competitive dynamics, and regulatory influences across diverse end-use applications.
Product Type:
The serveware market exhibits a spectrum from highly customized presentation pieces to standardized functional items across product types.
- Plates:Essential for individual food portions, these items feature technical specifications like rim design for sauces or flat surfaces for intricate plating. Demand concentrates in fine dining establishments in Tokyo, driven by precise culinary presentation.
- Bowls:Used for soups, salads, or side dishes, these vessels exhibit functional characteristics varying by depth and capacity.
- Platters:Designed for communal serving or buffet displays, the material choice for platters significantly impacts thermal retention and aesthetic appeal. Demand surges in luxury hotel banquet services in London, where visual impact is paramount.
- Serving Utensils:These implements include tongs, spoons, and ladles, with ergonomics and material durability being key design considerations.
Most installed capacity flows through Plates. Expansion is steepest in Platters.
Material:
Material selection in serveware is primarily driven by functional requirements and aesthetic preferences for different applications.
- Wood:This material offers a rustic aesthetic and is often used for breadboards or cheese platters. It requires specific care for longevity.
- Glass:Valued for transparency and versatility, glass is often used for beverage service or dessert presentation.
- Ceramic:Highly versatile, ceramic allows for diverse glazes and shapes; vitrification ensures non-porosity and thermal stability. Demand is high across premium hospitality in New York City, favoring bespoke designs.
- Stainless Steel:Chosen for durability, corrosion resistance, and hygienic properties, particularly 18/10 grade, this material is often used for buffet equipment and serving implements. Demand is consistent in high-volume catering operations, prioritizing longevity.
Ceramic materials hold significant market share due to design flexibility. Stainless steel is gaining traction in commercial kitchens for its resilience.
Design Style:
Serveware design styles cater to distinct aesthetic preferences and brand identities across various hospitality and home settings.
- Modern:Characterized by clean lines, minimalist forms, and often monochromatic palettes, this style is embraced by contemporary restaurants in Dubai seeking sleek, uncluttered presentations.
- Rustic:Featuring natural textures, earthy tones, and often handcrafted appearances, rustic designs appeal to farm-to-table concepts.
- Traditional:This style reflects classic patterns, intricate detailing, and formal aesthetics. It is preferred in heritage hotels.
- Elegant:Emphasizing sophisticated forms, refined finishes, and often subtle embellishments, elegant serveware is sought after by luxury fine dining venues in Singapore for a premium guest experience.
Modern designs are widely adopted across diverse settings. Elegant styles are experiencing accelerated growth in luxury hospitality segments.
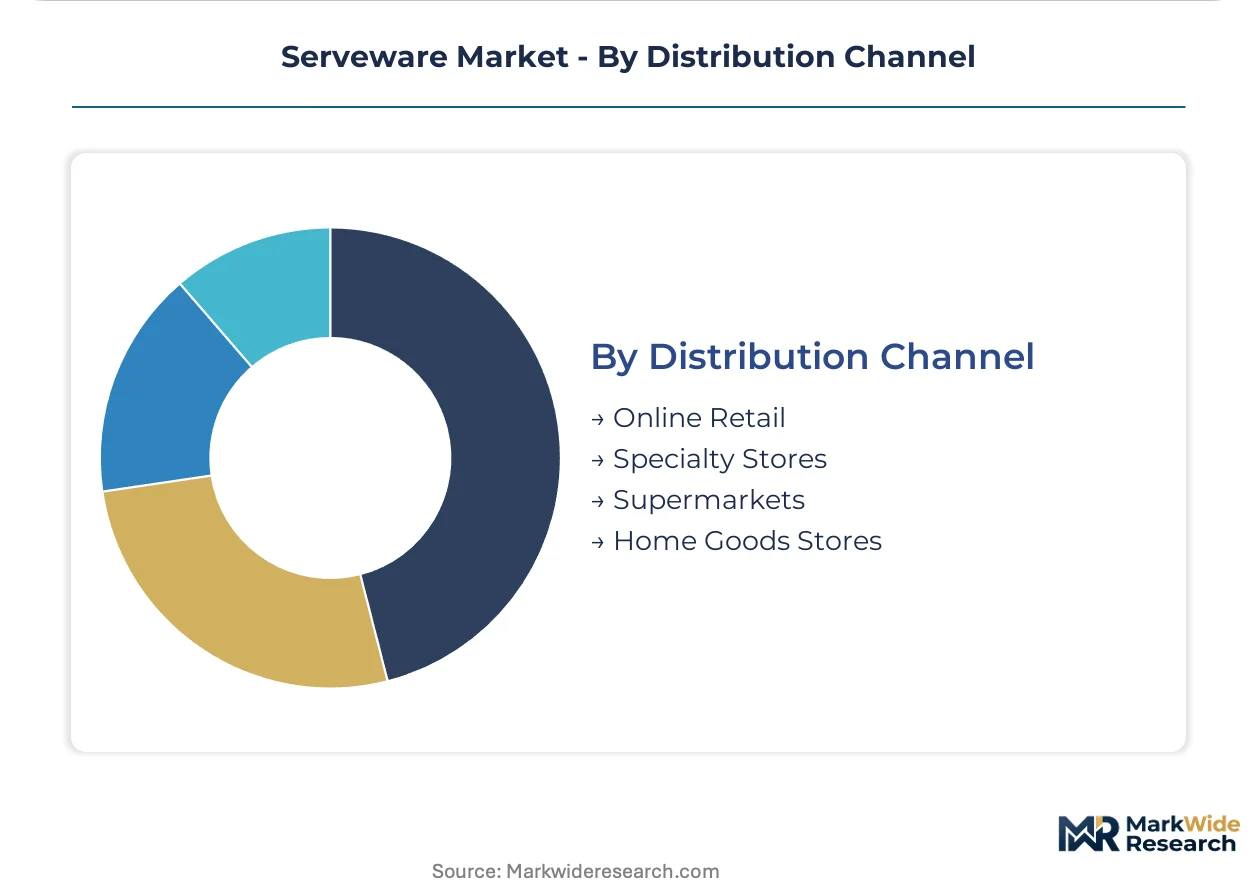
Distribution Channel:
The procurement landscape for serveware is undergoing significant transformation, influenced by digital platforms and evolving buyer preferences.
- Online Retail:This channel provides broad access to diverse products and competitive pricing, facilitating direct sourcing for smaller businesses and individual consumers. Its growth is reshaping procurement patterns for mid-sized hospitality groups.
- Specialty Stores:These establishments offer curated selections, expert advice, and a tactile shopping experience, catering to discerning buyers seeking unique or high-end items. They maintain relevance for bespoke design consultations.
- Supermarkets:These outlets focus on mass-market, affordable serveware options. They primarily serve everyday consumer needs.
- Home Goods Stores:Providing a wide array of serveware, often emphasizing interior design coordination, these stores cater to household consumers.
Online retail is expanding most quickly due to convenience and reach. Specialty stores continue to serve niche, premium markets with personalized service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Serveware market faces significant regulatory arbitrage, where manufacturing shifts to regions with less stringent food contact material compliance, creating cost-of-compliance gaps. This dynamic influences investment and production decisions for serveware manufacturers globally. Navigating diverse international standards like FDA and REACH is crucial for market access.
United States
Demand for bespoke ceramic designs from premium hospitality in New York City drives innovation. The FDA's Food Contact Substance program dictates material safety and market entry for serveware manufacturers. Major design and distribution hubs in Los Angeles and Chicago focus on efficient supply chains for diverse product types.
Germany
European demand for elegant serveware in luxury fine dining venues influences product development here. Regulation (EC) No 1935/2004 and REACH compliance mandate strict heavy metal limits in ceramic glazes. Production facilities in Bavaria specialize in high-quality porcelain and glass, serving both domestic and export markets.
Japan
Fine dining establishments in Tokyo drive demand for plates with precise culinary presentation. METI oversees industrial standards, including material specifications for serveware used in commercial settings. Artisanal ceramic workshops in Arita and Seto continue to innovate traditional forms for modern applications.
United Arab Emirates
Rapid growth in luxury hospitality in Dubai and Abu Dhabi creates demand for elegant serveware. The Emirates Authority for Standardization and Metrology (ESMA) sets food contact material safety standards. Strategic sourcing operations in Dubai manage imports and distribution across the Middle East for hotel groups.
China
High-volume catering operations and emerging premium hospitality drive demand for durable stainless steel and ceramic options. The GB standards for food contact materials regulate manufacturing processes and product composition. Major production centers in Jingdezhen and Chaozhou focus on ceramic serveware for global export and domestic markets.
Serveware Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting a tiered market structure. The serveware market exhibits consolidation in premium segments but remains fragmented at the lower end, driven by diverse material and design needs across hospitality and retail. Key strategic archetypes include global brand leaders, specialized material innovators, and high-volume OEM producers. Companies pursue portfolio diversification, strategic partnerships, and targeted geographic expansion to enhance market reach and product offerings.
Within the premium and mid-market segments, Villeroy & Boch, a German-based AG, exemplifies strong brand heritage and premium positioning, focusing on design and craftsmanship for discerning hospitality clients. Libbey Inc., an American Inc., occupies a position as a broad distributor with a wide array of glass and ceramic offerings, emphasizing market reach and diverse product lines across various price points. Steelite International USA, an American entity, represents a comprehensive solution provider for large-scale hotel and restaurant chains, leveraging an extensive product portfolio and bespoke customization services. These entities collectively highlight the varied approaches to serving the global serveware market.
| Leading Market Players |
|---|
| Oneida Hospitality Group |
| Cardinal (Arc Cardinal USA) |
| Libbey Inc. |
| Front of the House |
| Tuxton China Inc. |
| Villeroy & Boch |
| Steelite International USA |
| Denby Pottery |
| Le Creuset |
| Others |
Cost & Logistics Intelligence
Premium hospitality demand for bespoke designs and customization services forces serveware manufacturers to invest in flexible production, directly influencing their pricing models. This dynamic shifts value from commodity products to tailored solutions.
Pricing Analysis
Distributor margins significantly influence final serveware pricing for mid-sized hospitality groups. The market primarily uses a contract-based pricing model for large hotel chains, with transactional sales dominating smaller buyers. Price differentiation stems from customization levels and specific material grades, such as vitrified ceramic quality. Pricing softness reflects intense substitution pressure from mass-produced imports. Luxury hospitality clients exhibit the lowest price sensitivity.
Supply Chain Analysis
Direct-to-client engagements for co-developed collections are increasingly prevalent, bypassing traditional distributors for luxury hospitality. Supply concentrates in China for high-volume ceramic and stainless steel production, while Germany specializes in high-quality porcelain and glass. The industry relies on specialized ceramic clays and specific 18/10 stainless steel grades. Raw material price volatility for these inputs presents a significant structural supply chain risk, impacting cost planning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The serveware market presents a clear margin-expansion story, driven by premium hospitality demand for elegant and bespoke designs. This shift towards higher-value custom solutions enables manufacturers to capture greater profitability.
For Market Incumbents: Deploy digital prototyping capabilities to accelerate bespoke design delivery for hospitality clients. Incumbents should expand customization services to deepen client relationships, countering substitution pressure from low-cost imports. Investing in multi-jurisdictional compliance expertise for FDA and REACH regulations mitigates market access risks. Prioritize R&D in sustainable materials like advanced ceramics to meet evolving buyer preferences and secure long-term competitive advantage.
For New Entrants and Emerging Players: Launch direct-to-client online platforms to target boutique hotels and independent fine-dining establishments. These players seek signature pieces and unique tabletop aesthetics. Focus on emerging hospitality hubs in the Middle East, leveraging digital fabrication for rapid prototyping and customization. A go-to-market angle emphasizing artisanal quality with modern production offers a strong differentiation point.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists possessing strong customization capabilities. Serveware demand remains robust across the next decade, driven by global hospitality expansion. Investors should target companies with established brand heritage and intellectual property in sustainable materials or advanced manufacturing processes. The signal to watch is increased M&A activity within sustainable material startups, indicating broader industry consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Ceramics | Meets growing demand for durable, aesthetically flexible serveware from premium hospitality. |
| Digital Design Platform Integration | Accelerates bespoke product development and reduces time-to-market for custom orders. |
| Strategic Partnership with Hospitality Chains | Secures long-term procurement contracts and fosters co-developed exclusive collections. |
| R&D Investment in Wood Composites | Addresses demand for sustainable materials while offering unique rustic design aesthetics. |
| Multi-Jurisdictional Regulatory Compliance | Ensures market access across major regions like the EU and US, mitigating trade barriers. |
Research Approach
Bottom-up hospitality sector modeling reconciled against top-down serveware manufacturer tracking forms the analytical core of this study. The approach combines primary interviews with industry stakeholders and secondary validation. Key primary participants included procurement managers at luxury hotels, R&D directors at ceramic manufacturers, and supply chain leads for major distributors. Secondary data sources comprised FDA filings, REACH compliance documents, customs trade data, and company annual reports.
Historical trendline analysis and market sizing across the modeling period informed the forecast framework. The study modeled segmentation dimensions including product type, material, design style, and distribution channel, alongside regional demand. Compound annual growth rates were derived through a robust statistical analysis of historical and projected data. Key industry-specific forecast inputs included luxury hotel construction pipelines and fine-dining establishment opening rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical instability or major raw material disruptions. Forecasts reflect assumptions concerning raw material price stability and consistent regulatory enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Accent Tables Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market