
 North America Kitchen Furniture Market | 2026-2036
North America Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Kitchen Furniture Market Analytics
Project finance for build-to-rent multifamily developments is tilting procurement power toward institutional buyers with centralized kitchen specification authority. MasterBrand Cabinets leverages its captive manufacturing footprint to sustain margin control across mid-market cabinet lines. Ashley Furniture Industries anchors its position through vertical integration into domestic upholstery and casegoods production. IKEA competes on global sourcing scale and flat-pack logistics density in suburban retail corridors.
North America kitchen furniture encompasses fixed and movable storage, work surface, and seating systems designed for food preparation and dining environments, typically fabricated from engineered wood substrates, solid lumber, or synthetic composites with moisture-resistant finishes and hardware rated for cyclic loading. Cabinets dominate product-type value pools due to their structural role in kitchen layouts and high replacement frequency during renovations. Wood materials command premium positioning in custom and semi-custom channels, while metal and plastic gain traction in commercial and hospitality end-use segments where durability standards exceed residential thresholds. Modern and industrial styles are expanding fastest among urban condominium buyers and food-service operators seeking streamlined maintenance protocols.
The EPA enforces TSCA Title VI formaldehyde limits on composite wood substrates, pushing manufacturers toward CARB Phase 2-compliant resins and third-party certification chains. The US Consumer Product Safety Commission monitors tip-over hazards for freestanding storage units, influencing anchoring hardware design and installation service bundling. Stakeholders must monitor how California's evolving indoor air quality standards propagate into neighboring state building codes and retailer procurement mandates.
Market Dynamics
Build-to-rent multifamily capital deployment is compressing kitchen specification cycles and concentrating procurement authority among institutional asset managers who demand CARB Phase 2-compliant substrates at volume price points.
Growth Catalysts
- TSCA Title VI formaldehyde limits:EPA enforcement is pushing composite wood manufacturers toward low-emission resins, creating upgrade demand across replacement cabinetry cycles.
- Texas and Florida housing corridors:Metro markets in these states are outpacing national construction averages, pulling specification volume into Sun Belt distribution nodes.
- Moisture-resistant thermally fused laminate:This surfacing technology is penetrating rental-unit specifications where durability requirements exceed residential renovation standards.
Market Restraints
- Hardwood lumber input volatility:Solid wood cabinet door production faces price instability from Canadian softwood tariff exposure and domestic sawmill capacity constraints.
- Asian melamine substrate concentration:Decorative overlay supply chains cluster in Chinese and Vietnamese manufacturing zones, creating single-source vulnerability for North American fabricators.
- Legacy particleboard density limitations:Standard-grade substrates fail screw-holding tests required for soft-close hardware in high-cycle commercial installations.
Strategic Opportunities
- Mexico nearshoring corridors:Cabinet component fabrication is migrating to Baja California and Chihuahua to compress lead times for US Southwest distribution.
- California indoor air quality mandates:AB 685 disclosure requirements are propagating into retailer procurement specifications across neighboring state markets.
- Digital-to-physical kitchen planning tools:Augmented reality visualization is converging with automated cut-list generation to reduce remeasurement errors in custom cabinet orders.
Industry Challenges
- CNC programming talent scarcity:Nested-based manufacturing lines require operators fluent in cabinet-specific CAD/CAM workflows that vocational programs undersupply.
- CARB Phase 2 certification lag:Third-party laboratory testing creates six-to-eight-week approval bottlenecks for new substrate formulations entering California distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Kitchen Furniture Market |
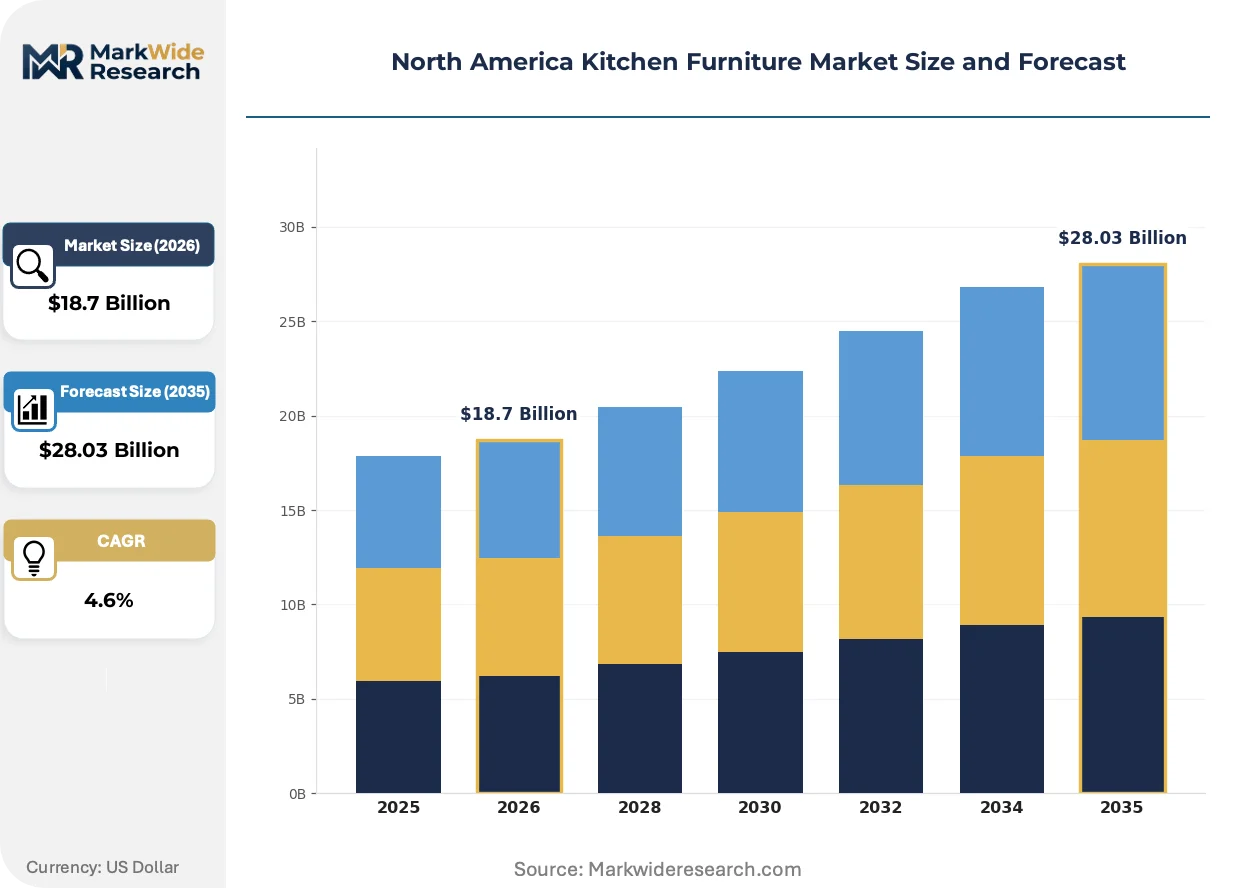
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Tables, Chairs Material: Wood, Metal, Plastic, Glass Style: Modern, Traditional, Rustic, Industrial End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | IKEA, Ashley Furniture Industries, American Woodmark, Steelcase, MasterBrand Cabinets, Maiden Home, Vermont Wood Studios, Howdens Joinery, Eastvold Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Kitchen Furniture Market Evolving Landscape
Material science advances and regulatory emission protocols are compressing traditional grade hierarchies while digital specification tools reshape how developers visualize kitchen systems before breaking ground.
Thermally fused melamine is hybridizing with high-pressure laminate edgebanding to deliver commercial-grade abrasion resistance at price points competitive with painted MDF in multifamily specifications. Institutional buyers in Texas build-to-rent projects are specifying these hybrid surfaces for unit-turn durability. The technology is hybridizing cost structures across mid-market and premium cabinet lines that previously separated by material grade alone.
EPA TSCA Title VI third-party certification requirements are forcing substrate mills to maintain chain-of-custody documentation from resin formulation through finished panel. Manufacturers serving California distribution must additionally satisfy CARB Phase 2 testing protocols that exceed federal baselines. Composite wood producers are responding by consolidating supplier relationships around certified resin systems to reduce audit burden.
Asset managers are centralizing kitchen specification authority through master service agreements that bundle design, material selection, and installation into single-source contracts. This procurement concentration is displacing traditional fragmented bidding where general contractors sourced cabinets through regional distributors. The shift is most visible in Florida and Arizona metro corridors where institutional multifamily ownership dominates new supply.
North America Kitchen Furniture Market Segmentation
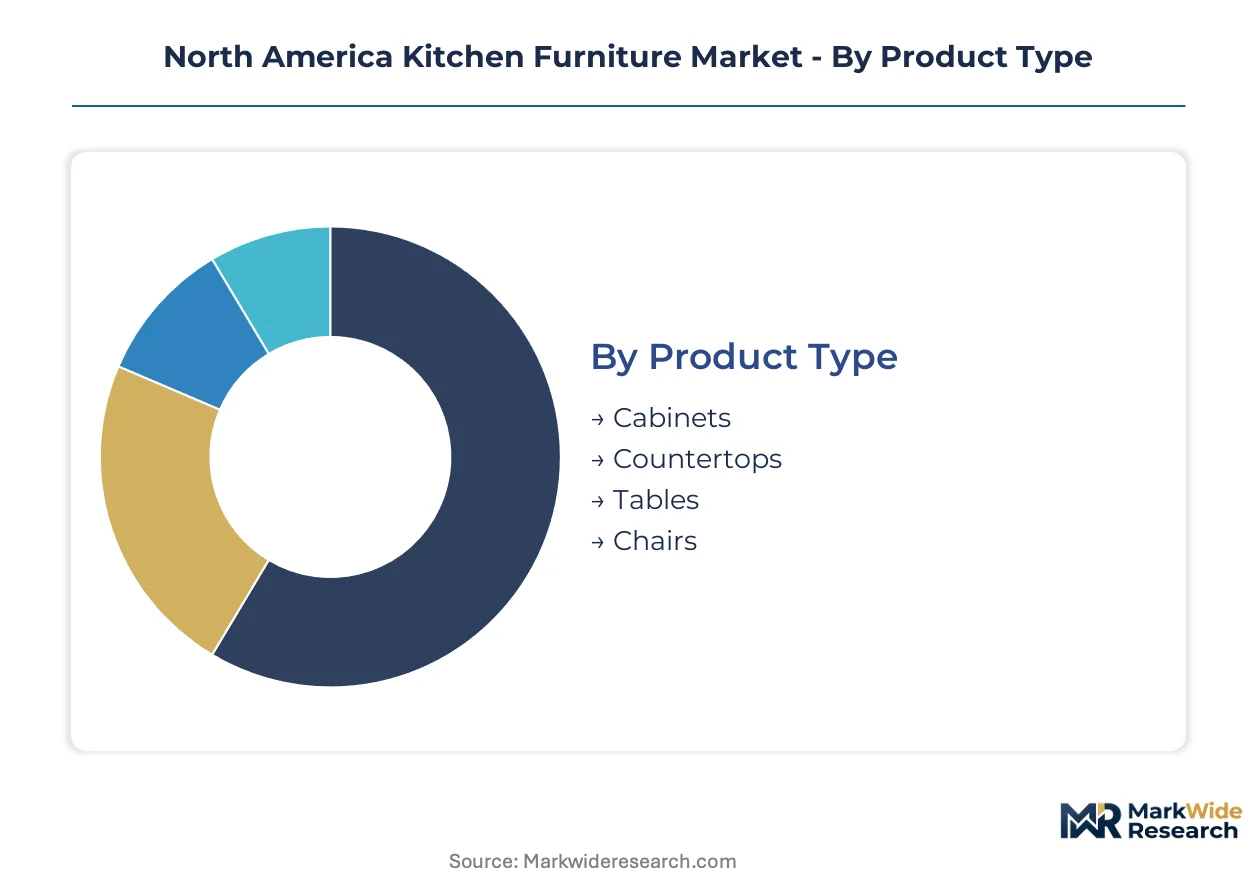
Kitchen furniture procurement splits sharply between institutional buyers with centralized specification authority and fragmented residential renovation demand. Material-grade hierarchies and style positioning determine margin capture across these divergent customer workflows.
Product Type:
Mature categories dominate revenue concentration while emerging formats reshape installation economics.
- Cabinets:Engineered wood substrates with moisture-resistant thermally fused laminate surfacing form the structural core of kitchen layouts. Texas and Florida multifamily developers are specifying CARB Phase 2-compliant cabinetry in build-to-rent volumes where unit-turn durability outweighs first-cost sensitivity.
- Countertops:Quartz and solid-surface materials are displacing laminate in mid-market renovation specifications. Demand concentrates in Sun Belt metro corridors where housing starts outpace national averages and developers prioritize low-maintenance surface protocols.
- Tables:Pedestal and trestle bases with engineered wood tops serve open-concept kitchen-dining hybrids.
- Chairs:Upholstered seating and metal-frame stools complete dining configurations for residential and hospitality end-uses.
Cabinets handle the majority of throughput; countertops are gaining share fastest on material substitution trends.
Material:
Cost-tier stratification separates premium custom channels from volume production lines.
- Wood:Solid lumber and engineered substrates including MDF, particleboard, and plywood with decorative overlays command specification in custom and semi-custom cabinet channels. EPA TSCA Title VI enforcement is pushing mills toward low-emission resin systems that add cost but satisfy California AB 685 disclosure requirements propagating into neighboring state codes.
- Metal:Powder-coated steel and aluminum framing penetrates commercial and hospitality segments where durability standards exceed residential thresholds. Food-service operators in urban condominium markets specify metal components for streamlined maintenance protocols.
- Plastic:Polypropylene and ABS components serve outdoor kitchen and utility applications.
- Glass:Tempered and laminated panels accent cabinet door inserts and shelving systems.
Wood commands the premium tier on customization flexibility; metal is expanding most quickly in commercial specification.
Style:
Volume distribution tracks geographic housing stock age and buyer demographic composition.
- Modern:Flat-panel doors with minimal ornamentation and integrated hardware dominate urban condominium renovations. Florida and Arizona institutional multifamily buyers specify modern styling for unit-turn efficiency and broad tenant appeal.
- Traditional:Raised-panel doors with decorative molding retain strength in suburban single-family replacement cycles.
- Rustic:Distressed finishes and reclaimed-wood aesthetics serve vacation property and secondary-home markets.
- Industrial:Exposed hardware and mixed-material construction gains traction among food-service operators and loft-style residential conversions.
Modern styling leads specification volume in new construction; industrial is climbing fastest on hospitality and adaptive-reuse demand.
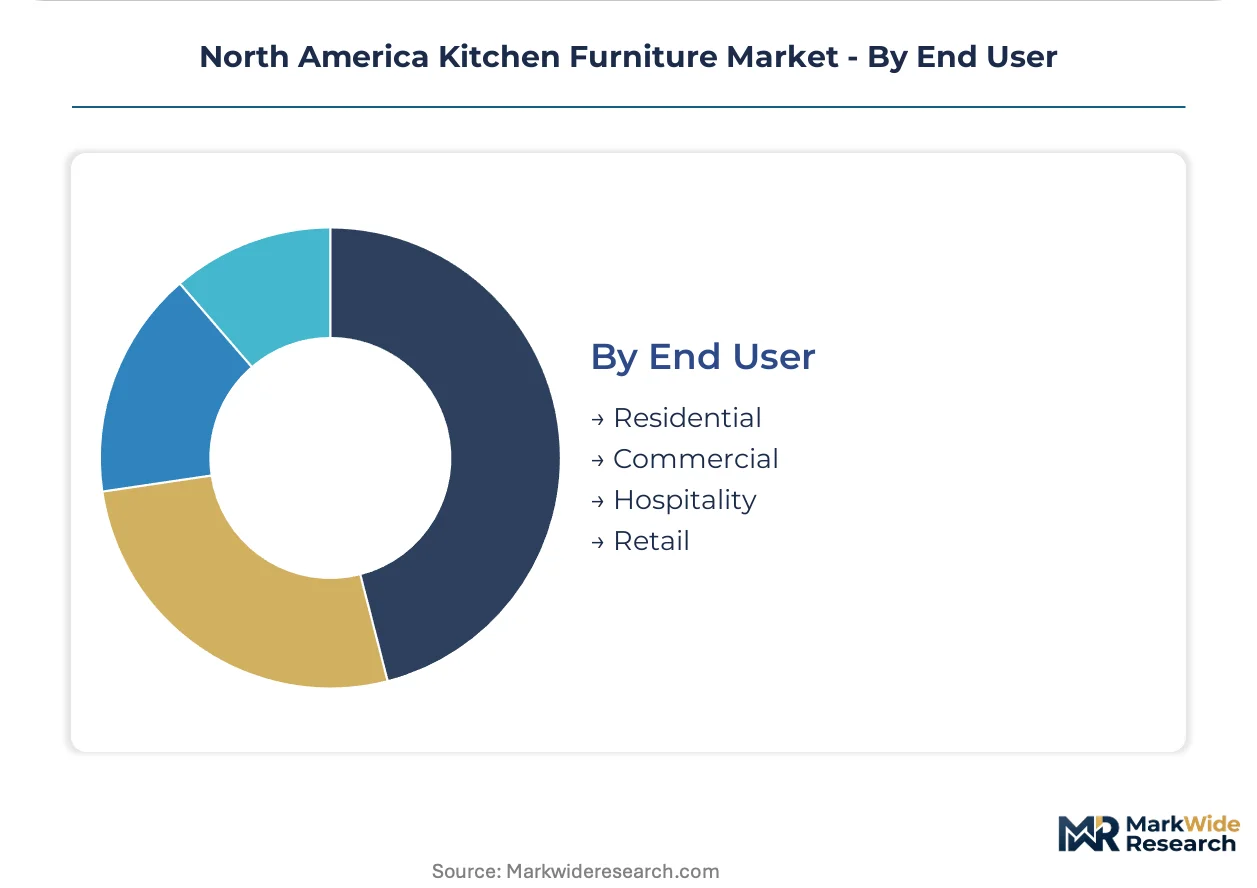
End User:
Customer-type concentration determines procurement channel structure and margin pressure.
- Residential:Single-family renovation and new construction accounts drive the majority of cabinet replacement cycles. Fragmented demand flows through kitchen design studios, home centers, and direct-to-builder supply agreements.
- Commercial:Corporate cafeteria and food-service installations specify abrasion-resistant surfacing and high-cycle hardware. Institutional buyers centralize procurement through master service agreements that bundle design, material selection, and installation.
- Hospitality:Hotel and extended-stay properties require rapid-turn durability and standardized replacement parts.
- Retail:Restaurant chains and food retail environments demand compliance with health department protocols and slip-resistant flooring integration.
Residential absorbs the greatest absolute volume; commercial is the steepest expansion trajectory on build-to-rent capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American kitchen furniture trade flows reflect a regional manufacturing ecosystem where US import dependence for decorative overlays contrasts with Mexican nearshoring momentum and Canadian softwood supply exposure.
United States
Texas and Florida metro corridors are outpacing national housing starts, pulling specification volume toward Sun Belt distribution nodes. EPA TSCA Title VI enforcement is pushing domestic mills toward CARB Phase 2-compliant resin systems that add cost but satisfy California AB 685 disclosure requirements propagating into neighboring state codes. Dallas-Fort Worth and Miami-Dade industrial clusters are consolidating fabrication capacity to serve institutional multifamily buyers.
Canada
Canadian softwood lumber exports face tariff exposure that transmits price volatility into US cabinet door production. Health Canada and PMRA coordinate with EPA on formaldehyde emission standards, creating regulatory alignment that smooths cross-border substrate trade. British Columbia sawmill capacity constraints are compressing supply availability for premium solid wood channels.
Mexico
Baja California and Chihuahua manufacturing corridors are attracting cabinet component fabrication to compress lead times for US Southwest distribution. Mexican labor cost advantages and USMCA tariff treatment are accelerating migration of thermally fused laminate pressing operations. Tijuana and Ciudad Juárez industrial parks are expanding dedicated kitchen furniture zones.
North America Kitchen Furniture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base splits between consolidated institutional suppliers with master service agreement scale and fragmented regional fabricators serving renovation demand. Three archetypes dominate: captive manufacturers with backward integration into substrate production, global retailers leveraging flat-pack logistics density, and specialist studios commanding premium custom channels. Competitive moves center on Mexico nearshoring capacity expansion and digital-to-physical specification tool deployment.
Among US-based fabricators, MasterBrand Cabinets and American Woodmark occupy positions within the institutional supply tier, while IKEA exemplifies global sourcing scale. These anchors represent divergent margin architectures: captive manufacturing control versus logistics network density.
| Leading Market Players |
|---|
| IKEA |
| Ashley Furniture Industries |
| American Woodmark |
| Steelcase |
| MasterBrand Cabinets |
| Maiden Home |
| Vermont Wood Studios |
| Howdens Joinery |
| Eastvold Furniture |
| Others |
Value Network & Pricing Analysis
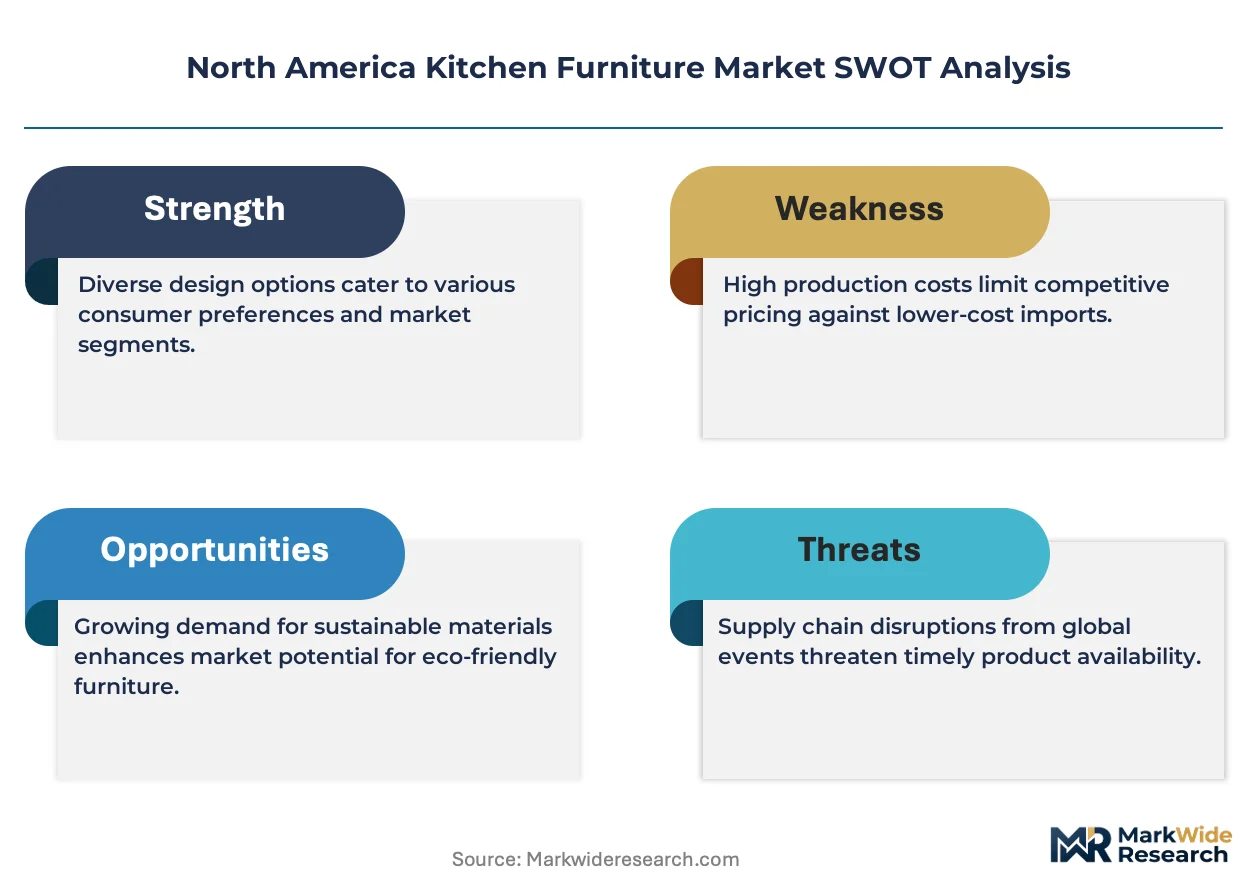
Overcapacity in Chinese melamine substrate pressing is compressing margin recovery for North American cabinet fabricators while simultaneously amplifying buyer leverage on volume contracts. This utilization imbalance forces domestic mills to absorb resin certification costs without full pass-through, tightening working capital cycles across CARB Phase 2-compliant supply tiers.
Pricing Analysis
Institutional OEM buyers anchor pricing structures through master service agreements that bundle design, material selection, and installation into single-source contracts. Three-tier pricing structure across premium, standard, and economy levels separates custom solid-wood channels from thermally fused laminate multifamily specifications and import-ready RTA volumes. Price differentiation rests on CARB Phase 2 certification status and geographic delivery cost to Sun Belt distribution nodes. Cost compression in mid-market laminate tiers is intensifying because Mexican nearshoring capacity is expanding faster than demand absorption. Renovation-driven residential buyers exhibit highest price sensitivity; institutional asset managers prioritize unit-turn durability over first-cost optimization.
Supply Chain Analysis
Export-control regime limitations on advanced CNC routing equipment from Germany and Japan are constraining automation upgrades for North American cabinet fabricators. Geographic supply concentration centers on China and Vietnam for decorative overlay films, Canada for softwood lumber inputs, and Mexico for thermally fused laminate pressing operations. Raw material dependencies draw from formaldehyde-based resins, thermally fused laminate films, and hardwood lumber species. Single-source vulnerability in Asian melamine substrate supply creates exposure to logistics chokepoints through Long Beach and Savannah port complexes. Distribution runs through institutional master service agreements for multifamily volumes and fragmented kitchen design studios for renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive positioning through regulatory entrenchment. TSCA Title VI and CARB Phase 2 certification chains create switching costs that lock institutional buyers into validated supplier relationships.
For Market Incumbents: Pre-empt margin erosion by consolidating Mexico nearshoring capacity in Baja California and Chihuahua to compress lead times for Texas and Arizona distribution. Invest in captive thermally fused laminate pressing to offset Asian substrate concentration. Secure CARB Phase 2 certification ahead of California AB 685 propagation into neighboring state codes to entrench specification authority before testing bottlenecks lengthen. For New Entrants and Emerging Players: Build out digital-to-physical kitchen planning tools that converge augmented reality visualization with automated cut-list generation to capture renovation demand from fragmented residential buyers. Target hospitality and food-service segments where industrial styling specifications remain underpenetrated by institutional suppliers. Lead with installation service bundling to differentiate from RTA competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermally fused laminate pressing as Mexican capacity expansion accelerates. Favor acquisition targets with validated CARB Phase 2 certification chains and established master service agreement relationships with Sun Belt institutional buyers. Watch for inflection when Texas and Florida housing starts decelerate below national averages, signaling procurement power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Mexico Nearshoring Capacity Expansion | Compresses lead times to Texas and Arizona distribution nodes while mitigating Asian substrate concentration risk. |
| CARB Phase 2 Certification Investment | Entrenches supplier relationships as California AB 685 disclosure requirements propagate into neighboring state codes. |
| Digital Kitchen Planning Tool Deployment | Reduces remeasurement errors in custom cabinet orders while capturing fragmented residential renovation demand. |
| Master Service Agreement Consolidation | Centralizes procurement authority among institutional asset managers displacing traditional fragmented bidding structures. |
| Thermally Fused Laminate Pressing Integration | Captures margin from surfacing technology penetration in rental-unit specifications requiring commercial-grade durability. |
Research Methodology
A standing panel of multifamily development executives, cabinet procurement managers at institutional asset managers, kitchen design studio operators, and thermally fused laminate mill technical directors provided ongoing calibration. Primary interviews combined with secondary validation from EPA TSCA Title VI certification databases, CARB Phase 2 third-party laboratory records, US Census Bureau housing starts data, and customs import records for decorative overlay films. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Scenario-bracketing framed projections across the analysis window through low-base-high housing start trajectories and regulatory enforcement intensity variants. Segmentation dimensions modeled include product type, material substrate grade, style positioning, and end-user procurement channel. CAGRs derived from regression against historical replacement cycles and new construction correlations. Forecast inputs incorporated resin cost pass-through elasticity and Mexican capacity expansion schedules.
Stress conditions across Canadian softwood tariff exposure, Asian logistics disruption severity, and institutional buyer concentration thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about CARB Phase 2 testing bottleneck duration and Sun Belt housing start momentum. Material shifts in EPA formaldehyde enforcement stringency or USMCA tariff treatment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Kitchen and Dining Furniture Market