
 Europe Kitchen Furniture Market | 2026-2036
Europe Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kitchen Furniture Market Foresight
Multi-source component procurement is decoupling from traditional single-factory dependency across the European kitchen furniture supply base. Nobia AB leverages its Nordic manufacturing footprint to sustain cost-efficient flat-pack distribution throughout Scandinavia and the British Isles. Schmidt Groupe anchors its competitive stance through vertically controlled retail networks spanning France, Belgium, and Spain. Häcker Küchen differentiates via precision-engineered German cabinet systems that dominate project-specified commercial installations.
Europe kitchen furniture encompasses fixed and modular storage, work-surface, and food-preparation installations engineered from particleboard substrates, solid timber, engineered stone, and tempered glass composites, typically finished with melamine, lacquer, or veneer treatments to meet moisture-resistance and abrasion standards for residential and food-service environments. Cabinets in wood and laminate materials occupy the highest volume share, though glass and metal accents are gaining specification in modern and industrial design styles where architects prioritize visual lightness and hygienic surfaces. Residential end users generate the dominant revenue pool, yet contractor and interior designer channels command superior margins through project-scale procurement and specification control.
The EU Green Deal and ECHA REACH frameworks mandate formaldehyde emission limits and sustainable timber chain-of-custody documentation, compelling manufacturers to reformulate adhesives and revalidate supplier certifications. CE marking under the Construction Products Regulation governs structural durability and fire-reaction performance for installed kitchen systems. Stakeholders must monitor evolving Ecodesign requirements and carbon-border adjustment mechanisms to calibrate material sourcing strategies and maintain market access across member states.
Market Dynamics
EU Green Deal mandates on formaldehyde emissions and timber chain-of-custody documentation are forcing manufacturers to reformulate adhesives and requalify supplier bases, compressing margins while raising entry barriers for uncertified competitors.
Growth Catalysts
- Residential renovation waves:Germany and France are experiencing sustained housing stock upgrades, with homeowners replacing aging cabinetry systems at accelerated cycles.
- ECHA REACH compliance premiums:Certified low-emission products command specification preference from architects and project developers across Nordic and Benelux markets.
- Engineered stone scaling:Italy's Emilia-Romagna cluster has expanded quartz-composite countertop output to serve premium residential developments.
Market Restraints
- Particleboard input volatility:Resin and wood fiber costs fluctuate with energy pricing, squeezing margin predictability for volume producers.
- Baltic timber supply concentration:Certified softwood sourcing pools heavily around Estonian and Latvian suppliers, creating geographic vulnerability to logistics disruptions.
- CE marking complexity:Construction Products Regulation fire-reaction testing adds six-to-nine month certification timelines for new cabinet system introductions.
Strategic Opportunities
- Polish manufacturing expansion:Lower labor and energy costs relative to Western Europe attract assembly capacity for flat-pack export programs.
- Carbon-border adjustment preparation:Early compliance with embedded carbon documentation positions suppliers favorably for 2026 implementation.
- Smart kitchen integration:Sensor-enabled cabinetry and connected appliance docking create specification pull from tech-forward residential developers.
Industry Challenges
- CNC programming talent scarcity:Precision cabinet production requires skilled operators for automated cutting and edge-banding lines, with recruitment lagging in Eastern European manufacturing zones.
- Multi-certification stacking:Simultaneous pursuit of FSC chain-of-custody, CE marking, and national fire-safety approvals strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kitchen Furniture Market |
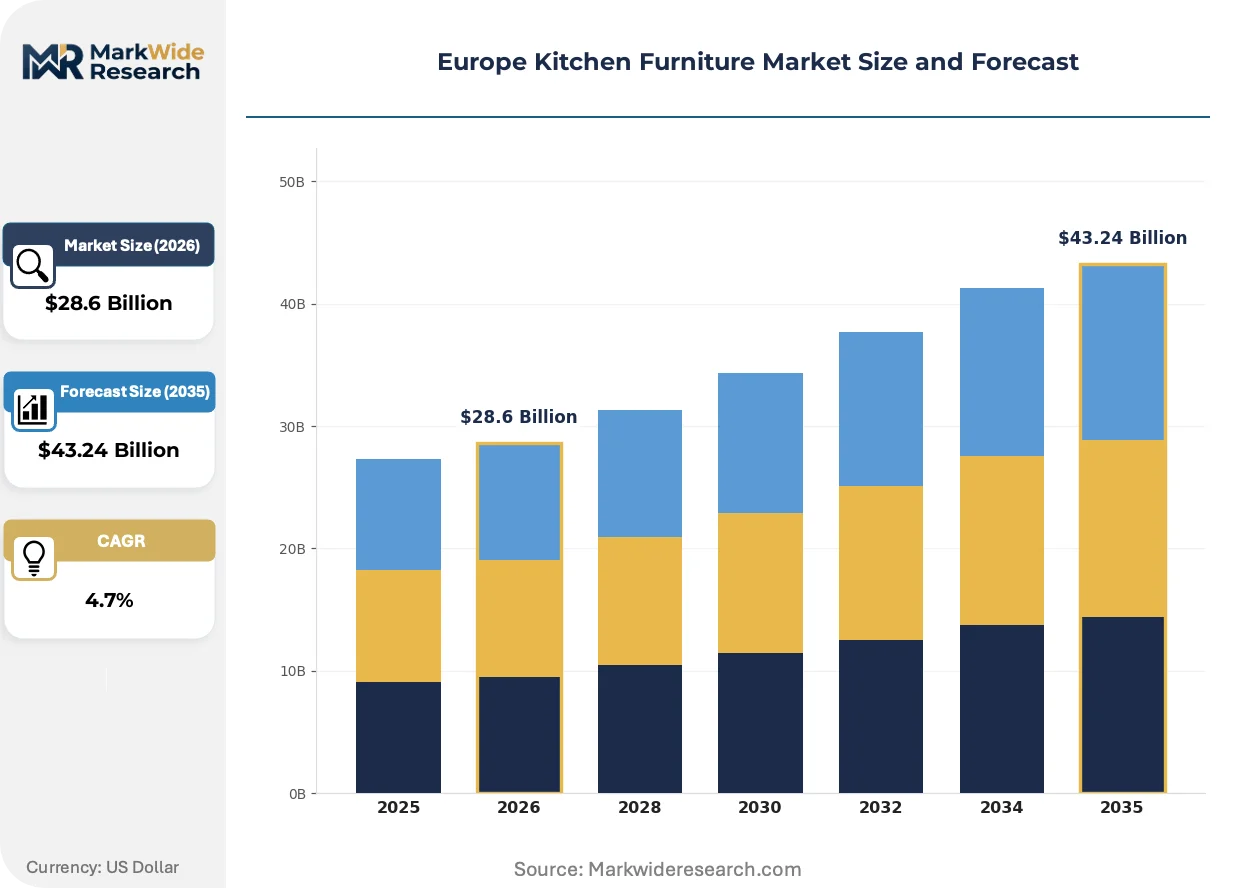
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Islands, Shelving Material: Wood, Metal, Laminate, Glass Design Style: Modern, Traditional, Rustic, Industrial End User: Residential, Commercial, Contractors, Interior Designers |
| Companies Covered | Nobia AB, XXXLutz, Nobilia, Ultima Kitchens, Scavolini, Häcker Küchen, Howdens Joinery Group, Leicht, Schmidt Groupe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kitchen Furniture Market Shifts & Advancements
Digital specification tools and sustainable material substitutions are compressing traditional design-to-installation timelines while elevating performance standards for moisture resistance and dimensional stability.
Thermally fused laminate surfaces with antimicrobial silver-ion integration are electrifying specification conversations among healthcare-adjacent foodservice designers. Hospital cafeterias and eldercare commissaries in Denmark and the Netherlands specify these finishes for hygienic durability. The technology is electrifying competitive differentiation, forcing lacquer-finish suppliers to defend position through price concessions or accelerated R&D cycles.
EU Ecodesign requirements for circularity and recyclability are mandating disassembly-friendly construction methods and material passports for installed kitchen systems. Manufacturers must redesign joint systems and substrate choices to enable end-of-life material recovery. German and Austrian producers face the steepest compliance curves given their project-scale export exposure to public procurement rules.
Direct-to-consumer configuration platforms are displacing traditional showroom-dependent purchase journeys for modular kitchen systems. Younger buyers in urban Spain and Italy complete entire design-to-order workflows online, with virtual reality visualization replacing physical sample handling. Channel margin compression follows, as manufacturers absorb fulfillment complexity previously managed by retailer networks.
Europe Kitchen Furniture Market Segmentation
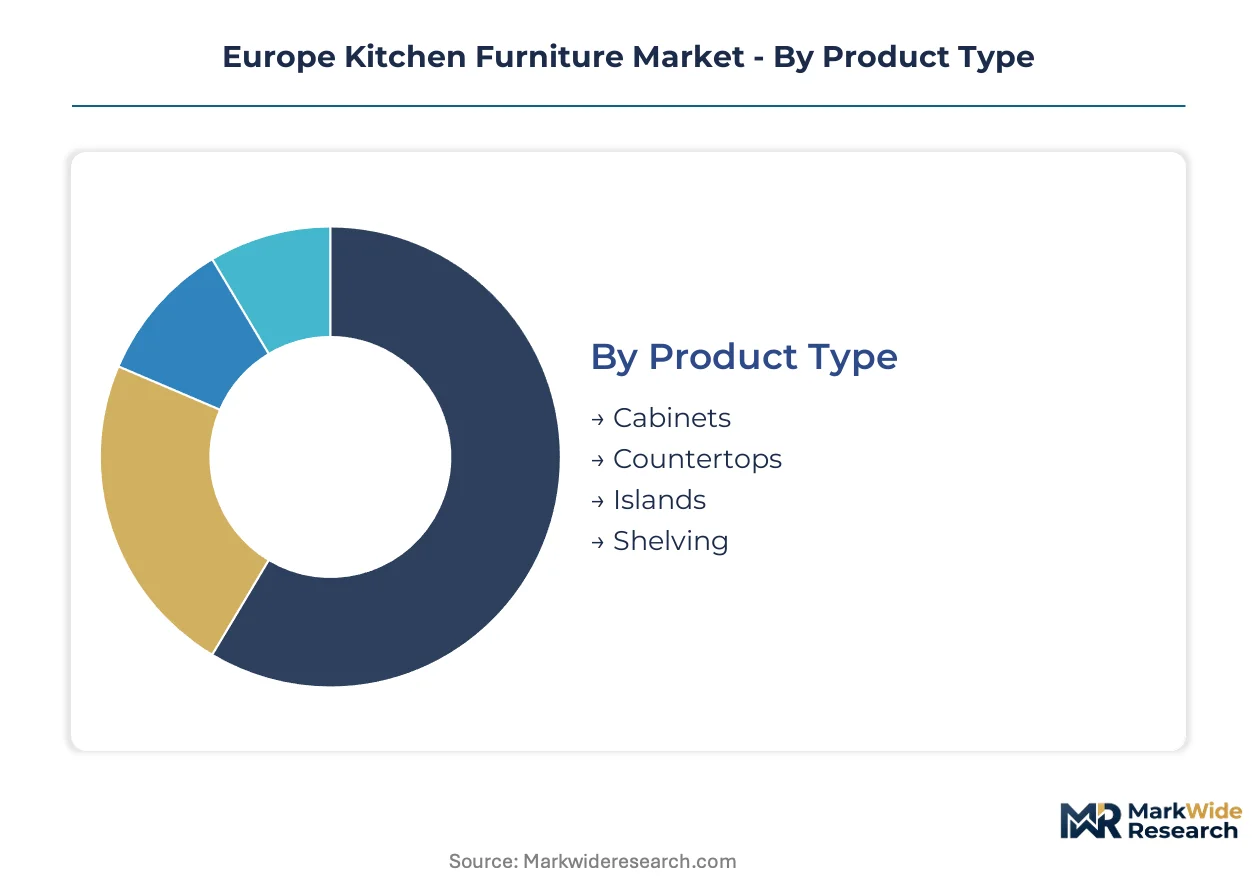
Segmentation in Europe kitchen furniture reveals how procurement patterns split between project-scale commercial channels and direct residential purchases. Understanding these divides helps suppliers calibrate certification investments, distribution formats, and margin structures across divergent buyer workflows.
Product Type:
Standalone installations dominate renovation spending, while integrated systems capture new-build specifications.
- Cabinets:Engineered from particleboard substrates with melamine, lacquer, or veneer finishes meeting ECHA REACH formaldehyde limits. German and French residential renovators drive specification for custom dimension systems with soft-close hardware. CE marking under the Construction Products Regulation governs structural durability for installed base units.
- Countertops:Quartz-composite and engineered stone surfaces from Italy's Emilia-Romagna cluster serve premium residential developments. The EU Green Deal's sustainable sourcing mandates redirect procurement toward certified stone suppliers with chain-of-custody documentation.
- Islands:Freestanding units with integrated storage and seating anchor open-plan kitchen layouts in Benelux urban renovations.
- Shelving:Wall-mounted and suspended systems gain traction in compact Spanish and Italian apartments where floor space is constrained.
Cabinets lead volumes today; islands are gaining share fastest in premium urban renovations.
Material:
Cost tiers separate certified sustainable inputs from commodity alternatives.
- Wood:Solid timber and veneer-faced particleboard occupy the premium tier, with FSC chain-of-custody certification mandatory for public procurement in Germany and Austria. Baltic softwood concentration in Estonian and Latvian suppliers creates geographic vulnerability to logistics disruptions.
- Laminate:Thermally fused surfaces with antimicrobial silver-ion integration electrify specification among Danish and Dutch healthcare-adjacent foodservice designers. Ecodesign circularity requirements mandate disassembly-friendly construction methods for end-of-life recovery.
- Metal:Stainless steel and aluminum accents specify into industrial design styles where architects prioritize visual lightness.
- Glass:Tempered glass composites specify for modern aesthetics and hygienic surfaces in high-end residential projects.
Wood commands the premium price tier; laminate is climbing the fastest on compliance-driven specification.
Design Style:
Application context determines whether aesthetics or durability dominates selection criteria.
- Modern:Clean lines, handleless cabinetry, and integrated appliances specify into new-build developments across Nordic markets. Direct-to-consumer configuration platforms displace traditional showroom journeys for modular systems.
- Traditional:Raised-panel doors, decorative molding, and natural wood finishes anchor renovation demand in historic French and Belgian housing stock.
- Rustic:Distressed wood and farmhouse sinks specify into rural Spanish and Italian secondary residences.
- Industrial:Exposed metal frames, concrete countertops, and open shelving gain traction in converted warehouse apartments in London and Berlin.
Modern styling dominates new-build specification; industrial is expanding most quickly in urban conversion projects.
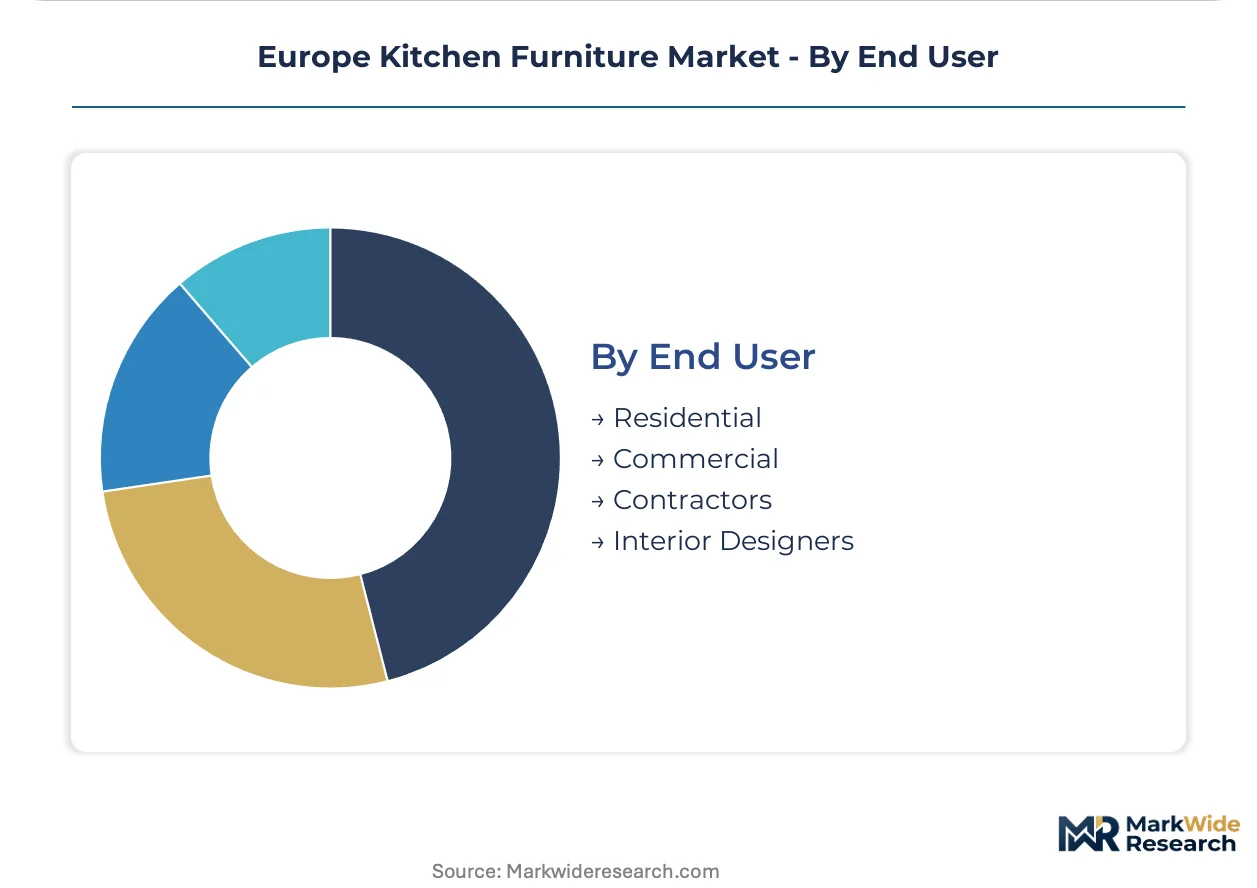
End User:
Customer type splits margin structures and channel control.
- Residential:Homeowners generate the dominant revenue pool, with younger buyers in urban Spain and Italy completing design-to-order workflows online. Virtual reality visualization replaces physical sample handling in purchase journeys.
- Commercial:Hospital cafeterias, eldercare commissaries, and corporate foodservice operations specify antimicrobial finishes and fire-reaction certified systems. Project-scale procurement commands superior margins through specification control.
- Contractors:Volume builders in Poland and Czech Republic source flat-pack assembly for cost-efficient installation programs.
- Interior Designers:Specification consultants in France and Belgium control material selection for high-value residential renovations, demanding extended finish libraries and sample logistics support.
Residential channels move the highest unit volumes; commercial end users deliver the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Emilia-Romagna cluster anchors European kitchen furniture manufacturing, with engineered stone countertop production scaling to serve premium residential developments across the continent.
Germany
Residential renovation waves in Berlin, Hamburg, and Munich accelerate replacement cycles for aging cabinetry systems. ECHA REACH formaldehyde emission limits compel adhesive reformulation across Baden-Württemberg and Bavaria manufacturing zones. The North Rhine-Westphalia industrial corridor concentrates precision-engineered cabinet production for project-specified commercial installations.
France
Historic housing stock in Paris, Lyon, and Marseille sustains demand for custom dimension systems with traditional raised-panel finishes. EU Green Deal timber chain-of-custody mandates redirect procurement toward certified suppliers for public renovation programs. The Schmidt Groupe anchors vertically controlled retail networks spanning Île-de-France through Nouvelle-Aquitaine.
Italy
Premium residential developments in Milan, Rome, and Florence specify quartz-composite surfaces from the Emilia-Romagna cluster. CE marking under the Construction Products Regulation governs fire-reaction performance for installed systems exported to Nordic markets. Scavolini exemplifies design-forward positioning within the modern styling segment.
Poland
Lower labor and energy costs relative to Western Europe attract flat-pack assembly capacity for export programs serving Scandinavia and the British Isles. National fire-safety approval timelines compress competitive entry for new cabinet system introductions. The Warsaw-Łódź manufacturing belt concentrates cost-efficient volume production for contractor channels.
United Kingdom
Urban conversion projects in London, Manchester, and Birmingham specify industrial-style exposed metal frames and open shelving configurations. Howdens Joinery Group maintains distribution density through builder-merchant relationships across England and Scotland. Direct-to-consumer configuration platforms displace traditional showroom journeys for modular kitchen purchases.
Europe Kitchen Furniture Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart kitchen integration and carbon-border adjustment compliance. The vendor base clusters around three strategic archetypes: Nordic flat-pack distributors leveraging cost-efficient logistics, German precision-engineered specialists dominating commercial specifications, and French vertically integrated retailers controlling margin capture. Consolidation pressure concentrates among mid-scale fabricators facing multi-certification stacking burdens. Dominant competitive moves include Polish manufacturing expansion for labor arbitrage and early carbon documentation positioning for 2026 border adjustment implementation.
Among Nordic-based fabricators, Nobia AB represents the scale-driven logistics archetype through its regional distribution footprint. Häcker Küchen exemplifies precision-engineered German positioning within project-specified channels. Schmidt Groupe anchors the vertically integrated retail tier across France, Belgium, and Spain.
| Leading Market Players |
|---|
| Nobia AB |
| XXXLutz |
| Nobilia |
| Ultima Kitchens |
| Scavolini |
| Häcker Küchen |
| Howdens Joinery Group |
| Leicht |
| Schmidt Groupe |
| Others |
Supply & Pricing Matrix
The EU Green Deal's chain-of-custody mandates gate qualified supply pools and premium-tier pricing access, compressing uncertified competitors into commodity tiers while rewarding documented sustainable sourcing with specification preference across German and French public procurement channels.
Pricing Analysis
Input-cost pass-through from Baltic timber and resin markets intensifies margin pressure across particleboard-dependent producers. Project-scale procurement commands premium-mid-economy pricing differentiation based on CE marking status and FSC certification tier. Price erosion runs through flat-pack volume tiers as Polish assembly capacity expands. Contractor channels exhibit highest price sensitivity; architect-specified commercial installations demonstrate lowest.
Supply Chain Analysis
Freight cost volatility from Estonian and Latvian softwood suppliers amplifies landed cost unpredictability for Western European fabricators. Engineered stone feeds from Italy's Emilia-Romagna cluster; particleboard substrates draw from German and Polish mills; hardware systems source from Austrian and Chinese specialists. Single-source vulnerability concentrates around certified Baltic timber pools. Distribution runs through vertically controlled retail networks in France, builder-merchant relationships in the United Kingdom, and direct-to-consumer platforms in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe kitchen furniture market functions as a stable compounder, with residential renovation cycles across Germany and France generating replacement demand that smooths cyclical volatility.
For Market Incumbents: Deepen backward integration into certified timber sourcing to defend against Baltic supply concentration risks. Expand Polish manufacturing footprint to capture labor arbitrage for flat-pack export programs. Prioritize early carbon-border adjustment documentation to secure specification preference ahead of compliance deadlines.
For New Entrants and Emerging Players: The mid-market price-point gap between premium German engineered systems and economy Polish flat-packs offers white-space opportunity. Target smart kitchen integration segments where sensor-enabled cabinetry specifications remain underdeveloped. Pursue direct-to-consumer configuration platforms to bypass established retail network control in urban Spain and Italy.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabricators facing multi-certification stacking burdens and quality assurance bandwidth constraints. Long-term viability favors targets with documented EU Green Deal compliance and established CE marking pathways. Monitor carbon-border adjustment implementation timelines as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Polish Manufacturing Expansion | Labor and energy cost arbitrage strengthens flat-pack export competitiveness across Scandinavia and the British Isles. |
| Carbon Documentation Early Compliance | Embedded carbon verification positions suppliers favorably for EU border adjustment mechanism implementation. |
| Smart Kitchen Integration Investment | Sensor-enabled cabinetry and connected appliance docking capture specification pull from tech-forward residential developers. |
| Direct-to-Consumer Platform Launch | Virtual reality visualization displaces traditional showroom journeys for modular kitchen purchases in Southern Europe. |
| Antimicrobial Finish Certification | Silver-ion laminate surfaces penetrate healthcare-adjacent foodservice specifications in Denmark and the Netherlands. |
Research Methodology
Multiple input streams — executive interviews with kitchen furniture manufacturers, procurement discussions with contractor and developer channels, and regulatory compliance tracking — were reconciled against secondary validation from ECHA REACH documentation, CE marking registries, and EU timber trade databases. Primary fieldwork encompassed plant managers at particleboard mills, procurement leads at cabinet assembly operations, retail network directors, and architect specification consultants across Germany, France, Italy, Poland, and the United Kingdom. Bottom-up volume modeling and top-down macroeconomic triangulation anchored value estimates.
Historical shipment patterns were cross-referenced against panel input from industry participants to construct projection frameworks across the analysis window. Segmentation dimensions encompassed product type, material certification tier, design styling, and end-user channel. CAGRs were derived from trend extrapolation calibrated to renovation cycle intensity and regulatory compliance cost trajectories. Engineered stone capacity expansion in Emilia-Romagna and flat-pack assembly growth in Poland served as industry-specific forecast anchors.
Caveats apply where energy price volatility, Baltic logistics disruptions, or accelerated Ecodesign circularity requirements could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation timelines and substitution elasticity between material categories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Accent Tables Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Dining Table Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Europe Restaurant Furniture Market