
 Restaurant Chairs Market | 2026-2036
Restaurant Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Chairs Market Analysis
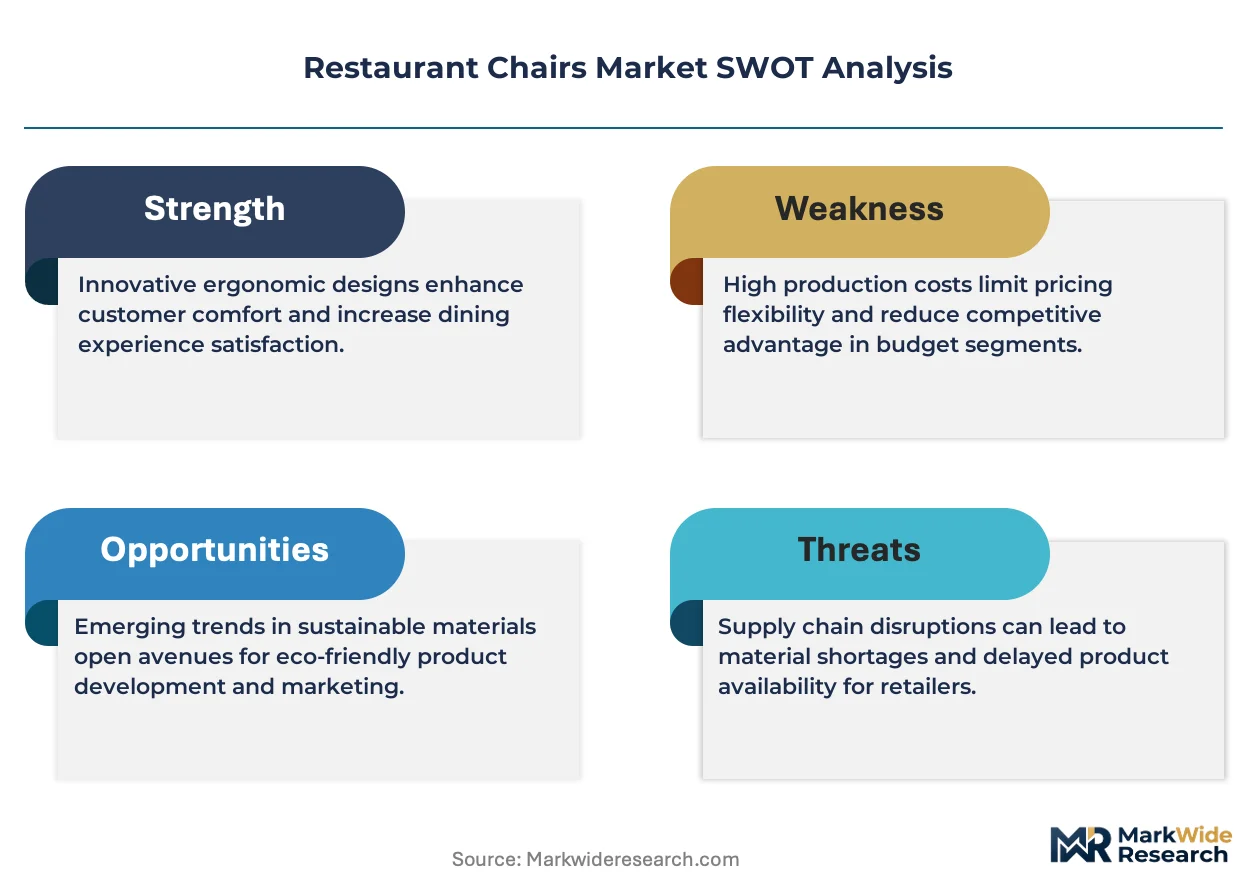
The contract furniture distribution channel is reconfiguring as hospitality procurement teams consolidate vendor relationships across multi-unit operators. Grand Rapids Chair Co leverages domestic hardwood sourcing to sustain its position in the wooden chair segment. Grosfillex anchors the outdoor seating category through resin-based manufacturing expertise. Plymold Seating competes on quick-ship programs for fast-casual rollout timelines.
Restaurant chairs are purpose-built seating structures engineered for commercial foodservice environments, typically rated for 300-pound static load capacity and fabricated with moisture-resistant adhesives or welded steel frames to withstand 8-16 hour daily use cycles. The upholstered product type commands premium positioning in full-service restaurants where acoustic comfort and brand aesthetics justify higher per-unit investment. Metal chairs dominate fast-casual applications where durability and stackability reduce replacement frequency. Wooden chairs retain strongholds in rustic and vintage design style segments across independent restaurants seeking material authenticity.
The US Consumer Product Safety Commission enforces stability and tip-over standards that shape structural testing protocols, while EPA regulations on volatile organic compound emissions from finishes constrain coating selections for domestic manufacturers. EU REACH compliance and FSC chain-of-custody certification requirements create dual compliance burdens for exporters serving European restaurant chains. Stakeholders must monitor evolving extended producer responsibility frameworks for furniture waste streams as jurisdictions in Germany and France advance circular economy mandates.
Market Dynamics
Fast-casual dining chains are consolidating vendor relationships across multi-unit rollouts, compressing supplier margins while demanding accelerated fulfillment timelines and unified fire-safety certifications.
Growth Catalysts
- California TB 117-2013:Fire-retardant upholstery mandates in North American foodservice have elevated technical specifications for foam and fabric suppliers, creating compliant product premiums.
- Fast-casual expansion:Seating capacity additions at new locations across the United States and Germany are pulling stackable metal chair volumes through contract furniture distributors.
- Resin manufacturing:Advanced polymer formulations for outdoor seating are extending product lifecycles in high-UV environments, reducing replacement frequency for patio operators.
Market Restraints
- Hardwood supply concentration:Domestic timber sourcing constraints in the United States limit wooden chair production scalability for mid-tier manufacturers.
- EU REACH compliance costs:Chemical restriction testing for exported seating creates dual certification burdens that erode margin on European-bound shipments.
- Steel price volatility:Welded frame input costs fluctuate with raw material indices, complicating long-term contract pricing for metal chair fabricators.
Strategic Opportunities
- Extended producer responsibility:Circular economy mandates advancing in Germany and France will reward manufacturers with closed-loop material recovery systems.
- Quick-ship programs:Compressed lead-time capabilities for fast-casual rollout schedules represent a service-based differentiation vector against standard distribution.
- Acoustic comfort integration:Upholstered seating with sound-dampening properties addresses full-service restaurant design priorities in urban China.
Industry Challenges
- FSC chain-of-custody certification:Documentation complexity for wooden chair exporters slows market entry timelines for European restaurant chains.
- Welded frame quality assurance:300-pound static load rating consistency across high-volume production runs demands capital-intensive testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Chairs Market |
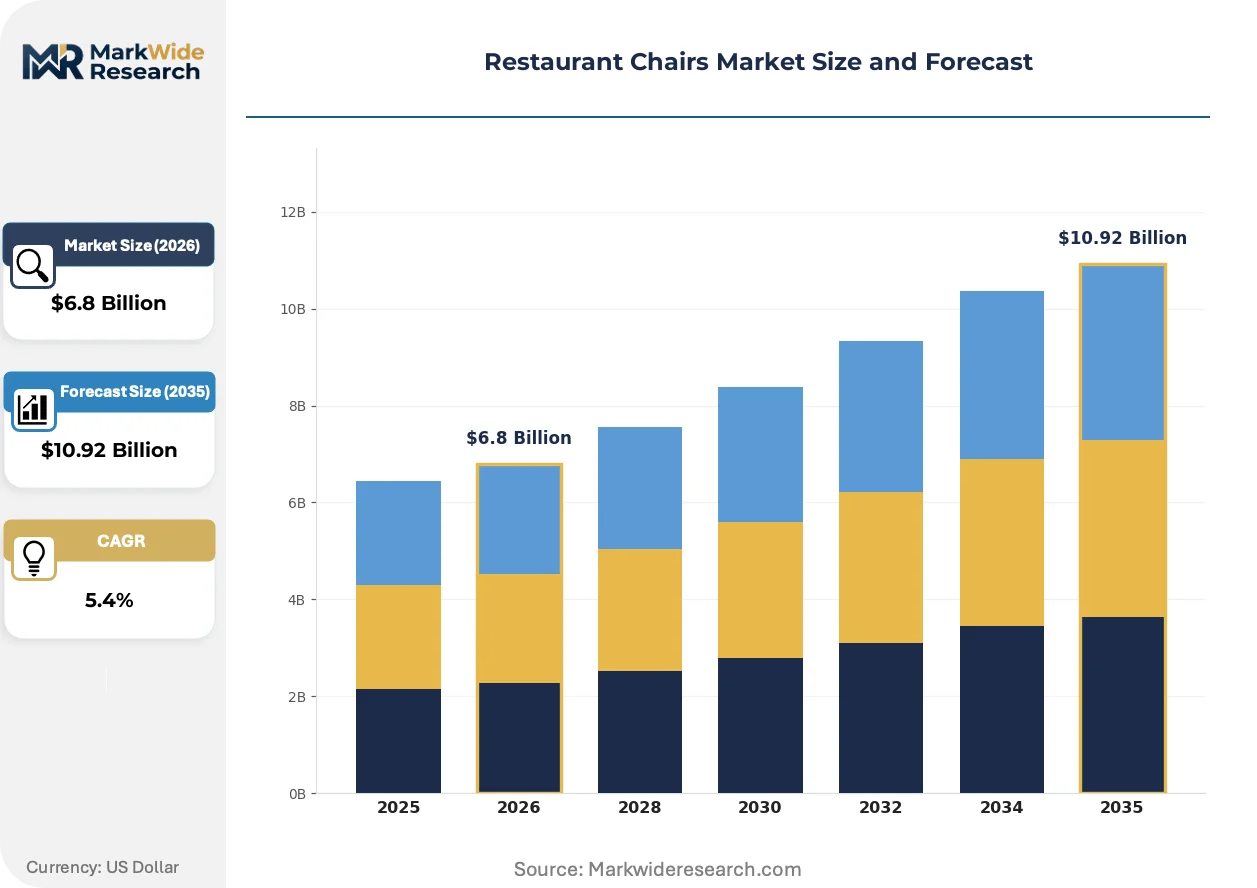
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upholstered, Metal, Wooden, Plastic Application: Indoor Seating, Outdoor Seating, Cafe Usage, Banquet Halls Design Style: Modern, Rustic, Vintage, Industrial End User: Restaurants, Cafes, Catering Services, Fast Food Chains |
| Companies Covered | Beaufurn, Grand Rapids Chair Co, Plymold Seating, Grosfillex, East Coast Chair & Barstool, Tropitone Furniture Co., MTS Seating, Forever Patio, Custom Seating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Chairs Market Emerging Trajectories
Contract furniture procurement is reconfiguring around consolidated vendor relationships and unified compliance documentation, compressing traditional multi-supplier sourcing patterns into streamlined single-source arrangements.
RFID-enabled inventory tracking is digitizing fleet management for multi-unit restaurant operators. Large chains in the United States are embedding tags during manufacturing to monitor chair location, condition, and replacement cycles. This visibility is digitizing asset depreciation schedules and reorder timing.
EU REACH chemical restrictions are reshaping foam and adhesive formulations for seating exported to European markets. Manufacturers serving German and French restaurant chains must maintain dual material specifications. Upholstered product categories face the steepest reformulation costs and testing timelines.
Consolidated procurement teams at fast-casual headquarters are displacing location-level purchasing autonomy. Single-source contracts now cover seating, tables, and fixtures across hundreds of units. This concentration is most visible in North American rollout schedules where speed-to-open metrics dominate supplier selection.
Restaurant Chairs Market Segmentation
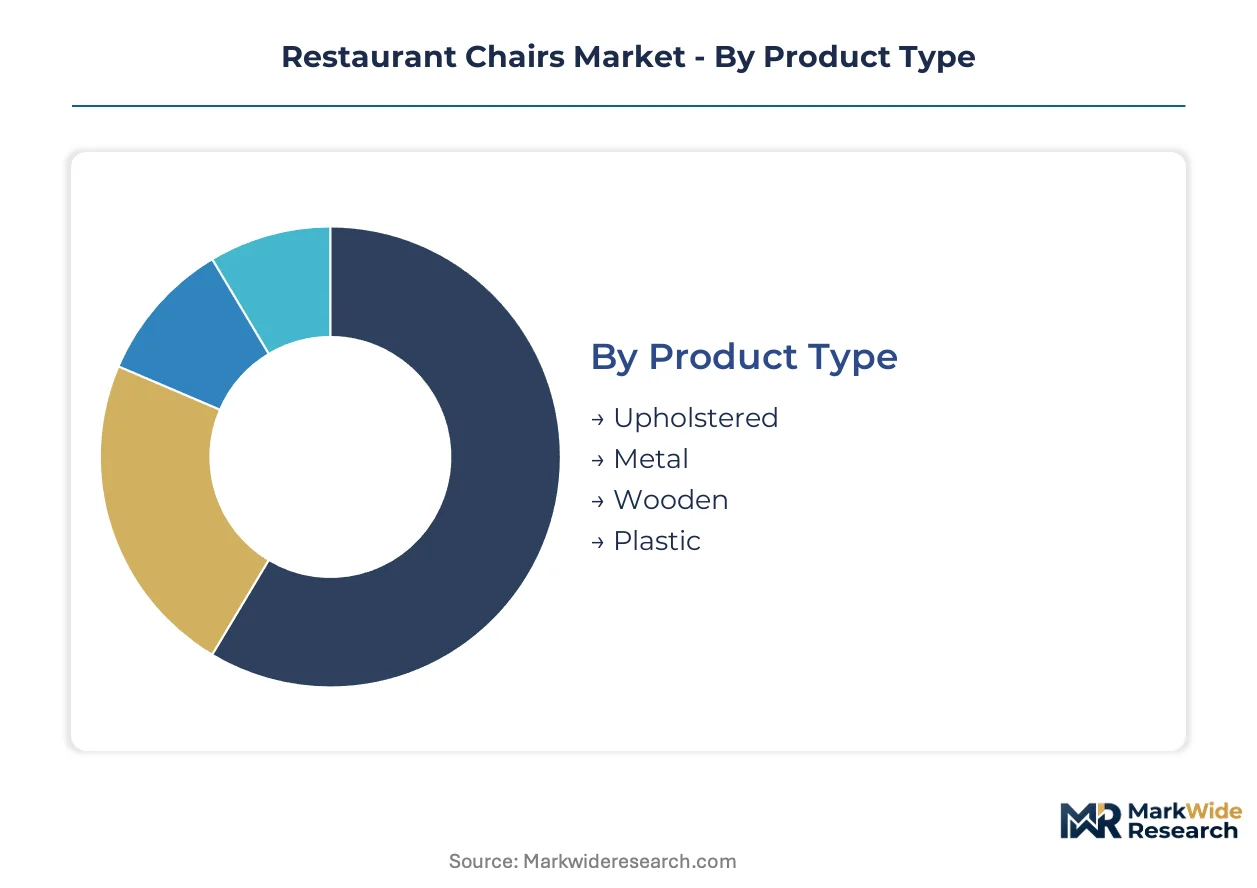
Restaurant chair procurement patterns diverge sharply by operational intensity. High-turnover segments demand rapid replacement cycles, while premium installations prioritize longevity over unit economics.
Product Type:
Replacement cycles vary from 18 months for budget polymer seating to 8-12 years for hardwood frames in heritage dining rooms.
- Upholstered:Foam-cushioned seats with fabric or leather coverings rated for commercial abrasion resistance. Full-service restaurants in urban China specify these for acoustic dampening in open-concept layouts, absorbing ambient noise from hard surfaces.
- Metal:Welded steel or aluminum frames with powder-coated finishes, typically stackable to 10-12 units. Fast-casual chains across the United States specify these for 300-pound static load ratings and rapid reconfiguration between service periods.
- Wooden:Solid hardwood or engineered timber with moisture-resistant adhesives. Independent restaurants seeking material authenticity favor these for rustic and vintage design executions.
- Plastic:Injection-molded polymer or resin formulations, often UV-stabilized for exterior deployment. Patio operators value these for weather resistance and minimal maintenance overhead.
Metal chairs anchor the volume base while upholstered seating gains share at the steepest rate.
Application:
Cost tier stratification separates specification-grade indoor installations from commodity outdoor replacements.
- Indoor Seating:Climate-controlled environments enable broader material latitude including natural fibers and unsealed wood. Fine-dining establishments in Germany prioritize these for extended guest dwell times.
- Outdoor Seating:Exposure-rated construction with drainage gaps and corrosion-resistant hardware. Grosfillex anchors this category through resin-based manufacturing expertise in high-UV environments.
- Cafe Usage:Compact footprints with lightweight frames for frequent repositioning. European sidewalk cafes drive demand for bistro-height profiles with slender silhouettes.
- Banquet Halls:Stackable or folding configurations with uniform styling for event flexibility. Catering operators require rapid setup breakdown cycles without aesthetic compromise.
Indoor seating commands the highest per-unit investment while outdoor applications expand most quickly.
Design Style:
Customer type alignment pairs aesthetic codes with target demographics and price positioning.
- Modern:Clean lines, minimal ornamentation, and neutral palettes compatible with fast-casual brand refreshes. Chains seeking Instagram-visible interiors specify these for visual consistency across locations.
- Rustic:Distressed finishes, visible joinery, and reclaimed material cues. Farm-to-table concepts in the United States deploy these to signal provenance and craft authenticity.
- Vintage:Period-accurate reproductions or refurbished antique sourcing. Boutique hospitality groups favor these for differentiation in saturated urban markets.
- Industrial:Exposed metal frames, riveted connections, and utilitarian silhouettes. Loft-conversion restaurants leverage these for architectural coherence with raw building fabric.
Modern styling dominates new construction volume while rustic designs climb the fastest among independent operators.
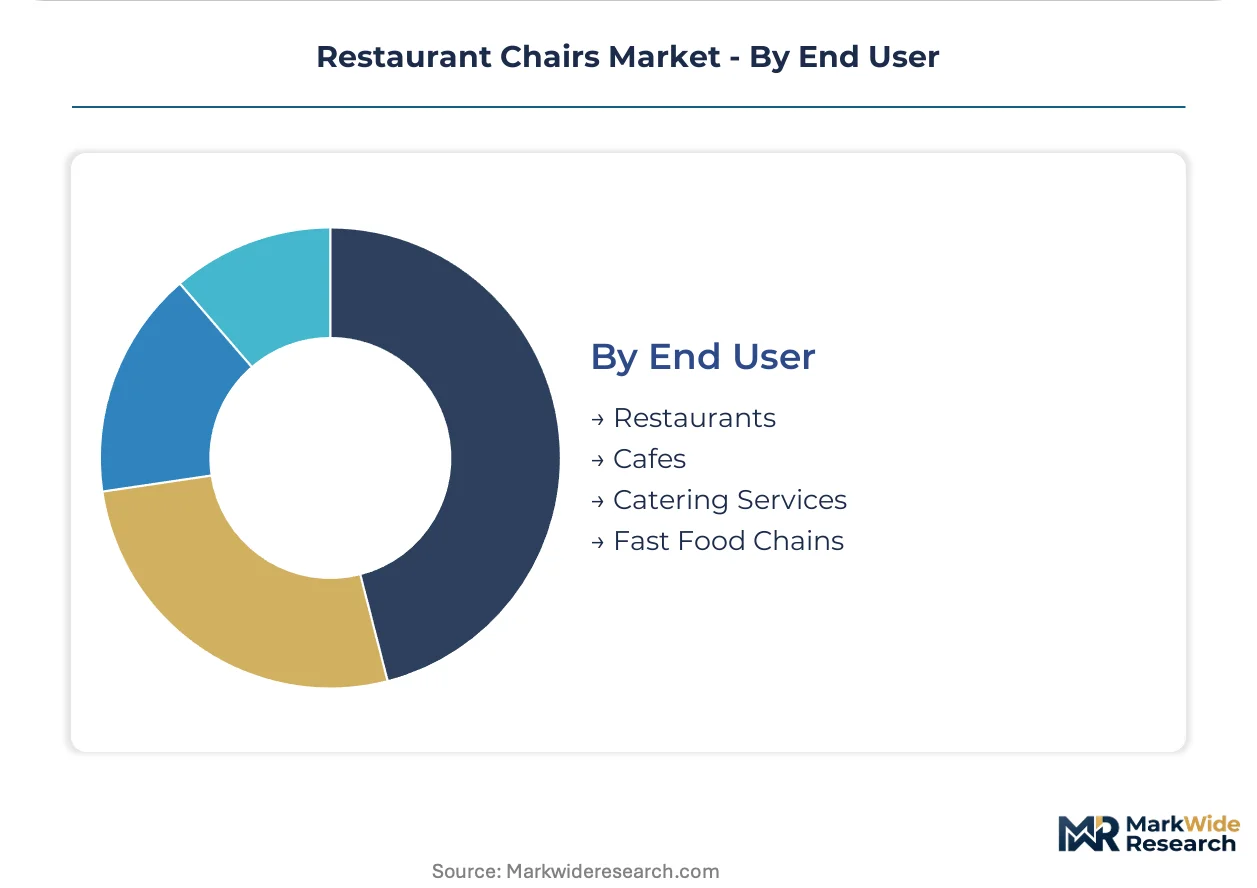
End User:
Procurement concentration separates consolidated multi-unit programs from fragmented single-location purchasing.
- Restaurants:Full-service establishments with dedicated dining rooms and extended menu programs. These buyers prioritize durability amortized over 5-7 year replacement horizons.
- Cafes:Beverage-forward operations with shorter average visits and higher table turns. Seated capacity optimization drives demand for compact, lightweight profiles.
- Catering Services:Event-based operators requiring inventory mobility and rapid deployment. Folding and stacking capabilities outweigh aesthetic permanence.
- Fast Food Chains:High-volume, quick-service systems with standardized interior packages. Plymold Seating competes here on quick-ship programs aligned with aggressive rollout timelines.
Fast food chains anchor procurement volume while full-service restaurants sustain the highest per-unit specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific furniture supply chains, while Rotterdam's Europoort handles intra-European distribution of contract seating. These maritime gateways sustain procurement velocity for restaurant construction cycles across their respective hinterlands.
United States
Fast-casual rollout schedules in Texas and Florida drive metal chair volumes through distributors serving multi-unit operators. The US Consumer Product Safety Commission enforces stability standards that shape welded frame testing protocols. Grand Rapids, Michigan hosts hardwood sourcing clusters where domestic timber constraints limit mid-tier manufacturer scalability.
Germany
Fine-dining establishments in Bavaria and North Rhine-Westphalia specify upholstered seating for extended guest dwell times. EU REACH chemical restrictions mandate dual material specifications for foam and adhesive suppliers. The Cologne-Düsseldorf corridor concentrates contract furniture procurement teams consolidating vendor relationships across European fast-casual expansions.
China
Urban restaurant construction in Shanghai and Shenzhen pulls specification-grade seating through Pearl River Delta manufacturing bases. GB standards and SAMR oversight constrain coating selections for domestic market entry. The Yangtze River Delta hosts resin formulation specialists serving outdoor seating demand from patio operators.
France
Sidewalk cafes in Paris and Lyon drive bistro-height chair specifications with slender silhouettes for frequent repositioning. Extended producer responsibility frameworks advancing under circular economy mandates reward closed-loop material recovery systems. The Île-de-France region anchors hospitality procurement concentration for multi-unit rollouts.
United Kingdom
Independent restaurants in London and Manchester favor wooden chairs for rustic and vintage design executions seeking material authenticity. FSC chain-of-custody certification requirements create documentation complexity slowing market entry timelines. The Midlands manufacturing belt supplies metal frame fabricators serving stackable chair demand from catering operators.
Restaurant Chairs Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on material and fabrication vectors. The vendor base organizes around three tiers: domestic hardwood specialists, resin-based outdoor seating manufacturers, and quick-ship metal fabricators. Consolidation pressures favor players with unified fire-safety certifications and accelerated fulfillment capabilities. Strategic moves center on vendor relationship consolidation and geographic expansion through distributor partnerships.
Among North American fabricators, Grand Rapids Chair Co exemplifies the domestic hardwood sourcing archetype, while Plymold Seating occupies the quick-ship program tier for fast-casual rollout timelines. Grosfillex anchors the resin-based outdoor seating specialization through advanced polymer formulation expertise. These three represent distinct competitive positioning vectors within the contract furniture supply base.
| Leading Market Players |
|---|
| Beaufurn |
| Grand Rapids Chair Co |
| Plymold Seating |
| Grosfillex |
| East Coast Chair & Barstool |
| Tropitone Furniture Co. |
| MTS Seating |
| Forever Patio |
| Custom Seating |
| Others |
Supply Flow & Price Mechanics
The Port of Los Angeles freight corridor anchors trans-Pacific contract furniture flows, where container rate volatility feeds directly into landed cost tiering and downstream price differentiation between domestic hardwood specialists and resin-based outdoor manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade upholstered seating from stackable metal frames and injection-molded polymer units. Price differentiation hinges on fire-safety certification grade and volume scale, with California TB 117-2013 compliance commanding material premiums. Pricing pressure stems from fast-casual procurement consolidation demanding accelerated fulfillment without margin expansion. Fast food chains exhibit highest price sensitivity; full-service restaurants in urban China show lowest.
Supply Chain Analysis
Contract manufacturing concentration centers on Pearl River Delta resin formulators, Grand Rapids hardwood fabricators, and European metalworking clusters in Germany and Poland. Raw material dependencies include domestic timber, steel coil, and UV-stabilized polymer feedstock. Supply chain risk concentrates in single-source vulnerability for FSC-certified hardwood. Distribution runs through hospitality procurement teams consolidating vendor relationships across multi-unit operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of unified fire-safety certification capabilities constrains supplier scalability, as mid-tier manufacturers struggle to meet dual California TB 117-2013 and EU REACH compliance burdens without dedicated testing infrastructure.
For Market Incumbents: Build certification moats through captive testing laboratories serving both North American and European compliance regimes. Consolidate vendor relationships across fast-casual rollout schedules to compress competitor access. Anchor capacity in hardwood sourcing clusters around Grand Rapids to defend against timber supply constraints. Threat: Resin-based outdoor manufacturers extending polymer expertise into indoor stackable segments. For New Entrants and Emerging Players: Mid-tier fast-casual chains in secondary US metropolitan markets represent the most penetrable entry point, as procurement teams there retain fragmented multi-supplier relationships. Acoustic comfort integration for full-service urban China applications offers specification-grade margin capture. Go-to-market angle: Quick-ship programs compressing lead times against established distributor networks. For Investors and Strategic Acquirers: Domestic hardwood specialists with FSC chain-of-custody certification and European market access represent priority acquisition targets. Long-term viability frames around circular economy mandate compliance capability as Germany and France advance extended producer responsibility. Signal to watch: RFID-enabled inventory tracking adoption rates among multi-unit operators indicating fleet management digitization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Unified Certification Investment | Dual California TB 117-2013 and EU REACH compliance opens fast-casual procurement consolidation. |
| Quick-Ship Program Expansion | Compressed lead times align with aggressive Texas and Florida rollout schedules. |
| Resin Formulation R&D | Advanced polymer expertise extends product lifecycles in high-UV patio environments. |
| RFID Fleet Integration | Embedded inventory tags digitize asset depreciation for US multi-unit operators. |
| Closed-Loop Recovery Systems | Circular economy compliance rewards manufacturers under advancing French and German mandates. |
Methodological Framework
Cross-validation between primary hospitality procurement interviews and secondary trade data anchors the qualitative findings. Restaurant development executives, contract furniture distributors, fast-casual rollout managers, and FSC certification auditors provided field intelligence. Secondary sources include US Consumer Product Safety Commission filings, EU REACH substance databases, customs import records, and hospitality construction permit data. Bottom-up unit economics triangulate against top-down construction cycle projections.
Calibration against historical replacement cycle patterns and material cost indices validates the analytical framework. Segmentation dimensions span product type, application environment, design style, and end-user procurement concentration. CAGRs derive from rolling average construction spend correlation with seating capacity additions. Industry-specific inputs include fire-safety certification adoption curves and resin formulation patent filings.
Practitioners should monitor steel price volatility, hardwood supply constraints, and circular economy mandate advancement for early signals of forecast revision. Quarterly review of fast-casual expansion permits and EU REACH substance restriction proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
UAE Kitchen Hoods Market