
 Luxury Plumbing Fixtures Market | 2026-2036
Luxury Plumbing Fixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Plumbing Fixtures Market Intelligence
Specification-grade brass forging is collapsing the gap between artisanal craftsmanship and precision-manufactured luxury, forcing mid-tier producers to retreat or reposition. Kohler leverages captive foundry capacity in Wisconsin to control alloy consistency across its premium faucet lines. Grohe anchors European demand through its German-engineered thermostatic shower systems, while TOTO dominates Japanese-influenced smart fixture categories with integrated sensor technology.
Luxury plumbing fixtures encompass high-end sanitary ware and water delivery systems fabricated from solid brass, marine-grade stainless steel, or hand-finished bronze, typically specifying flow rates below 1.5 gallons per minute and pressure-balancing valves rated for 100,000-cycle durability; these products serve upscale residential, hospitality, and commercial environments where aesthetic distinction and water efficiency carry equal weight. The material dimension stratifies sharply, with brass commanding the deepest margin pools due to machining complexity and patina customization, while glass vessel sinks represent the fastest-growing segment among minimalist design specifications. Installation type reveals structural tension: wall-mounted configurations lead in urban luxury condominiums where floor space commands premium valuation, yet freestanding bathtub fixtures accelerate in suburban estate construction.
The EPA's WaterSense program and the EU Ecodesign Directive enforce escalating flow-rate restrictions that manufacturers must satisfy to maintain market access, while California's Title 20 plumbing standards extend these thresholds to the largest US state economy. China's GB standards for water efficiency and India's BIS certification for sanitary fixtures add compliance layers for brands targeting Asia-Pacific expansion. Stakeholders must monitor regulatory divergence between efficiency mandates and consumer preference for high-pressure sensory experience, as this tension will determine which engineering investments yield durable competitive separation.
Market Dynamics
Specification-grade brass forging is collapsing the gap between artisanal craftsmanship and precision-manufactured luxury, forcing mid-tier producers to retreat or reposition as captive foundry capacity becomes the decisive competitive moat.
Growth Catalysts
- EPA WaterSense certification thresholds:Tightening US flow-rate mandates below 1.5 gallons per minute are accelerating replacement cycles in existing luxury residential stock as owners seek compliant upgrades without aesthetic compromise.
- Marine-grade stainless specification:Coastal high-rise developments in Miami and Dubai are specifying 316L stainless for corrosion resistance, creating premium tier separation from 304-grade standard offerings.
- Saudi giga-project pipeline:Neom and Red Sea Project developments are procuring fixture packages at volumes that justify dedicated production lines and custom alloy development.
Market Restraints
- Copper-zinc alloy price volatility:Brass billet input costs swing with London Metal Exchange copper pricing, compressing margin predictability for forged-component manufacturers.
- EU Ecodesign Directive friction:Divergent testing protocols between EU member states create compliance duplication costs for thermostatic valve assemblies.
- Glass vessel sink substitution:Engineered stone and sintered ceramic alternatives are capturing minimalist specification share in Scandinavian and Japanese markets.
Strategic Opportunities
- India tier-one urban renovation:Mumbai and Delhi luxury condominium retrofits remain underpenetrated by international fixture brands due to distribution infrastructure gaps.
- Sensor-thermostatic convergence:Integration of TOTO-style proximity activation with Grohe-engineered temperature stability creates new product category white space.
- California Title 20 plumbing standards:State-level efficiency mandates are accelerating faster than federal timelines, rewarding early compliance investment with preferential specification status.
Industry Challenges
- Master alloy metallurgist scarcity:Precision brass formulation for patina consistency requires specialized foundry expertise concentrated in Wisconsin and Baden-Württemberg.
- 100,000-cycle valve certification timelines:Pressure-balancing durability testing extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Plumbing Fixtures Market |
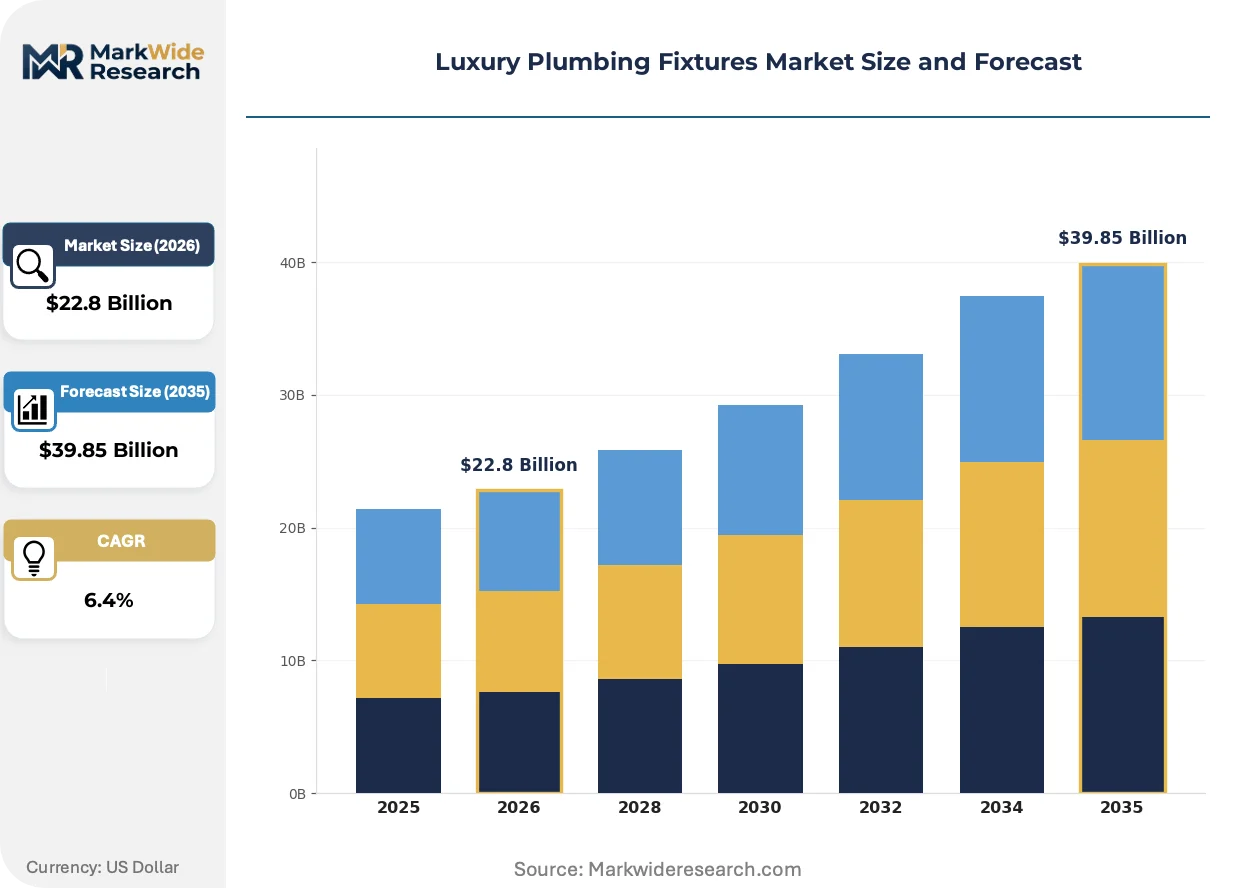
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Showers, Faucets, Sinks, Bathtubs Material: Brass, Stainless Steel, Bronze, Glass Design Style: Modern, Vintage, Minimalist, Art Deco Installation Type: Wall-mounted, Deck-mounted, Freestanding, Integrated |
| Companies Covered | Brizo, Perrin & Rowe, Kohler, Lacava, Crosswater London, Grohe, TOTO, Watermark Designs, Hansgrohe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Plumbing Fixtures Market Strategic Shifts & Innovations
Active sensor integration is decomposing the traditional separation between water delivery hardware and building automation systems, compressing the competitive set to include controls specialists alongside legacy fixture manufacturers.
Electrochemical deposition finishing is decomposing the cost structure of artisanal patina application. Automated PVD coating lines in Kohler's Wisconsin captive foundry now replicate hand-finished bronze variation at production scale. Hospitality procurement teams at Marriott and Four Seasons are specifying these finishes for portfolio-wide consistency. The technology is decomposing the premium previously commanded by small-batch European ateliers.
The EU Ecodesign Directive's expanding scope to thermostatic mixing valves is forcing recertification of entire product lines. Manufacturers must resubmit flow-rate and temperature stability documentation under harmonized testing protocols. German-engineered shower systems face the steepest compliance burden given their dominant specification share in EU hospitality projects.
Buyers in urban luxury condominiums are unbundling fixture specification from general contractor procurement. Direct engagement with architects and interior designers is displacing traditional wholesale distribution in Manhattan, London, and Singapore. This channel compression rewards brands with specification sales teams and digital visualization tools.
Luxury Plumbing Fixtures Market Segmentation
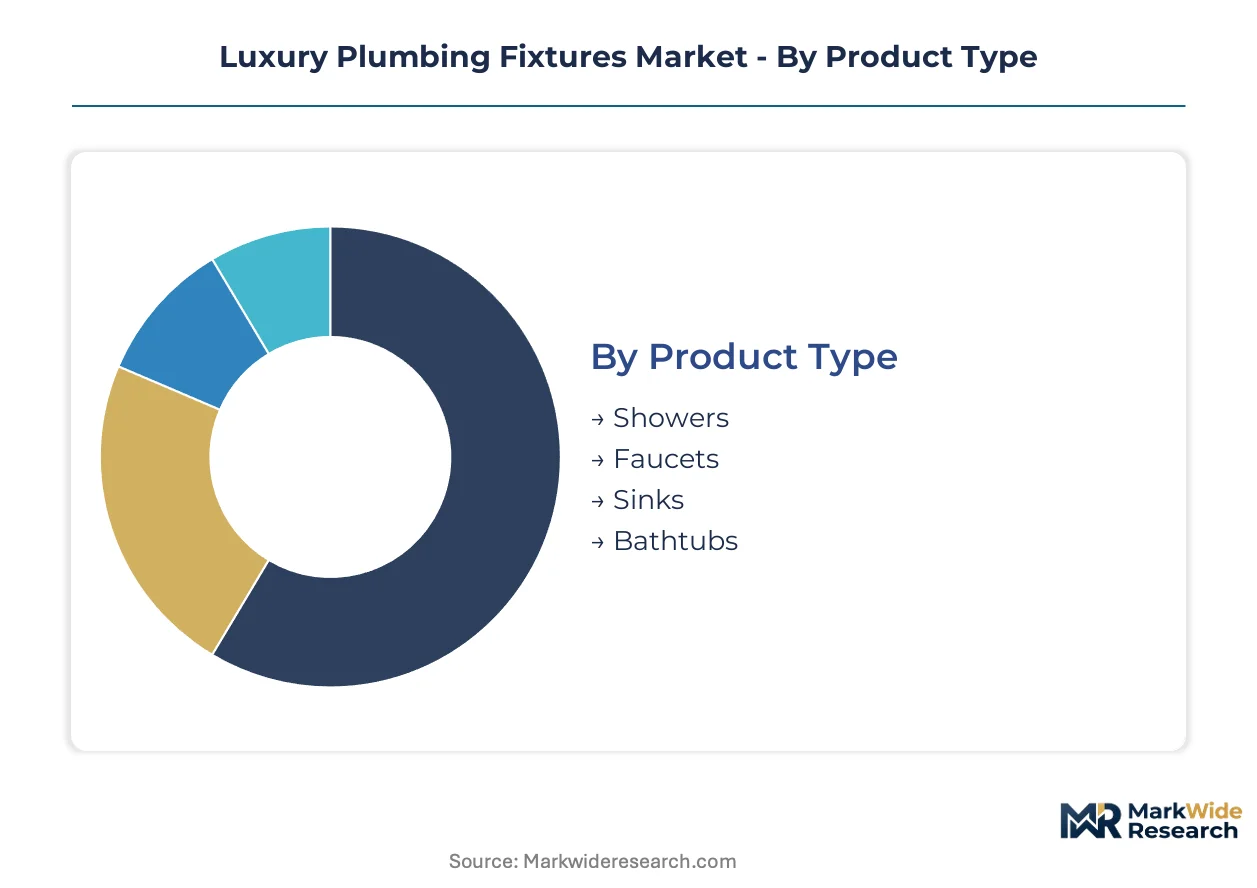
Luxury plumbing fixture procurement channels diverge sharply by segment, with specification-grade products flowing through architect-direct relationships while volume SKUs move through wholesale distribution. Understanding these pathway distinctions enables targeted channel investment and margin defense.
Product Type:
Channel concentration varies dramatically: showers and faucets dominate specification-direct procurement, while sinks and bathtubs retain stronger wholesale penetration.
- Showers:Thermostatic valve assemblies with 100,000-cycle durability ratings command the deepest specification involvement. Demand concentrates in Saudi Arabia's Neom and Red Sea Project developments where giga-project procurement justifies dedicated production lines.
- Faucets:Solid brass forging with sub-1.5 gallon per minute flow rates represents the engineering frontier. EPA WaterSense certification requirements in the United States are accelerating replacement cycles in existing luxury residential stock as owners seek compliant upgrades.
- Sinks:Vessel and undermount configurations serve distinct installation contexts.
- Bathtubs:Freestanding specifications accelerate in suburban estate construction while alcove variants dominate urban retrofits.
Showers dominate installed base. Faucets are where expansion concentrates.
Material:
Cost tier stratification separates captive-foundry producers from component assemblers, with alloy control determining margin capture.
- Brass:Copper-zinc alloys enable machining complexity and patina customization that command premium positioning. Wisconsin and Baden-Württemberg foundries concentrate metallurgical expertise for specification-grade consistency.
- Stainless Steel:Marine-grade 316L specifications create tier separation from 304-grade offerings in Miami and Dubai coastal high-rises where corrosion resistance is non-negotiable.
- Bronze:Electrochemical deposition finishing now replicates artisanal variation at production scale.
- Glass:Engineered stone and sintered ceramic alternatives are capturing specification share in Scandinavian and Japanese minimalist markets.
Brass dominates installed base. Glass is climbing the fastest among emerging specifications.
Design Style:
Customer type alignment shapes marketing investment, with modern and minimalist styles penetrating urban luxury condominiums while vintage and Art Deco serve heritage hospitality renovation.
- Modern:Clean lines and concealed hardware dominate Manhattan, London, and Singapore luxury condominium specifications where architects unbundle procurement from general contractors.
- Minimalist:Sensor-integrated surfaces and hidden controls align with Japanese-influenced smart fixture categories. TOTO-style proximity activation converges with thermostatic engineering in this white space.
- Vintage:Cross-handle and porcelain-lever details serve historic property renovation.
- Art Deco:Geometric patterns and stepped profiles target boutique hospitality in tier-one urban cores.
Modern dominates installed base. Minimalist is gaining share fastest among specification architects.
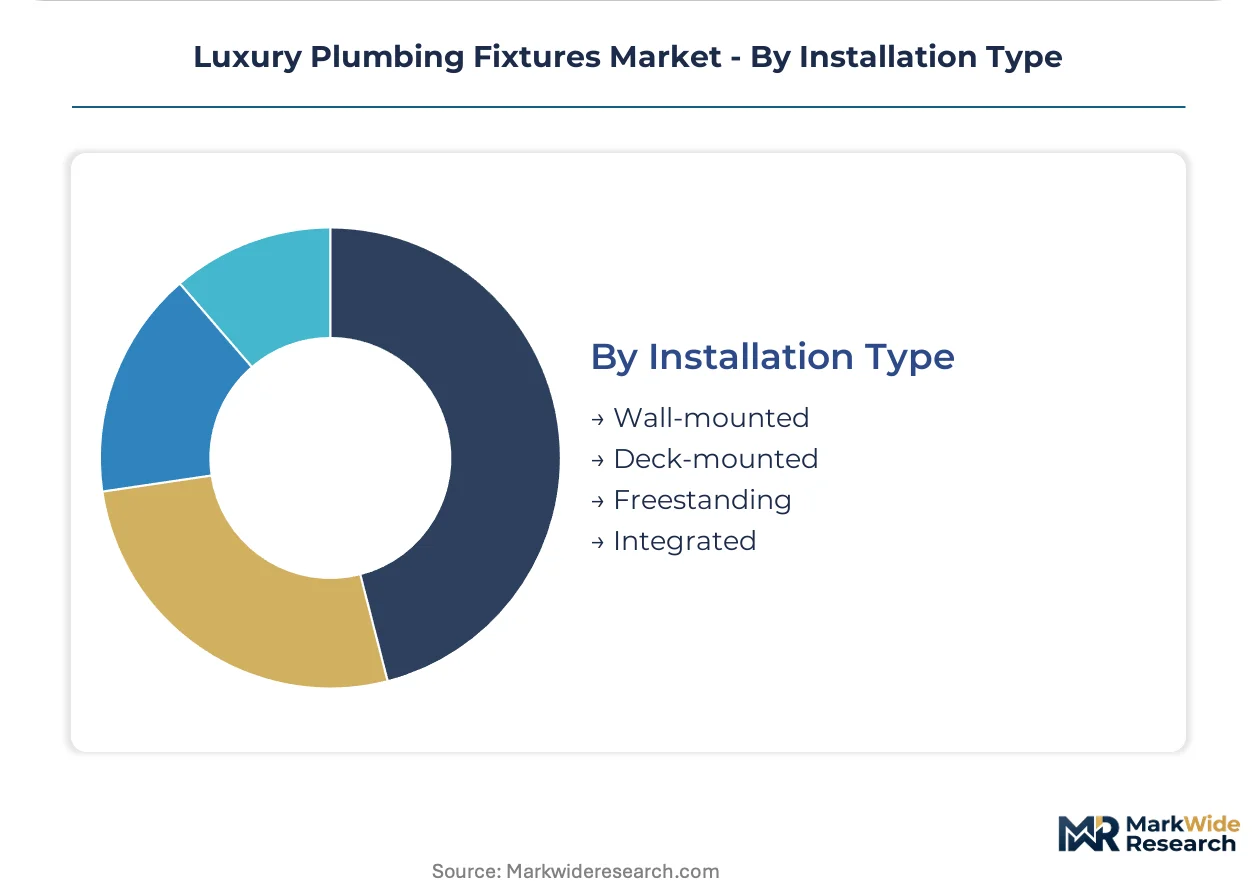
Installation Type:
Volume distribution tracks construction format, with wall-mounted and integrated systems penetrating vertical development while freestanding and deck-mounted accelerate in horizontal expansion.
- Wall-mounted:Concealed carriers and in-wall rough-in systems lead urban luxury condominiums where floor space commands premium valuation. China's tier-one urban renovation programs specify these configurations for space efficiency.
- Freestanding:Floor-mounted tub fillers and independent shower columns accelerate in suburban estate construction across Riyadh and Dubai high-end residential developments.
- Deck-mounted:Rim and ledge installations persist in traditional bathroom layouts.
- Integrated:Trough and seamless basin-wall combinations serve ultra-contemporary specifications.
Wall-mounted dominates installed base. Freestanding is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in luxury plumbing fixtures reveal a pronounced trade imbalance favoring manufacturing clusters with captive foundry capacity. Countries with precision metallurgy heritage dominate outbound shipment value, while high-end construction markets absorb premium imports regardless of domestic production scale.
United States
EPA WaterSense certification mandates below 1.5 gallons per minute are accelerating fixture replacement cycles in luxury residential stock. California's Title 20 plumbing standards extend efficiency thresholds beyond federal timelines, rewarding early compliance investment. Wisconsin's captive foundry clusters supply alloy consistency for specification-grade brass forging serving Manhattan and Miami high-rise developments.
Germany
Thermostatic shower system engineering concentrates in Baden-Württemberg industrial corridors where metallurgical expertise supports 100,000-cycle valve certification. The EU Ecodesign Directive's expanding scope to thermostatic mixing valves forces recertification of entire product lines under harmonized testing protocols. Stuttgart-based production facilities face the steepest compliance burden given their dominant specification share in EU hospitality projects.
China
Tier-one urban renovation programs in Shanghai and Beijing specify wall-mounted configurations for space efficiency in luxury condominium retrofits. GB standards for water efficiency add compliance layers for brands targeting domestic expansion. Pearl River Delta manufacturing clusters compete on volume production while Yangtze River Delta facilities develop precision forging capability for export-tier specifications.
Saudi Arabia
Neom and Red Sea Project giga-developments procure fixture packages at volumes justifying dedicated production lines and custom alloy development. SFDA certification requirements align with international plumbing standards for hospitality procurement. Riyadh's high-end residential developments are accelerating specification-grade fixture procurement ahead of Vision 2030 construction milestones.
Japan
Sensor-integrated smart fixture categories command premium positioning in Tokyo and Osaka luxury residential specifications. METI efficiency standards converge with consumer preference for high-pressure sensory experience in thermostatic engineering. Kanto region manufacturing clusters supply proximity activation technology that integrates with building automation systems.
Luxury Plumbing Fixtures Market Key Industry Players
Listed leaders compete with private specialists across specification-grade brass forging and thermostatic engineering dimensions, creating a tiered structure where scale advantages clash with artisanal positioning. Consolidation pressures concentrate among mid-tier producers lacking captive foundry capacity, while premium tiers fragment across heritage European ateliers and integrated Asian manufacturers. Three archetypes dominate: vertically integrated foundry-owners controlling alloy consistency, controls specialists converging on sensor-thermostatic integration, and design houses outsourcing precision manufacturing. Dominant competitive moves include backward integration into brass billet supply and geographic expansion through architect-direct specification teams.
Within the heritage European tier, Grohe and Hansgrohe exemplify German-engineered thermostatic positioning, while TOTO anchors Japanese-influenced smart fixture categories with integrated sensor technology. Kohler represents North American vertical integration through captive Wisconsin foundry capacity controlling alloy consistency across premium lines. These three occupy positions spanning the competitive spectrum from precision manufacturing to building automation convergence.
| Leading Market Players |
|---|
| Brizo |
| Perrin & Rowe |
| Kohler |
| Lacava |
| Crosswater London |
| Grohe |
| TOTO |
| Watermark Designs |
| Hansgrohe |
| Others |
Cost & Logistics Intelligence
Electrochemical deposition finishing replacing artisanal patina application simultaneously concentrates supply geography in Wisconsin and Baden-Württemberg captive foundries while collapsing the premium pricing previously commanded by small-batch European ateliers. This substitution dynamic compresses margin pools for mid-tier assemblers lacking alloy control while rewarding integrated manufacturers with pricing power across hospitality procurement portfolios.
Pricing Analysis
Architect-direct specification buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on WaterSense certification tier and captive foundry alloy consistency, with certified brass forging commanding substantial premiums over component-assembled alternatives. Cost compression in mid-tier forged products is intensifying because electrochemical deposition replicates hand-finished variation at scale. Hospitality procurement teams exhibit lowest price sensitivity due to portfolio-wide consistency requirements, while wholesale-distributed SKUs face highest pressure from private-label substitution.
Supply Chain Analysis
Strait of Hormuz transit underwrites copper concentrate flows from Chile and Peru to foundry clusters in Wisconsin, Germany, and Saudi Arabia's emerging Neom-adjacent facilities. Raw material sourcing draws from London Metal Exchange copper billet, precision master alloys, and 316L stainless steel for coastal specifications. Single-source vulnerability concentrates in Baden-Württemberg thermostatic valve engineering expertise. Distribution runs through architect-direct specification teams in Manhattan, London, and Singapore displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxury plumbing fixtures trace a cyclical recovery pattern tied to giga-project construction waves in Saudi Arabia and China's tier-one urban renovation programs. These capital-intensive development cycles create predictable demand surges that favor prepared suppliers.
For Market Incumbents: Secure captive foundry capacity expansion in Wisconsin or Baden-Württemberg to defend alloy consistency premiums against electrochemical deposition commoditization. Deepen specification sales team presence in Mumbai and Delhi to preempt emerging competitor channel establishment. Master alloy metallurgist scarcity represents the critical talent chokepoint requiring long-term employment contracts.
For New Entrants and Emerging Players: Differentiate on sensor-thermostatic convergence as TOTO-style proximity activation integrated with Grohe-engineered temperature stability remains underexploited white space. Target India's tier-one urban renovation segment where international brand distribution infrastructure gaps persist. Pursue architect-direct engagement models with digital visualization tools to bypass entrenched wholesale relationships.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors vertically integrated foundry-owners over component assemblers. Long-term viability over the next decade hinges on regulatory compliance capability as EPA and EU Ecodesign thresholds tighten progressively. Acquisition target archetype: mid-tier producers with established specification relationships but lacking captive alloy control, where backward integration unlocks margin expansion. Monitor copper-zinc alloy price volatility as the inflection indicator for margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Wisconsin and Baden-Württemberg alloy control secures specification-grade brass forging premiums against electrochemical deposition competition. |
| Sensor-Thermostatic Product Development | Integration of Japanese proximity activation with German temperature stability engineering captures unoccupied category white space. |
| Architect-Direct Specification Team Buildout | Manhattan, London, and Singapore channel compression rewards brands displacing traditional wholesale distribution relationships. |
| India Distribution Infrastructure Investment | Mumbai and Delhi luxury condominium retrofits remain underpenetrated by international fixture brands due to local channel gaps. |
| WaterSense and Ecodesign Pre-Certification | Early compliance with California Title 20 and EU thermostatic valve directives secures preferential specification status ahead of enforcement. |
Research Approach
Operator-level perspectives from specification sales directors, hospitality procurement managers, foundry metallurgists, and architect studio principals anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of listed fixture manufacturers, EPA WaterSense certification databases, EU Ecodesign Directive implementation documents, and London Metal Exchange copper pricing records. Bottom-up project pipeline assessment across Saudi giga-developments and China urban renovation programs triangulated with top-down market sizing.
Sensitivity analysis around copper price volatility, regulatory timeline acceleration, and substitution elasticity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, installation configuration, design style, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new construction fixture intensity ratios. Industry-specific forecast inputs encompassed 100,000-cycle valve certification timelines and architect procurement unbundling penetration rates.
Forecasts assume regulatory continuity in EPA WaterSense, EU Ecodesign, and California Title 20 regimes; material policy shifts would require re-modeling flow-rate threshold impacts on replacement demand. Scenario risks include brass input cost spikes, master alloy metallurgist supply constraints, and hospitality sector demand contraction. Practitioners should keep alternative scenarios live as giga-project completion schedules and copper concentrate shipping routes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Shower Tray Market