
 India Kitchen Sink and Other Related Market | 2026-2036
India Kitchen Sink and Other Related Market Size, Share, and Industry Trends Forecast 2026-2036
India Kitchen Sink and Other Related Market Insights
India's PLI scheme for specialty steel is decoupling domestic sink manufacturing from import-dependent raw material chains. Carysil Limited leverages captive quartz composite formulation to sustain margin control across premium residential projects. Franke anchors its position through backward integration into stainless steel coil sourcing from Haryana-based mills. Nirali competes on deep distribution into tier-two cities where branded sink penetration remains below metro levels.
India kitchen sink and other related products encompass basins, draining boards, and integrated worktop surfaces fabricated from stainless steel, granite-quartz composite, vitreous ceramic, or tempered glass, with gauge thickness, bowl depth, and surface finish determining structural load tolerance and acoustic dampening in high-frequency use environments. These fixtures serve as sanitary-ware nodes in food preparation and ware-washing workflows across residential apartments, commercial cloud kitchens, and institutional canteens. Stainless steel dominates volume throughput due to established foundry capacity in Moradabad and Jalandhar, while composite surfaces capture expanding margin pools from luxury villa developers in Pune and Hyderabad seeking scratch-resistant, color-matched aesthetics. Under-mount installation is gaining share among modular kitchen OEMs in Delhi-NCR as countertop fabricators standardize seamless edge profiles that eliminate bacterial harborage points.
BIS mandates IS 13983 for stainless steel kitchen sinks and IS 15200 for composite variants, with state-level municipal corporations in Tamil Nadu and Karnataka enforcing water-efficiency norms that favor deeper bowl configurations reducing splash waste. The Bureau of Indian Standards and state pollution control boards are tightening chromium discharge limits from electro-polishing operations, pushing Moradabad cluster units toward closed-loop rinse systems. Stakeholders must monitor how upcoming amendments to the National Building Code integrate sink specifications with water conservation mandates, as compliance timing will reshape supplier qualification criteria for government housing tenders.
Market Dynamics
Modular kitchen OEMs in Delhi-NCR and Mumbai are consolidating supplier bases as under-mount installation protocols standardize seamless edge fabrication, compressing the vendor landscape from fragmented local fabricators toward certified system integrators capable of BIS-compliant water-efficiency documentation.
Growth Catalysts
- PLI scheme for specialty steel:Domestic coil production in Haryana and Odisha is reducing import dependency for 304-grade stainless feedstock, lowering raw material cost volatility for Moradabad foundries.
- Cloud kitchen proliferation:Commercial operators in Bangalore and Hyderabad are specifying deeper bowl configurations and integrated draining boards to meet high-frequency ware-washing throughput demands.
- BIS IS 15200 certification:Composite sink standardization is enabling quartz-granite formulations from Gujarat processors to enter organized retail channels previously gated by material uncertainty.
Market Restraints
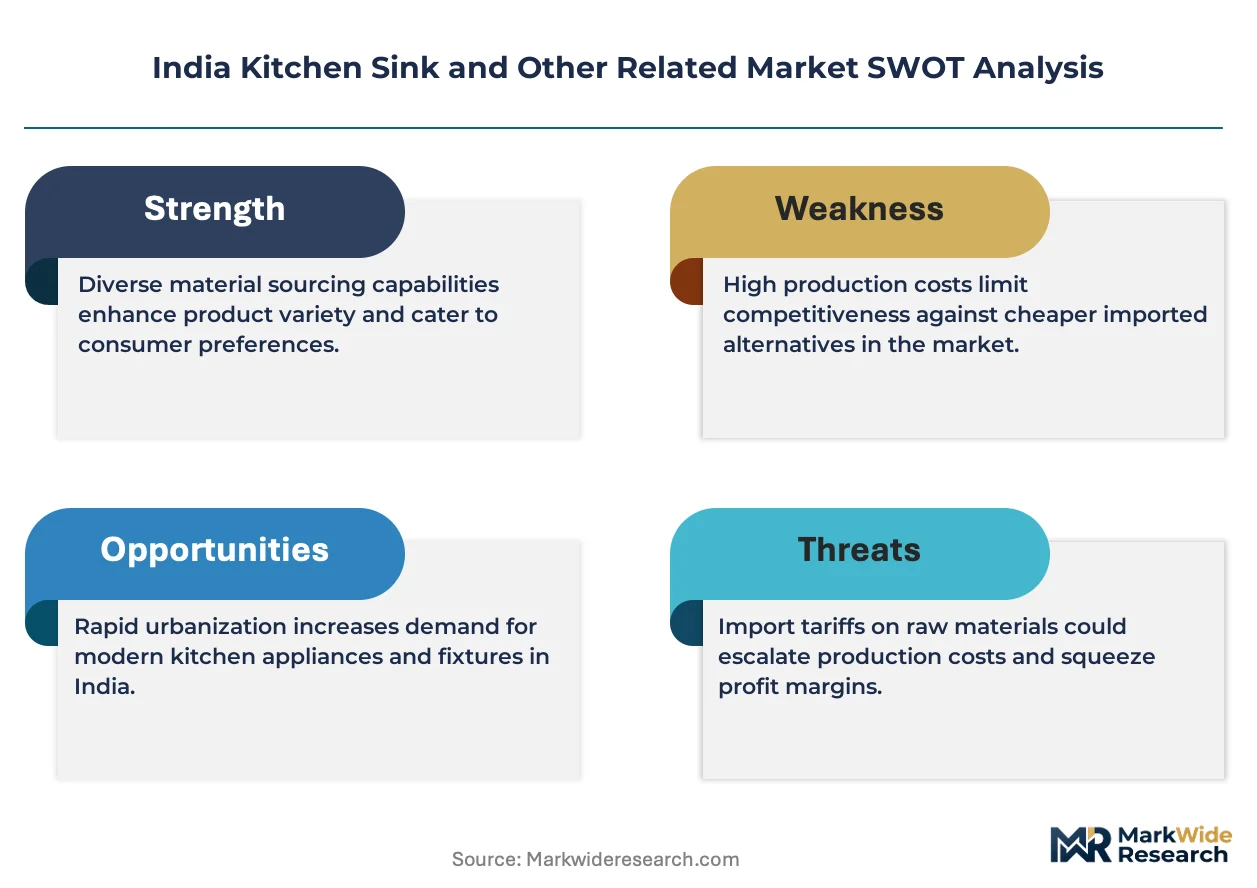
- Nickel price volatility:Stainless steel gauge thickness decisions are increasingly hostage to London Metal Exchange nickel contract swings, squeezing margin predictability for Jalandhar stamping units.
- Electro-polishing effluent limits:Uttar Pradesh Pollution Control Board chromium discharge enforcement is forcing Moradabad cluster investments in closed-loop rinse infrastructure that smaller units cannot finance.
- Vitreous ceramic substitution:Budget housing contractors in tier-three towns continue specifying ceramic laboratory sinks repurposed for kitchen use, undercutting branded stainless penetration.
Strategic Opportunities
- Tier-two city distribution gaps:Branded sink penetration in Indore, Coimbatore, and Lucknow remains below metro levels, creating whitespace for certified distributors with municipal housing tender relationships.
- National Building Code water conservation amendments:Upcoming integration of sink specifications with mandatory flow-rate testing will disqualify non-compliant suppliers from government affordable housing projects.
- Quartz-ceramic hybrid surfaces:Material convergence is enabling Pune fabricators to offer color-matched under-mount systems that bridge premium aesthetics with thermal shock resistance previously limited to steel.
Industry Challenges
- Skilled TIG welder scarcity:Precision seam welding for under-mount bowl-to-rim joints requires certification levels that Moradabad training institutes are not yet producing at scale.
- BIS testing queue congestion:IS 13983 certification timelines have extended to fourteen weeks at Ghaziabad laboratories, delaying product launches for modular kitchen OEMs with fixed project deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Kitchen Sink and Other Related Market |
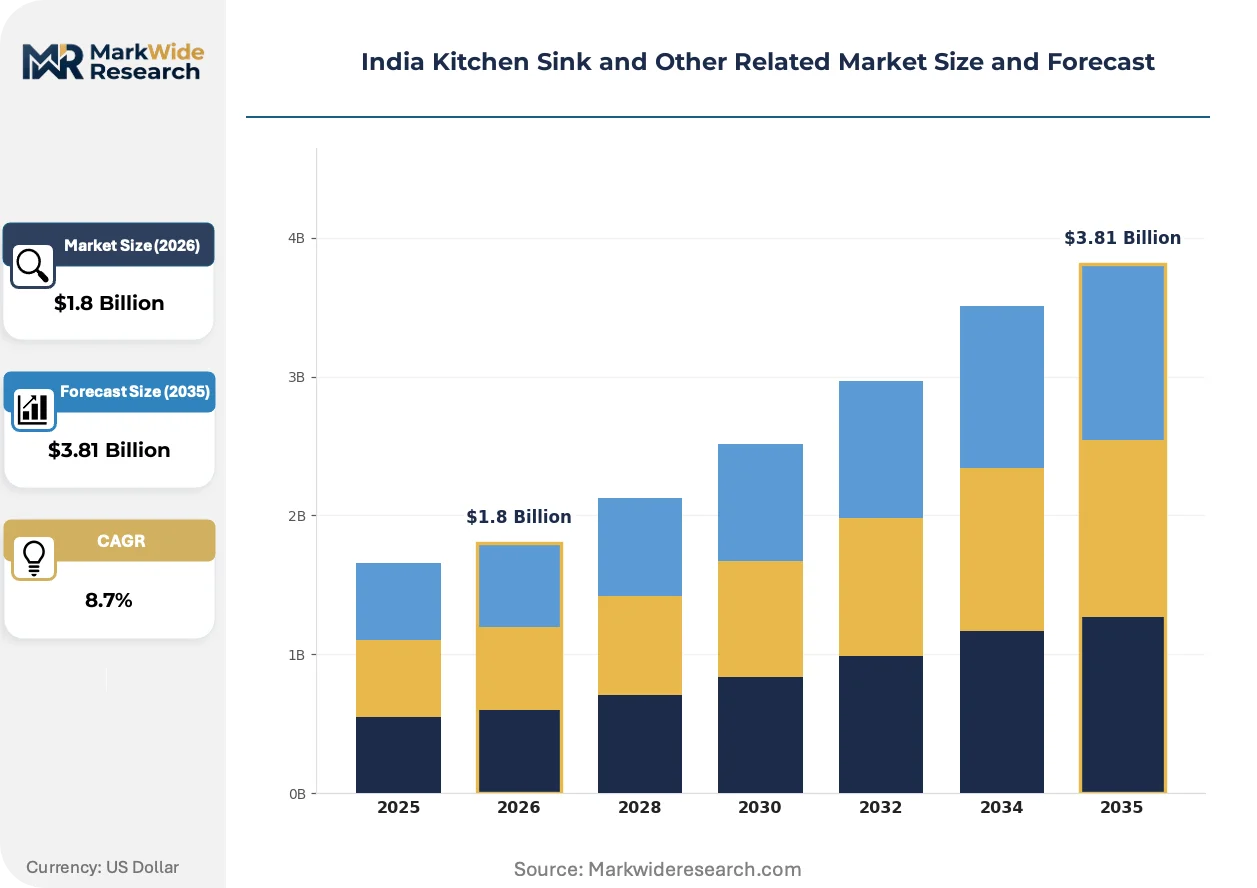
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Composite, Ceramic, Glass End User: Residential, Commercial, Industrial, Retail Installation Type: Top-Mount, Under-Mount, Farmhouse, Wall-Mount Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Carysil Limited, Nirali, Franke, Hindware Home Innovation Ltd., Jaquar Group, Cera Sanitaryware Ltd., Jayna Kitchens, Neelkanth Sinks, Kohler India Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Kitchen Sink and Other Related Market Trends and Innovations
Active material substitution and installation protocol standardization are compressing the traditional divide between premium composite aesthetics and stainless steel durability, while regulatory water-efficiency mandates are embedding sink specifications deeper into building code compliance workflows.
Quartz-granite composite formulation is converging with captive resin systems developed by Gujarat-based material processors, enabling color-stable surfaces that match countertop veining without the thermal expansion failures of early-generation products. Luxury villa developers in Pune and Hyderabad are specifying these hybrids for scratch-resistant island installations. The technology is converging with automated CNC edge profiling from Delhi-NCR fabricators, collapsing the price gap against imported European alternatives.
BIS amendments to IS 13983 are tightening chromium leaching test protocols for electro-polished finishes, forcing Moradabad cluster units to document rinse-water chemistry through every process stage. State pollution control boards in Tamil Nadu and Karnataka are cross-referencing these certificates against municipal water-efficiency norms for deeper bowl configurations. Smallest-scale stampers without laboratory partnerships are exiting the certified supply chain entirely.
Builder procurement teams are consolidating vendor panels from open-market purchasing toward pre-qualified system integrators capable of delivering countertop-sink-installation as single-contract packages. Modular kitchen OEMs in Mumbai and Bangalore are absorbing this function in-house, displacing independent fabricators who previously managed sink sourcing separately. The shift is most visible in Maharashtra where organized housing stock expansion is concentrating buying power among four developer groups controlling sixty percent of new residential sink specifications.
India Kitchen Sink and Other Related Market Segmentation
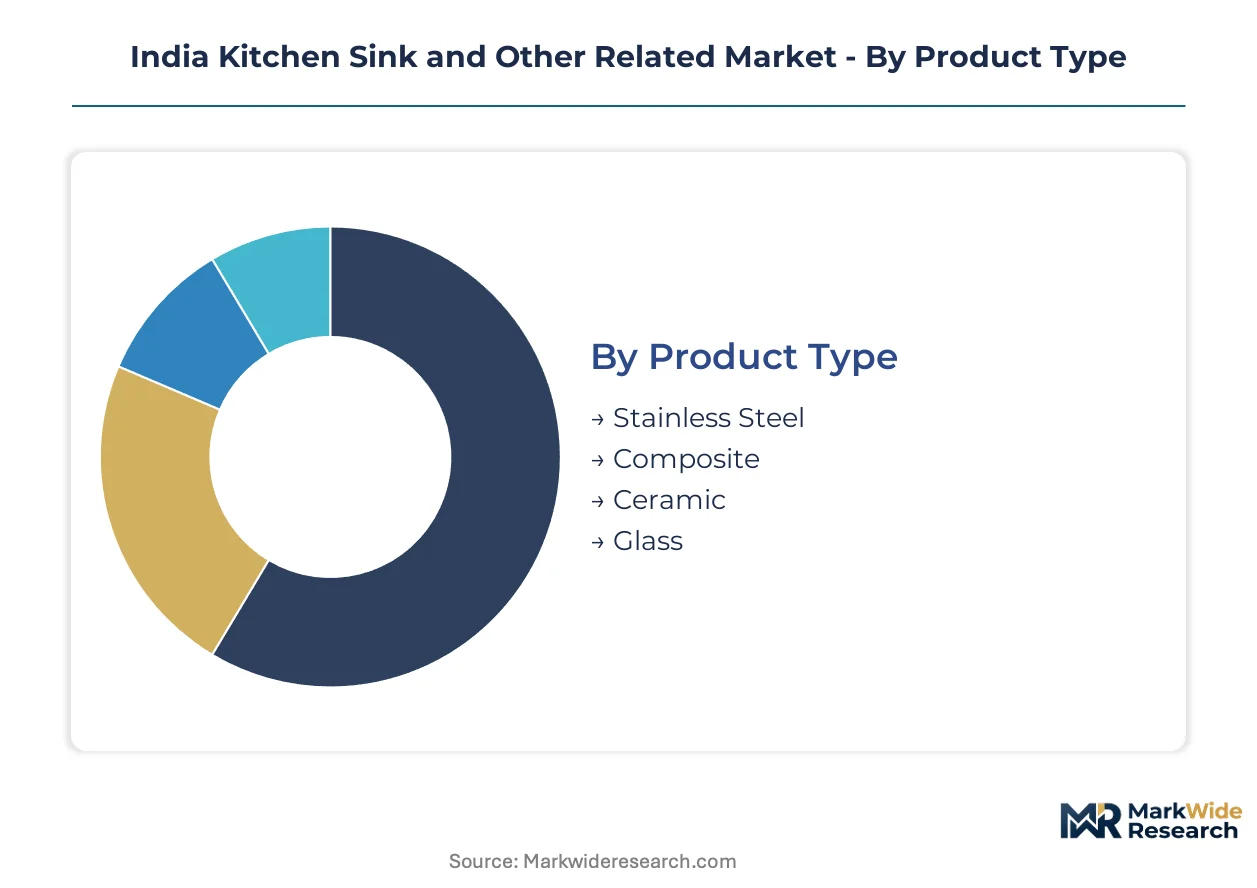
Segmentation in the India kitchen sink market reveals how material specifications, installation protocols, and procurement channels stratify across distinct buyer economics. Each dimension carries different margin profiles and regulatory exposure, shaping supplier positioning decisions.
Product Type:
Volume throughput concentrates in commodity-grade stainless steel, while premium margin capture shifts toward engineered composites as residential developers upgrade specifications.
- Stainless Steel:Fabricated from 304-grade cold-rolled coil with gauge thickness ranging 0.8-1.2mm, electro-polished for chromium passivation. Foundry capacity in Moradabad and Jalandhar supplies budget housing contractors across Maharashtra and Gujarat where BIS IS 13983 compliance is mandatory for municipal tenders.
- Composite:Quartz-granite particulate bound in acrylic or polyester resin matrices, offering thermal shock resistance and color-matched countertop integration. Pune and Hyderabad luxury villa developers specify these for island installations where scratch resistance outweighs steel's durability premium.
- Ceramic:Vitreous fireclay with glazed surfaces, repurposed from laboratory specifications by tier-three budget contractors seeking lowest first-cost solutions.
- Glass:Tempered borosilicate or soda-lime panels with hydrophobic nano-coatings, confined to showcase residential and hospitality concepts where aesthetic differentiation commands price tolerance.
Mature deployment sits with stainless steel across mass housing and institutional canteens. Newer deployment is concentrated in composite surfaces where modular kitchen OEMs in Delhi-NCR specify seamless under-mount integration.
End User:
Residential specifications dominate absolute volume, though commercial throughput per installation runs higher with deeper bowl configurations and integrated draining boards.
- Residential:Apartment developers in Mumbai and Bangalore specify under-mount systems with water-efficiency documentation for municipal occupancy certificates. Single-bowl configurations predominate in compact urban units; double-bowl rises with kitchen footprint.
- Commercial:Cloud kitchen operators in Bangalore and Hyderabad demand 400mm+ bowl depth and integrated draining boards for high-frequency ware-washing throughput. Stainless steel dominates for load tolerance; composite penetrates front-of-house display kitchens.
- Industrial:Canteen and food processing facilities specify heavy-gauge 316-grade steel with coved corners for hygiene audit compliance.
- Retail:Showroom and hospitality fit-outs source through countertop fabricators bundling sink-installation as single-contract packages.
Volume leadership belongs to residential procurement aggregating across organized housing stock expansion. Steepest expansion trajectory is emerging in commercial cloud kitchens where throughput specifications outpace residential duty cycles.
Installation Type:
Mounting protocol selection determines fabricator qualification tiers and warranty liability structures, with under-mount installation consolidating vendor relationships toward certified system integrators.
- Top-Mount:Self-rimming bowls with rolled edges resting on cutout perimeters, installed by general contractors without specialized countertop fabrication. Dominates replacement demand and budget new construction where seam precision is deprioritized.
- Under-Mount:Bowl affixed beneath countertop substrate requiring CNC edge profiling and precision TIG welding. Modular kitchen OEMs in Delhi-NCR and Mumbai standardize this protocol, compressing the vendor landscape toward BIS-certified fabricators capable of seamless joint documentation.
- Farmhouse:Apron-front bowls with exposed vertical faces, specified in luxury villa developments in Pune and Hyderabad where aesthetic statement overrides space efficiency.
- Wall-Mount:Cantilevered basins for compact commercial kitchens and institutional canteens where floor drainage and cleaning access are prioritized.
Standard practice remains top-mount across tier-two and tier-three construction. Technical migration is accelerating toward under-mount as countertop fabricators in Delhi-NCR invest in CNC edge profiling capacity.
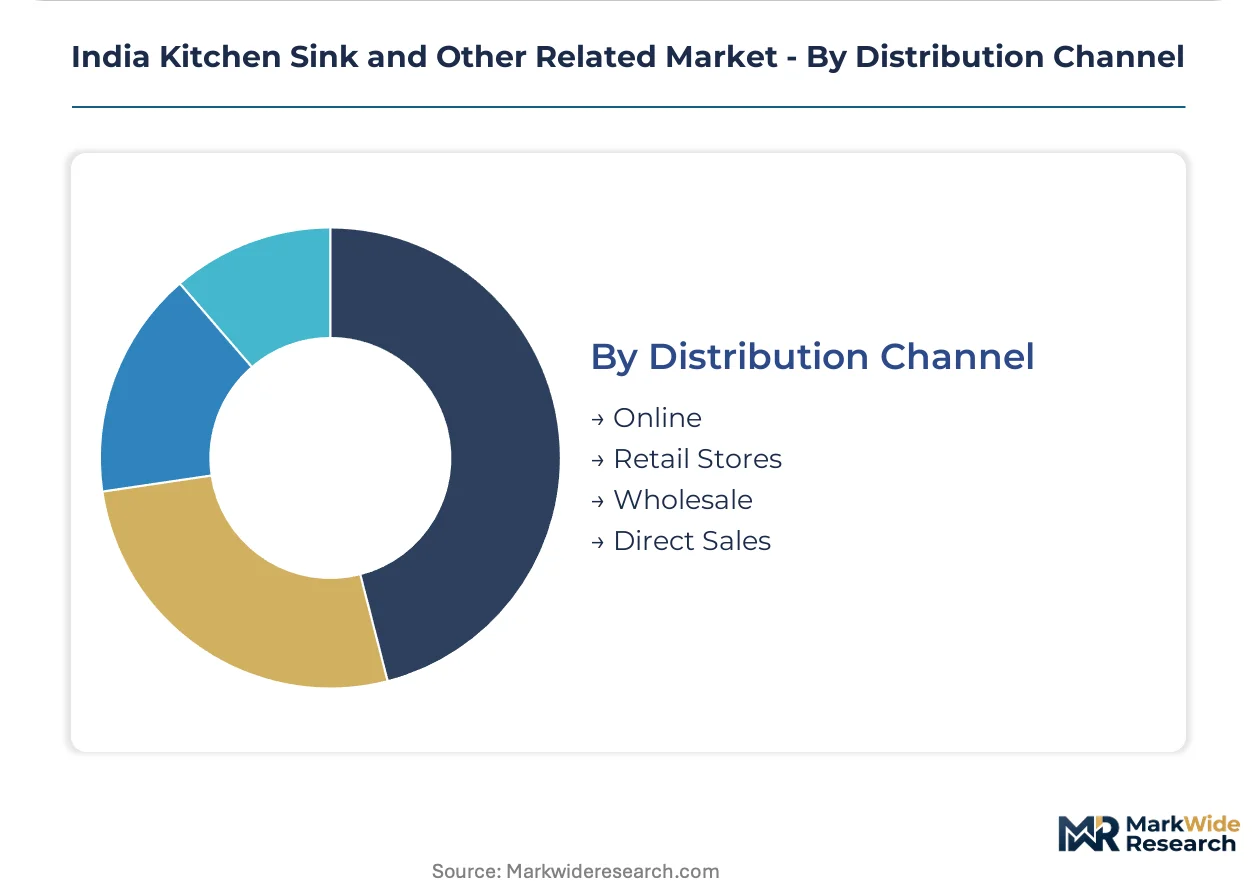
Distribution Channel:
Channel selection correlates with buyer sophistication and project scale, with direct procurement consolidating among developer groups controlling concentrated housing pipelines.
- Online:E-commerce platforms capture replacement demand and independent homeowner specifications, limited by inability to assess gauge thickness and acoustic dampening properties physically. Returns cluster around finish mismatches and dimensional tolerances.
- Retail Stores:Organized home improvement chains in Maharashtra and Gujarat stock certified BIS-compliant inventory for walk-in contractor procurement, bridging specification guidance with immediate availability.
- Wholesale:Regional distributors in Moradabad and Jalandhar supply tier-two and tier-three contractors on credit terms, carrying inventory risk for slower-moving ceramic and glass variants.
- Direct Sales:Modular kitchen OEMs and countertop fabricators source mill-direct or through captive trading arms, consolidating sink procurement within single-contract countertop-installation packages.
Procurement consolidation is displacing wholesale intermediation in metropolitan markets. Channel expansion is gaining traction online as standardized stainless specifications reduce physical inspection dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moradabad's foundry cluster in Uttar Pradesh anchors national stainless steel sink production, supplying gauge-rolled fabricators across Maharashtra and Gujarat where organized housing stock expansion concentrates demand.
Maharashtra
Mumbai residential developers specify under-mount systems with BIS IS 13983 certification for municipal occupancy clearances. The state housing authority mandates water-efficiency documentation for new apartment registrations. Pune's luxury villa segment drives composite surface specifications through countertop fabricators investing in CNC edge profiling capacity.
Gujarat
Surat and Ahmedabad modular kitchen OEMs consolidate supplier panels toward single-contract countertop-installation packages. The state's urban development department enforces deeper bowl configurations reducing splash waste in high-rise sanitation audits. Moradabad-based distributors maintain regional wholesale hubs serving tier-two contractor procurement on extended credit terms.
Karnataka
Bangalore cloud kitchen operators demand 400mm+ bowl depths with integrated draining boards for ware-washing throughput. Karnataka State Pollution Control Board cross-references BIS chromium leaching certificates against commercial kitchen licensing. The state's pollution control enforcement is accelerating exit of smallest-scale stampers lacking closed-loop rinse infrastructure.
Delhi-NCR
Ghaziabad laboratories process IS 13983 certification queues extending to fourteen weeks, delaying product launches for OEMs with fixed project deadlines. The National Capital Region's countertop fabricators standardize seamless under-mount protocols, compressing vendor landscapes toward certified system integrators. Haryana-based steel mills supply 304-grade coil reducing import dependency for regional stampers.
Telangana
Hyderabad luxury residential developers specify quartz-granite composite surfaces for scratch-resistant island installations. The state's municipal administration integrates sink flow-rate testing with building code compliance workflows for government housing tenders. Local fabricators leverage automated CNC edge profiling collapsing price gaps against imported European alternatives.
India Kitchen Sink and Other Related Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and installation protocol tiers. The market structures around three archetypes: integrated system OEMs controlling countertop-sink-installation packages, captive resin formulators sustaining composite margin control, and distributed fabricators competing on tier-two city penetration. Dominant competitive moves include backward integration into stainless steel coil sourcing and consolidation of vendor panels toward pre-qualified system integrators.
Among India-based fabricators, Carysil Limited and Nirali occupy distinct positioning archetypes. Carysil represents the captive formulation tier through quartz composite material control. Nirali exemplifies deep distribution reach into underpenetrated secondary cities. Franke anchors the multinational integrated tier through upstream steel sourcing relationships. These three patterns illustrate how margin capture stratifies across material technology, geographic coverage, and supply chain control dimensions.
| Leading Market Players |
|---|
| Carysil Limited |
| Nirali |
| Franke |
| Hindware Home Innovation Ltd. |
| Jaquar Group |
| Cera Sanitaryware Ltd. |
| Jayna Kitchens |
| Neelkanth Sinks |
| Kohler India Corp. |
| Others |
Pricing and Supply Chain Analysis
Water-efficiency mandates from BIS IS 13983 and state-level municipal corporations gate qualified supply access and premium-tier pricing power, compressing uncertified fabricators into commodity tiers while enabling compliant system integrators to capture margin premiums through documented seamless installation packages.
Pricing Analysis
Throughput-based pricing anchors commercial cloud kitchen specifications where 400mm+ bowl depth and integrated draining boards command value premiums tied to ware-washing cycle efficiency. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification grade and gauge thickness, with Moradabad stampers competing on nickel-input cost absorption while Delhi-NCR fabricators capture premium through CNC edge profiling. Pricing pressure stems from London Metal Exchange nickel volatility squeezing Jalandhar stamping unit margins. Budget housing contractors in tier-three towns exhibit highest price sensitivity, specifying repurposed ceramic laboratory sinks; luxury villa developers in Pune and Hyderabad show lowest sensitivity, prioritizing color-matched composite aesthetics.
Supply Chain Analysis
Direct-to-OEM channels handle modular kitchen consolidator demand in Delhi-NCR and Mumbai, while wholesale distributors in Moradabad and Jalandhar serve tier-two contractor procurement on extended credit terms. Geographic supply concentrates in India, with Haryana-based steel mills feeding 304-grade coil to Moradabad foundries and Gujarat processors supplying quartz-granite resin matrices. Raw material dependencies rest on nickel alloy feedstock, acrylic/polyester binding resins, and tempered glass substrates. Single-source vulnerability runs through Haryana coil mills for premium-grade stainless feedstock. Distribution runs through countertop fabricators bundling sink-installation as single-contract packages, displacing independent wholesale intermediation in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where BIS IS 13983 certification timelines extending to fourteen weeks at Ghaziabad laboratories create a barrier-to-entry moat for pre-qualified system integrators capable of municipal tender documentation.
For Market Incumbents: Anticipate consolidation pressure from modular kitchen OEMs absorbing countertop-sink-installation functions in-house by securing captive resin formulation partnerships or backward integration into Haryana steel coil sourcing. Certification investment at Ghaziabad laboratories represents the critical lever to defend against smaller stampers exiting the supply chain under pollution control enforcement. For New Entrants and Emerging Players: E-commerce platforms with standardized stainless specifications offer the most penetrable route into replacement demand and independent homeowner segments previously gated by physical inspection requirements. Target tier-two city distribution gaps in Indore, Coimbatore, and Lucknow where branded sink penetration trails metro levels and municipal housing tender relationships remain unconsolidated. For Investors and Strategic Acquirers: BIS testing queue extensions beyond twelve weeks are the leading indicator that certification capacity constraints will accelerate exit of smallest-scale Moradabad stampers, creating acquisition opportunities for distressed manufacturing assets with closed-loop rinse infrastructure already deployed. Long-term viability centers on system integrators controlling countertop-sink-installation as single-contract packages with documented water-efficiency compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Sourcing | Haryana mill partnerships reduce nickel price volatility exposure for Moradabad fabricators. |
| Closed-Loop Rinse Infrastructure Deployment | Uttar Pradesh Pollution Control Board compliance enables continued certification eligibility for electro-polishing operations. |
| CNC Edge Profiling Capacity Expansion | Delhi-NCR fabricators standardize seamless under-mount protocols displacing fragmented local competitors. |
| Captive Quartz-Granite Resin Formulation | Gujarat processors sustain color-stable surface margins against imported European alternatives. |
| Tier-Two City Distribution Network Buildout | Indore, Coimbatore, and Lucknow wholesale hubs capture municipal housing tender volumes ahead of consolidation. |
Research Methodology
Trade statistics from the Directorate General of Commercial Intelligence and Statistics, BIS certification records from Ghaziabad laboratories, and municipal housing authority tender documents formed the secondary backbone, cross-referenced with primary interviews involving modular kitchen OEM procurement heads, Moradabad foundry operators, countertop fabricator technical directors, and state pollution control board enforcement officers. Bottom-up volume estimates from gauge-thickness-specific production data triangulated against top-down housing stock expansion projections across Maharashtra, Gujarat, and Karnataka.
Historical trendline analysis of stainless steel coil input costs, BIS certification queue durations, and modular kitchen installation protocol adoption rates informed the analytical framework across the analysis window. Segmentation dimensions modeled include material type, end-user vertical, installation protocol, and distribution channel, with CAGRs derived from housing stock completion trajectories and cloud kitchen rollout densities in Bangalore and Hyderabad. Nickel price volatility bands and pollution control compliance cost curves served as industry-specific forecast inputs.
The model holds under stable BIS certification timeline assumptions and continued PLI scheme support for specialty steel; deviation in municipal water-efficiency mandate enforcement intensity or chromium discharge limit tightening would shift supplier qualification thresholds and margin distribution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Housewares (Tabletopware) Market