
 Australia Kitchen Furniture Market | 2026-2036
Australia Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Kitchen Furniture Market Outlook
The gap between premium bespoke joinery and flat-pack commodity offerings is realigning how Australian manufacturers structure their production and distribution. Farmers Kitchens leverages its vertical integration to control timber sourcing and finishing quality for high-end residential projects. Polytec sustains competitive pressure through engineered surface technologies that bridge the mid-market segment.
Australia kitchen furniture encompasses fixed and modular storage, preparation, and service units engineered from timber substrates, engineered stone, laminates, and metals to residential and commercial food preparation environments. Cabinet carcasses typically employ moisture-resistant particleboard with thermolaminated or polyurethane finishes meeting AS/NZS 4266 structural standards. The cabinets segment anchors volume demand through renovation-driven replacement cycles, while islands command premium positioning as open-plan kitchen centrepieces. Laminate surfaces dominate material selection for cost-sensitive projects, though engineered stone countertops capture margin concentration in premium renovations.
The Australian Building Codes Board administers the National Construction Code, which mandates bushfire attack level compliance for kitchen external joinery in designated zones, while the ACCC enforces product safety standards for furniture stability and formaldehyde emissions. These frameworks elevate compliance costs for import-dependent suppliers while creating certification barriers that favor domestic manufacturers with established testing relationships. Stakeholders must track impending NCC updates on condensation management and thermal bridging, as these will reshape cabinet specification requirements for new builds and substantial renovations alike.
Market Dynamics
Renovation-driven replacement cycles dominate Australian kitchen furniture demand, with owner-occupiers prioritizing integrated storage systems and energy-efficient appliance housing that complies with tightening National Construction Code provisions.
Growth Catalysts
- Heritage Renovation Pipeline:Inner-ring suburbs in Greater Sydney and Melbourne generate sustained demand for custom joinery that respects architectural character while meeting modern functional requirements.
- NCC Energy Efficiency Mandates:The National Construction Code's condensation management and thermal bridging provisions are accelerating specification of high-performance cabinet materials in new residential construction.
- Apartment Conversion Activity:Multi-residential developers are specifying modular kitchen systems that reduce on-site installation time and labor cost in high-density urban projects.
Market Restraints
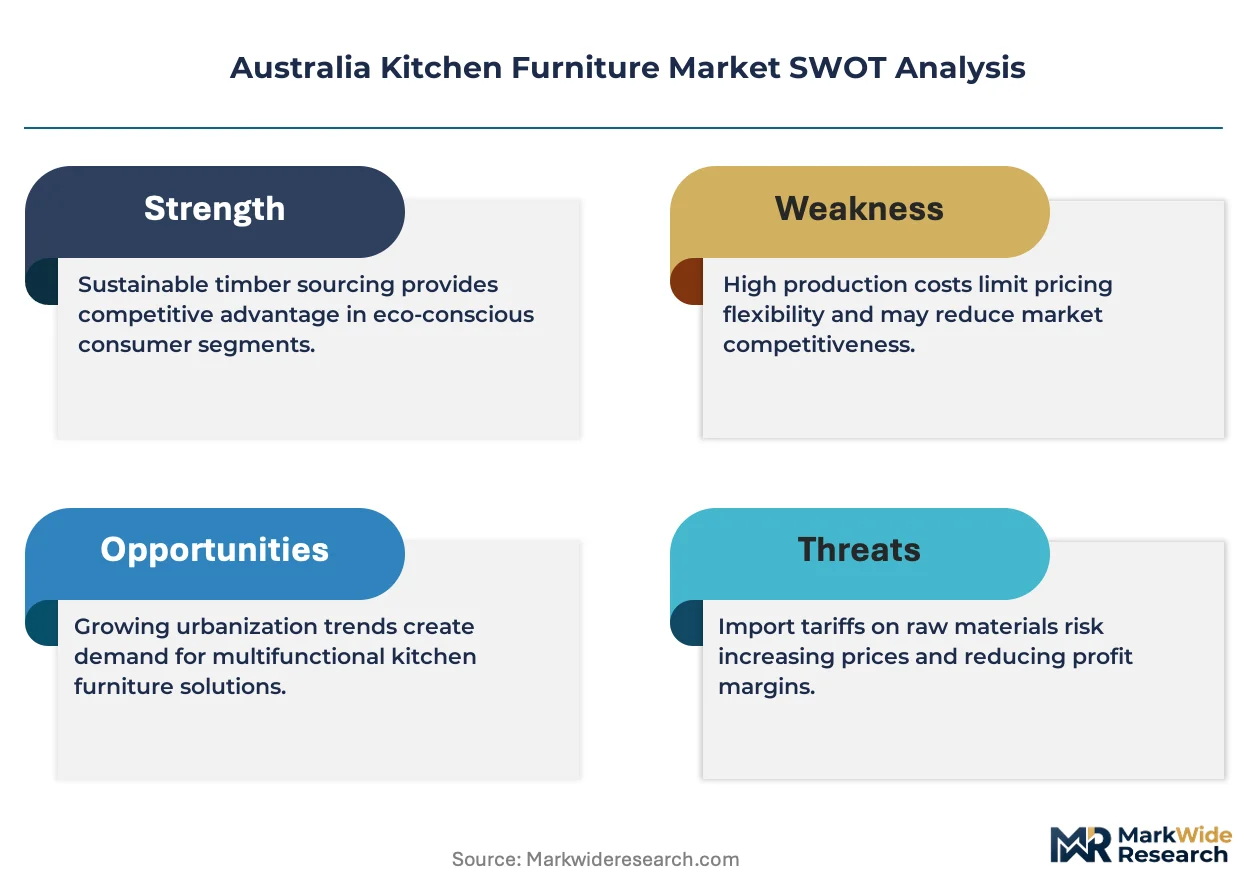
- Import Supply Concentration:Flat-pack commodity suppliers dependent on Southeast Asian manufacturing face extended lead times and freight cost volatility that compress margin flexibility.
- Formaldehyde Emission Standards:ACCC enforcement of product safety standards for furniture stability and emissions creates certification barriers that favor established domestic testing relationships.
- Moisture-Resistant Substrate Costs:Particleboard and MDF meeting AS/NZS 4266 structural standards command premium pricing that constrains cost-sensitive renovation segments.
Strategic Opportunities
- Bushfire Attack Level Zones:The Australian Building Codes Board's BAL compliance requirements for external joinery in designated regions create specialized demand for fire-rated timber and metal cabinet systems.
- Engineered Stone Countertops:Premium renovation projects are specifying quartz surfaces that capture higher margin concentration compared to laminate alternatives.
- Direct-to-Builder Digital Platforms:Online specification tools that integrate with project management software are reducing friction in multi-residential procurement workflows.
Industry Challenges
- Skilled Joinery Labor Scarcity:Qualified cabinetmakers capable of executing high-end bespoke work command wage premiums that strain project economics for mid-tier manufacturers.
- Legacy Inventory Systems:Established producers face integration complexity when retrofitting automated cutting and edge-banding equipment into existing production footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Kitchen Furniture Market |
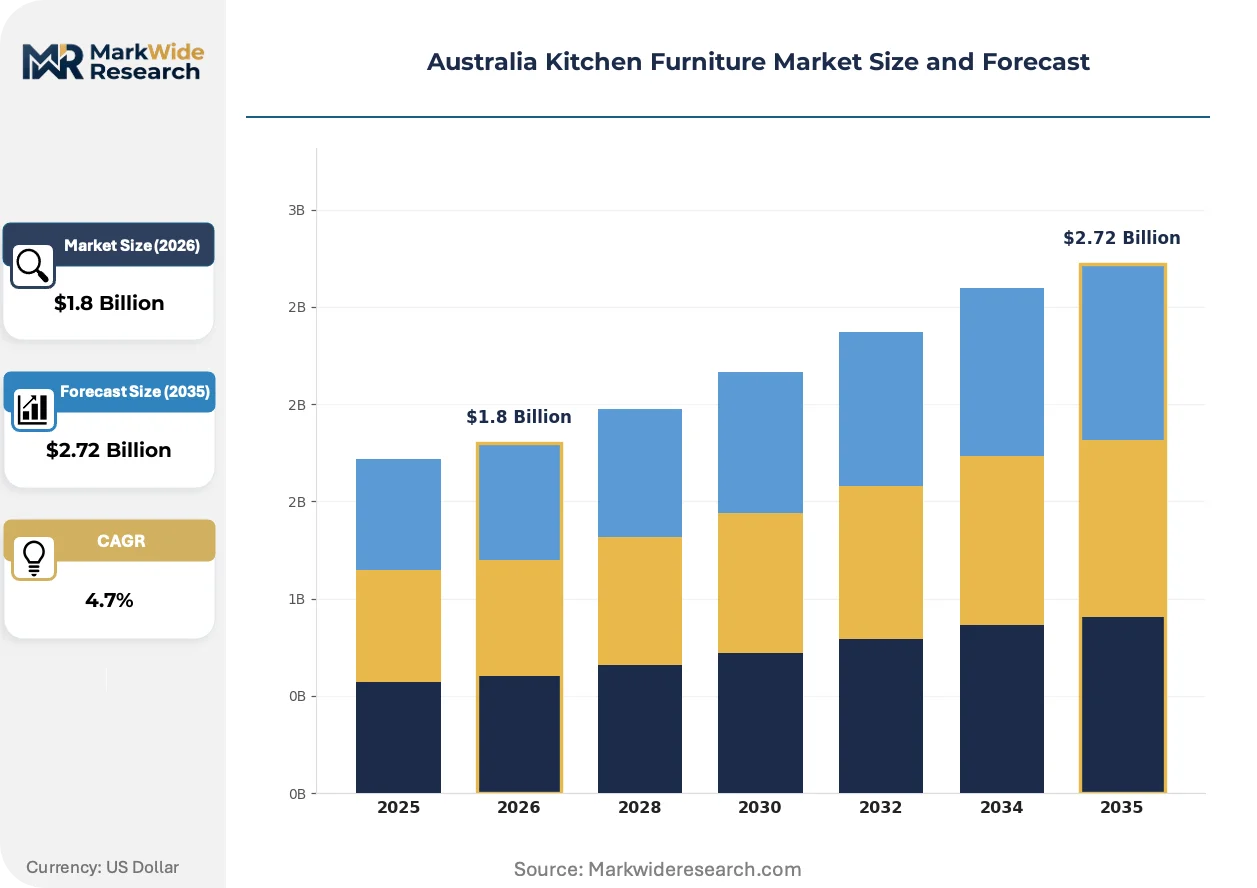
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Islands, Storage Solutions Material: Wood, Metal, Laminate, Glass Style: Modern, Traditional, Rustic, Minimalist End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | A & T Cabinet Makers, Farmers Kitchens, Nobby Kitchens, Impala, CCW Cabinet Works, Zeel Kitchens, AMj Joinery, Polytec, Damco Kitchens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Kitchen Furniture Market Strategic Shifts
Material science advances and regulatory pressure are compressing traditional product lifecycles, forcing Australian manufacturers to reconcile heritage aesthetics with performance specifications that exceed previous standards.
Engineered stone surfaces are expanding into mid-market renovation segments previously dominated by laminate countertops. Owner-occupiers undertaking kitchen refreshes now specify quartz composites at price points that manufacturers have compressed through slab optimization and templating automation. This material migration is expanding into apartment conversion projects where developers previously specified entry-grade finishes to meet budget constraints.
The National Construction Code's impending updates on condensation management are mandating vapor-permeable cabinet backings and improved thermal breaks at appliance penetrations. Builders in Victoria and New South Wales are pre-emptively specifying these features to avoid retrofit costs during compliance inspections. Multi-residential developers report that early adoption of NCC-aligned specifications reduces variation claims during handover.
Builder procurement teams are consolidating vendor relationships around suppliers offering integrated design-to-installation workflows. This concentration pattern displaces fragmented purchasing across separate cabinet, countertop, and hardware specialists. The shift is most visible in Sydney's apartment pipeline, where project managers prioritize single-source accountability for kitchen package delivery timelines.
Australia Kitchen Furniture Market Segmentation
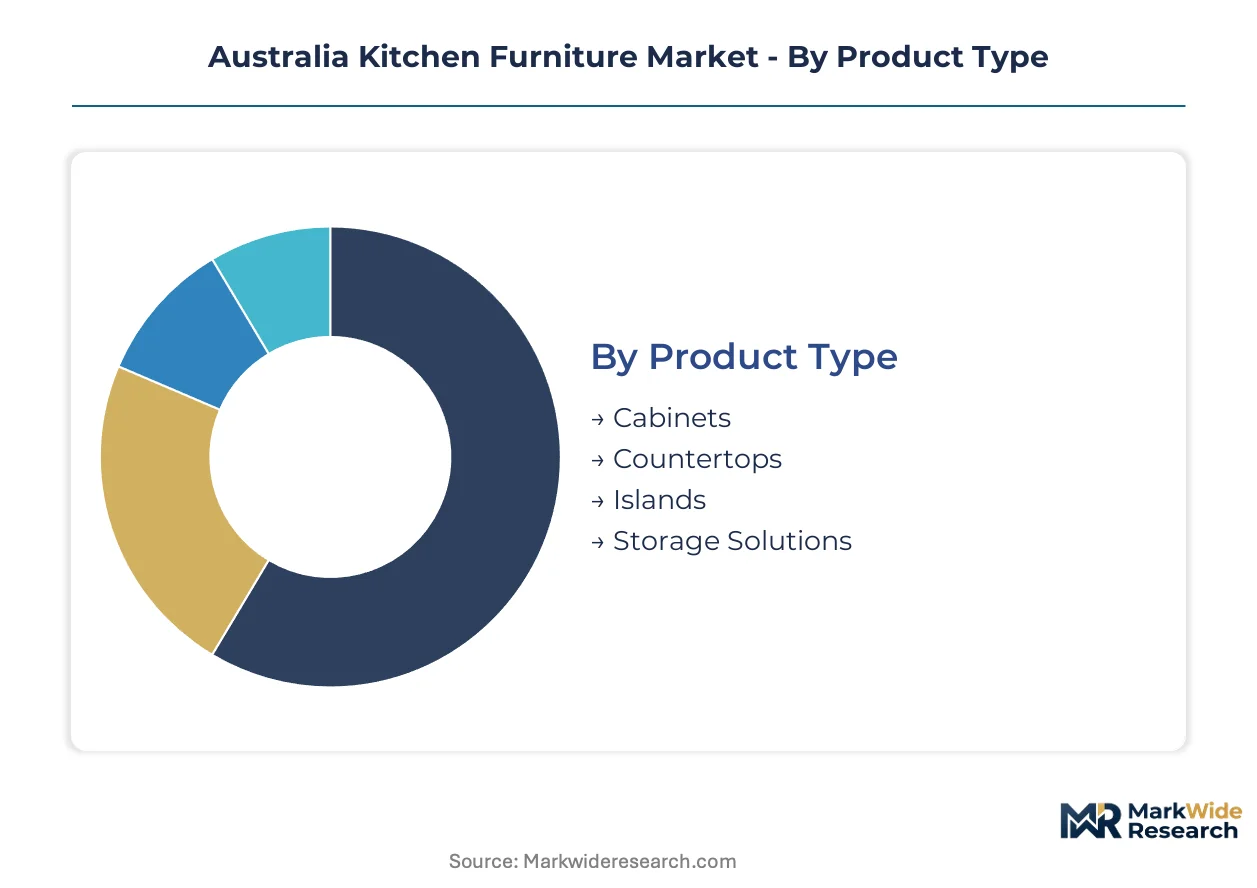
Renovation-driven replacement cycles in Australian kitchen furniture create distinct demand profiles across product categories. Material specifications and compliance requirements vary sharply between heritage restorations and new apartment developments.
Product Type:
Upgrade cycles differentiate replacement intensity across fixed and modular kitchen elements, with owner-occupiers prioritizing integrated systems over standalone component swaps.
- Cabinets:Cabinet carcasses employ moisture-resistant particleboard with thermolaminated or polyurethane finishes meeting AS/NZS 4266 structural standards. Demand concentrates in Greater Sydney and Melbourne's inner-ring suburbs where heritage renovations require custom joinery that respects architectural character while accommodating modern appliance integration.
- Countertops:Engineered stone surfaces capture premium positioning through quartz composites that manufacturers have compressed into mid-market price points via slab optimization and templating automation. Specifiers in apartment conversion projects increasingly select these over entry-grade laminate alternatives to reduce handover variation claims.
- Islands:Open-plan kitchen centrepieces command premium positioning as focal points for residential entertaining spaces.
- Storage Solutions:Modular pantry systems and pull-out organizers address space constraints in high-density urban renovations.
Volume placements concentrate in Cabinets; the faster expansion belongs to Countertops.
Material:
Cost tier stratification separates specification patterns between renovation budgets and new construction allowances.
- Wood:Timber substrates dominate bespoke joinery for high-end residential projects, with bushfire attack level compliance requirements in designated zones creating specialized demand for fire-rated timber systems. Farmers Kitchens leverages upstream control over timber sourcing to secure finishing quality for heritage restoration work.
- Laminate:Thermolaminated surfaces dominate cost-sensitive renovation segments through price accessibility that constrains margin capture. Polytec sustains competitive pressure through engineered surface technologies bridging mid-market specifications.
- Metal:Stainless steel and aluminum systems satisfy BAL compliance for external joinery in bushfire-prone regions.
- Glass:Tempered glass accents appear in contemporary minimalist designs for splashbacks and display cabinetry.
Wood commands the premium tier; laminate dominates unit placements.
Style:
Geographic concentration of renovation activity shapes aesthetic preferences across metropolitan markets.
- Modern:Clean lines and handleless cabinetry align with apartment conversion specifications in Sydney's high-density pipeline where developers prioritize reduced on-site installation complexity.
- Traditional:Ornate detailing and raised-panel doors satisfy heritage renovation requirements in Melbourne's inner-ring suburbs where architectural character preservation drives joinery specifications.
- Rustic:Distressed finishes and visible grain patterns appeal to regional owner-occupiers seeking farmhouse aesthetics.
- Minimalist:Concealed hardware and integrated appliances respond to compact footprints in urban infill developments.
Traditional styling anchors heritage restoration volume; modern designs are gaining share fastest in multi-residential procurement.
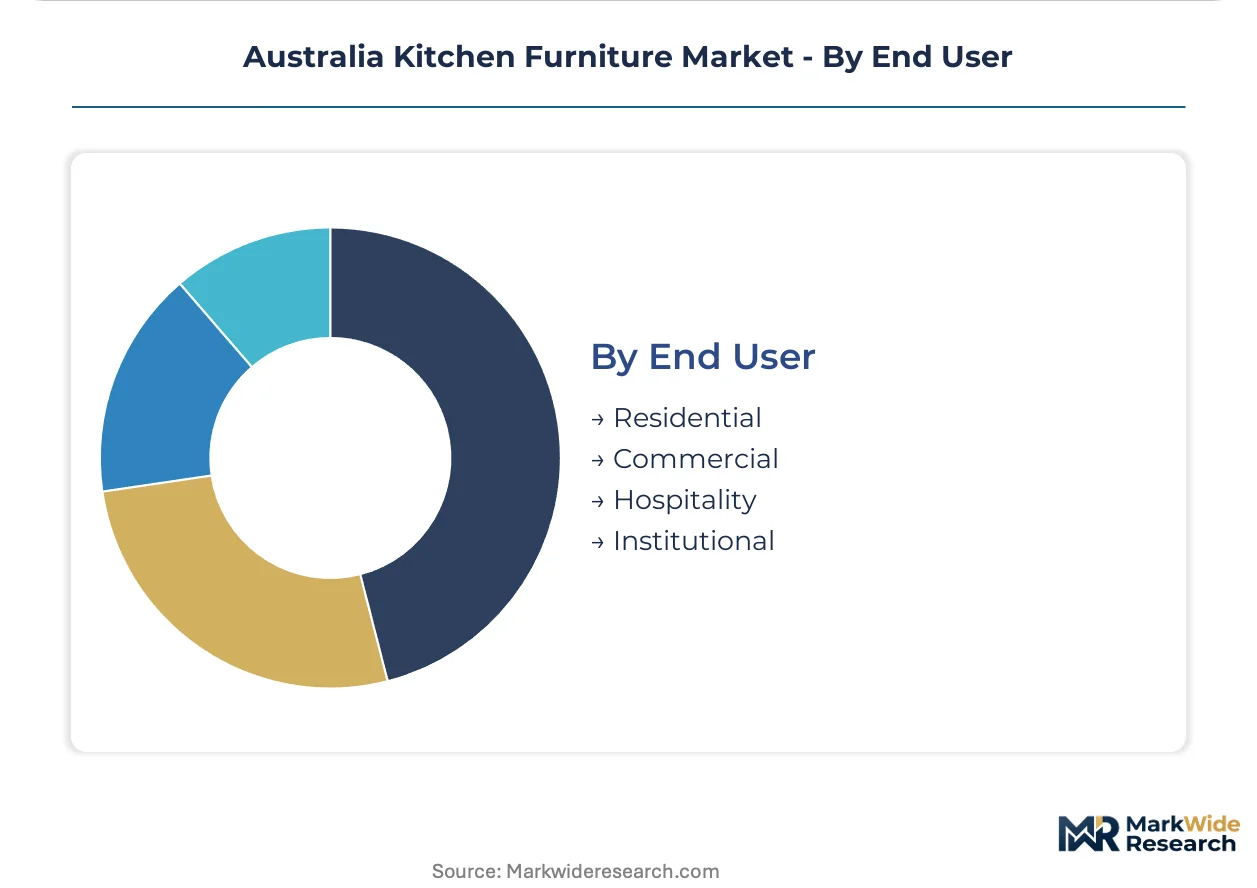
End User:
Application context determines compliance burden and specification authority in procurement workflows.
- Residential:Owner-occupier renovations generate sustained demand for custom joinery with integrated storage systems that comply with National Construction Code energy efficiency provisions for appliance housing and thermal bridging.
- Commercial:Workplace kitchenettes and staff amenities specify durable laminates and metal cabinetry to withstand high-traffic use cycles.
- Hospitality:Restaurant and hotel food preparation environments require commercial-grade stainless steel systems with enhanced hygiene certification.
- Institutional:School and healthcare facility kitchens mandate accessibility compliance and formaldehyde emission controls enforced by ACCC product safety standards.
Residential absorbs the dominant placement volume; hospitality specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Sydney and Melbourne's inner-ring suburbs concentrate Australia's kitchen furniture demand through heritage renovation pipelines and apartment conversion activity. The National Construction Code's energy efficiency mandates reshape material specifications across all major metropolitan markets. State-level building regulators enforce varying compliance timelines that fragment procurement patterns.
New South Wales
Heritage renovations in Sydney's inner suburbs drive custom joinery specifications that balance architectural preservation with modern appliance integration. The NSW Department of Planning, Housing and Infrastructure administers building code amendments that accelerate condensation management requirements for residential construction. Parramatta's emerging high-density corridor generates modular kitchen demand from multi-residential developers seeking reduced on-site installation complexity.
Victoria
Melbourne's inner-ring municipalities sustain bespoke cabinetry demand through period home restorations requiring traditional detailing and raised-panel joinery. The Victorian Building Authority enforces product safety standards for furniture stability and formaldehyde emissions that elevate compliance costs for import-dependent suppliers. Richmond and South Yarra's apartment pipeline concentrates procurement activity among builders consolidating vendor relationships around integrated design-to-installation workflows.
Queensland
Brisbane's subtropical climate conditions specify moisture-resistant substrates and vapor-permeable cabinet backings for residential renovations. The Queensland Building and Construction Commission mandates bushfire attack level compliance for external joinery in designated zones that creates specialized demand for fire-rated timber systems. Gold Coast's coastal developments prioritize engineered stone countertops that withstand humidity exposure in open-plan entertaining spaces.
Western Australia
Perth's infill development activity generates demand for compact kitchen systems addressing space constraints in urban renewal projects. The Building Commission of Western Australia enforces thermal bridging provisions that influence cabinet specification requirements for new residential construction. Fremantle's heritage precinct drives restoration work requiring custom joinery that respects architectural character while accommodating contemporary functional requirements.
South Australia
Adelaide's established suburbs sustain renovation-driven replacement cycles for integrated storage systems and energy-efficient appliance housing. The South Australian Building Industry Consultative Council tracks impending National Construction Code updates that will reshape specification requirements for substantial renovations. The city's design-focused residential market exhibits preference for minimalist styling with concealed hardware and handleless cabinetry in contemporary developments.
Australia Kitchen Furniture Market Competitive Environment
Premium-margin players sit above commodity-margin players across material quality and customization depth in Australia's kitchen furniture structure. The vendor base separates into three distinct tiers: bespoke joinery specialists commanding heritage restoration premiums, mid-market engineered surface fabricators bridging cost and performance specifications, and flat-pack commodity suppliers competing on price accessibility. Strategic differentiation concentrates on backward integration into timber sourcing, automated templating capabilities for engineered stone, and direct-to-builder digital procurement platforms.
Among Australian-based fabricators, Farmers Kitchens exemplifies upstream control over timber sourcing and finishing quality for high-end residential projects. Polytec occupies a position within the mid-market tier through engineered surface technologies that bridge cost-sensitive and premium renovation segments. A & T Cabinet Makers represent the bespoke joinery archetype serving heritage restoration pipelines in Sydney's inner-ring suburbs.
| Leading Market Players |
|---|
| A & T Cabinet Makers |
| Farmers Kitchens |
| Nobby Kitchens |
| Impala |
| CCW Cabinet Works |
| Zeel Kitchens |
| AMj Joinery |
| Polytec |
| Damco Kitchens |
| Others |
Value Chain & Pricing Dynamics
The National Construction Code's bushfire attack level compliance mandates gate both qualified supply and premium-tier pricing access, as manufacturers with certified fire-rated timber systems command material premiums while import-dependent suppliers face exclusion from designated zones.
Pricing Analysis
Value-based pricing anchored to renovation outcome quality separates bespoke joinery from commodity flat-pack alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by customization depth and material certification, with Polytec's engineered surfaces bridging mid-market specifications. Cost compression in the laminate segment intensifies because Southeast Asian manufacturing competition compresses margin flexibility. Owner-occupiers in heritage renovation pipelines exhibit lowest price sensitivity, while apartment conversion developers drive hardest bargain pressure.
Supply Chain Analysis
Single-source vulnerability sits with moisture-resistant particleboard feedstock concentrated among domestic engineered wood producers. Raw material dependencies center on timber substrates from certified Australian plantations, engineered stone slabs from Italy and China, and hardware systems from Germany. Tariff exposure on imported laminate surfaces and engineered stone creates margin volatility for fabricators without captive supply arrangements. Distribution runs through builder merchant networks and direct-to-project procurement platforms consolidating multi-residential vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over timber sourcing and finishing quality determines premium-tier access. Players are pursuing captive supply of certified substrates to defend margin position against import volatility.
For Market Incumbents: Anchor defensive positioning through backward integration into fire-rated timber systems that satisfy BAL compliance requirements in designated zones. Invest in automated templating capabilities for engineered stone countertops to capture margin expansion as quartz composites migrate into mid-market renovations. Consolidate vendor relationships around integrated design-to-installation workflows that reduce project variation claims. For New Entrants and Emerging Players: Builder procurement teams represent the most accessible channel for establishing initial footprint. Target direct-to-builder digital platforms in Sydney's apartment pipeline where project managers prioritize single-source accountability. White-space opportunity concentrates in modular kitchen systems for multi-residential developers seeking reduced on-site installation complexity. For Investors and Strategic Acquirers: NCC condensation management compliance adoption rates are the leading indicator that specification requirements are tightening sufficiently to reshape competitive economics. Acquisition focus should center on mid-market fabricators with established testing relationships to ACCC product safety standards. Watch for impending NCC updates on thermal bridging as the signal for accelerated consolidation among import-dependent suppliers facing certification barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Sourcing | Captive supply of certified substrates insulates margin from import volatility and BAL compliance exclusion. |
| Automated Templating Investment | Slab optimization technology compresses engineered stone price points to capture mid-market renovation volume. |
| Direct-to-Builder Platform Development | Digital procurement integration reduces friction in Sydney's multi-residential project workflows. |
| Fire-Rated System Certification | ACCC testing relationships create defendable positioning in bushfire-prone regions under NCC mandates. |
| Modular System Expansion | Reduced on-site installation time addresses labor scarcity and apartment conversion timeline pressure. |
Study Parameters
Document review covered National Construction Code amendments, Australian Building Codes Board technical standards, and ACCC product safety enforcement records, complemented by interviews with cabinet fabrication executives, heritage restoration architects, multi-residential project managers, and builder procurement officers. Secondary validation drew from Australian Bureau of Statistics construction activity data, state-level building regulator compliance reports, and industry association membership directories. Bottom-up demand modeling triangulated against top-down construction pipeline assessments.
Historical renovation cycle patterns cross-referenced against panel input from manufacturer order backlogs and builder contract pipelines across the projection horizon. Segmentation dimensions modeled include product type, material substrate, styling category, and end-use application, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs derived from regression analysis of replacement cycle intensity against dwelling stock age profiles and energy efficiency retrofit mandates.
Caveats apply where NCC implementation timeline delays, skilled joinery labor availability shocks, or engineered stone supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and renovation financing accessibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Accent Tables Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Europe Kitchen Hobs Market