
 China Kitchen Products Market | 2026-2036
China Kitchen Products Market Size, Share, and Industry Trends Forecast 2026-2036
China Kitchen Products Market Insights
Zhejiang province is tilting toward high-capacity cookware manufacturing with specialized industrial parks in Ningbo and Wenzhou. Supor leverages integrated forging and coating facilities to command the premium stainless steel segment. Midea anchors its position through in-house production of smart heating elements for induction-compatible cookware. Joyoung competes aggressively on small appliance automation with connected rice cookers and soy milk makers.
Kitchen products encompass cookware, utensils, appliances, and tableware manufactured from stainless steel, plastic, ceramics, and glass, with thickness tolerances for clad cookware typically ranging from 1.5mm to 3.0mm and surface finishes graded by GB/T 3280 cold-rolled standards for corrosion resistance. These items serve food preparation, cooking, serving, and storage functions across residential and commercial foodservice operations. The appliances segment leads value generation as induction cooktops and smart rice cookers absorb disproportionate R&D investment, while the utensils category in food-grade 304 stainless steel sustains the highest margin pools due to material certification premiums. Online retail channels are accelerating fastest among sales channels, though specialty stores in tier-one cities still dominate experiential purchases for premium ceramic and glass tableware.
China's SAMR enforces GB food-contact material standards that mandate heavy metal migration limits for ceramic and stainless steel products, while MEE oversight of the dual carbon goals pressures manufacturers toward electric furnace steel and recycled glass feedstocks. BIS-equivalent provincial testing bureaus in Zhejiang and Guangdong conduct mandatory batch inspections that shape market access timelines for new entrants. Stakeholders must monitor how tightening carbon intensity benchmarks for steel and ceramics reshape supplier qualification criteria and regional production licensing.
Market Dynamics
Urban household appliance upgrades are compressing replacement cycles from ten-year spans to five-to-seven-year refresh rates, while SAMR enforcement of GB food-contact standards is disqualifying legacy coating chemistries and forcing reformulation investments across the cookware base.
Growth Catalysts
- Dual carbon goals:MEE carbon intensity benchmarks for steel and ceramics production are accelerating electric furnace adoption and recycled glass feedstock integration, creating first-mover advantages for compliant manufacturers in Zhejiang industrial parks.
- Smart appliance connectivity:MIIT IoT standards for home appliances are enabling remote diagnostics and predictive maintenance features that urban households in Shanghai and Hangzhou increasingly demand for rice cookers and induction cooktops.
- Yangtze River Delta cluster concentration:Specialized industrial parks in Ningbo and Wenzhou are consolidating forging, coating, and assembly capabilities within 150-kilometer radii, reducing logistics costs and inspection coordination burdens for export-oriented producers.
Market Restraints
- Nickel price volatility:Stainless steel 304 input costs fluctuate with LME nickel contract movements, compressing margin pools for utensil manufacturers who cannot pass through material swings to price-sensitive retail channels.
- Batch inspection timelines:Zhejiang and Guangdong provincial testing bureaus conduct mandatory SAMR compliance reviews that extend new product launch windows by four to eight weeks versus unregulated markets.
- Ceramic tableware substitution:Tempered glass serving pieces from Shandong producers are capturing gifting and hospitality procurement share from traditional porcelain, pressuring Jingdezhen-centered supply chains.
Strategic Opportunities
- Central and western provinces:Tier-three and tier-four cities in Sichuan and Hubei show underpenetrated smart appliance adoption relative to coastal saturation, offering volume expansion paths for induction-compatible product lines.
- Commercial foodservice automation:Connected batch cooking equipment for cloud kitchen operators represents an emerging application segment with higher per-unit values and service attach rates than residential equivalents.
- GB standard harmonization:SAMR alignment of food-contact material rules with Codex Alimentarius frameworks is reducing technical barriers for export-qualified producers seeking ASEAN market access.
Industry Challenges
- Coating chemistry reformulation:PFAS-free ceramic non-stick alternatives require R&D cycles of eighteen to twenty-four months to match legacy performance benchmarks, straining mid-tier manufacturers without captive laboratory resources.
- Legacy induction compatibility:Retrofitting existing cookware designs for uniform magnetic field response demands die and mold reinvestment that smaller forging operations cannot finance without external capital.
- Cross-provincial licensing friction:Manufacturers with Jiangsu production and Zhejiang headquarters face dual environmental compliance audits that duplicate documentation and extend facility certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Kitchen Products Market |
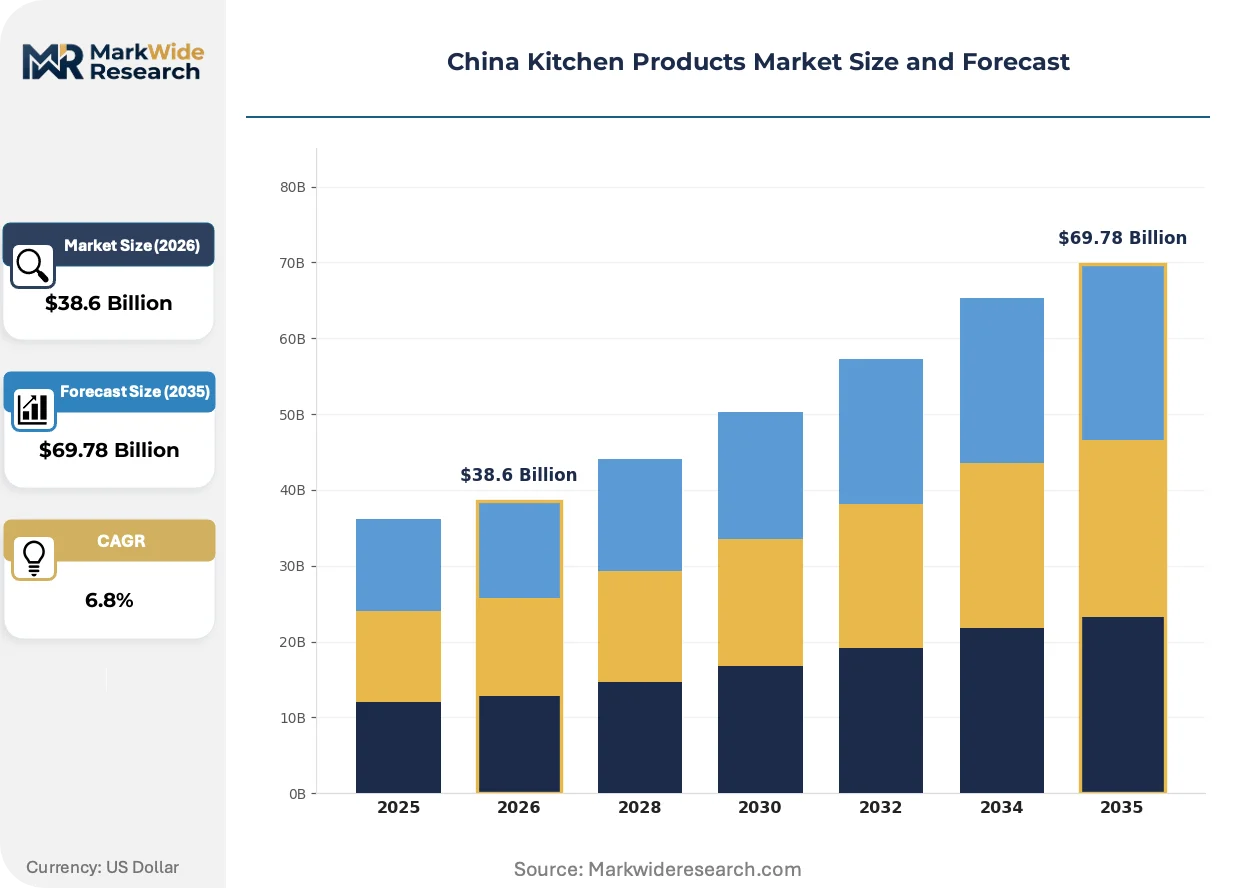
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware, Utensils, Appliances, Tableware Material: Stainless Steel, Plastic, Ceramics, Glass End User: Households, Restaurants, Cafes, Catering Services Sales Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Fangtai Kitchenware, Yinghua Kitchenware, Supor, Midea, ASD, Chances, Joyoung, Linkfair, Cooker King, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Kitchen Products Market Trends and Innovations
Active materials substitution and regulatory chemistry restrictions are forcing simultaneous innovation across coating formulations, steel metallurgy, and connected device architectures. These shifts are redrawing competitive boundaries between integrated manufacturers and assembly specialists.
Clad cookware construction is migrating from aluminum-core tri-ply configurations toward copper-core and fully stainless steel designs that satisfy induction compatibility requirements without adapter discs. Premium urban households in Beijing and Shenzhen are adopting these designs at replacement rates exceeding traditional cookware by a factor of two. This migration from aluminum-dependent supply chains is compressing demand for brazing sheet imports and elevating domestic cold-rolling capacity utilization.
GB 4806 food-contact material standards are tightening heavy metal migration limits for ceramic glazes and stainless steel surface finishes, with SAMR batch testing protocols expanding from six to eleven parameter categories. Manufacturers must now submit third-party laboratory reports from accredited Zhejiang or Guangdong bureaus before retail distribution authorization. The ceramic tableware segment is responding by accelerating lead-free and cadmium-free glaze development, with Jingdezhen producers investing in X-ray fluorescence screening equipment for inbound raw material verification.
Specialty store experiential purchases for premium ceramic and glass tableware are fragmenting across live-stream commerce and flagship showroom formats. Tier-one city consumers now research surface finish grades and GB/T 3280 corrosion resistance specifications through short-video platforms before visiting physical locations for tactile validation. This behavioral bifurcation is most visible in Shanghai, where Nanjing Road showrooms function as fulfillment nodes for online orders rather than primary transaction venues.
China Kitchen Products Market Segmentation
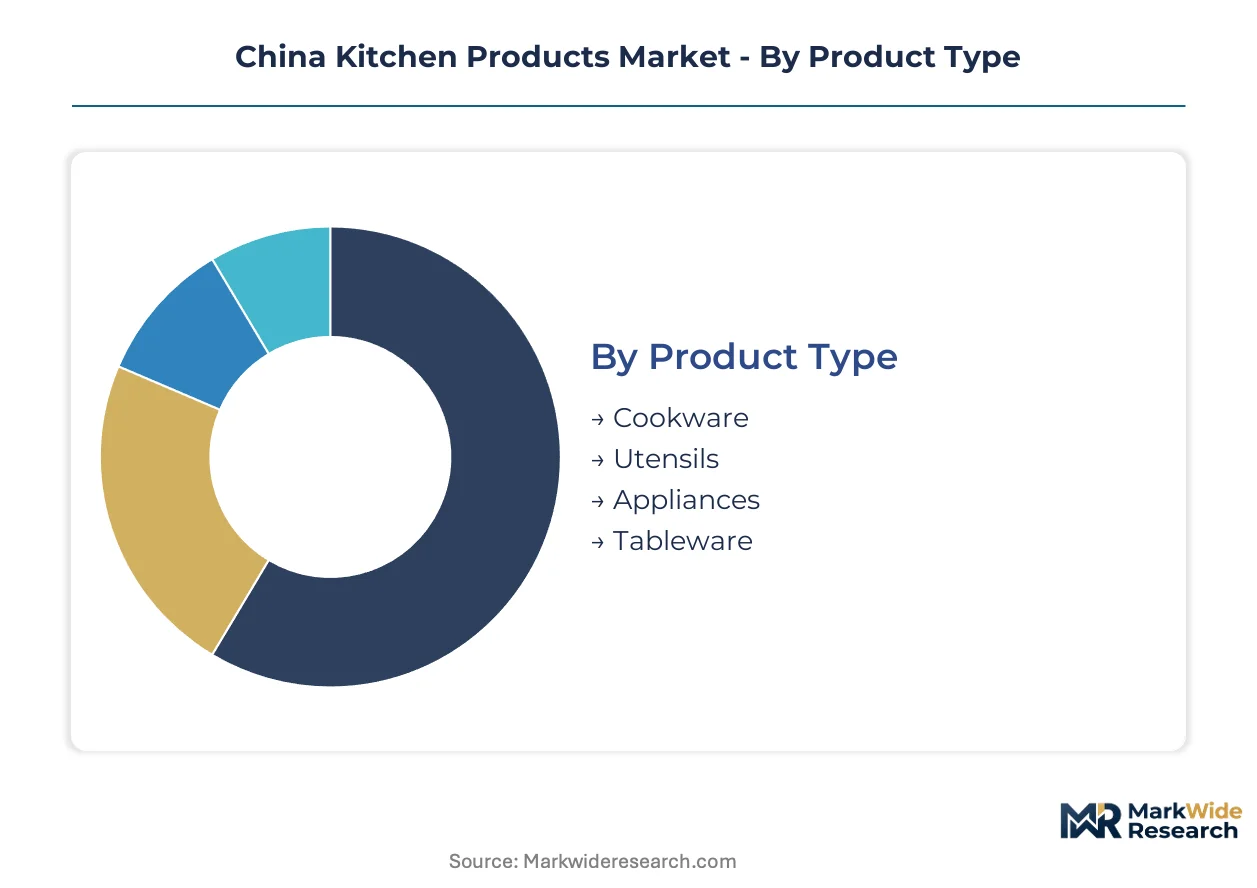
Segmentation in the China kitchen products market reveals how regulatory pressure and channel fragmentation reshape competitive boundaries. Distinct material specifications, end-use requirements, and distribution economics govern profitability within each slice.
Product Type:
Cost tier stratification separates premium smart-enabled lines from commoditized basics across four functional categories.
- Cookware:Clad construction in copper-core and fully stainless steel designs now dominates premium urban replacement cycles. Yangtze River Delta households absorb these at refresh rates double those of traditional aluminum-dependent configurations.
- Appliances:Induction cooktops and connected rice cookers concentrate disproportionate R&D investment from MIIT-aligned manufacturers. Shanghai and Hangzhou consumers demand remote diagnostics and predictive maintenance features that elevate per-unit values above residential cookware.
- Utensils:Food-grade 304 stainless steel sustains the highest margin pools due to SAMR certification premiums and GB/T 3280 surface finish grading.
- Tableware:Premium ceramic and glass serving pieces fragment across live-stream commerce and flagship showroom formats in tier-one cities.
Cookware holds installed capacity. Appliances is rotating up the share rankings.
Material:
Application requirements from SAMR food-contact standards and MEE carbon intensity benchmarks dictate material selection trade-offs.
- Stainless Steel:Cold-rolled grades per GB/T 3280 corrosion resistance specifications anchor utensil and cookware production. Ningbo and Wenzhou industrial parks consolidate forging and coating capabilities within 150-kilometer radii.
- Ceramics:Jingdezhen producers invest in X-ray fluorescence screening for lead-free and cadmium-free glaze compliance with expanding GB 4806 parameter categories.
- Glass:Recycled feedstock integration accelerates under dual carbon goals, with tempered serving pieces from Shandong capturing hospitality procurement share.
- Plastic:Food-contact compliance limits restrict applications to storage and preparation tools outside high-heat cooking functions.
Stainless steel holds installed capacity. Glass is rotating up the share rankings.
End User:
Customer type determines volume scale, service attach rates, and specification tolerance thresholds.
- Households:Urban appliance upgrades compress replacement cycles from ten-year spans to five-to-seven-year refresh rates. Smart connectivity features from MIIT IoT standards drive specification demands in Beijing and Shenzhen.
- Restaurants:Commercial foodservice automation for cloud kitchen operators represents an emerging application segment with higher per-unit values than residential equivalents.
- Cafes:Beverage-focused equipment requirements prioritize compact footprint and rapid cycle times over batch capacity.
- Catering Services:Volume procurement concentrates through wholesale channels with standardized durability specifications.
Households holds installed capacity. Restaurants is rotating up the share rankings.
Sales Channel:
Geography and customer journey stage determine channel economics and working capital intensity.
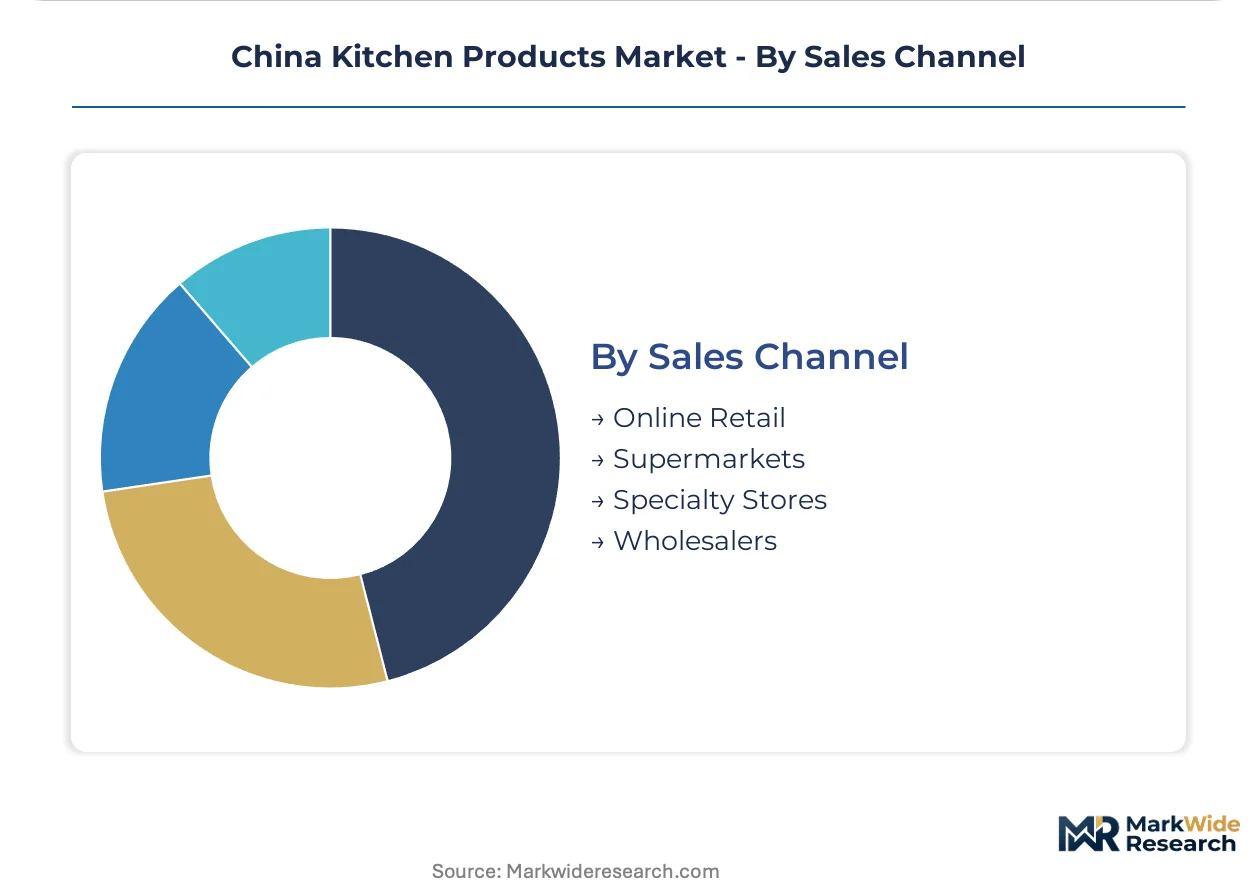
- Online Retail:Short-video platforms now host surface finish research and GB specification education before purchase. This channel accelerates fastest among all distribution modes.
- Specialty Stores:Nanjing Road showrooms in Shanghai function as fulfillment nodes for online orders rather than primary transaction venues.
- Supermarkets:Mass-market cookware and utensil volumes concentrate here, with price sensitivity limiting premium product penetration.
- Wholesalers:Commercial foodservice and catering procurement runs through this channel with extended payment terms and bulk logistics.
Supermarkets holds installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forging and coating capabilities cluster within 150-kilometer radii across eastern coastal provinces. SAMR batch testing protocols and MEE carbon intensity benchmarks reshape where production capacity expands.
Yangtze River Delta
Shanghai anchors smart appliance demand as households refresh induction cooktops on five-to-seven-year cycles. MIIT IoT standards for home appliances mandate remote diagnostics capabilities that Hangzhou and Suzhou consumers now expect. Ningbo and Wenzhou industrial parks consolidate stainless steel forging, coating, and assembly for export-oriented producers.
Pearl River Delta
Guangzhou and Shenzhen households drive connected rice cooker penetration with predictive maintenance features. SAMR enforcement of GB 4806 food-contact standards disqualifies legacy coating chemistries across cookware imports. Foshan ceramic producers face mandatory batch inspections from Guangdong provincial testing bureaus that extend launch windows.
Beijing-Tianjin-Hebei
Premium urban replacement cycles for copper-core clad cookware run double the national average in Beijing. MEE oversight of dual carbon goals pressures manufacturers toward electric furnace steel and recycled glass feedstocks. Tianjin port logistics handle inbound nickel and cold-rolled sheet for northern distribution networks.
Sichuan-Chongqing
Tier-three and tier-four cities show underpenetrated smart appliance adoption relative to coastal saturation. Chongqing municipal programs promote induction-compatible product lines for residential kitchen upgrades. Chengdu wholesale channels supply western province catering services with standardized durability specifications.
Shandong Peninsula
Tempered glass serving pieces capture hospitality procurement share from traditional porcelain. Recycled feedstock integration accelerates under national carbon intensity benchmarks for ceramics. Qingdao producers invest in X-ray fluorescence screening for inbound raw material verification.
China Kitchen Products Market Competitive Landscape
Integrated manufacturers and assembly specialists split the market along capability depth lines. The vendor base concentrates around three strategic archetypes: diversified appliance conglomerates with captive component production, specialized cookware fabricators with integrated forging and coating, and automation-focused small appliance developers. Competitive moves center on die and mold reinvestment for induction compatibility and PFAS-free ceramic non-stick reformulation.
Within the diversified conglomerate tier, Midea and Supor exemplify scale-driven positions. Supor occupies a fabrication-specialist role through integrated forging and coating facilities. Joyoung sits within the automation-focused vector for connected small appliances. These three anchors represent how strategic archetypes map to regulatory compliance advantages under tightening GB standards and carbon intensity benchmarks.
| Leading Market Players |
|---|
| Fangtai Kitchenware |
| Yinghua Kitchenware |
| Supor |
| Midea |
| ASD |
| Chances |
| Joyoung |
| Linkfair |
| Cooker King |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shandong tempered glass production is compressing unit economics and forcing producers toward export markets or premium hospitality positioning. This utilization squeeze simultaneously elevates bargaining power for consolidated Yangtze River Delta stainless steel forgers while squeezing margin pools for fragmented ceramic tableware suppliers.
Pricing Analysis
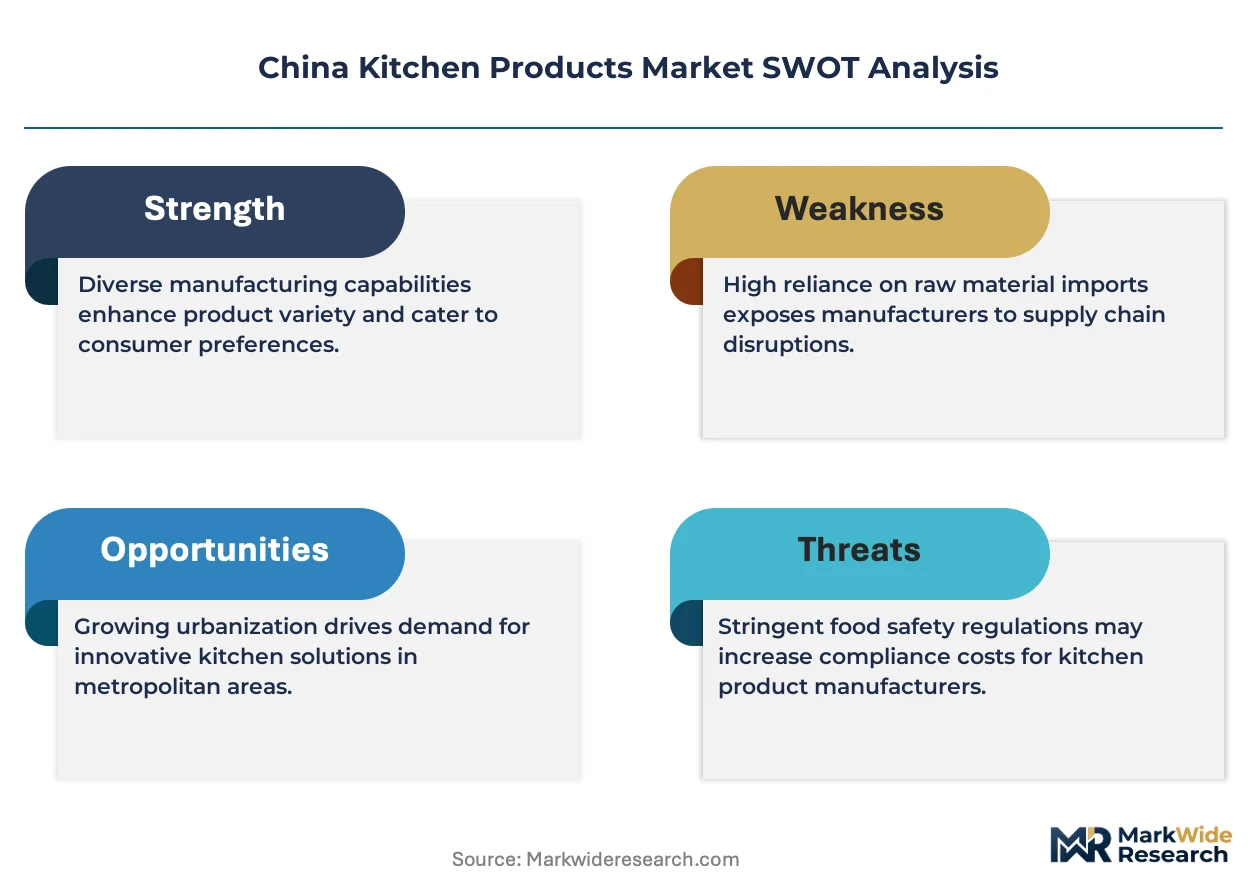
GB 4806 food-contact standards dictate the pricing tier structure by mandating third-party laboratory certification from Zhejiang or Guangdong bureaus before retail authorization. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-compliant certified lines from uncertified imports and basic uncoated steel. Pricing pressure stems from nickel volatility on LME contracts that mid-tier utensil manufacturers cannot pass to price-sensitive supermarket channels. Mass-market cookware buyers exhibit highest price sensitivity, while specialty store purchasers of premium ceramic absorb certification premiums without volume trade-offs.
Supply Chain Analysis
Upstream cold-rolled stainless steel feedstock draws from Ningbo and Wenzhou industrial parks within 150-kilometer forging clusters, with secondary ceramic raw material sourcing from Jingdezhen and Shandong glassworks. Nickel cathode and recycled glass cullet constitute critical input dependencies alongside food-grade coating chemistries. Single-source vulnerability concentrates in electric furnace steel capacity under MEE carbon intensity enforcement. Distribution runs through online retail channels accelerating fastest, though wholesale networks still anchor commercial foodservice procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated forging-coating capabilities and SAMR certification infrastructure represent scarce assets that will determine competitive survival as GB standards tighten and dual carbon goals reshape metallurgy requirements.
For Market Incumbents: Pre-empt coating chemistry obsolescence by captive PFAS-free ceramic non-stick R&D investment before SAMR disqualifies legacy formulations. Secure electric furnace steel supply agreements ahead of MEE carbon intensity benchmarks that will disqualify conventional blast furnace inputs. Defend against tempered glass substitution from Shandong by embedding X-ray fluorescence screening into inbound raw material verification protocols. For New Entrants and Emerging Players: Establish a beachhead in tier-three Sichuan and Hubei smart appliance segments where coastal saturation has left underpenetrated demand for induction-compatible product lines. Target cloud kitchen automation equipment with higher per-unit values and service attach rates than saturated residential cookware. Lead through live-stream commerce education on GB/T 3280 surface finish grades before tactile validation at flagship showrooms. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive forging facilities and in-house coating capabilities that can absorb eighteen-to-twenty-four-month reformulation cycles without external laboratory dependence. Long-term viability favors producers with Jiangsu-Zhejiang dual licensing compliance already navigated. Monitor SAMR batch inspection timeline extensions as an inflection signal for market access barriers favoring scaled incumbents over fragmented assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Reformulation | Eighteen-to-twenty-four-month R&D cycles under SAMR chemistry restrictions separate integrated manufacturers from assembly-dependent competitors. |
| Electric Furnace Steel Transition | MEE carbon intensity benchmarks reward first-mover producers in Ningbo and Wenzhou industrial parks with compliant feedstock access. |
| Smart Appliance Connectivity Investment | MIIT IoT standards for remote diagnostics capture premium replacement cycles in Shanghai and Hangzhou urban households. |
| Cross-Provincial Licensing Consolidation | Dual Jiangsu-Zhejiang environmental audits favor single-location production to compress facility certification timelines. |
| Live-Stream Commerce Channel Buildout | Short-video platform education on GB specifications precedes tactile validation at tier-one flagship showrooms. |
Research Methodology
Desk research of customs trade records, SAMR regulatory filings, and MIIT IoT standard disclosures preceded structured interviews with cookware plant managers, procurement leads at Yangtze River Delta OEMs, distribution channel partners in wholesale catering supply, and technical R&D directors at coating formulation laboratories. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Assumptions held SAMR enforcement intensity and MEE carbon benchmark trajectories fixed while varying nickel price volatility bands and smart appliance penetration rates. Segmentation dimensions modeled include product type, material grade, end-user category, and sales channel geography. CAGRs derived from regression against historical replacement cycle compression and urban household appliance upgrade elasticities, with MIIT IoT adoption curves and GB 4806 compliance cost pass-through as industry-specific forecast inputs.
Stress conditions across LME nickel contract movements, SAMR inspection timeline extensions, and tempered glass substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against provincial testing bureau certification volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Rainbow Flatware Market
Kitchen and Dining
Dining Table Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
GCC Modular Kitchen Market