
 Prefabricated Kitchen Pod Market | 2026-2036
Prefabricated Kitchen Pod Market Size, Share, and Industry Trends Forecast 2026-2036
Prefabricated Kitchen Pod Market Insights
Premium-grade fire-rated kitchen specifications is collapsing the gap between site-built and modular quality perceptions. Walker Modular Ltd. leverages its UK manufacturing base to dominate hospitality supply chains across Northern Europe. Oldcastle SurePods anchors North American demand through large-scale production capacity and direct developer relationships. Offsite Solutions Ltd. specializes in compact configurations for urban micro-units where space efficiency governs specification.
A prefabricated kitchen pod denotes a fully factory-assembled cooking enclosure incorporating cabinetry, appliances, ventilation, plumbing rough-ins, and electrical terminations within a self-supporting frame, delivered as a single unit for crane or roll-in installation. Steel-framed variants with integrated MEP connections serve high-rise residential and commercial hospitality projects where on-site trade coordination carries schedule risk. Modular Units lead volume shipments due to repeatability in multi-unit developments, while Custom Pods capture margin pools from boutique hotel operators seeking branded interior differentiation. Stainless Steel dominates material selection in hospitality applications for durability compliance, though Composite Wood gains traction in residential complexes targeting carbon-footprint reduction.
The EU Construction Products Regulation and CE marking framework govern fire reaction performance and structural load ratings for kitchen pods installed in multi-occupancy buildings across member states. The US ICC and NFPA codes shape product access through kitchen exhaust and grease-duct specifications that factory builders must pre-engineer. Japan's METI building energy standards influence insulation and appliance efficiency thresholds for export-oriented manufacturers. Stakeholders must monitor evolving national building codes that increasingly recognize factory quality assurance as equivalent to site inspection regimes.
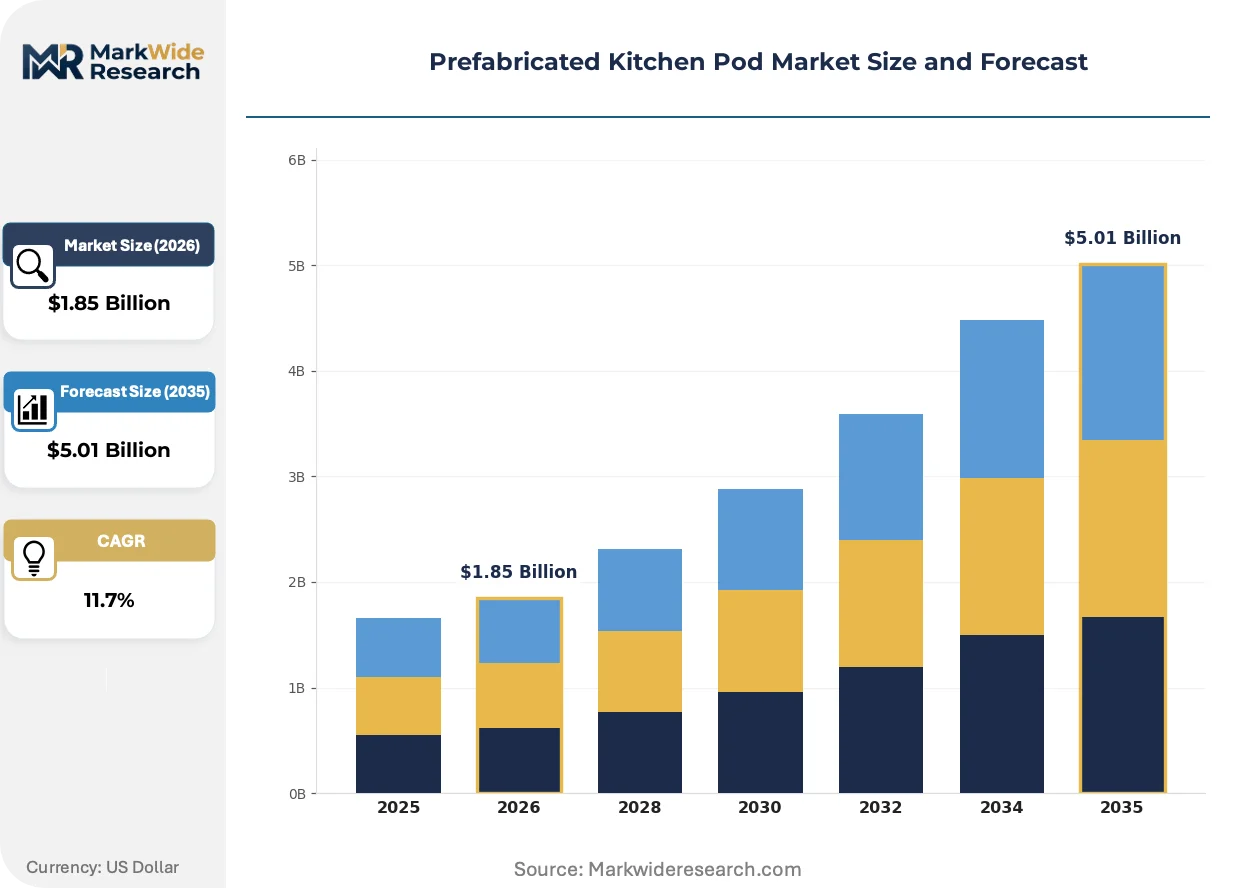
Market Dynamics
Construction labor shortages across Germany, the United Kingdom, and Japan are compressing project timelines and forcing developers toward factory-built kitchen modules that eliminate on-site trade coordination.
Growth Catalysts
- EU Construction Products Regulation:Harmonized fire-safety and energy-performance standards for offsite components are eliminating regulatory friction for cross-border pod shipments between member states.
- Hospitality renovation cycles:Hotel operators in Germany and France are specifying certified modular kitchens to minimize guest disruption during property refreshes.
- Steel framing with integrated MEP:This construction method is reducing high-rise installation risk by pre-wiring electrical terminations and plumbing rough-ins at the factory.
Market Restraints
- Stainless steel price volatility:Raw material cost swings for hospitality-grade surfaces are compressing margins for pod manufacturers locked into fixed-price contracts.
- CE marking compliance costs:Small fabricators face structural barriers entering multi-occupancy building supply chains due to third-party testing and documentation burdens.
- Site-built kitchen substitution:Custom millwork remains competitive in one-off luxury residential projects where unit economics favor traditional construction.
Strategic Opportunities
- Japan's METI building energy standards:Export-oriented manufacturers can capture share by engineering insulation and appliance efficiency thresholds for the Japanese residential tower market.
- Student housing micro-units:Compact pod configurations for space-constrained urban developments represent underpenetrated demand in German university cities.
- BIM-to-factory data pipelines:Direct digital transfer from architectural models to CNC cutting equipment is compressing design-to-delivery cycles for repeat multi-unit projects.
Industry Challenges
- Multi-trade coordination expertise:Factory floor teams must integrate cabinetry, ventilation, and electrical terminations within tolerance—skills scarce in traditional construction labor pools.
- NFPA kitchen exhaust pre-engineering:North American market entry requires grease-duct specifications locked before factory production, extending certification timelines for new entrants.
- Legacy building stock integration:Crane access constraints and dimensional mismatches in older European residential towers complicate roll-in installation logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefabricated Kitchen Pod Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Custom Pods, Semi-assembled Kits, Built-in Designs Material: Stainless Steel, MDF, Composite Wood, Aluminum, Acrylic Application: Residential Complexes, Hospitality Suites, Student Housing, Retirement Communities Distribution Channel: Direct Sales, Authorized Dealers, Online Platforms, Wholesale Distributors |
| Companies Covered | Walker Modular Ltd., Offsite Solutions Ltd., Oldcastle SurePods, B&T Manufacturing, Pivotek LLC, Modulart, Hydrodiseno S.L., Plant Prefab Inc., Boxabl Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefabricated Kitchen Pod Market Trends and Innovations
Digital fabrication and regulatory harmonization are compressing design-to-installation cycles while reshaping how developers procure cooking enclosures for multi-unit buildings.
Composite wood panel systems with embedded fire-retardant chemistry are decomposing the historic durability gap against stainless steel in residential applications. German student housing developers are specifying these materials for carbon-footprint reduction targets. Factory quality assurance for fire-reaction performance is decomposing the risk premium that site-built alternatives previously commanded.
REACH chemical restrictions and evolving EU F-Gas Regulation thresholds are forcing refrigerant and insulation material substitutions in pod-integrated appliances. Manufacturers serving the European market must reformulate supply chains to maintain CE marking compliance. Hospitality pod builders are responding by consolidating procurement of certified low-GWP components across their production lines.
Developer procurement teams are bundling kitchen pods with bathroom modules under single-source contracts to compress vendor management overhead. This pattern concentrates specification authority with integrated offsite manufacturers and marginalizes standalone cabinet suppliers. The United Kingdom and Netherlands show the most advanced bundling adoption in residential tower developments.
Prefabricated Kitchen Pod Market Segmentation
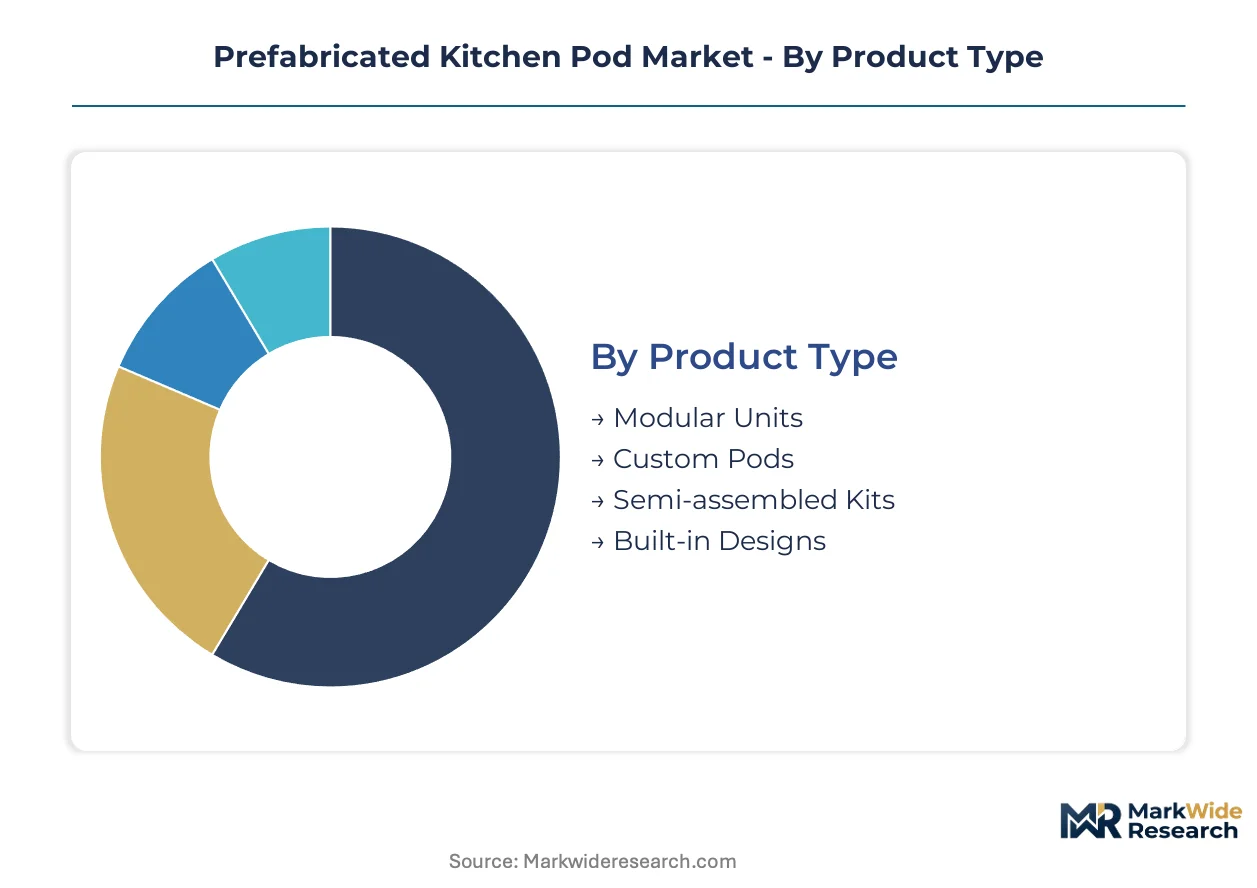
Product differentiation in the prefabricated kitchen pod market maps directly to regulatory compliance tiers and installation complexity. Segmentation strategy determines factory capital allocation, certification pathways, and margin capture across multi-unit construction verticals.
Product Type:
CE marking intensity varies sharply across factory completion levels, with fully assembled variants facing stricter fire-reaction testing than field-finished alternatives.
- Modular Units:Standardized dimensions with pre-integrated MEP rough-ins and ventilation systems. Demand concentrates in German student housing developments where repeatability governs procurement specifications and batch certification reduces per-unit compliance costs.
- Custom Pods:Bespoke dimensions with branded interior finishes for boutique hospitality operators. French hotel renovation cycles favor these units for guest-room differentiation despite longer factory lead times and elevated documentation burdens for one-off CE marking.
- Semi-assembled Kits:Factory-cut components requiring on-site cabinetry assembly and appliance connection.
- Built-in Designs:Structural frames sized for existing shaft dimensions in legacy European residential towers.
Established volume favors Modular Units; emerging adoption favors Custom Pods.
Material:
Surface selection governs fire-reaction classification under EU Construction Products Regulation and durability warranties in high-traffic hospitality environments.
- Stainless Steel:Non-combustible substrate with inherent grease resistance and structural rigidity. German hotel operators specify this material for kitchen exhaust zones where NFPA-equivalent fire standards apply through national building codes.
- Composite Wood:Engineered panels with embedded intumescent chemistry achieving Class B fire ratings. Student housing developers in the Netherlands specify these for embodied carbon reduction targets under national building energy standards.
- MDF:Medium-density fiberboard with laminate surfacing for residential cost sensitivity.
- Aluminum:Lightweight framing for high-rise crane-access constraints.
- Acrylic:Thermoformed surfaces for visual depth in premium residential applications.
Stainless Steel commands the installed base; Composite Wood climbs the fastest on sustainability-linked procurement.
Application:
End-use specifications diverge on ventilation capacity, appliance duty cycles, and accessibility compliance thresholds.
- Hospitality Suites:Heavy-duty exhaust systems with integrated fire suppression and commercial-grade refrigeration. Procurement concentrates in France and Germany where renovation cycles compress installation windows and guest disruption penalties exceed pod premiums.
- Student Housing:Compact footprints with space-efficient appliance configurations and vandal-resistant hardware. German university cities including Munich and Berlin drive volume through public-private partnership developments targeting rapid occupancy turnover.
- Residential Complexes:Standardized specifications for multi-family towers with uniform finish packages.
- Retirement Communities:Accessibility-compliant layouts with lowered counter heights and enhanced lighting integration.
Hospitality Suites dominate revenue per unit; Student Housing expands most quickly on unit volume.
Distribution Channel:
Channel selection reflects project scale, specification authority concentration, and documentation complexity for cross-border shipments.
- Direct Sales:Factory-to-developer relationships for multi-tower residential projects with bundled kitchen and bathroom module procurement. Major German and Dutch developers leverage this channel to compress vendor management overhead and align BIM data pipelines directly with production scheduling.
- Authorized Dealers:Regional stocking with installation coordination for mid-scale hospitality renovations. UK-based dealers dominate Northern European supply chains through CE marking documentation support and crane logistics expertise.
- Online Platforms:Specification browsing with digital configuration tools for preliminary project budgeting.
- Wholesale Distributors:Inventory aggregation for small-fabricator access to certified component supply chains.
Direct Sales capture the largest project value; Authorized Dealers penetrate renovation demand most deeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in Germany and the United Kingdom ship certified kitchen pods across EU member states, while North American producers serve domestic hospitality developers through direct sales channels. Trade flows concentrate where CE marking and local building code alignment eliminate cross-border friction.
Germany
Hotel renovation cycles in Berlin and Munich drive procurement of fire-rated modular kitchens, with operators prioritizing guest-room refresh speed over construction premiums. The country's national building energy standards enforce strict insulation performance thresholds for factory-assembled components. Bavaria's manufacturing corridor hosts steel-framed pod fabricators supplying student housing developments across German university cities.
United Kingdom
London residential tower developers bundle kitchen pods with bathroom modules to compress vendor management overhead on multi-unit projects. CE marking documentation requirements under the EU Construction Products Regulation shape export competitiveness for UK-based manufacturers serving Northern European markets. Midlands industrial clusters concentrate CNC-equipped factories with direct BIM-to-production data pipelines.
France
Boutique hospitality operators in Paris and Lyon specify custom pod configurations for branded interior differentiation during property renovations. The country's national building regulator enforces fire-reaction performance standards equivalent to NFPA exhaust specifications for commercial kitchen zones. Auvergne-Rhône-Alpes hosts composite wood panel specialists targeting carbon-footprint reduction mandates in residential construction.
United States
Hospitality developers in Florida and California leverage large-scale pod production capacity to accelerate hotel construction timelines amid skilled labor shortages. ICC and NFPA codes govern grease-duct pre-engineering requirements that factory builders must lock before production commencement. The Southeast manufacturing belt supplies roll-in installation units for high-rise residential towers from Atlanta to Miami.
Japan
Tokyo residential tower developers import insulation-efficient pod systems to meet METI building energy standards for high-density urban housing. The country's technical standards for factory quality assurance increasingly recognize offsite construction as equivalent to site inspection regimes. Kanto region engineering firms coordinate crane logistics for steel-framed kitchen modules in legacy building stock renovations.
Prefabricated Kitchen Pod Market Competitive Landscape
Concentration sits with vertically integrated manufacturers possessing in-house MEP engineering and multi-trade factory floor coordination. The vendor base stratifies across three tiers: large-scale hospitality suppliers with direct developer relationships, regional specialists in compact urban configurations, and emerging fabricators targeting carbon-certified residential materials. Two dominant competitive moves define positioning: backward integration into certified component supply chains, and geographic expansion through CE marking documentation support for cross-border shipments.
Within the hospitality supply tier, Walker Modular Ltd. and Oldcastle SurePods anchor manufacturer-direct procurement relationships with multi-tower developers. Offsite Solutions Ltd. occupies a position among compact-configuration specialists serving space-constrained urban micro-unit developments. These three entities exemplify the archetype divergence between scale-driven production and niche specification authority.
| Leading Market Players |
|---|
| Walker Modular Ltd. |
| Offsite Solutions Ltd. |
| Oldcastle SurePods |
| B&T Manufacturing |
| Pivotek LLC |
| Modulart |
| Hydrodiseno S.L. |
| Plant Prefab Inc. |
| Boxabl Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at UK and German steel-framed pod factories shapes both supply concentration and price floors, with underutilized lines in the Midlands corridor compressing margins across Northern European hospitality procurement.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratifying across CE-marked premium, standard fire-rated, and economy semi-assembled configurations. Price differentiation hinges on certification grade under EU Construction Products Regulation and volume scale in multi-tower residential bundles. Cost compression in standard tiers is intensifying because stainless steel input volatility transfers unevenly through fixed-price hospitality contracts. Student housing developers exhibit highest price sensitivity; boutique hotel operators absorb premiums for branded custom finishes.
Supply Chain Analysis
Container availability on Rotterdam-to-UK trade lanes constrains inbound logistics costs for composite wood panel feedstock sourced from Nordic suppliers. Manufacturing concentrates in Germany, the United Kingdom, and the Netherlands, drawing from stainless steel mills in Sheffield, fire-retardant chemistry suppliers in Basel, and appliance component clusters in Northern Italy. Single-source vulnerability sits with CE marking test houses accredited for kitchen pod fire-reaction performance. Distribution runs through factory-direct relationships for bundled kitchen-bathroom procurement and authorized dealer networks for renovation crane logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against site-built millwork, with custom carpentry retaining cost competitiveness in one-off luxury residential projects.
For Market Incumbents: Shield hospitality supply relationships through backward integration into certified low-GWP component supply chains under evolving EU F-Gas Regulation thresholds. Consolidate procurement authority by bundling bathroom modules with kitchen pods to marginalize standalone cabinet competitors. CE marking documentation expertise serves as the priority defensive moat against cross-border entrants. For New Entrants and Emerging Players: Anchor in Japanese residential tower imports by engineering METI-compliant insulation and appliance efficiency specifications. Student housing micro-units in German university cities represent the most penetrable white-space segment. Pursue direct-to-developer BIM-to-factory data pipelines as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with in-house MEP engineering and multi-trade factory floor coordination. Long-term viability across the projection horizon favors acquisition targets possessing captive certified component supply and CE marking documentation capabilities. Monitor crane logistics capacity constraints in legacy European residential towers as the inflection signal for installation-margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Components | Captures margin pools from low-GWP refrigerant and insulation suppliers under REACH and F-Gas Regulation compliance. |
| BIM-to-Factory Data Pipeline Deployment | Compresses design-to-delivery cycles for German student housing and Dutch residential tower developments. |
| CE Marking Documentation Expansion | Enables cross-border pod shipments from UK Midlands factories into French and German hospitality renovation cycles. |
| Compact Configuration R&D Investment | Targets space-constrained urban micro-units in Munich, Berlin, and Tokyo high-density residential towers. |
| Crane Logistics Partnership Network | Resolves installation barriers in legacy European residential stock with dimensional mismatches and access constraints. |
Research Methodology
A standing panel of hospitality procurement directors, student housing development managers, factory operations leads, and CE marking compliance officers provided ongoing calibration across the study. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against EU Construction Products Regulation filings, national building energy standard documentation, customs trade data for steel and composite wood inputs, and hospitality development pipeline databases. Bottom-up unit shipment estimates triangulated against top-down construction spend allocations.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product completion level, material fire-reaction classification, end-use application, and distribution channel concentration. CAGRs derived from regression analysis of historical installation rates against construction labor shortage indices and regulatory harmonization milestones. Industry-specific forecast inputs incorporated METI building energy standard adoption curves and EU F-Gas Regulation phase-down schedules.
Material uncertainties — construction labor shortage persistence, stainless steel price volatility, and CE marking accreditation bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and cross-border trade flow continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market