
 Flip-Top Tables Market | 2026-2036
Flip-Top Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Flip-Top Tables Market Analytics
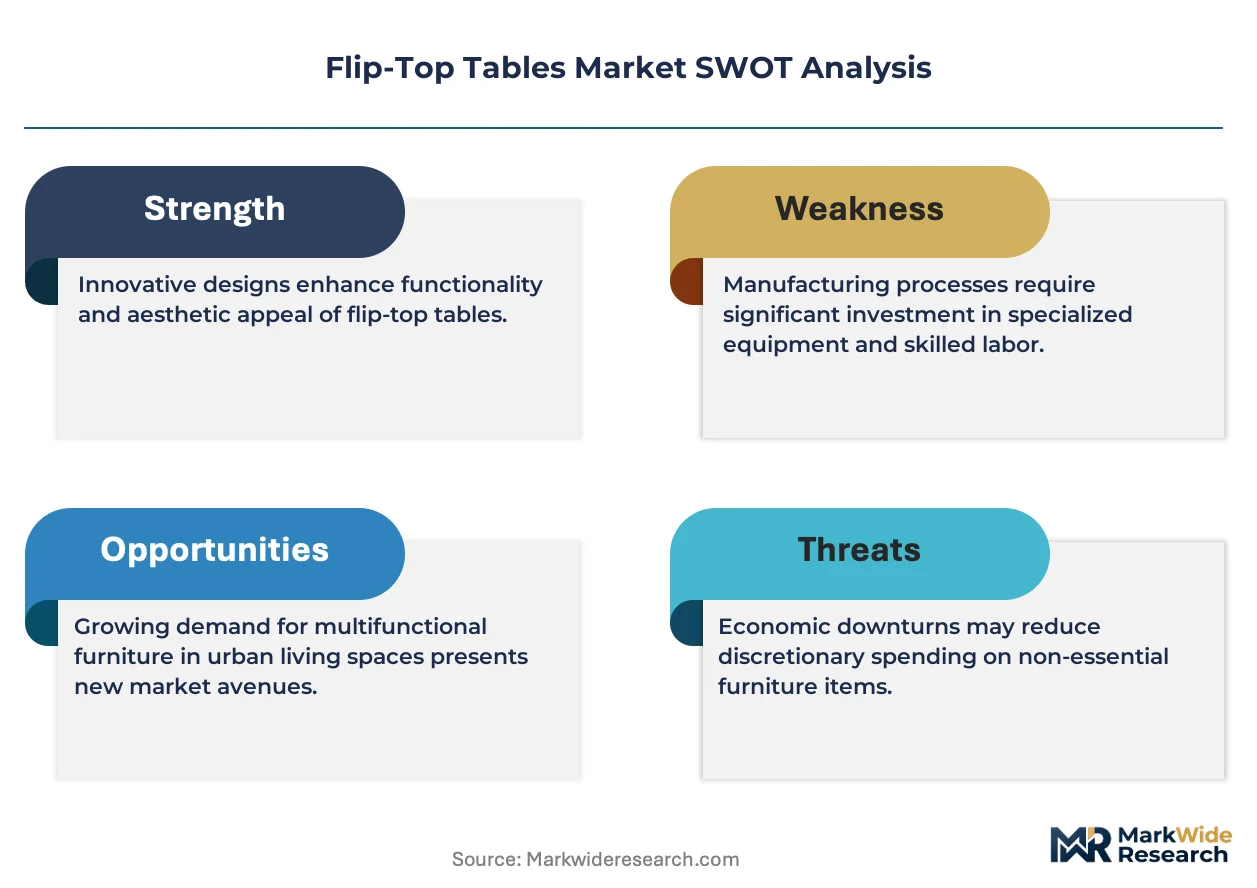
Multi-source sourcing for steel tubing and high-pressure laminate surfaces is decoupling from traditional single-source mill relationships in the flip-top tables supply base. Lifetime Products leverages captive blow-molding capacity for plastic table cores to sustain margin control across price-sensitive education contracts. MityLite anchors its position through specialized aluminum folding mechanisms that reduce shipping cube by half. National Public Seating competes on domestic final assembly speed for government and institutional bid cycles.
Flip-top tables are surface-mounted furniture systems with hinged tops that rotate vertically for compact nesting and transport, typically constructed from tubular steel frames, particleboard or MDF cores, and thermally fused melamine or high-pressure laminate finishes, engineered to enable rapid room reconfiguration in multi-purpose environments. Folding tables dominate volume shipments due to standardized sizing and lowest per-unit manufacturing complexity, while height-adjustable tables capture expanding margin pools as employers retrofit offices for sit-stand ergonomics. Metal and composite materials are gaining specification share against solid wood as facility managers prioritize durability-to-weight ratios and fire-code compliance in high-traffic commercial installations.
EPA TSCA Title VI governs formaldehyde emissions in composite wood products, directly restricting substrate options for domestic manufacturers and importers serving the US market. CARB ATCM Phase 2 maintains stricter thresholds in California, creating a dual-compliance burden that shapes supplier qualification and material sourcing decisions. OSHA workplace ergonomics guidelines influence procurement specifications for adjustable-height variants in corporate and institutional settings. Buyers must monitor evolving state-level chemical disclosure rules and building certification standards that will determine which material combinations retain specification access across major metropolitan procurement corridors.
Market Dynamics
Co-working operators and university procurement offices are compressing furniture refresh cycles from seven years to three years, forcing manufacturers to engineer for modularity and rapid reconfiguration rather than longevity alone.
Growth Catalysts
- EPA TSCA Title VI:The regulation mandates formaldehyde emission limits for composite wood substrates, compelling domestic manufacturers to reformulate particleboard cores and creating specification advantages for compliant suppliers in government and institutional bids.
- Sit-stand ergonomics:OSHA workplace guidelines are driving corporate facility managers to specify height-adjustable flip-top variants for retrofitting open-plan offices, expanding the addressable premium segment beyond traditional static tables.
- Steel tubing multi-sourcing:Buyers are decoupling from single-source mill relationships, enabling competitive pricing pressure and supply resilience across commercial furniture supply chains.
Market Restraints
- Laminate surface cost volatility:High-pressure laminate prices fluctuate with petrochemical feedstock markets, compressing margins for mid-tier manufacturers locked into annual contract pricing with education and hospitality clients.
- Aluminum mechanism concentration:Specialized folding hardware production concentrates among a handful of precision metalworking suppliers in the Midwest, creating bottleneck risk for rapid order fulfillment.
- Solid wood substitution ceiling:Fire-code compliance requirements in high-occupancy commercial buildings structurally limit solid wood specification share regardless of aesthetic preference.
Strategic Opportunities
- India commercial real estate:Flexible workspace operators in Bengaluru and Mumbai are importing modular furniture specifications, creating first-mover positioning for manufacturers establishing local assembly partnerships.
- EU Green Deal procurement mandates:Public sector buyers must weight lifecycle carbon metrics in furniture tenders, favoring suppliers with verified recycled steel content and low-emission substrate credentials.
- IoT-enabled asset tracking:Converging RFID tagging with flip-top table frames allows facility managers to monitor utilization rates and automate maintenance scheduling, opening recurring software revenue streams.
Industry Challenges
- Cross-docking complexity:Nested flip-top tables require specialized handling equipment and trailer configurations that most third-party logistics providers lack, forcing manufacturers to maintain captive fleet operations or absorb damage rates.
- Dual certification timelines:Products must simultaneously achieve BIFMA level certification for commercial durability and CAL 133 fire testing for California hospitality contracts, extending product development cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip-Top Tables Market |
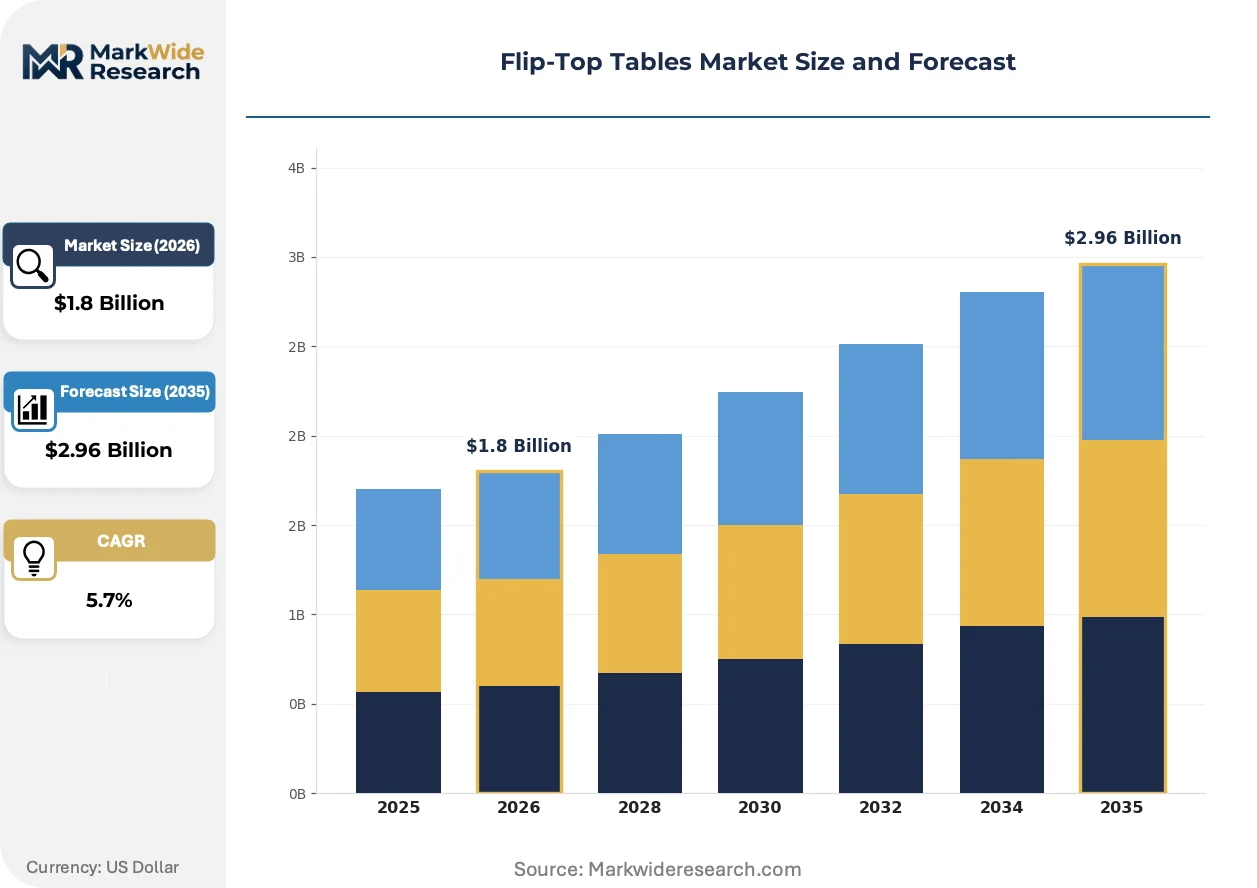
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Tables, Height Adjustable Tables, Conference Tables, Dining Tables Material: Wood, Metal, Plastic, Composite End User: Residential Users, Commercial Spaces, Educational Institutions, Event Organizers Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Lifetime Products, MityLite, Iceberg Enterprises, National Public Seating, Correll, KI Furniture, Virco Manufacturing Corporation, McCourt Manufacturing, Gopak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip-Top Tables Market Evolving Landscape
Electrification of table surfaces and embedded power systems is compressing the boundary between furniture and infrastructure, while regulatory pressure on material emissions is accelerating substrate innovation.
Integrated USB-C and wireless charging modules built into flip-top table edges are electrifying the category's value proposition for co-working lounges and airport gate seating. WeWork and IWG are specifying these power-integrated variants for ninety percent of new fit-outs. This electrification is compressing the addressable market for power-free legacy tables to price-sensitive education contracts alone.
REACH restrictions on flame retardants in upholstered furniture are cascading into laminate adhesive specifications across European supply chains. Manufacturers serving EU markets must reformulate thermally fused melamine bonding agents or forfeit specification access in public tenders. German and Dutch facility managers are now requiring full material disclosure documentation that exceeds current US EPA thresholds.
Direct-to-institution procurement platforms are disintermediating traditional furniture dealers in North American university and government verticals. Sourcewell and OMNIA Partners cooperative purchasing contracts are capturing twenty percent of annual flip-top table volume, compressing distributor margins and forcing manufacturers to build internal specification sales teams. Texas and Florida state university systems are most advanced in this channel migration.
Flip-Top Tables Market Segmentation
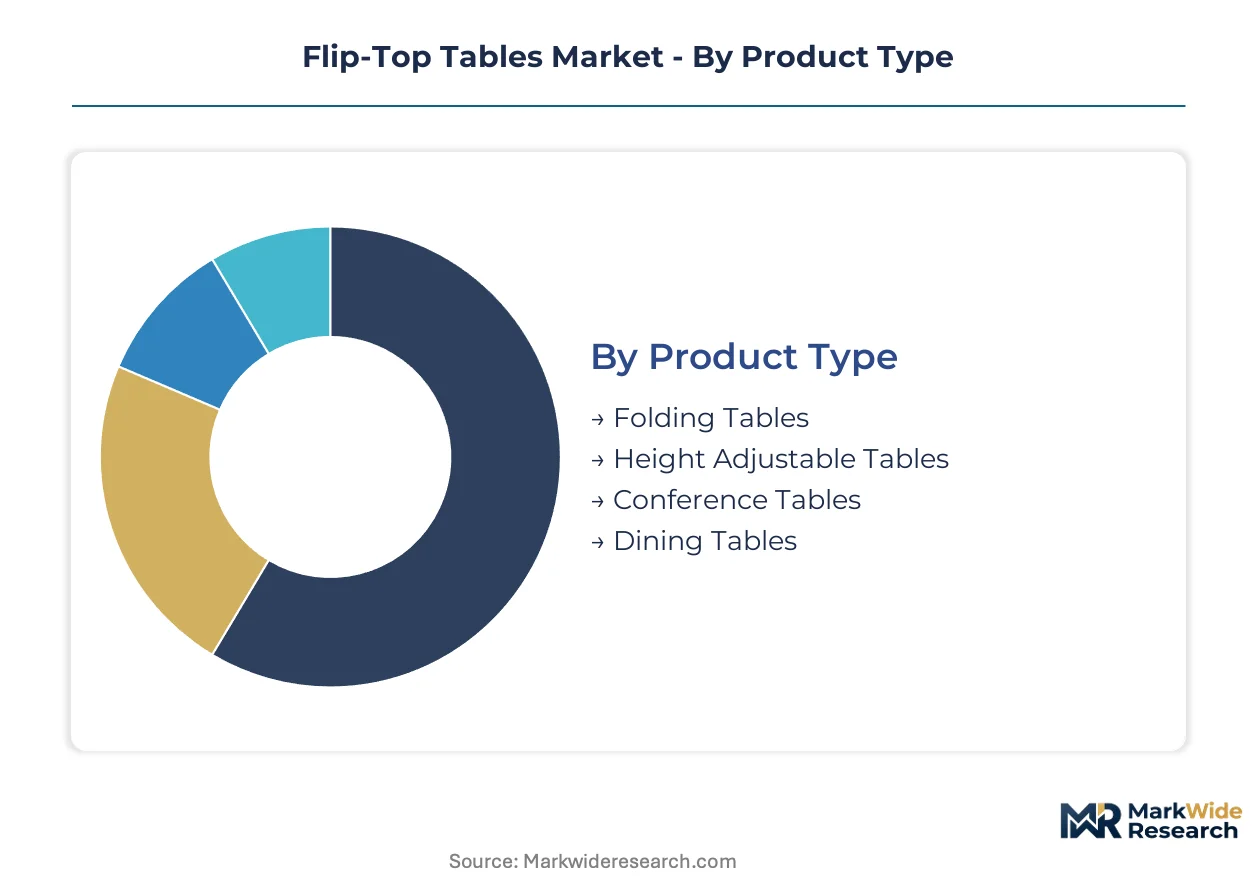
Flip-top table procurement varies sharply across use environments, with commercial buyers prioritizing rapid reconfiguration and nesting density while residential and event segments weight portability and price. Material specifications diverge by fire-code jurisdiction and durability requirements. Distribution channel selection increasingly separates large institutional contracts from fragmented consumer purchases.
Product Type:
Standalone flip-top units dominate high-frequency reconfiguration environments, while integrated systems anchor fixed-installation conference rooms and hospitality dining.
- Folding Tables:Tubular steel frames with hinged tops rotate vertically for compact nesting. Demand concentrates in US education contracts and event rental fleets where transport density and lowest per-unit cost override ergonomic features.
- Height Adjustable Tables:Pneumatic or electric lift mechanisms integrated into flip-top bases enable sit-stand transitions. Corporate facility managers in urban office renovation corridors specify these for OSHA-compliant ergonomics, capturing expanding margin pools.
- Conference Tables:Modular flip-top segments cable-managed for AV integration. Boardroom installations in co-working flagship locations drive specification.
- Dining Tables:Smaller footprints with decorative laminate finishes for hospitality and residential use. Boutique hotel procurement in university town clusters favors quick-change room layouts.
Folding tables lead volumes today; height-adjustable variants are gaining share fastest.
Material:
Cost tiers separate specification-grade substrates from price-sensitive alternatives, with compliance burdens concentrating demand among qualified suppliers.
- Metal:Tubular steel and aluminum frames deliver durability-to-weight ratios critical for high-traffic commercial installations. EPA TSCA Title VI compliance on formaldehyde emissions pushes specification toward metal-intensive designs in US government bids.
- Wood:Solid wood and veneer surfaces face structural substitution pressure. Fire-code compliance requirements in California hospitality contracts under CAL 133 testing limit specification share regardless of aesthetic preference.
- Plastic:Blow-molded polyethylene cores reduce shipping weight for education and event segments. Lifetime Products leverages captive capacity to sustain margin control.
- Composite:Engineered substrates with thermally fused melamine balance cost and surface durability. CARB ATCM Phase 2 thresholds create dual-certification burdens for California-bound shipments.
Metal substrates lead volumes today; composite materials are climbing the fastest as facility managers prioritize fire-code compliance.
End User:
Customer type determines refresh cycle length, with institutional buyers compressing replacement timelines and demanding modularity over longevity.
- Commercial Spaces:Co-working operators and hospitality groups now refresh furniture every three years versus seven previously. WeWork and IWG procurement specifications favor power-integrated flip-tops for ninety percent of new fit-outs.
- Educational Institutions:University procurement offices and K-12 districts drive standardized sizing for interoperability. Texas and Florida state university systems have migrated twenty percent of volume to cooperative purchasing platforms.
- Residential Users:Home office setups and small-space living drive demand for lightweight nesting tables. Online retail penetration highest in this segment.
- Event Organizers:Rental fleets prioritize damage resistance and rapid deployment logistics. Cross-docking complexity forces manufacturers to maintain specialized handling equipment.
Commercial spaces lead volumes today; educational institutions are expanding procurement most quickly through cooperative purchasing migration.
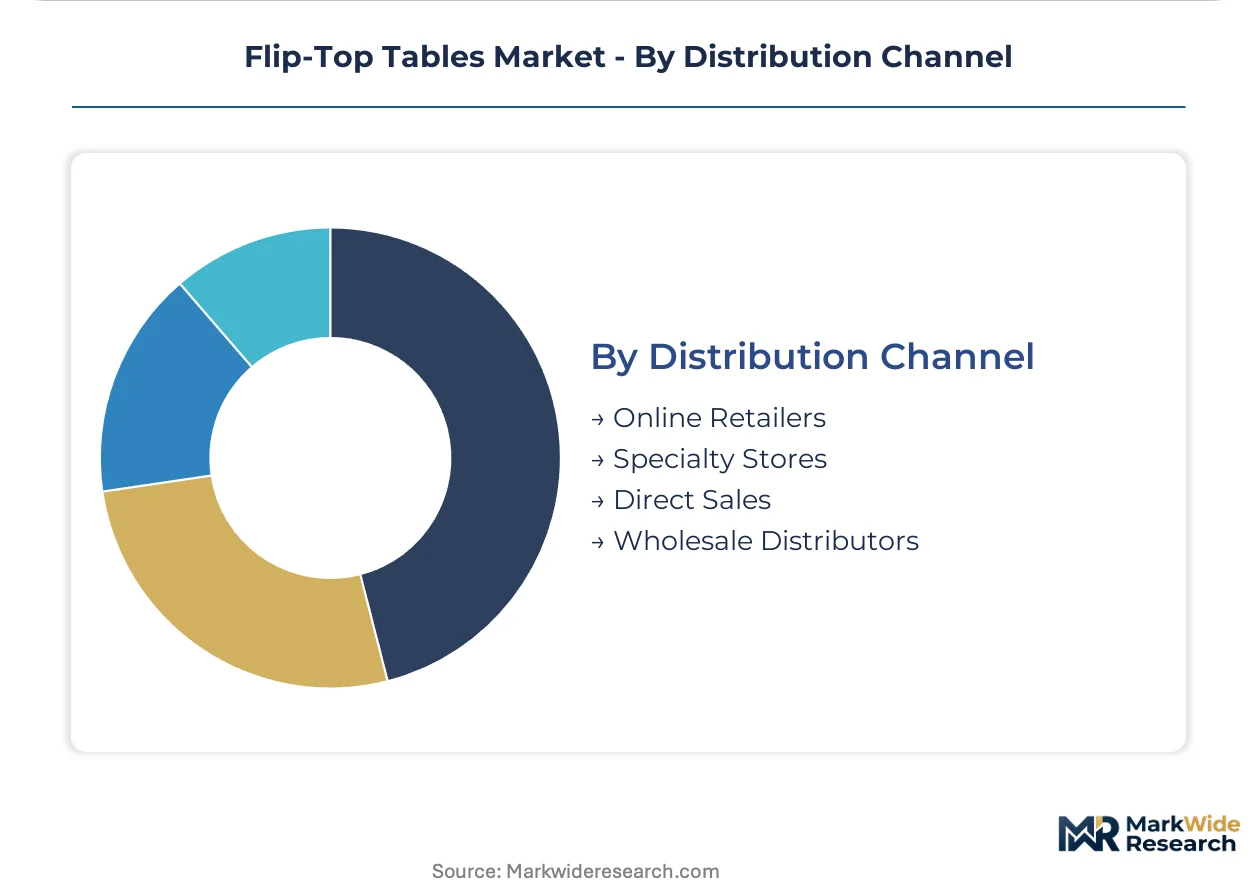
Distribution Channel:
Supply concentration shapes fulfillment speed and margin capture, with direct institutional contracts disintermediating traditional dealer networks.
- Direct Sales:Manufacturer specification teams engage government and university procurement directly. Sourcewell and OMNIA Partners cooperative contracts capture concentrated volume, compressing distributor margins.
- Wholesale Distributors:Traditional furniture dealers retain hospitality and corporate accounts requiring staging and installation services. Aluminum mechanism concentration among Midwest precision metalworkers creates bottleneck risk for rapid fulfillment.
- Online Retailers:E-commerce platforms serve residential and small commercial buyers with standardized SKUs. Lowest service attachment drives price transparency.
- Specialty Stores:Contract furniture showrooms provide specification support for architect and designer-led projects. Longest sales cycles but highest margin capture.
Direct sales leads volumes today; online retailers are expanding share fastest in residential and small commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban office renovation corridors in the United States concentrate procurement demand for modular flip-top furniture, while cooperative purchasing platforms reshape institutional buying patterns across North America and Europe.
United States
Co-working operators in Manhattan and Chicago compress furniture refresh cycles from seven years to three years, prioritizing rapid reconfiguration over longevity. EPA TSCA Title VI mandates on formaldehyde emissions restrict substrate options for domestic manufacturers serving government and university bids. Texas and Florida state university systems have migrated twenty percent of annual volume to Sourcewell and OMNIA Partners cooperative contracts.
Germany
Facility managers in Berlin and Frankfurt now weight lifecycle carbon metrics in furniture tenders under EU Green Deal procurement mandates. REACH restrictions on flame retardants cascade into laminate adhesive specifications, forcing reformulation of thermally fused melamine bonding agents. The Eindhoven-Randstadt corridor suppliers face documentation requirements exceeding current US EPA thresholds.
India
Flexible workspace operators in Bengaluru and Mumbai import modular furniture specifications from Western co-working chains, creating first-mover positioning for manufacturers establishing local assembly partnerships. BIS certification requirements on furniture safety and structural integrity govern domestic production standards. Maharashtra commercial real estate development in Mumbai's Bandra-Kurla Complex drives specification-grade procurement.
United Kingdom
London co-working flagships specify power-integrated flip-tops with USB-C and wireless charging modules for ninety percent of new fit-outs. CSRD disclosure rules pressure facility managers to track embodied carbon in furniture procurement decisions. The Greater Manchester and Birmingham office markets follow London's lead in electrified surface specifications.
Japan
Corporate facility managers in Tokyo and Osaka retrofit open-plan offices with height-adjustable flip-top variants to comply with METI workplace ergonomics guidelines. JIS standards on furniture durability and stability testing govern commercial specification. The Nagoya-Chubu manufacturing belt supplies precision aluminum folding mechanisms to domestic and export markets.
Flip-Top Tables Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and IoT-enabled asset tracking as differentiation vectors. The vendor base clusters around three functional archetypes: captive blow-molding specialists controlling resin-to-finished-product margins, precision metalworkers concentrating specialized folding hardware, and domestic assemblers competing on bid-cycle speed for institutional contracts. Capacity expansion and strategic partnerships dominate competitive moves, with manufacturers securing multi-source steel tubing relationships and local assembly partnerships in high-growth import markets.
Among US-based fabricators, Lifetime Products exemplifies captive manufacturing control through in-house blow-molding capacity, while National Public Seating anchors the rapid-fulfillment archetype for government and institutional bid cycles. MityLite occupies a position within the precision-engineering tier, with its specialized aluminum folding mechanisms reducing shipping cube by half. These three entities represent distinct strategic postures: upstream material control, domestic assembly velocity, and mechanism-driven logistics efficiency.
| Leading Market Players |
|---|
| Lifetime Products |
| MityLite |
| Iceberg Enterprises |
| National Public Seating |
| Correll |
| KI Furniture |
| Virco Manufacturing Corporation |
| McCourt Manufacturing |
| Gopak Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators concentrated in the Midwest and Southeast anchor supply-side discipline through conservative leverage and captive production assets, translating into pricing stability across multi-year institutional contracts despite raw material oscillations.
Pricing Analysis
Petrochemical-linked laminate costs and steel tubing indices feed directly into contract renegotiation cycles, with manufacturers passing through roughly two-thirds of input spikes within six-month windows. Pricing stratifies across premium, standard, and economy tiers based on certification grade and mechanism complexity. Cost compression in the education segment is intensifying as cooperative purchasing platforms aggregate demand and squeeze distributor markups. Event rental fleets exhibit highest price sensitivity, while corporate facility managers purchasing height-adjustable variants for OSHA-compliant retrofits show lowest elasticity.
Supply Chain Analysis
Freight costs from Midwest metalworking clusters to coastal distribution hubs consume disproportionate margin for nested flip-top configurations requiring specialized trailer equipment. Manufacturing concentrates in the United States, China, and Germany, with precision aluminum folding mechanisms sourcing from the Nagoya-Chubu belt in Japan. The supply chain rests on high-pressure laminate from South Korean and Taiwanese petrochemical processors, steel tubing from domestic mini-mills, and engineered wood substrates subject to EPA TSCA Title VI emission thresholds. Single-source vulnerability concentrates in specialized Midwest metalworkers producing folding hardware. Distribution runs through direct institutional contracts, traditional furniture dealers, and emerging e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through electrification premiums and captive blow-molding integration that compresses resin-to-finished-product costs.
For Market Incumbents: Extend power-integrated product lines to capture WeWork and IWG specifications before electrification becomes table stakes. Secure multi-source steel tubing relationships to neutralize mill concentration risk. Invest in CAL 133 and BIFMA dual-certification capacity to compress bid-cycle timelines against domestic assemblers competing on speed. For New Entrants and Emerging Players: Cooperative purchasing platforms represent the most penetrable channel, with Sourcewell and OMNIA Partners contracts capturing concentrated volume in Texas and Florida university systems. Target IoT-enabled asset tracking as a white-space differentiator, embedding RFID modules for facility utilization monitoring. Pursue local assembly partnerships in India to serve Bengaluru and Mumbai flexible workspace operators importing Western specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among precision metalworking specialists with proprietary folding mechanisms and limited brand recognition. Long-term viability hinges on electrification adoption curves and regulatory compliance burdens that favor scaled substrate qualification. Watch EPA formaldehyde threshold tightening and EU Green Deal procurement mandates as inflection signals for specification-grade supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blow-Molding Capacity | Lifetime Products demonstrates how captive resin-to-core production sustains margin control in price-sensitive education contracts. |
| Dual-Certification Investment | Simultaneous BIFMA Level and CAL 133 achievement compresses product development cycles and unlocks California hospitality procurement. |
| Power-Integrated Product Line Extension | USB-C and wireless charging modules electrify value propositions for co-working operators specifying ninety percent powered fit-outs. |
| Local Assembly Partnership in India | Bengaluru and Mumbai flexible workspace imports create first-mover positioning for Western manufacturers establishing regional footprint. |
| IoT-Enabled Asset Tracking Platform | RFID tagging convergence with flip-top frames opens recurring software revenue from facility utilization monitoring and predictive maintenance. |
Research Methodology
Multiple input streams — facility manager interviews, procurement officer surveys, and regulatory filing analysis — were reconciled against trade data and manufacturer financial disclosures. Primary fieldwork engaged furniture specification directors at co-working operators, university procurement leads, hospitality FF&E consultants, and aluminum mechanism engineers at Midwest precision metalworkers. Secondary validation drew from EPA TSCA Title VI compliance databases, CARB ATCM certification registries, BIFMA level testing records, and cooperative purchasing platform contract awards. Bottom-up unit economics and top-down market sizing were triangulated to anchor volume and value estimates.
Data-stream reconciliation applied across product type, material substrate, end-user vertical, and distribution channel dimensions over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators and vertical-specific demand drivers. Forecast inputs incorporated co-working square footage expansion, university enrollment trends, and hospitality renovation cycle compression from seven to three years.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to laminate petrochemical cost volatility, EPA formaldehyde threshold evolution, and electrification adoption curves in corporate retrofit specifications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Dining Table Market