
 Global Kitchenware Market | 2026-2036
Global Kitchenware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kitchenware Market Intelligence
The split between premium enameled cast iron and mass-market aluminum cookware is realigning how manufacturers allocate capital and brand investment. Groupe SEB leverages its multi-brand architecture to span both tiers across European and Asian markets. Meyer Corporation anchors North American distribution through department store partnerships and direct-to-consumer channels. TTK Prestige Ltd. dominates India's pressure-cooker segment while extending into premium stainless steel cookware for urban households.
Kitchenware comprises vessels, utensils, and implements used in food preparation, cooking, serving, and storage, typically manufactured from metals, ceramics, glass, or synthetic polymers with specified heat conductivity and food-contact safety parameters. Cookware in stainless steel and cast iron commands the highest margin pools due to durability premiums and replacement cycles, while bakeware in silicone and ceramic represents the fastest-expanding material segment driven by oven-safe versatility and color aesthetics. Specialty stores and online retailers together capture the most dynamic sales channel growth as consumers research material specifications before purchase.
The EU's REACH regulation and F-Gas framework restrict perfluorinated compounds in non-stick coatings, compelling reformulation toward ceramic and diamond-infused alternatives. FDA food-contact substance notifications govern import eligibility for coated aluminum goods entering the United States. China's GB standards and SAMR oversight enforce nickel migration limits in stainless steel exports. Stakeholders must monitor evolving chemical compliance thresholds across multiple jurisdictions to sustain market access and avoid inventory obsolescence.
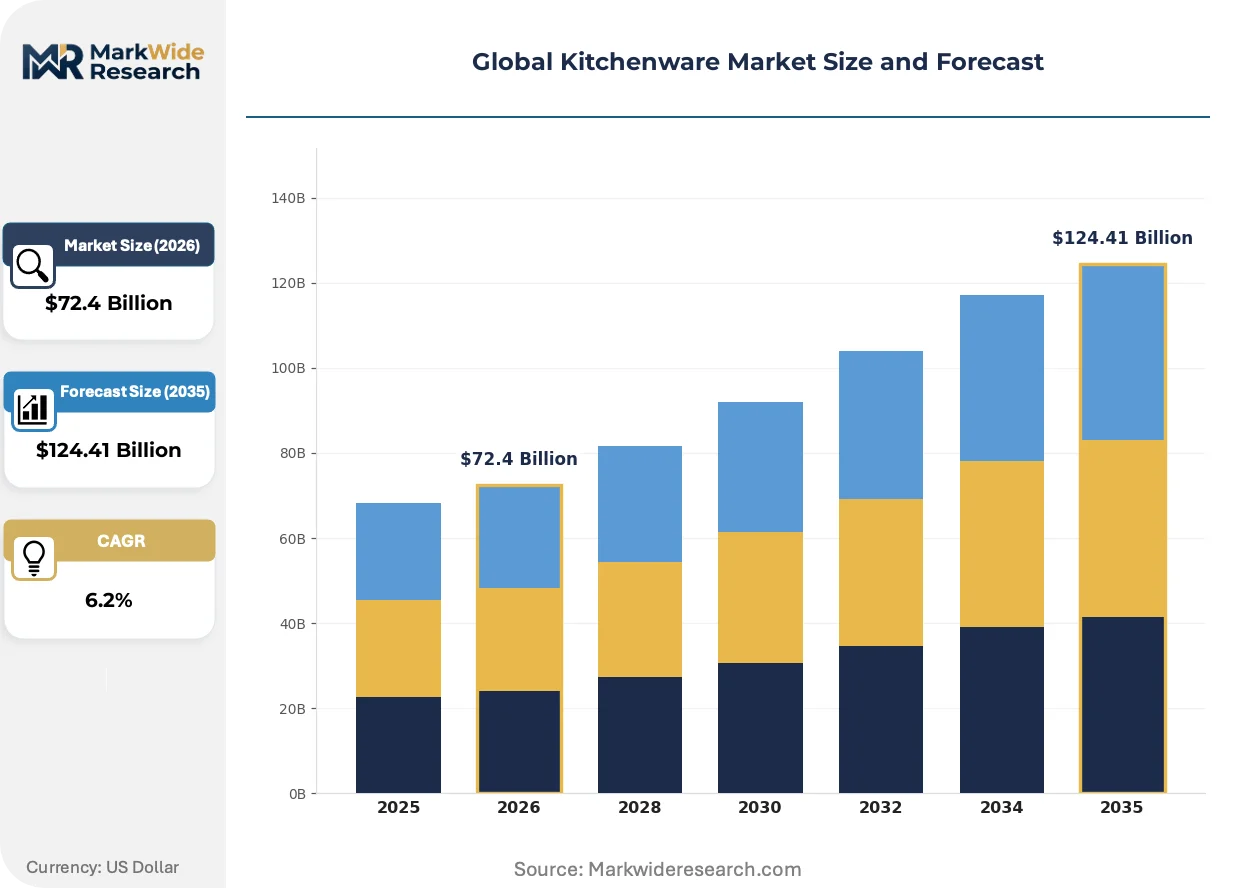
Market Dynamics
EU REACH and F-Gas Regulation compliance costs are compressing margins for non-stick coating manufacturers while redirecting R&D budgets toward ceramic and diamond-infused alternatives. The regulatory burden falls unevenly across the supply base, favoring integrated producers with in-house formulation labs over import-dependent distributors.
Growth Catalysts
- Commercial kitchen expansion:Food service operators in North America and Western Europe are replacing worn equipment after deferred maintenance during pandemic-era closures. Professional-grade stainless steel and cast iron orders from restaurant chains are accelerating production line utilization at specialized foundries.
- REACH-driven material innovation:The EU's restriction on perfluorinated compounds has forced coating suppliers to commercialize sol-gel ceramic alternatives. Reformulation investments are now yielding patent-protected product lines that command durability premiums in export markets.
- China manufacturing cluster scale:Guangdong and Zhejiang provinces host vertically integrated cookware production from raw aluminum smelting through enamel finishing. Concentrated supplier networks enable rapid prototyping for private-label buyers and reduce minimum order quantities for emerging brands.
Market Restraints
- Raw material cost volatility:Nickel and chromium price swings in stainless steel alloys create margin unpredictability for mid-tier producers without long-term commodity hedging programs. Foundries pass through 60-80% of input spikes within one quarter, eroding distributor inventory valuations.
- Supply concentration risk:Over 70% of global ceramic glaze production concentrates in Shandong province facilities. Single-source dependency for heat-resistant coatings exposes brands to logistics disruption and quality inconsistency during peak export seasons.
- Substitution pressure from meal-kit packaging:Single-use oven-safe aluminum trays and compostable bakeware reduce household cookware purchase frequency among urban millennials. Convenience-oriented food delivery services displace home cooking occasions that drive replacement cycles.
Strategic Opportunities
- India urban premium segment:Tier-1 city households are upgrading from basic aluminum to tri-ply stainless steel and hard-anodized collections. Local assembly partnerships can circumvent 15-20% import duties while leveraging BIS certification requirements that disadvantage direct exporters.
- Induction-compatible retrofit demand:European rental housing stock conversion to induction cooktops creates replacement demand for legacy aluminum cookware. Ferromagnetic base retrofit services and adapter plate accessories represent ancillary revenue streams for existing brand owners.
- EU Green Deal circularity mandates:Upcoming ecodesign requirements for product durability and recyclability will favor cast iron and premium stainless steel with documented lifecycle data. Early compliance positioning secures preferred placement in retailer sustainability programs.
Industry Challenges
- Coating chemist talent scarcity:Reformulation of PTFE-free non-stick surfaces requires rare expertise in sol-gel chemistry and plasma deposition. European and North American manufacturers compete for limited PhD-level formulation scientists against semiconductor and aerospace sectors.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact notification, EU REACH registration, and China GB standard testing extends new product introduction cycles to 18-24 months. Parallel regulatory submissions strain quality assurance teams and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kitchenware Market |
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $124.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware, Bakeware, Tableware, Kitchen Tools, Storage Containers Material: Stainless Steel, Cast Iron, Ceramic, Silicone, Glass Sales Channel: Specialty Stores, Online Retailers, Department Stores, Supermarkets, Direct Selling Customer Type: Households, Food Service Businesses, Hospitality Sector, Culinary Schools |
| Companies Covered | Tramontina, Fissler, Groupe SEB, Wilh. Werhahn KG., Le Creuset Group, Meyer Corporation, TTK Prestige Ltd., SCANPAN, Newell Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kitchenware Market Strategic Shifts & Innovations
Active reformulation of non-stick chemistries and induction-compatible base designs are reshaping product development priorities. Manufacturers balance regulatory compliance against performance benchmarks that consumers associate with legacy coating technologies.
Ceramic-reinforced sol-gel coatings are overtaking traditional PTFE-based non-stick surfaces in premium cookware lines. Direct-to-consumer brands and specialty retailers are accelerating adoption to preempt regulatory restrictions and capture sustainability-minded buyers. The shift is compressing margins for commodity aluminum producers unable to fund reformulation R&D while rewarding integrated manufacturers with captive coating facilities.
ECHA's 2023 restriction proposal on PFAS compounds has triggered inventory destocking across European distribution channels. Importers are redirecting sourcing toward Turkish and Indian suppliers with established ceramic coating capabilities. The regulatory friction most severely affects discount retailers with long-lead private-label programs and limited supplier flexibility.
Specialty store and online channel convergence is fragmenting traditional department store dominance in cookware distribution. Consumers research material specifications through video content and third-party testing sites before purchasing. This behavioral shift is most pronounced in Germany and the United Kingdom, where kitchen specialty chains have expanded showroom footprints to capture comparison-shopping traffic.
Global Kitchenware Market Segmentation
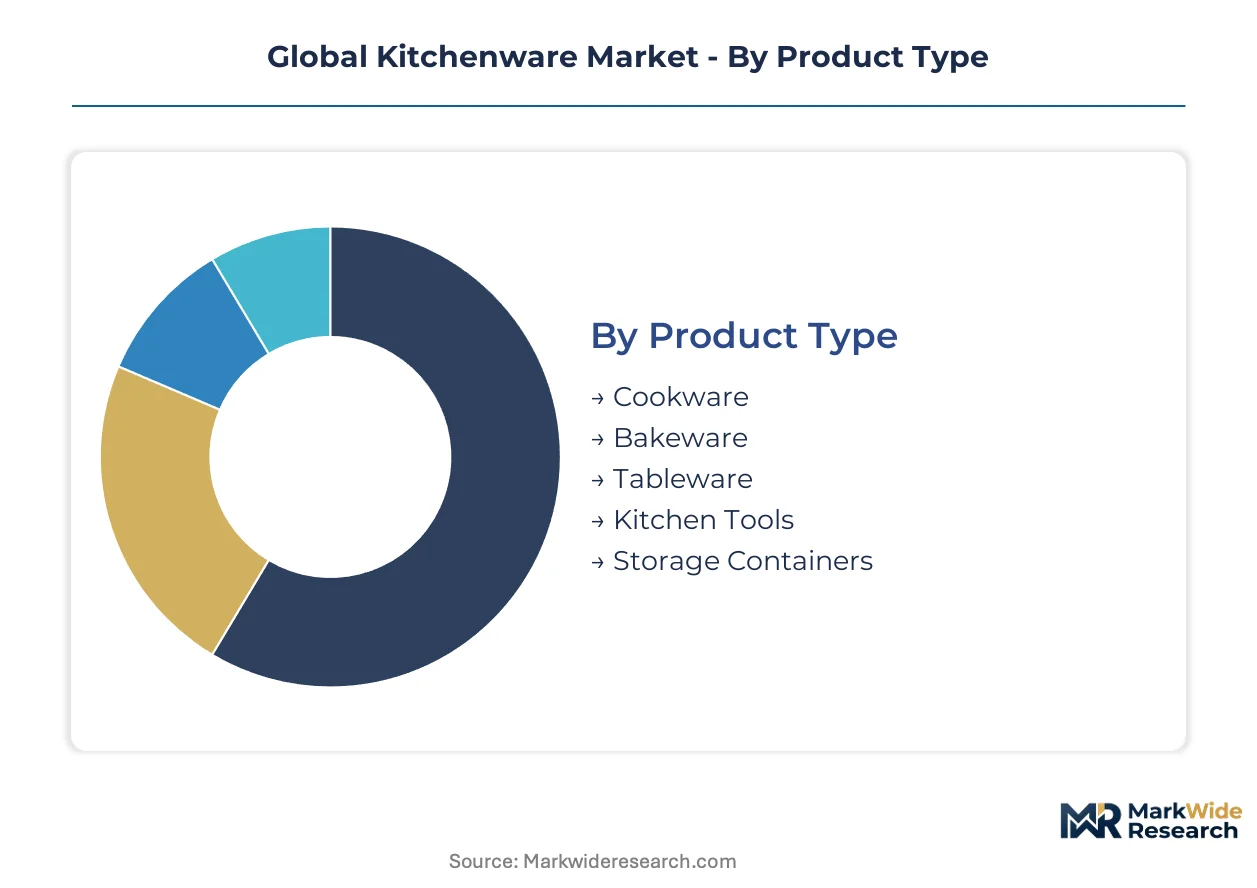
Kitchenware purchasing decisions diverge sharply across end-use contexts, from commercial kitchens prioritizing thermal conductivity specifications to households selecting for color aesthetics and storage efficiency. Manufacturers configure product lines, pricing architectures, and distribution partnerships around these distinct buyer profiles rather than pursuing undifferentiated scale.
Product Type:
Professional kitchens and home cooks allocate budgets differently based on heat distribution requirements, replacement cycles, and frequency of use.
- Cookware:Vessels designed for stovetop and oven heat application, including saucepans, skillets, and stockpots with specified thermal conductivity ratings. Restaurant chains in Germany and Japan are expanding procurement of tri-ply stainless steel and enameled cast iron as deferred equipment replacement resumes.
- Bakeware:Oven-safe forms for bread, pastry, and dessert preparation, manufactured from aluminized steel, ceramic, or silicone composites. Silicone-flexible and ceramic-glazed formats are expanding most quickly in direct-to-consumer channels across France and the United Kingdom.
- Tableware:Serving vessels and flatware for food presentation, spanning formal dining collections and casual everyday sets. Italian and Portuguese manufacturers dominate premium porcelain export markets through heritage positioning.
- Kitchen Tools:Implements including spatulas, ladles, whisks, and cutting boards with food-contact safety certifications. Japanese carbon steel knife collections command durability premiums in North American specialty retail.
- Storage Containers:Lidded vessels for refrigeration, freezing, and pantry organization, with glass and BPA-free polymer formats displacing legacy plastic. Airtight sealing mechanisms and modular stacking dimensions drive replacement demand in South Korean urban households.
Cookware leads volumes today; bakeware is gaining share fastest.
Material:
Raw material selection determines regulatory compliance pathways, margin structures, and end-use performance benchmarks.
- Stainless Steel:Iron-chromium-nickel alloys with corrosion resistance and induction compatibility, specified by grade (304, 316, 430) for food-contact applications. China's SAMR enforces nickel migration limits that filter export eligibility for lower-grade alloys.
- Cast Iron:Carbon-rich ferrous metal with superior heat retention, requiring enamel coating or seasoning maintenance. French foundries in Haute-Savoie and Ardennes anchor premium enameled production for global distribution.
- Ceramic:Clay-based materials fired at high temperatures for heat-resistant cookware and decorative tableware. Shandong province facilities supply over 70% of global ceramic glaze production, creating single-source concentration risk.
- Silicone:Synthetic elastomers with temperature stability from freezing to oven exposure, prevalent in bakeware and utensil categories. FDA food-contact substance notifications govern import eligibility for silicone goods entering the United States.
- Glass:Borosilicate and soda-lime formulations for bakeware and storage, valued for chemical inertness and visual transparency. German manufacturers lead technical glass production for laboratory-grade kitchen applications.
Stainless steel dominates current revenue; ceramic formats are climbing the fastest.
Sales Channel:
Channel selection shapes how manufacturers communicate material specifications and build brand equity.
- Specialty Stores:Dedicated kitchenware retailers with trained staff and physical product demonstration. German chains have expanded showroom footprints to capture comparison-shopping traffic from department store defectors.
- Online Retailers:E-commerce platforms enabling specification research through video content and third-party testing. Direct-to-consumer brands leverage this channel to preempt regulatory restrictions and capture sustainability-minded buyers.
- Department Stores:Traditional multi-category retailers with cookware as a home goods anchor. Meyer Corporation maintains North American distribution through these partnerships despite traffic erosion.
- Supermarkets:Mass-market grocery retailers carrying basic cookware and kitchen tools as convenience purchases. Private-label programs dominate this channel with price-competitive aluminum offerings.
- Direct Selling:Catalog, party-plan, and brand-ambassador networks for premium collections. Tupperware and equivalent models persist in emerging markets with limited retail infrastructure.
Specialty stores anchor premium positioning today; online retailers are expanding most quickly.
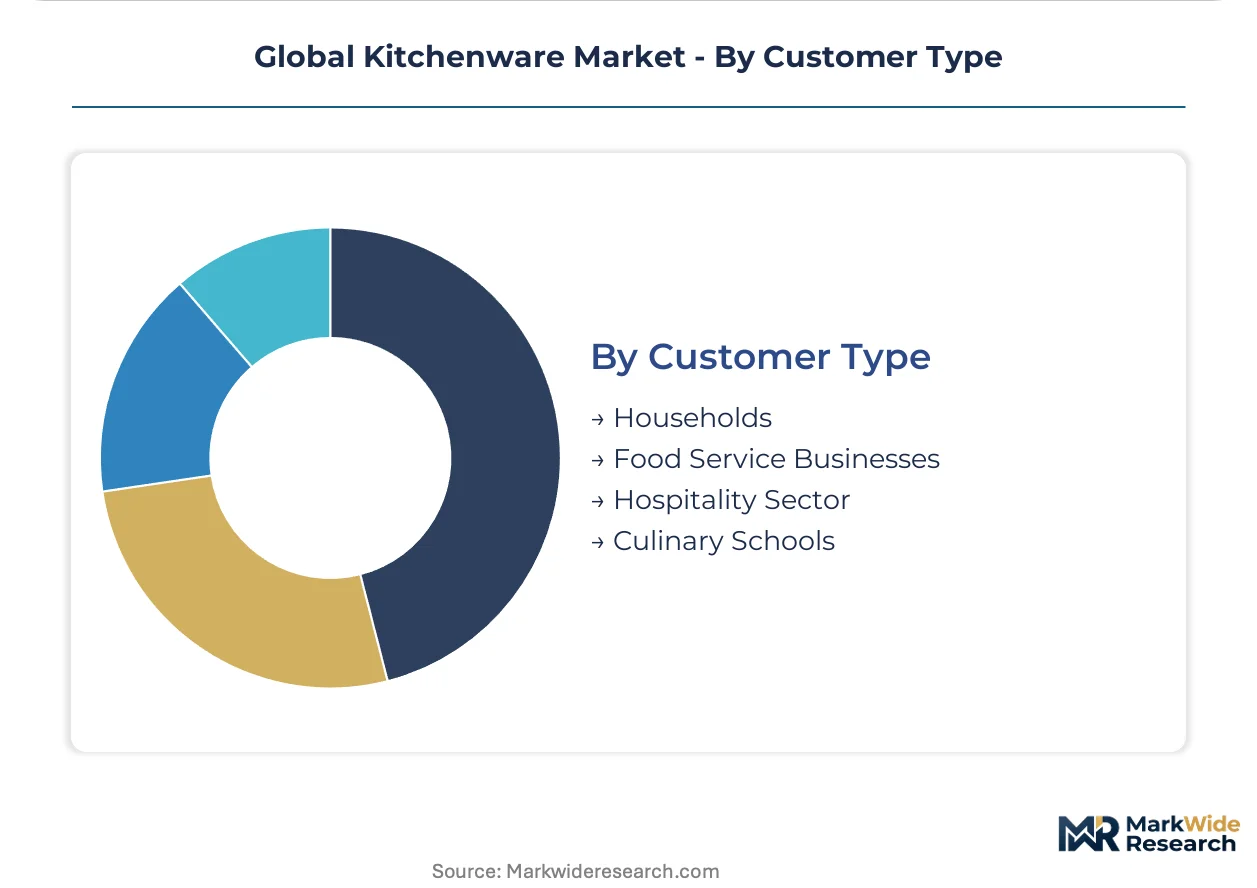
Customer Type:
Volume and margin concentration split between replacement-driven household demand and specification-intensive commercial procurement.
- Households:Individual consumers purchasing for home cooking, baking, and food storage. Tier-1 city households in India are upgrading from basic aluminum to tri-ply stainless steel and hard-anodized collections.
- Food Service Businesses:Restaurants, cafeterias, and catering operations requiring professional-grade durability and standardized equipment. North American and Western European chains are accelerating orders after pandemic-era deferred maintenance.
- Hospitality Sector:Hotels, resorts, and cruise lines sourcing tableware and service equipment at volume. Procurement emphasizes chip resistance and dishwasher durability over thermal performance.
- Culinary Schools:Training institutions equipping teaching kitchens with standardized student kits. Specifications prioritize affordability and uniformity over premium performance characteristics.
Households generate the largest absolute volumes; food service businesses are driving the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled ceramic glaze chemists in Shandong province and metallurgical engineers in Germany's Ruhr industrial belt anchor the industry's geographic talent distribution. Foundry specialists in France's Haute-Savoie region and stainless steel fabricators in India's Gujarat state complete the core workforce map.
China
Guangdong and Zhejiang provinces host vertically integrated cookware production from raw aluminum smelting through enamel finishing. SAMR enforces nickel migration limits in stainless steel exports under GB standards. Shandong province facilities supply over 70% of global ceramic glaze production, creating concentrated supplier networks for rapid private-label prototyping.
Germany
Specialty kitchenware chains in Berlin and Munich have expanded showroom footprints to capture comparison-shopping traffic from department store defectors. ECHA's REACH regulation restricts perfluorinated compounds in non-stick coatings, compelling reformulation toward ceramic alternatives. The Ruhr industrial belt retains metallurgical engineering expertise for tri-ply stainless steel fabrication.
United States
Restaurant chains in Texas and California are accelerating professional-grade stainless steel orders after pandemic-era deferred maintenance. FDA food-contact substance notifications govern import eligibility for coated aluminum goods. Meyer Corporation anchors North American distribution through department store partnerships and direct-to-consumer channels.
India
Tier-1 city households in Mumbai and Delhi are upgrading from basic aluminum to tri-ply stainless steel and hard-anodized collections. BIS certification requirements disadvantage direct exporters and favor local assembly partnerships. TTK Prestige Ltd. dominates the pressure-cooker segment while extending into premium stainless steel for urban households.
France
Enameled cast iron foundries in Haute-Savoie and Ardennes anchor premium production for global distribution. The EU Green Deal circularity mandates favor cast iron with documented lifecycle data for upcoming ecodesign requirements. Le Creuset Group exemplifies heritage positioning in this premium tier.
Global Kitchenware Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the kitchenware value chain. Foundry operators with captive enamel facilities and in-house coating labs command margin premiums over import-dependent distributors. Three archetypes dominate: integrated European heritage brands, North American multi-brand conglomerates, and Asian volume manufacturers with export flexibility. Competitive moves concentrate on portfolio diversification across price tiers and strategic partnerships to secure ceramic coating supply.
Within the heritage foundry tier, Le Creuset Group and Fissler exemplify European craftsmanship positioning anchored in specific regional manufacturing traditions. Groupe SEB represents the multi-brand architecture archetype, spanning premium enameled cast iron and mass-market aluminum across European and Asian markets through portfolio breadth rather than single-brand dominance.
| Leading Market Players |
|---|
| Tramontina |
| Fissler |
| Groupe SEB |
| Wilh. Werhahn KG. |
| Le Creuset Group |
| Meyer Corporation |
| TTK Prestige Ltd. |
| SCANPAN |
| Newell Brands |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in France's Haute-Savoie and Ardennes regions anchor premium enameled cast iron production, translating heritage manufacturing into pricing power that resists commodity erosion while constraining volume flexibility. Their supply discipline—captive foundry operations and multi-generational craft labor pools—creates natural price floors that integrated conglomerates match through brand architecture rather than cost parity.
Pricing Analysis
Bundled cookware-plus-coating warranties separate premium tri-ply stainless steel from unbundled aluminum commodity offerings. Three-tier pricing structure across premium, standard, and economy levels rests on certification grade differentiation—EU REACH-compliant ceramic coatings command durability premiums over legacy PTFE alternatives. Cost compression in mass-market aluminum is intensifying because Shandong glaze suppliers pass through nickel and chromium volatility within one quarter. Food service buyers exhibit least price sensitivity due to replacement cycle urgency, while urban millennials in meal-kit markets show highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from European retailers now mandate ceramic coating qualification at both Shandong and emerging Turkish facilities. Geographic supply concentration centers on China for aluminum smelting and enamel finishing, France for cast iron foundry work, and Germany for tri-ply fabrication. Raw material dependencies draw from nickel-chromium alloys, sol-gel ceramic precursors, and borosilicate glass. Single-source vulnerability in Shandong glaze production exposes brands to logistics disruption during peak export seasons. Distribution runs through specialty store networks in Germany and direct-to-consumer platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's PFAS restriction proposal triggers inventory destocking and accelerates ceramic coating demand across European channels.
For Market Incumbents: Deploy captive coating laboratory investments to secure sol-gel chemist talent pools against semiconductor sector competition. Accelerate India local assembly partnerships to circumvent BIS certification barriers that disadvantage direct exporters. The threat of meal-kit packaging substitution demands defensive positioning in induction-compatible retrofit accessories. For New Entrants and Emerging Players: Ceramic-reinforced sol-gel surface technology offers entry wedge into premium direct-to-consumer channels where legacy PTFE brands face regulatory obsolescence. Target India's tier-1 city households upgrading from basic aluminum through local assembly joint ventures. White-space exists in European rental housing induction retrofit services—adapter plate accessories and ferromagnetic base conversion represent underpenetrated ancillary revenue. For Investors and Strategic Acquirers: Multi-brand conglomerates with European heritage portfolios are the most active acquirer in this space, seeking coating-capable foundries to fill portfolio gaps. Long-term viability favors targets with documented lifecycle data for upcoming EU Green Deal ecodesign mandates. The signal to watch is ECHA restriction implementation timelines—accelerated enforcement would shift valuation premiums toward REACH-compliant ceramic coating assets.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Reformulation | ECHA REACH compliance secures European market access against PTFE obsolescence. |
| India Local Assembly Partnership | BIS certification requirements favor domestic assembly over direct import channels. |
| Induction-Compatible Retrofit Launch | European rental housing conversion creates replacement demand for legacy aluminum. |
| Direct-to-Consumer Channel Expansion | Specialty retailers capture comparison-shopping traffic from department store erosion. |
| EU Green Deal Circularity Positioning | Documented lifecycle data secures preferred retailer sustainability program placement. |
Research Approach
Coverage spans China, Germany, United States, India, and France, with primary inputs from each market's stakeholder base. The analysis combines interviews with foundry operations managers, ceramic coating R&D directors, specialty retail category buyers, and food service procurement leads with secondary validation from SAMR GB standard filings, ECHA restriction proposals, FDA food-contact substance notifications, and customs trade records. Bottom-up demand modeling and top-down supply capacity assessments triangulate volume estimates.
Granularity-level modeling disaggregates the analysis window by product type, material composition, sales channel, and customer archetype—cookware versus bakeware, stainless steel grade tier versus ceramic format, specialty store versus online retailer, household versus food service. CAGRs derive from segment-level growth rate synthesis anchored in replacement cycle timing and regulatory compliance deadlines. Forecast inputs include nickel price volatility assumptions and pandemic-era deferred maintenance catch-up patterns.
The model holds under stable regulatory implementation timelines; deviation in ECHA enforcement acceleration or SAMR nickel migration limit tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market