
 Opalware Dinnerware and Crockery Market | 2026-2036
Opalware Dinnerware and Crockery Market Size, Share, and Industry Trends Forecast 2026-2036
Opalware Dinnerware and Crockery Market Analytics
ISO 6486-1 certification for ceramic ware release of lead and cadmium is redrawing competitive boundaries across the opalware supply base. La Opala leverages integrated manufacturing in India to sustain cost-competitive production of thermal-shock-resistant dinnerware. Christofle differentiates through heritage craftsmanship and controlled distribution in European premium retail channels. Bernardauld anchors its position via technical partnerships with luxury hospitality groups requiring customized service configurations.
Opalware dinnerware and crockery denotes tempered glass-ceramic tableware engineered with high thermal shock resistance and low porosity, typically manufactured through sintering of silica, alumina, and flux materials at temperatures exceeding 1,200°C for commercial food service and residential dining applications. The material segment shows opal formulations commanding premium positioning against porcelain alternatives due to superior chip resistance and microwave compatibility. Serveware within product type classifications captures expanding margin pools as hospitality procurement shifts toward coordinated presentation sets. The end-user split reveals restaurants and catering services outpacing household channels in volume velocity, though residential replacement cycles sustain baseline manufacturing utilization.
India's BIS and the EU's REACH framework govern food-contact migration limits and chemical safety thresholds, respectively, compelling manufacturers to reformulate glazes and validate compliance through accredited laboratory testing. The FDA maintains parallel lead and cadmium leaching standards for ceramicware marketed in the United States, creating multi-jurisdiction certification burdens for exporters. Stakeholders must monitor evolving substance restrictions under the EU Green Deal's chemical sustainability agenda and calibrate R&D allocation toward cadmium-free pigment systems before regulatory phase-ins tighten supply eligibility.
Market Dynamics
ISO 6486-1 certification requirements for lead and cadmium migration limits are restructuring supplier eligibility across opalware manufacturing bases, forcing glaze reformulation investments and accredited laboratory validation protocols.
Growth Catalysts
- EU REACH substance restrictions:Chemical safety thresholds under the EU Green Deal are accelerating R&D allocation toward cadmium-free pigment systems before regulatory phase-ins tighten supply eligibility for European market access.
- Full-service restaurant procurement:Hotel chains and dining establishments across Southeast Asia are expanding procurement of thermal-shock-resistant opalware sets for daily service durability and reduced replacement frequency.
- Vietnam hospitality corridor:Resort construction acceleration from Ho Chi Minh City to Da Nang is compressing tableware procurement cycles and concentrating demand for coordinated presentation serveware.
Market Restraints
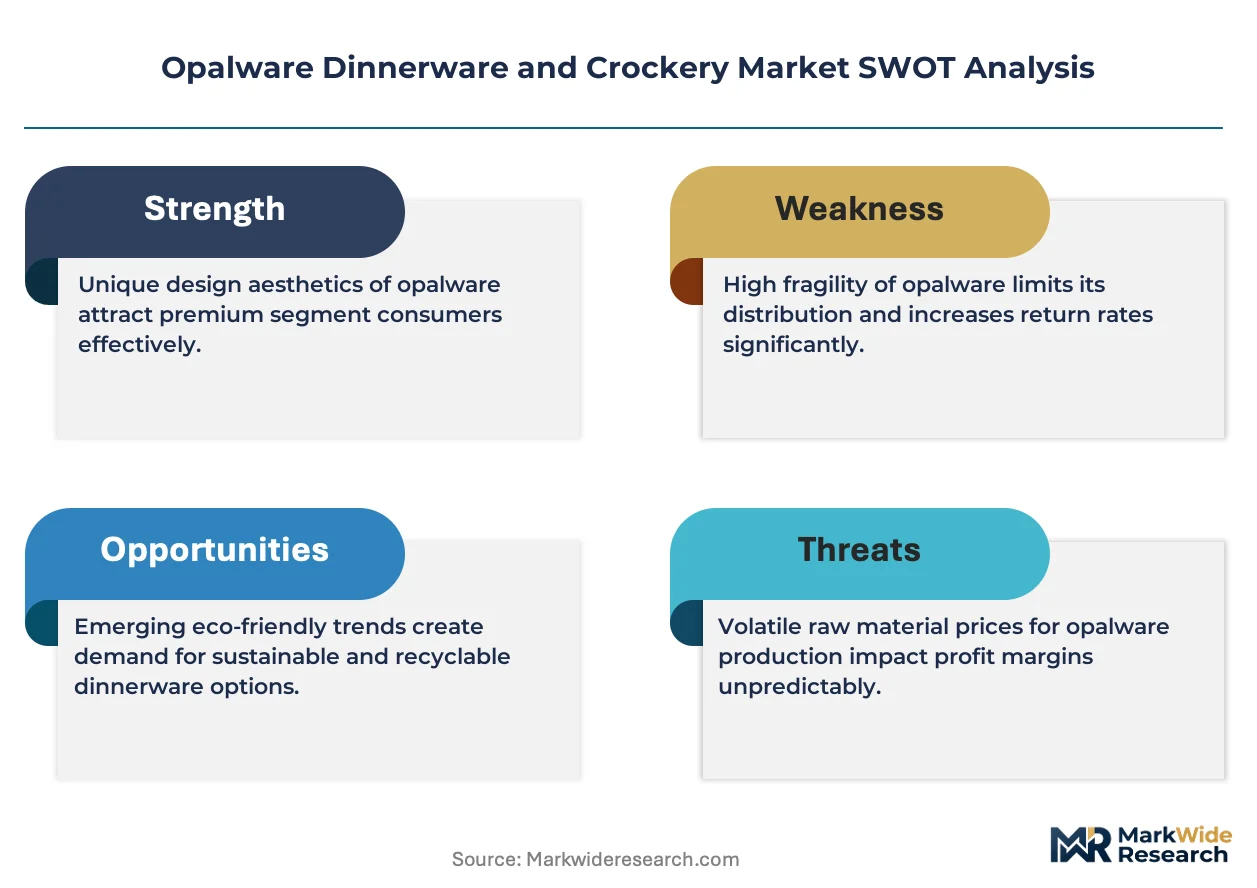
- Flux material cost volatility:Alumina and specialized silica input prices fluctuate with energy-intensive sintering requirements, squeezing margin pools for manufacturers operating below 1,200°C production scale.
- Indian supply concentration:Integrated manufacturing clusters around domestic BIS certification infrastructure create geographic dependency risks for buyers seeking alternative qualified suppliers.
- Porcelain substitution threat:Premium porcelain alternatives retain foothold in heritage hospitality segments where chip resistance carries lower procurement priority than aesthetic tradition.
Strategic Opportunities
- EU Green Deal chemical sustainability agenda:Early compliance with evolving substance restrictions creates first-mover positioning for exporters targeting European food-service procurement tenders.
- Coordinated presentation sets:Serveware margin expansion potential exists as hospitality buyers shift from piecemeal replacement toward unified aesthetic configurations across banquet and room-service operations.
- Residential microwave compatibility:Underpenetrated household channels in emerging Asian markets present volume velocity upside as consumer awareness of thermal-shock performance spreads beyond commercial buyers.
Industry Challenges
- Multi-jurisdiction certification burdens:Simultaneous FDA lead-leaching standards, BIS food-contact requirements, and EU REACH compliance create extended validation timelines for export-oriented manufacturers.
- Sintering process capex intensity:Temperature-exceeding 1,200°C furnace infrastructure demands substantial capital allocation, limiting entry for mid-scale producers seeking thermal-shock-resistant product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opalware Dinnerware and Crockery Market |
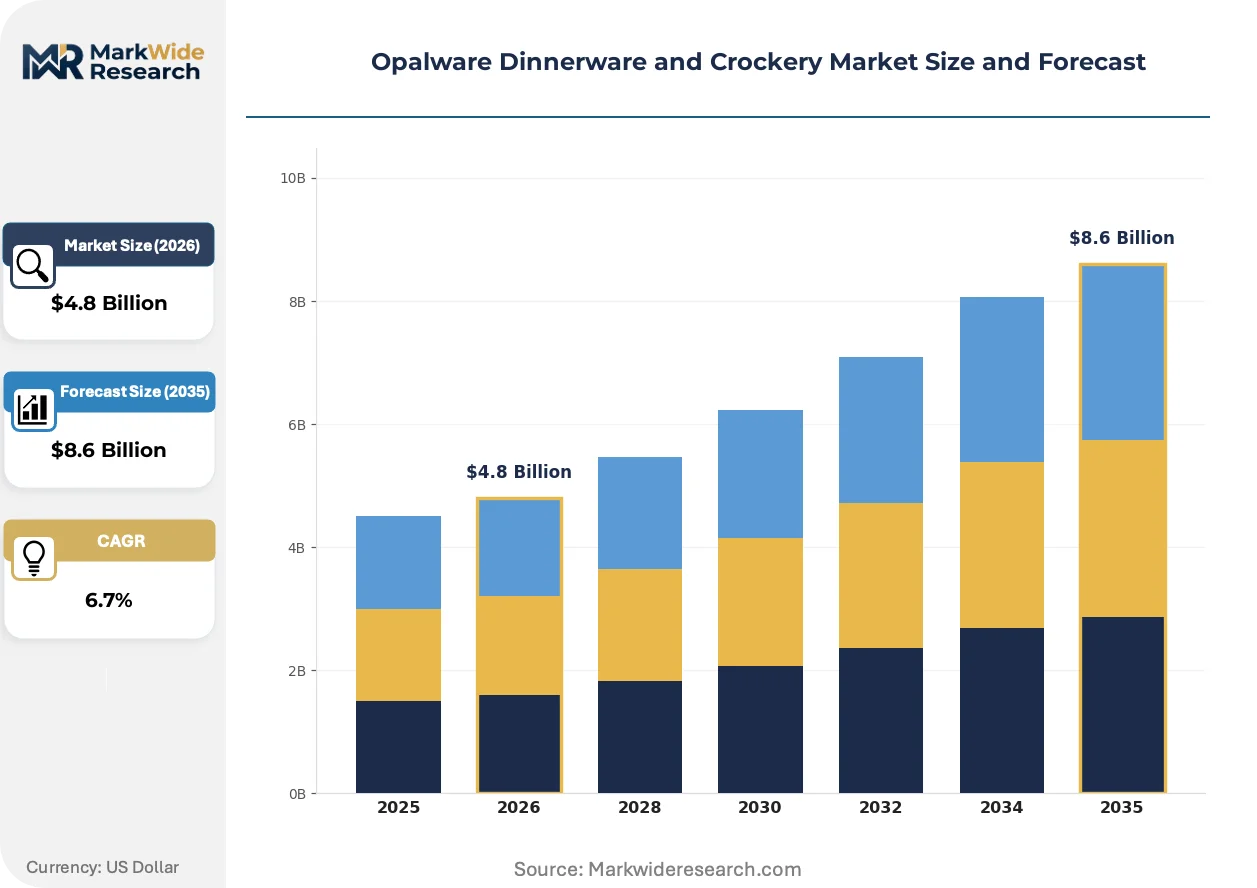
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cups, Serveware Material: Opal, Porcelain, Stoneware, Glass Design Style: Contemporary, Vintage, Minimalist, Floral End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Bernardauld, Meissen, La Opala, Christofle, Lalique, Diva, Herend, Robbe & Berking, Haviland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opalware Dinnerware and Crockery Market Evolving Landscape
Manufacturing technology and regulatory chemistry are converging to redefine competitive positioning in opalware, with certification-validated production methods displacing conventional glaze formulations and procurement patterns fragmenting across buyer segments.
Cadmium-free pigment systems are fragmenting established supplier hierarchies as manufacturers reformulate colorant chemistry to preempt EU Green Deal phase-ins. Full-service restaurants and hotel procurement teams are accelerating validation of these reformulated glazes to secure uninterrupted European market access. The structural consequence is compressing margin tolerance for late-adopting producers still dependent on legacy pigment supply chains.
REACH framework substance restrictions are compelling manufacturers to reallocate R&D expenditure toward accredited laboratory testing partnerships and documentation infrastructure. Industrial consequence includes elongated product development cycles as glaze validation extends beyond traditional quality assurance protocols. Hospitality procurement segments in Germany and France are responding by consolidating supplier relationships around pre-certified production sources.
Buyer preference is rotating toward coordinated serveware configurations that unify banquet presentation aesthetics across property portfolios. Traditional piecemeal replacement purchasing is yielding to contracted set-procurement agreements with specification-lock provisions. Vietnam's resort construction pipeline from Ho Chi Minh City to Da Nang exhibits the most visible compression of procurement decision timelines as developers seek single-source tableware fulfillment.
Opalware Dinnerware and Crockery Market Segmentation
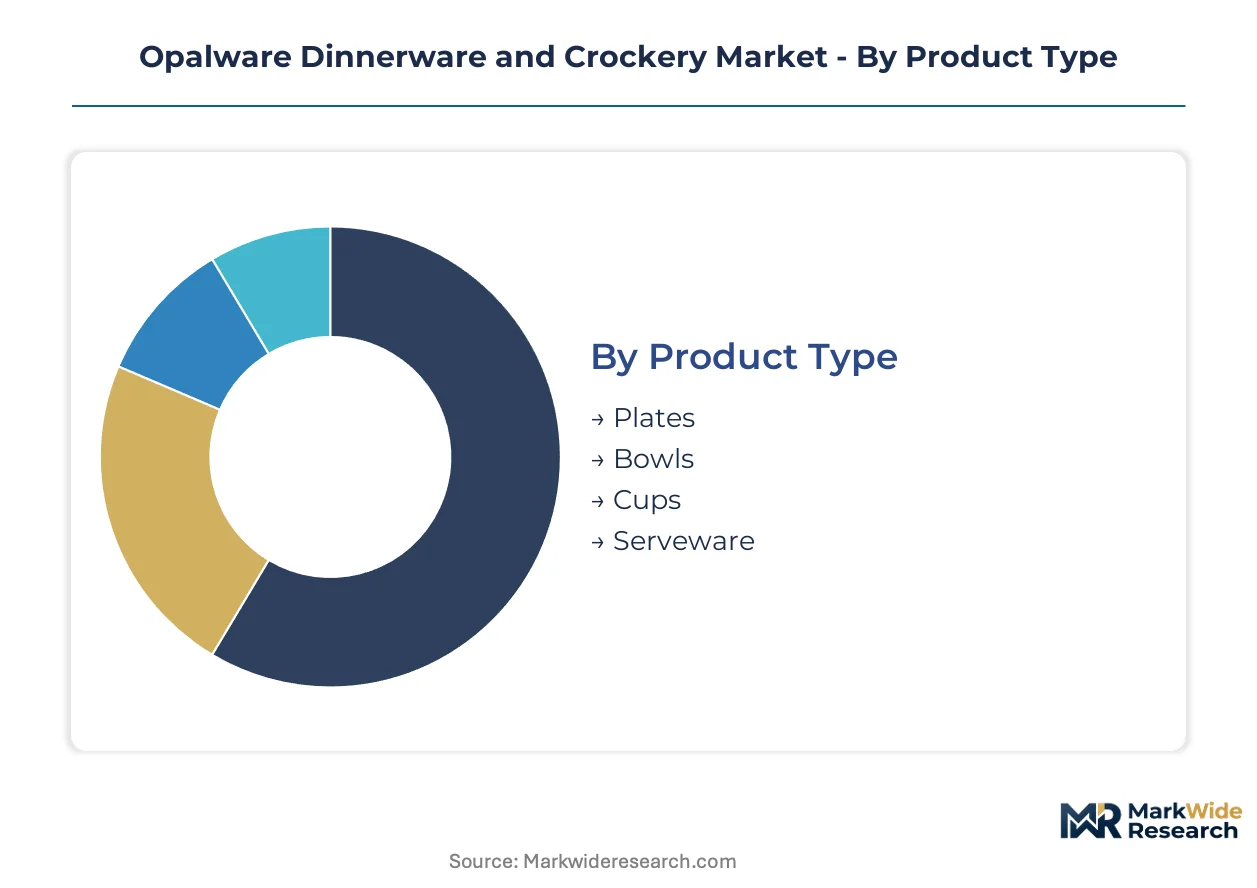
Opalware procurement patterns fragment sharply across buyer categories, with commercial food-service channels demanding thermal-shock certification while residential segments prioritize microwave compatibility and aesthetic coordination. Segmentation clarity enables manufacturers to calibrate glaze formulations, furnace investments, and distribution partnerships against divergent margin and volume profiles.
Product Type:
Plates and serveware dominate export-led procurement from Vietnam's hospitality corridor, while bowls and cups concentrate in domestic Indian household replacement cycles.
- Plates:Standard dinner and side plates constitute the foundational opalware specification, engineered with 1,200°C sintered silica-alumina matrices for thermal shock resistance. Vietnam's resort construction pipeline from Ho Chi Minh City to Da Nang compresses procurement timelines for coordinated banquet configurations. Demand concentrates in full-service restaurants seeking chip-resistant daily service durability.
- Serveware:Coordinated presentation sets capture expanding margin pools as hospitality buyers shift from piecemeal replacement toward unified aesthetic configurations. Hotel chains across Southeast Asia specify serveware for banquet and room-service operations. Procurement teams prioritize BIS-validated thermal performance for high-frequency commercial use.
- Bowls:Soup and cereal bowls target residential microwave compatibility in emerging Asian markets.
- Cups:Teacups and mugs sustain baseline manufacturing utilization through household replacement cycles.
Plates hold the largest share; momentum sits with serveware.
Material:
Cost tier differentiation separates premium opal formulations from commodity alternatives, with sintering scale determining thermal-shock qualification and pricing power.
- Opal:Tempered glass-ceramic engineered through high-temperature sintering delivers superior chip resistance and microwave compatibility against porcelain alternatives. La Opala's integrated Indian manufacturing sustains cost-competitive production of thermal-shock-resistant dinnerware. Full-service restaurants specify opal for reduced replacement frequency in daily service environments.
- Porcelain:Heritage hospitality segments retain porcelain procurement where aesthetic tradition outweighs chip resistance priorities. European premium retail channels maintain porcelain distribution for craftsmanship positioning. Bernardaud anchors technical partnerships with luxury hospitality groups requiring customized service configurations.
- Stoneware:Mid-tier positioning targets residential buyers seeking durability without opal's thermal-shock premium.
- Glass:Transparent and tempered variants serve beverage-focused applications with lower sintering capex requirements.
Opal commands premium positioning; porcelain defends heritage footholds.
Design Style:
Volume concentration clusters in minimalist and contemporary specifications for commercial procurement, while floral and vintage styles serve fragmented residential preferences.
- Contemporary:Clean-lined geometries dominate Southeast Asian hospitality procurement for property portfolio standardization. Vietnam's resort developers specify contemporary designs for unified banquet presentation across Ho Chi Minh City to Da Nang properties. Christofle differentiates through controlled distribution in European premium retail channels.
- Minimalist:Reduced ornamentation aligns with modern kitchen aesthetics and simplified replacement sourcing.
- Vintage:Heritage patterns serve niche hospitality segments and collector-oriented residential channels.
- Floral:Decorative motifs target household replacement cycles in traditional aesthetic markets.
Contemporary holds the largest share; minimalist gains share fastest.
End User:
Customer type determines certification burden intensity, with restaurants and catering services requiring multi-jurisdiction validation against lighter household compliance thresholds.
- Restaurants:Full-service dining establishments drive volume velocity through thermal-shock-resistant opalware procurement for daily service durability. ISO 6486-1 certification requirements restructure supplier eligibility across manufacturing bases. India's BIS food-contact ceramics standards tighten quality thresholds for domestic production and import.
- Catering Services:Event and institutional food service demands coordinated presentation sets with specification-lock provisions. Procurement shifts from piecemeal replacement toward contracted agreements with validated glaze documentation. EU REACH framework substance restrictions compel R&D reallocation toward cadmium-free pigment systems.
- Households:Residential channels sustain baseline manufacturing utilization through replacement cycles.
- Cafes:Coffee-focused operations prioritize cup and saucer configurations with moderate thermal performance requirements.
Restaurants hold the largest share; catering services climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement incentives and hospitality infrastructure programs are redistributing manufacturing investment across key production bases. National regulators impose divergent food-contact certification burdens that reshape export eligibility and domestic supply positioning.
India
BIS certification requirements for food-contact ceramics are tightening quality thresholds for import and domestic production. The Bureau of Indian Standards mandates accredited laboratory testing for lead and cadmium migration limits. Manufacturing clusters around Gujarat and Tamil Nadu concentrate integrated opalware production serving both household replacement cycles and hospitality export demand.
Vietnam
Resort construction acceleration from Ho Chi Minh City to Da Nang compresses tableware procurement cycles for coordinated serveware configurations. The Ministry of Industry and Trade oversees technical standards for ceramic imports used in commercial food service. The central coast hospitality corridor concentrates demand for thermal-shock-resistant dinnerware specifications.
Germany
EU REACH framework substance restrictions accelerate R&D allocation toward cadmium-free pigment systems before regulatory phase-ins tighten supply eligibility. The Federal Institute for Risk Assessment validates food-contact migration limits for ceramicware distribution. Industrial procurement in Bavaria and North Rhine-Westphalia consolidates supplier relationships around pre-certified production sources.
United States
FDA lead and cadmium leaching standards for ceramicware create multi-jurisdiction certification burdens for exporters targeting food-service procurement. The Food and Drug Administration maintains parallel compliance requirements alongside international ISO 6486-1 protocols. Hospitality procurement in Florida and California prioritizes thermal-shock-resistant specifications for high-frequency commercial use.
France
Heritage hospitality segments retain procurement footholds where aesthetic tradition outweighs chip resistance priorities in premium positioning. The National Agency for Food, Environmental and Occupational Health Safety enforces EU-aligned substance restrictions on food-contact ceramics. Luxury hospitality groups in Paris and Provence-Alpes-Côte d'Azur specify customized service configurations through technical partnerships.
Opalware Dinnerware and Crockery Market Competitive Landscape
Player mix skews toward integrated manufacturers with captive sintering capacity and heritage craft specialists serving premium retail channels. Market structure exhibits tiered consolidation around scale-driven producers and design-focused niche operators. Three archetypes dominate: vertically integrated thermal-shock specialists, heritage craftsmanship houses, and regional cost-competitive fabricators. Competitive moves center on glaze reformulation investments for multi-jurisdiction certification and contracted set-procurement agreements with specification-lock provisions.
Within the heritage craftsmanship tier, Bernardauld and Christofle exemplify positioning anchored in controlled distribution and technical partnerships with luxury hospitality groups. La Opala represents the integrated manufacturing archetype with cost-competitive production sustained through domestic sintering infrastructure. Meissen occupies a position bridging heritage positioning with commercial scalability for coordinated presentation configurations.
| Leading Market Players |
|---|
| Bernardauld |
| Meissen |
| La Opala |
| Christofle |
| Lalique |
| Diva |
| Herend |
| Robbe & Berking |
| Haviland |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day furnace commissioning lead times for 1,200°C sintering infrastructure concentrate pricing power with Indian and Vietnamese integrated manufacturers, while alumina flux cost volatility compresses margin tolerance for mid-scale producers lacking backward integration into raw material sourcing.
Pricing Analysis
Certification level creates the primary spread across opalware tiers, with ISO 6486-1-validated production commanding premium positioning against BIS-only domestic grade. Three-tier pricing structure separates export-grade thermal-shock-certified specifications from standard commercial hospitality grade and unvalidated economy residential tier. Pricing pressure stems from energy-intensive sintering requirements and specialized silica input cost swings. Full-service restaurant procurement teams exhibit lowest price sensitivity due to replacement frequency calculations, while emerging Asian household channels remain most responsive to unit cost.
Supply Chain Analysis
India and Vietnam anchor opalware manufacturing through integrated sintering clusters serving hospitality export corridors and domestic replacement cycles respectively. Production draws from alumina, specialized silica flux, and cadmium-free pigment systems as critical inputs. Single-source vulnerability concentrates in BIS-accredited laboratory testing capacity for food-contact migration validation. Distribution runs through hospitality procurement consortia in Southeast Asia and premium retail channel partners in European heritage markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Opalware dinnerware sits in early-cycle expansion as Vietnam's resort construction pipeline from Ho Chi Minh City to Da Nang accelerates coordinated serveware procurement beyond traditional replacement velocity.
For Market Incumbents: Shield margin pools through captive sintering capacity expansion in Gujarat and Tamil Nadu manufacturing clusters before REACH phase-ins tighten European supply eligibility. Cement specification-lock provisions with hospitality procurement teams seeking uninterrupted thermal-shock certification across property portfolios. Prioritize glaze reformulation R&D toward cadmium-free pigment systems ahead of regulatory deadlines. For New Entrants and Emerging Players: Residential microwave compatibility in underpenetrated emerging Asian households offers service-layer white space where incumbents under-serve with hospitality-focused distribution. Vietnam's central coast hospitality corridor presents fastest-penetrable geography as resort developers compress procurement timelines. Pursue private-label partnerships with regional retailers seeking thermal-shock positioning without heritage brand premiums. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because multi-jurisdiction certification burdens create durable moats around validated production sources. Target acquisition archetypes: integrated manufacturers with captive 1,200°C furnace infrastructure and pre-established BIS-FDA-REACH laboratory partnerships. Monitor cadmium-free pigment adoption rates across European hospitality procurement tenders as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Flux Supply | Gujarat manufacturing clusters secure input cost stability against energy price volatility. |
| Cadmium-Free Pigment System Transition | REACH compliance ahead of phase-ins locks European hospitality procurement eligibility. |
| Coordinated Serveware Set Configuration | Vietnam resort developers specify unified banquet aesthetics across Ho Chi Minh City to Da Nang properties. |
| Multi-Jurisdiction Certification Investment | Simultaneous BIS, FDA, and ISO 6486-1 validation extends addressable market across India, United States, and European Union. |
| Residential Channel Distribution Partnership | Emerging Asian household microwave compatibility awareness spreads beyond commercial buyer concentration. |
Research Methodology
The analysis maps opalware product types, material grades, and end-user procurement patterns, each validated through hospitality procurement directors, ceramic manufacturing plant managers, and regulatory compliance officers across primary interviews combined with secondary validation from BIS certification databases, EU REACH substance restriction filings, and customs trade records. Bottom-up volume triangulation against top-down market sizing ensures cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material formulation, design style, and end-user channel alongside thermal-shock certification tier. CAGRs derived from fitted growth curves incorporate sintering capacity expansion timelines, hospitality construction pipeline data, and regulatory phase-in schedules as industry-specific inputs.
Underlying assumptions cover sustained resort construction velocity in Vietnam's central corridor and stable alumina flux supply availability, with deviation risk concentrated in REACH substance restriction acceleration or BIS certification backlog accumulation. Recalibration cycles align with material shifts in regulatory enforcement intensity and hospitality capital expenditure announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Outdoor Kitchen Market