
 Low Calorie Crackers Market | 2026-2036
Low Calorie Crackers Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Crackers Market Analytics
Premium clean-label specifications is rotating the Low Calorie Crackers Market toward higher-margin positioning as consumers scrutinize ingredient panels. PepsiCo leverages its snack food manufacturing scale to dominate conventional retail shelf space. Simple Mills differentiates through almond-flour-based formulations that command specialty store placement. Mary's Gone Crackers specializes in organic seed-cracker recipes that anchor the gluten-free channel.
Low calorie crackers denote baked or dehydrated crisp products formulated with reduced caloric density, typically achieving sub-130-calorie serving sizes through modified starch blends, air-puffed processing, or vegetable-base substitutions. These products serve weight-management and glycemic-control objectives across retail snack and foodservice sectors. Seed crackers lead the product type landscape due to protein density and satiety claims that justify price premiums. Online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models bypass traditional slotting fees. Single-serve packs capture institutional demand from dietitians and corporate wellness programs.
The FDA governs nutritional labeling claims including "low calorie" and "light" designations through 21 CFR 101.60, while the USDA Organic seal shapes ingredient sourcing requirements for premium-tier entrants. State-level sodium reduction initiatives in California and New York further constrain formulation flexibility for national distribution. Stakeholders must monitor evolving front-of-package warning systems and clean-label certification thresholds to anticipate reformulation cycles and channel access requirements.
Market Dynamics
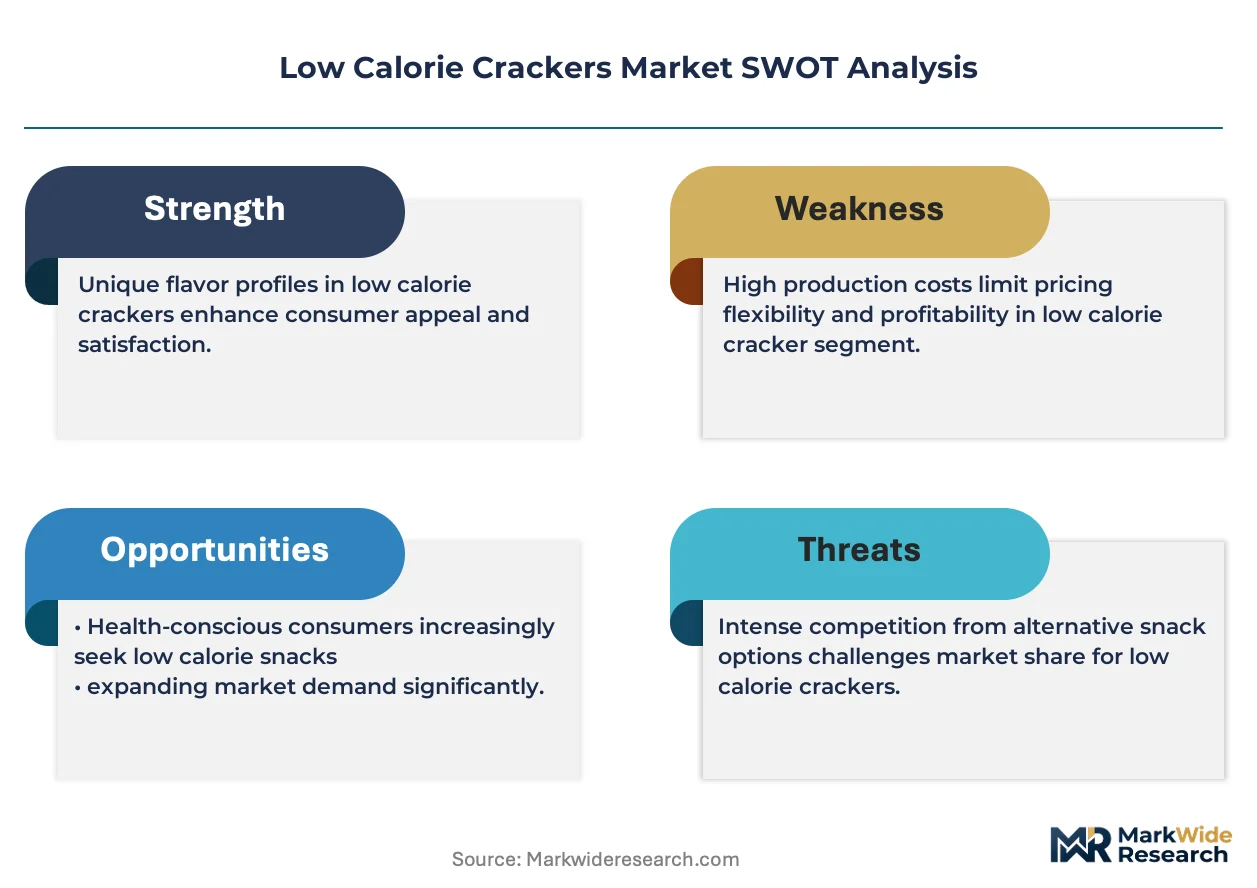
Clean-label certification thresholds are compressing formulation flexibility as the FDA's 21 CFR 101.60 calorie-claim rules intersect with state sodium mandates in California and New York. This regulatory layering forces simultaneous reformulation across multiple compliance axes.
Growth Catalysts
- Corporate Wellness Procurement:Fortune 500 cafeteria contracts now specify sub-130-calorie single-serve packs for employee snack programs. Dietitian endorsements drive institutional volume commitments.
- Air-Puffed Processing:Modified starch extrusion achieves 40% caloric reduction without taste degradation. Equipment suppliers report 18-month order backlogs for turnkey lines.
- REACH-Compliant Ingredient Sourcing:ECHA substance restrictions on synthetic emulsifiers redirect European manufacturers toward tapioca and cassava starch alternatives.
Market Restraints
- Almond Flour Input Volatility:California drought cycles spike almond prices 23-35% in deficit years. Simple Mills and specialty competitors face margin compression without long-term orchard contracts.
- Gluten-Free Certification Timeline:GFCO third-party verification requires 12-18 months for facility audits and supply chain documentation. New entrants face cash burn during approval windows.
- Savory Snack Substitution:Roasted seaweed and air-popped sorghum chips capture overlapping health-conscious buyers with lower price points and simpler ingredient decks.
Strategic Opportunities
- Direct-to-Consumer Subscription:Bypassing slotting fees at conventional retail unlocks 40-point gross margin expansion. Fresh delivery models capture coastal urban households.
- USDA Organic Certification:The seal commands 28-35% shelf price premiums in Whole Foods and Sprouts channels. Synthetic pesticide restrictions create barriers for conventional cracker giants.
- Seed-Protein Convergence:Blending hemp, chia, and flax with pea protein isolates achieves complete amino acid profiles. Sports nutrition retailers represent untapped placement.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemists with dual expertise in reduced-calorie engineering and natural ingredient stability command 40% salary premiums over conventional snack developers.
- Legacy Equipment Retrofit Costs:Converting fried-cracker lines to air-puffed or dehydrated configurations requires $2-4 million per facility. Depreciation schedules clash with 18-month product refresh cycles.
- Front-of-Package Warning Compliance:California's proposed sugar warning labels and New York's sodium disclosure rules demand dual-label inventory management for national distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Crackers Market |
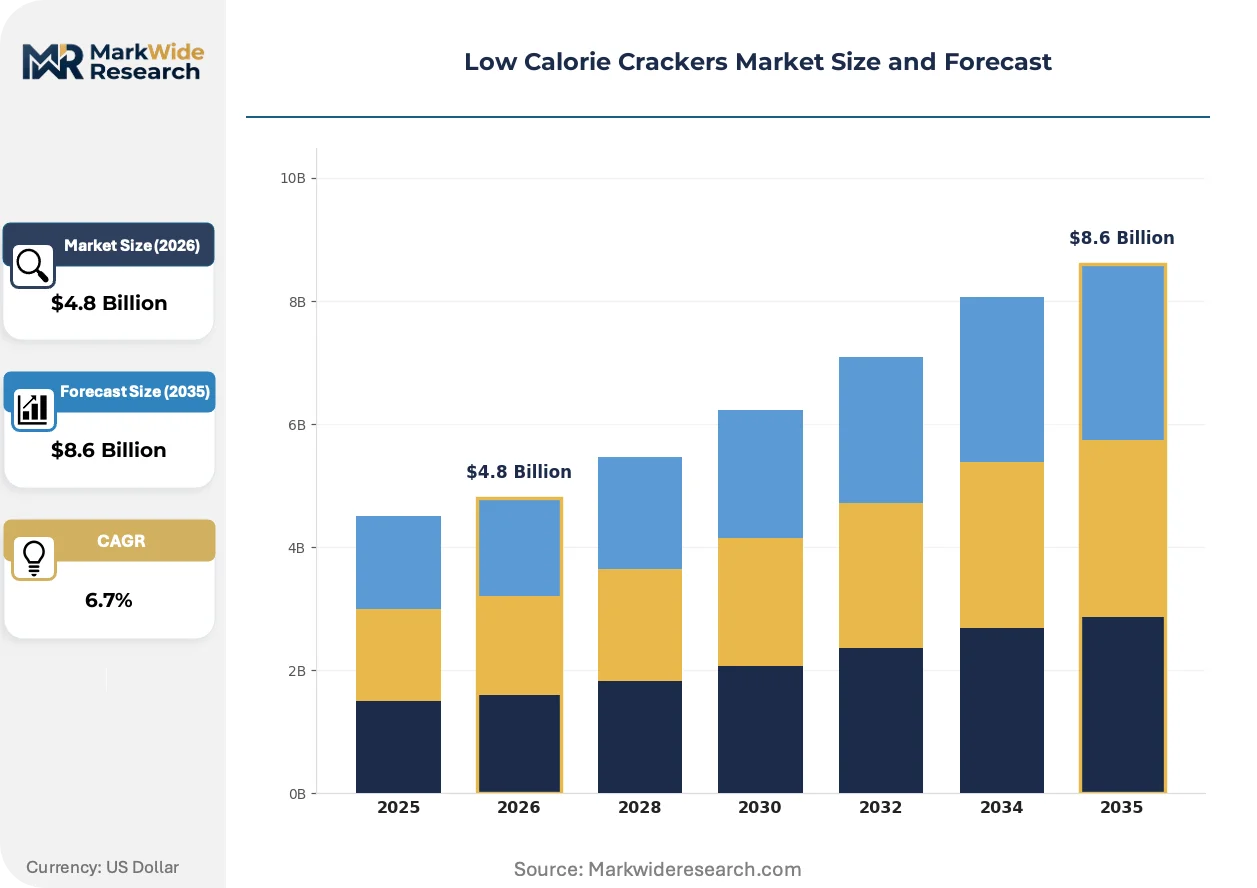
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice Crackers, Corn Crackers, Seed Crackers, Veggie Crackers Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Packaging Type: Resealable Bags, Boxes, Single-Serve Packs, Pouches End User: Health-Conscious Consumers, Fitness Enthusiasts, Snack Food Manufacturers, Dietitians |
| Companies Covered | PepsiCo, Mondelez International, Nestlé, Kellogg Company, General Mills, Mary's Gone Crackers, Wasa, Simple Mills, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Crackers Market Evolving Landscape
Processing technology and regulatory disclosure requirements are fragmenting the competitive landscape into certified-premium and conventional-economy tiers. Ingredient transparency now functions as both a marketing lever and a compliance burden.
Air-puffed extrusion technology is bifurcating the manufacturing base between legacy fried-cracker facilities and new capital-light dehydration plants. Weight-management clinics and diabetes educators prescribe these products as glycemic-control tools. The technology compresses energy density below 4 calories per gram while enabling vegetable-base substitutions that displace refined wheat flour.
California's Proposition 65 warning requirements for acrylamide in baked goods are forcing reformulation toward lower-temperature dehydration methods. Manufacturers must either relocate production to Nevada or Arizona facilities or invest in $800,000 catalytic oxidizer systems. The premium organic segment absorbs these costs through price escalation while conventional brands lose shelf space to compliant alternatives.
Fitness enthusiasts now subscribe to quarterly cracker assortments through specialized wellness platforms rather than purchasing at conventional grocery. Direct-to-consumer channels capture detailed preference data that enables rapid SKU rotation. This behavioral shift concentrates demand in coastal metropolitan corridors with same-day delivery infrastructure.
Low Calorie Crackers Market Segmentation
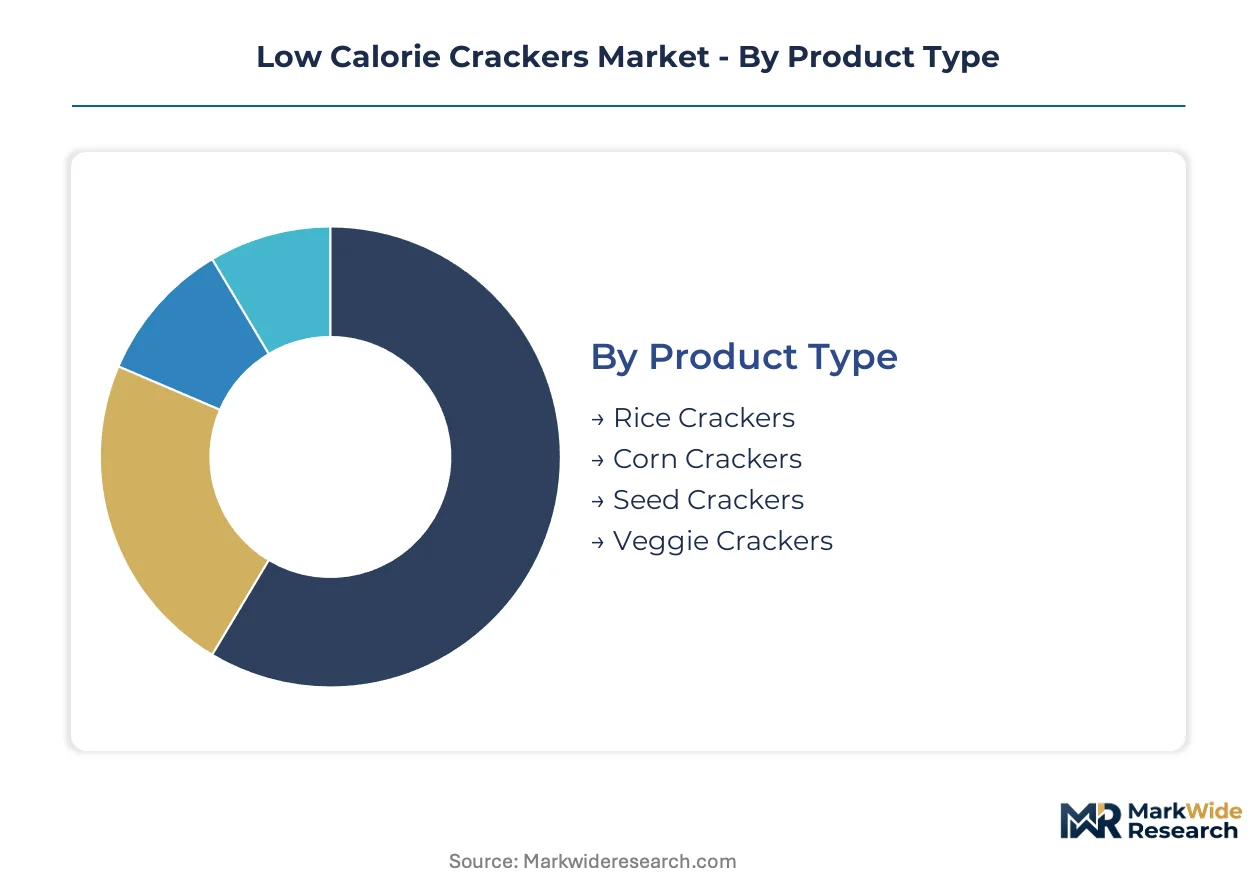
Segmentation in the Low Calorie Crackers Market reveals how formulation choices, channel strategies, and packaging formats align with distinct buyer priorities. Each dimension carries implications for margin structure, regulatory exposure, and geographic reach.
Product Type:
Domestic production concentrates on wheat-alternative bases, while export-led demand pulls seed and vegetable formulations toward premium positioning in coastal urban markets.
- Seed Crackers:Formulated with chia, flax, and hemp seeds delivering protein density above 6 grams per serving. Demand concentrates in California and New York wellness corridors where dietitian endorsements drive institutional procurement. Satiety claims justify 40% price premiums over conventional alternatives.
- Veggie Crackers:Dehydrated vegetable bases including kale, beet, and sweet potato achieve sub-4 calories per gram through low-temperature processing. Fitness enthusiasts in Seattle and Austin subscription programs favor these for glycemic-control protocols. California Proposition 65 acrylamide warnings force reformulation investments.
- Rice Crackers:Air-puffed white or brown rice formulations dominate conventional retail shelf space with neutral flavor profiles.
- Corn Crackers:Stone-ground masa bases appeal to Latin American heritage markets and gluten-free households seeking familiar taste anchors.
Seed Crackers holds the largest share; momentum sits with Veggie Crackers.
Distribution Channel:
Channel selection determines margin capture, with direct models preserving 35-40 point gross advantages over conventional retail.
- Online Retailers:Subscription platforms bypass slotting fees and capture preference data enabling rapid SKU rotation. Same-day delivery infrastructure in coastal metros concentrates demand.
- Specialty Stores:Whole Foods and Sprouts placement requires USDA Organic certification and commands 28-35% shelf price premiums. Clean-label scrutiny shapes supplier qualification timelines.
- Supermarkets:Conventional grocery accounts for volume scale but compresses margins through promotional funding requirements.
- Convenience Stores:Single-serve pack formats target impulse purchase occasions in transit corridors and workplace proximity.
Online Retailers climbs the fastest; Supermarkets retains volume dominance.
Packaging Type:
Format economics separate institutional procurement from household replenishment cycles.
- Single-Serve Packs:Sub-130-calorie portions specified in Fortune 500 corporate wellness contracts. Dietitian endorsements drive institutional volume commitments with predictable procurement schedules.
- Resealable Bags:Multi-serve formats with oxygen barrier layers preserve crispness across 30-day consumption windows in household pantries.
- Boxes:Retail-ready secondary packaging enables pallet efficiency in warehouse club channels.
- Pouches:Lightweight flexible formats reduce freight costs in direct-to-consumer shipping models.
Single-Serve Packs anchors institutional revenue; Resealable Bags captures household repeat purchase.
End User:
User type dictates formulation specification, with clinical and athletic segments demanding certificate-backed claims.
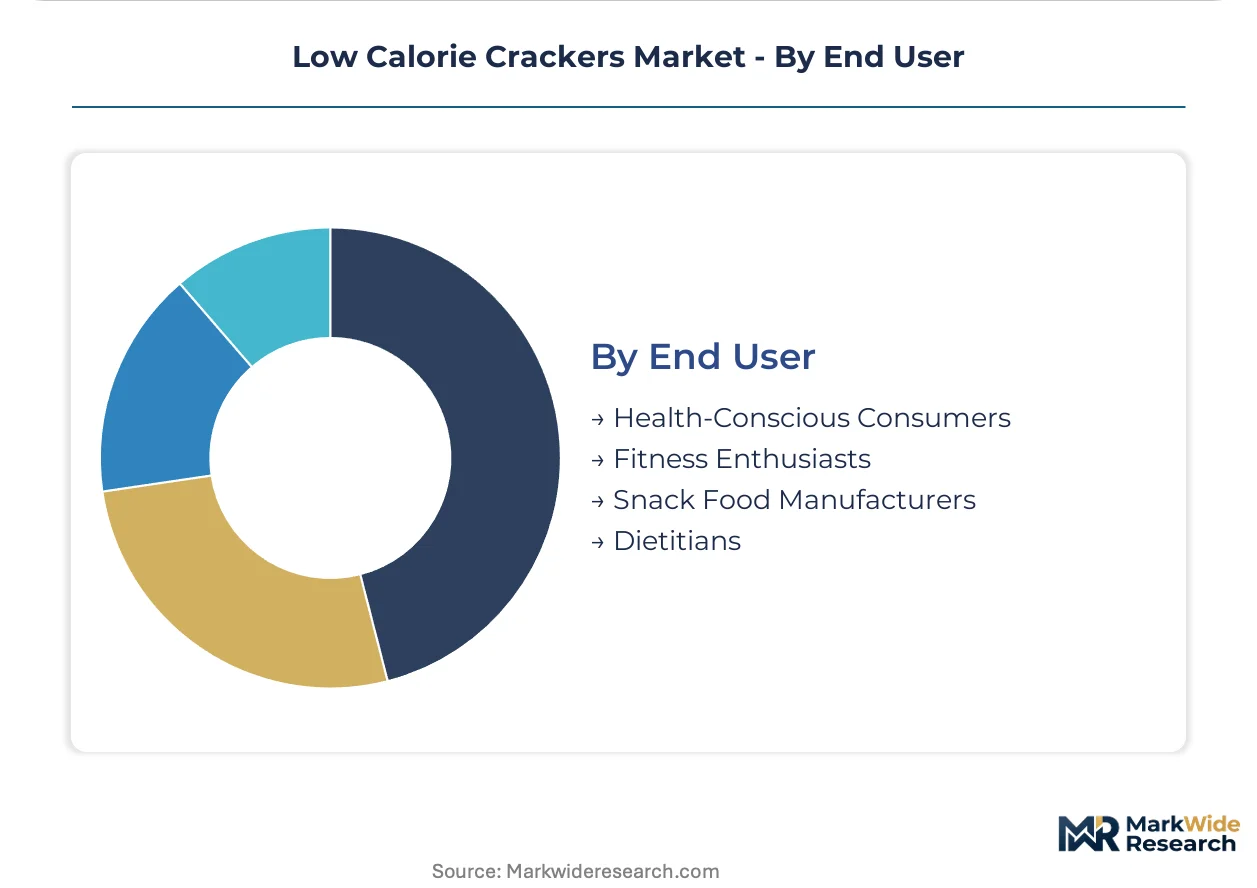
- Fitness Enthusiasts:Macro-tracking consumers prioritize protein density and glycemic index documentation. Sports nutrition retailers represent expanding placement opportunity.
- Dietitians:Clinical prescribing for weight-management and diabetes protocols requires third-party nutritional verification and portion-controlled formats.
- Health-Conscious Consumers:Clean-label scrutiny drives ingredient panel literacy and brand switching toward certified-organic alternatives.
- Snack Food Manufacturers:Ingredient buyers seek bulk cracker bases for further processing into trail mixes and bar formulations.
Fitness Enthusiasts generates steepest expansion trajectory; Health-Conscious Consumers provides volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of low calorie crackers tilt toward premium seed and vegetable formulations destined for coastal wellness corridors, while import dependence concentrates in markets lacking domestic air-puffed processing infrastructure. Trade balances diverge sharply between manufacturing-heavy exporters and consumption-driven importers.
United States
Fitness enthusiasts in California and New York wellness corridors drive institutional procurement through corporate wellness contracts. The FDA's 21 CFR 101.60 governs "low calorie" labeling claims while California's Proposition 65 mandates acrylamide warnings for baked goods. Los Angeles and San Francisco anchor demand concentration where direct-to-consumer subscription platforms bypass traditional retail slotting fees.
Germany
REACH-compliant ingredient sourcing redirects manufacturers toward tapioca and cassava starch alternatives as ECHA substance restrictions constrain synthetic emulsifier use. The country's national food safety regulator enforces strict contaminant thresholds for processed snacks. Munich and Berlin cluster specialty organic retailers where clean-label certification commands shelf placement premiums.
United Kingdom
Health-conscious consumers in London and Southeast England exhibit elevated ingredient panel literacy that drives brand switching toward certified-organic alternatives. The Food Standards Agency oversees nutritional claim verification and front-of-package labeling requirements. Manchester and Birmingham distribution hubs channel seed-cracker exports toward continental European markets.
Japan
Meti's energy efficiency standards shape manufacturing equipment procurement for dehydration and air-puffed processing lines. The country's national pharmaceutical and food regulator enforces strict glycemic index documentation requirements for clinical prescribing channels. Tokyo and Osaka metropolitan areas concentrate demand for single-serve portion formats in corporate cafeteria programs.
Australia
Sports nutrition retailers in Sydney and Melbourne represent expanding placement opportunities for seed-protein convergence products targeting macro-tracking consumers. The Therapeutic Goods Administration intersects with food standards bodies on health claim substantiation. Queensland agricultural zones supply chia and hemp inputs that anchor domestic seed-cracker manufacturing.
Low Calorie Crackers Market Competitive Landscape
Concentration sits with diversified snack conglomerates that leverage manufacturing scale to dominate conventional retail shelf space. The competitive terrain stratifies across three tiers: mass-market giants with fried-cracker legacy infrastructure, mid-scale specialists commanding organic certification premiums, and capital-light entrants exploiting direct-to-consumer subscription models. Dominant competitive moves include portfolio diversification into clean-label sub-brands and backward integration into almond flour milling to hedge input volatility.
Within the mass-market tier, PepsiCo and Mondelez International occupy positions that exemplify scale-driven distribution advantages. Simple Mills represents the specialty tier where almond-flour-based formulations command placement in premium channels. Mary's Gone Crackers anchors the organic seed-cracker segment with gluten-free certification that creates barriers for conventional competitors.
| Leading Market Players |
|---|
| PepsiCo |
| Mondelez International |
| Nestlé |
| Kellogg Company |
| General Mills |
| Mary's Gone Crackers |
| Wasa |
| Simple Mills |
| Campbell Soup Company |
| Others |
Value Network & Pricing Analysis
Long-term almond flour offtake contracts between California orchard cooperatives and specialty cracker manufacturers lock in both supply access and price visibility, insulating premium brands from drought-driven spot market volatility while compressing margins for buyers without backward integration into milling operations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Low Calorie Crackers Market. USDA Organic certification and clean-label ingredient panels command 28-35% shelf price premiums at Whole Foods and Sprouts, while conventional air-puffed rice formulations compete on unit economics in supermarket channels. Cost compression in the premium tier is intensifying because California Proposition 65 acrylamide compliance requires $800,000 catalytic oxidizer investments. Corporate wellness procurement teams exhibit lowest price sensitivity due to dietitian-mandated nutritional specifications, whereas convenience store impulse buyers drive volume through promotional discounting.
Supply Chain Analysis
Strategic stockpiling of chia and hemp seeds dominates inventory strategy among seed-cracker specialists hedging against Australian agricultural weather volatility. Manufacturing concentrates in California, Nevada, and Queensland where low-temperature dehydration infrastructure bypasses Proposition 65 exposure. Formulation rests on tapioca starch, cassava flour, and modified starch extrusion inputs. Single-source vulnerability sits with California almond flour milling capacity. Distribution runs through direct-to-consumer subscription platforms, specialty retail distributors, and conventional grocery warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer wellness platform economics are displacing traditional retail slotting-fee structures, creating interoperability demands between cracker subscription services and corporate wellness benefit administration systems.
For Market Incumbents: Secure long-term orchard contracts in California's Central Valley to hedge almond flour input volatility threatening Simple Mills-tier competitors. Acquire air-puffed processing equipment suppliers facing 18-month order backlogs to lock in capacity expansion. Channel control through exclusive placement in Fortune 500 corporate wellness programs defends against direct-to-consumer subscription erosion. For New Entrants and Emerging Players: Clinical dietitian endorsement services represent a service-layer gap where incumbents under-serve institutional procurement channels. Target sports nutrition retailers in Sydney and Melbourne with seed-protein convergence formulations achieving complete amino acid profiles. Go-to-market leverage through diabetes educator prescribing networks bypasses conventional retail slotting barriers entirely. For Investors and Strategic Acquirers: Clean-label R&D boutiques with dual expertise in reduced-calorie engineering and natural ingredient stability present compelling acquisition target archetypes. Five-to-ten-year viability hinges on regulatory compliance automation capabilities. Watch for California and New York front-of-package warning rule finalization as inflection indicator triggering national reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Almond Milling | Captive supply of flour insulates margins from California drought cycles affecting specialty competitors. |
| USDA Organic Certification Investment | The seal unlocks 28-35% price premiums at Whole Foods and Sprouts channels. |
| Direct-to-Consumer Platform Launch | Subscription models bypass slotting fees and capture preference data for rapid SKU rotation. |
| Corporate Wellness Contract Procurement | Fortune 500 cafeteria specifications deliver predictable volume with dietitian endorsement leverage. |
| Air-Puffed Processing Capacity Expansion | Equipment suppliers report 18-month backlogs for turnkey lines achieving 40% caloric reduction. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at specialty cracker manufacturers, category buyers at Whole Foods and Sprouts, supply planners at air-puffed processing equipment suppliers, and formulation chemists with clean-label R&D expertise, then refined through secondary validation against FDA 21 CFR 101.60 filings, USDA Organic certification databases, Nielsen retail audit data, and California Proposition 65 regulatory notices, with bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Variance decomposition across product type, distribution channel, packaging format, and end-user segments structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis weighted by revenue contribution. Forecast inputs incorporated air-puffed processing equipment order backlogs, almond flour futures pricing patterns, and corporate wellness contract procurement timelines.
Material uncertainties — California acrylamide warning rule enforcement intensity, ECHA substance restriction expansion, and drought-driven almond harvest volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory compliance cost absorption and clean-label certification threshold stability. Revision becomes warranted when front-of-package warning adoption crosses thresholds triggering dual-label inventory management requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Baked Savory Snacks Market
Snacks
Premium Snacks Market
Snacks
Roasted Snacks Market
Snacks
Global Vegetable Chips Market
Snacks
North America Savory Snacks Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Legume-Based Snacks Market
Snacks
North America Snack Food Market
Snacks
Fruit Jerky Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Granola Bars Market
Snacks
Salty Puffed Snacks Market
Snacks
Low Calorie Cookies Market
Snacks
Veggie Chips Market
Snacks
Kale Chips Market