
 Extruded Snacks Market | 2026-2036
Extruded Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded Snacks Market Analysis
EU F-Gas Regulation is consolidating the cost-of-entry calculus for manufacturers relying on hydrofluorocarbon-based expansion systems in European facilities. PepsiCo leverages its North American corn supply chain to sustain volume leadership across puffed and baked extruded platforms. ITC Limited anchors its South Asian position through deep rural distribution networks for salty extruded products. Intersnack Group GmbH competes on flavor localization, operating regionally tuned R&D centers across Central and Eastern Europe.
Extruded snacks are cereal- or starch-based products forced through a die under heat and mechanical shear, typically achieving bulk densities of 50–150 g/L and moisture contents below 4% after drying. The process converts raw flour or grit into expanded, porous structures through gelatinization and flash vaporization, creating the crispy texture central to consumer acceptance. Corn snacks dominate volume globally due to favorable expansion ratios and low raw material cost, while rice snacks command premium shelf positioning in allergen-conscious and clean-label segments. Online stores represent the fastest-growing distribution channel, though supermarkets still control the majority of margin pools through slotting fees and promotional leverage.
FDA sodium reduction targets and EFSA acrylamide benchmarks are tightening compositional standards, forcing manufacturers to reformulate recipes and retool thermal profiles. BIS certification requirements in India and GB standards in China add parallel compliance layers for brands seeking multi-territory scale. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility frameworks in Europe reshape packaging material selection and energy intensity thresholds for extrusion lines.
Market Dynamics
Reformulation pressure from sodium and acrylamide regulations is compressing product development cycles while expanding clean-label R&D budgets across extruded snack portfolios.
Growth Catalysts
- FSSAI fortification mandates:India's micronutrient enrichment requirements for processed foods are accelerating premix integration into extruded bases, opening new functional positioning for regional brands.
- Dual carbon goals:China's energy intensity targets are forcing thermal efficiency upgrades in extrusion lines, indirectly improving yield rates and reducing per-unit energy costs for compliant manufacturers.
- Die-face cutting advances:Precision rotary cutting systems are enabling complex 3D shapes at higher line speeds, differentiating shelf presence without material cost increases.
Market Restraints
- Corn price volatility:US Midwest drought cycles and biofuel diversion are amplifying input cost swings for corn-dominant extruded platforms, squeezing margin stability.
- Acrylamide benchmarks:EFSA's tightened exposure limits are forcing thermal profile reductions that compromise expansion ratios, creating texture-quality trade-offs in European production.
- Palm oil substitution complexity:Clean-label pledges are accelerating sunflower and rapeseed oil switches, but these alternatives degrade faster under extrusion shear, shortening fryer oil cycles.
Strategic Opportunities
- PLI scheme leverage:India's production-linked incentive scheme for food processing is subsidizing greenfield extrusion capacity, lowering breakeven thresholds for domestic market entry.
- Direct-to-consumer channels:Branded snack subscriptions and micro-lot e-commerce are bypassing slotting fee structures, capturing margin pools previously absorbed by supermarket gatekeepers.
- Pulse flour convergence:Lentil and chickpea protein concentrates are integrating with traditional starch extrusion, opening allergen-free and high-protein positioning in North American natural retail.
Industry Challenges
- Extrusion engineer scarcity:The specialized knowledge base for screw profile design and die flow simulation is aging out, with limited university pipeline replacement creating hiring bottlenecks.
- Retrofit capex burdens:Legacy lines require substantial mechanical and control system overhauls to meet EFSA acrylamide protocols, straining mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded Snacks Market |
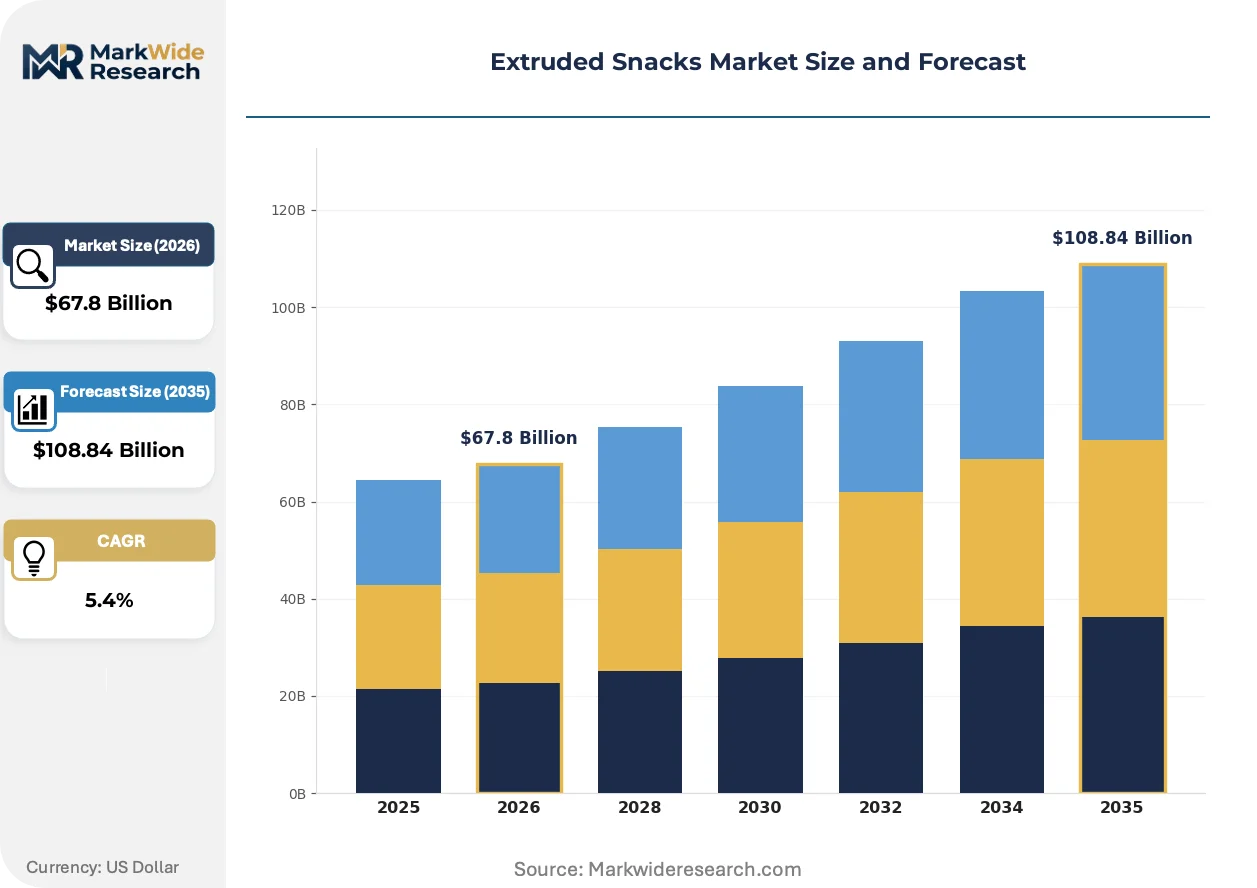
| Market Size in 2026 | $67.8 Billion |
| Market Size in 2035 | $108.84 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Snacks, Potato Snacks, Rice Snacks, Multigrain Snacks Ingredient Type: Flavored Base, Seasonings, Texturizers, Preservatives Packaging Type: Bags, Pouches, Boxes, Cans Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Specialty Shops |
| Companies Covered | Calbee Inc, Want Want Holdings Limited, PepsiCo Inc, Mondelez International Inc, Conagra Brands Inc, General Mills Inc, ITC Limited, Intersnack Group GmbH, Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded Snacks Market Emerging Trajectories
Extrusion technology is converging with digital process control and alternative protein sourcing, reshaping how manufacturers balance texture engineering with regulatory compliance and clean-label positioning.
Artificial vision systems are automating real-time die-face monitoring and cutting synchronization, reducing shape defect rates without manual line intervention. Mid-tier European processors are adopting these systems fastest, driven by EFSA documentation requirements for consistent thermal processing. This automation is compressing the quality gap between mass-market and premium extruded products.
REACH restrictions on processing aids are eliminating certain emulsifiers and lubricants previously standard in European extrusion, forcing reformulation around native starch functionality. Manufacturers are responding with modified screw configurations that compensate for reduced slip agents. The baked extruded segment bears the heaviest adaptation burden, as its lower oil content offers less masking of texture defects.
Urban Indian consumers are gravitating toward single-serve pouches and flavor novelty rotations, fragmenting demand away from family-size formats that dominated traditional distribution. Convenience stores in Mumbai and Bangalore are expanding chilled extruded snack sections, displacing ambient shelf space historically reserved for legacy brands. This channel shift is most pronounced among 18-34 year old purchasers prioritizing portion control and impulse variety.
Extruded Snacks Market Segmentation
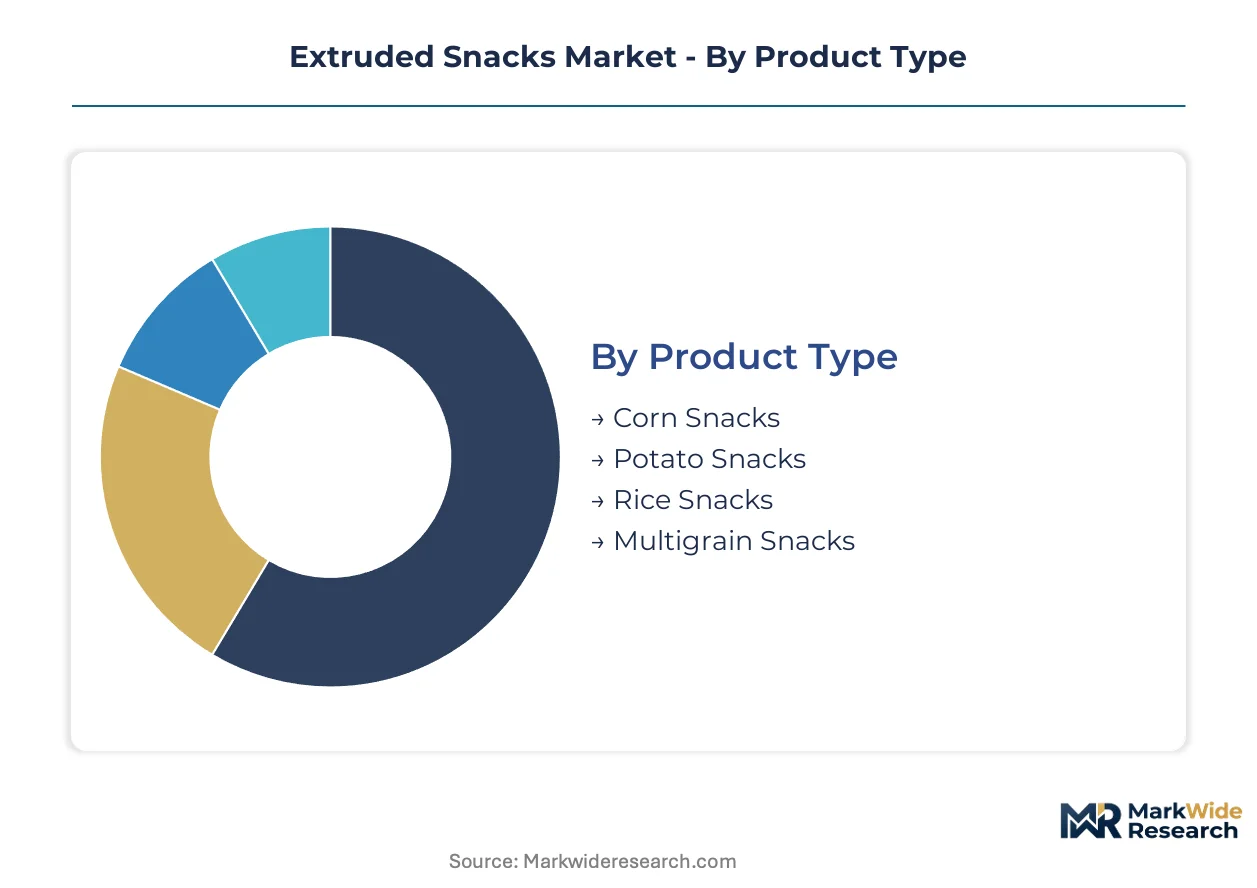
Extruded snack manufacturers configure product portfolios around four intersecting dimensions that determine margin capture and regulatory exposure. Each segmentation layer carries distinct certification burdens and channel access requirements that shape competitive positioning.
Product Type:
FSSAI fortification mandates apply differentially across base materials, with corn and rice platforms facing distinct micronutrient premix integration timelines in India. EFSA acrylamide benchmarks impose stricter thermal profile documentation on high-starch variants.
- Corn Snacks:Achieve bulk densities of 50–150 g/L through gelatinization and flash vaporization of maize grit. Demand concentrates in North American convenience retail where PepsiCo's supply chain integration sustains volume leadership despite Midwest drought volatility.
- Rice Snacks:Command premium shelf positioning through allergen-free claims and clean-label positioning. Urban Indian consumers in Mumbai and Bangalore are absorbing expanded single-serve pouch formats as chilled extruded sections displace ambient legacy brands.
- Potato Snacks:Face elevated acrylamide scrutiny under EFSA protocols due to reducing sugar content.
- Multigrain Snacks:Require complex BIS certification paths in India for composite flour declarations.
Leading the category by volume: Corn Snacks. Growing fastest: Rice Snacks.
Ingredient Type:
REACH restrictions on processing aids are eliminating standard emulsifiers across European extrusion, forcing reformulation toward native starch functionality with modified screw configurations.
- Flavored Base:Carries the heaviest FSSAI micronutrient enrichment compliance burden in India, where fortification mandates accelerate premix integration into extruded bases for functional positioning.
- Seasonings:Sodium reduction targets from FDA labeling requirements are compressing development cycles for North American portfolios while expanding clean-label R&D budgets.
- Texturizers:Substitute complexity rises as palm oil pledges accelerate sunflower and rapeseed switches that degrade faster under shear.
- Preservatives:Face parallel BIS and GB standards compliance layers for multi-territory scale.
Dominant by margin contribution: Seasonings. Expanding most quickly: Flavored Base.
Packaging Type:
Extended producer responsibility frameworks in Europe and dual carbon goals in China are reshaping material selection and energy intensity thresholds across format categories.
- Pouches:Urban Indian demand is fragmenting toward single-serve formats as 18-34 year old purchasers prioritize portion control and impulse variety in convenience stores.
- Bags:Retain supermarket dominance through slotting fee absorption and promotional leverage despite online channel encroachment.
- Boxes:Require heavier compliance documentation for EU recycling content mandates.
- Cans:Face elevated energy intensity scrutiny under China's dual carbon targets for metal forming processes.
Highest volume throughput: Bags. Steepest expansion trajectory: Pouches.
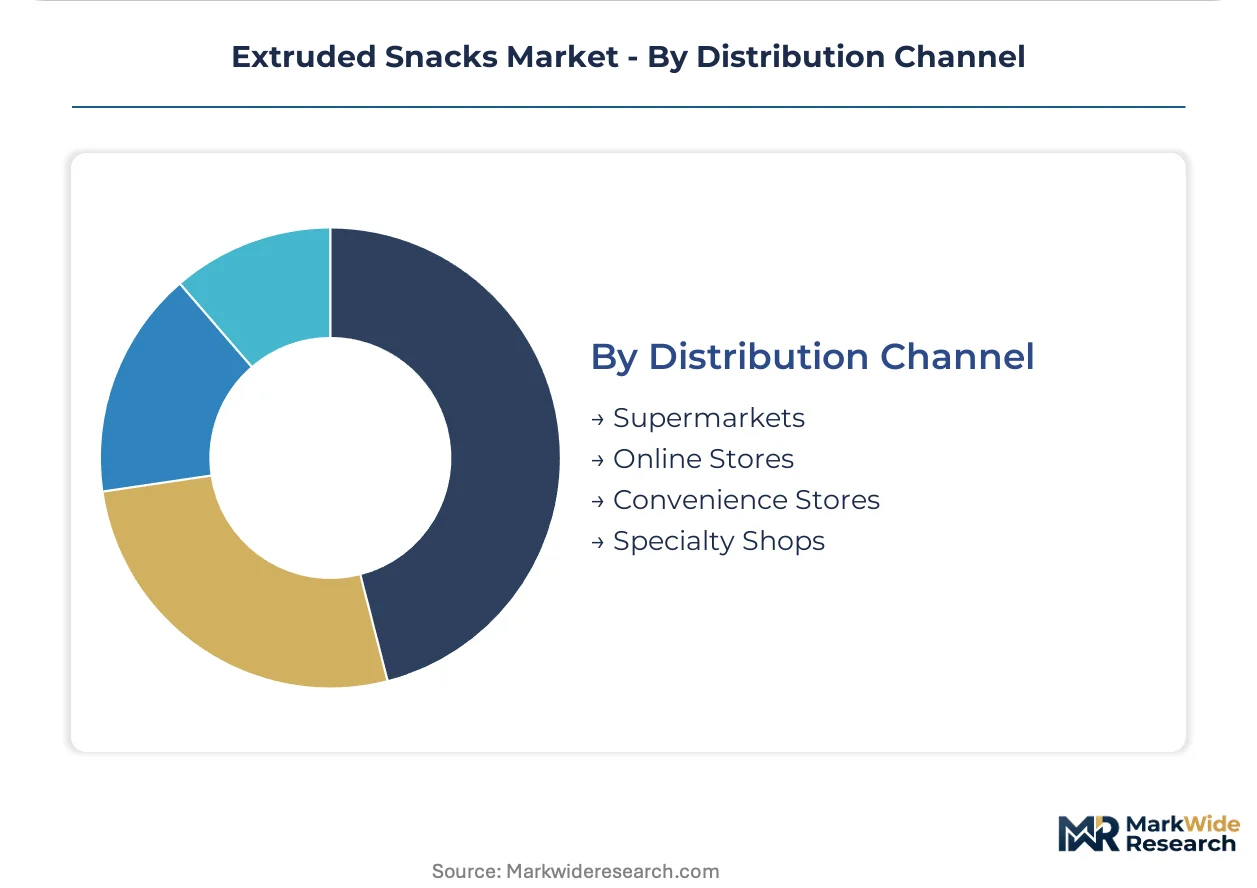
Distribution Channel:
Channel selection determines margin pool access, with direct-to-consumer subscriptions bypassing slotting structures that supermarket gatekeepers historically absorbed.
- Supermarkets:Control majority margin pools through slotting fees and promotional leverage, though chilled extruded sections in Indian convenience retail are displacing their ambient shelf dominance.
- Online Stores:Represent the fastest-growing distribution channel as branded snack subscriptions and micro-lot e-commerce capture margin pools previously absorbed by physical gatekeepers.
- Convenience Stores:Absorb larger volumes as on-the-go consumption patterns intensify across quick-service retail channels.
- Specialty Shops:Concentrate pulse flour convergence demand for lentil and chickpea protein positioning in North American natural retail.
Current revenue concentration: Supermarkets. Gaining share fastest: Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for food processing has concentrated greenfield extrusion investment around Mumbai, Pune, and Bangalore, where domestic brands expand capacity to serve price-sensitive urban consumers.
United States
Midwest drought cycles and biofuel diversion amplify corn price volatility for extruded snack manufacturers. FDA sodium reduction targets and updated labeling requirements for added sugars compress reformulation timelines across North American portfolios. Chicago and Minneapolis-St. Paul host major processing clusters where legacy lines face retrofit capex burdens to meet thermal efficiency standards.
India
ITC Limited and regional brands expand extruded production capacity to capture demand from 18-34 year old purchasers prioritizing portion control and impulse variety. FSSAI fortification mandates for micronutrient enrichment accelerate premix integration into extruded bases for functional positioning. Mumbai and Bangalore convenience stores expand chilled extruded sections, displacing ambient shelf space for legacy formats.
China
Dual carbon goals force thermal efficiency upgrades in extrusion lines, indirectly improving yield rates for compliant manufacturers. GB standards for composite flour declarations add compliance layers for brands seeking multi-territory scale. Yangtze River Delta processing hubs face elevated energy intensity scrutiny under provincial carbon targets.
Germany
Intersnack Group GmbH operates regionally tuned R&D centers across Central and Eastern Europe to compete on flavor localization. EFSA acrylamide benchmarks force thermal profile reductions that compromise expansion ratios, creating texture-quality trade-offs. Bavaria hosts precision rotary cutting system adoption for complex 3D shapes at higher line speeds.
Japan
Clean-label positioning commands premium shelf positioning for rice-based extruded snacks in allergen-conscious segments. METI efficiency standards drive artificial vision system adoption for real-time die-face monitoring. Osaka-Kobe industrial corridor concentrates modified screw configuration development to compensate for reduced slip agents under REACH restrictions.
Extruded Snacks Market Vendor Landscape
North American producers anchor one tier through corn supply chain integration; European specialists hold another via flavor localization and thermal compliance expertise. The market structures around consolidated multinational portfolios and fragmented regional challengers. Three archetypes dominate: scale-driven commodity players, clean-label premium specialists, and emerging-market capacity builders. Competitive moves concentrate on portfolio diversification into pulse flour and direct-to-channel bypass strategies.
Within the scale-driven tier, PepsiCo Inc and Kellogg Company represent integrated North American supply chain positions, while ITC Limited anchors South Asian distribution density. Calbee Inc exemplifies the premium clean-label archetype through rice-based positioning in allergen-conscious segments. These three occupy distinct competitive spaces without direct overlap in core geographies or product architectures.
| Leading Market Players |
|---|
| Calbee Inc |
| Want Want Holdings Limited |
| PepsiCo Inc |
| Mondelez International Inc |
| Conagra Brands Inc |
| General Mills Inc |
| ITC Limited |
| Intersnack Group GmbH |
| Kellogg Company |
| Others |
Supply Flow & Price Mechanics
FSSAI fortification mandates in India are forcing premix integration into extruded bases, compelling manufacturers to absorb micronutrient costs or reformulate around native starch functionality. This specification shift tightens margin pools for mid-tier producers while rewarding scale players with captive premix supply.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Indian convenience chains and North American quick-service retailers compete for spot extrusion capacity. Pricing stratifies across premium, standard, and economy tiers based on fortification grade and thermal profile documentation depth. Cost compression in the standard tier is intensifying due to corn price volatility from Midwest drought cycles. Private-label buyers at supermarket chains exhibit highest price sensitivity, while allergen-conscious natural retail segments absorb premium positioning for rice and pulse flour variants.
Supply Chain Analysis
Freight cost escalation from Yangtze River Delta hubs to European ports is reshaping sourcing calculus for brands seeking multi-territory scale. Raw material supply concentrates in the United States for corn grit, India for rice flour, and China for modified starch and packaging films. Extrusion equipment and precision rotary cutting systems draw from Germany and Japan. Single-source vulnerability sits with hydrofluorocarbon-based expansion systems facing EU F-Gas Regulation phase-down. Distribution runs through supermarket slotting fee structures in mature markets, while direct-to-consumer subscriptions bypass these gatekeepers in growth corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extrusion engineer scarcity and legacy line retrofit burdens are constraining capacity expansion, propping pricing power for compliant manufacturers with thermal efficiency upgrades already deployed.
For Market Incumbents: Anchor defensive positioning through backward integration into corn supply chains and captive premix production for FSSAI compliance. Expand chilled extruded capacity in Mumbai and Bangalore convenience corridors to displace ambient legacy formats. Pulse flour convergence threatens commodity corn positioning; accelerate lentil and chickpea protein R&D to capture natural retail margin pools. For New Entrants and Emerging Players: Direct-to-consumer snack subscriptions represent the most penetrable white-space target, bypassing supermarket slotting fees that absorb margin for established brands. India's PLI scheme-subsidized greenfield capacity offers breakeven threshold advantages for domestic market entry. Lead with micro-lot e-commerce and flavor novelty rotations targeting 18-34 year old urban Indian purchasers prioritizing portion control. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier European processors adopting artificial vision systems for EFSA documentation compliance, given acrylamide benchmark tightening. Long-term viability favors manufacturers with thermal profile optimization expertise and modified screw configuration capabilities. Watch die-face cutting patent filings and REACH restriction adaptation timelines as inflection indicators for technical differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses supermarket slotting fees and captures margin pools in branded snack subscriptions. |
| Pulse Flour Integration | Opens allergen-free and high-protein positioning in North American natural retail segments. |
| Thermal Efficiency Upgrade | Meets China's dual carbon goals while improving yield rates and reducing per-unit energy costs. |
| Precision Rotary Cutting Deployment | Enables complex 3D shapes at higher line speeds for shelf differentiation without material cost increases. |
| Clean-Label Reformulation | Addresses FDA sodium targets and EFSA acrylamide benchmarks while expanding R&D budgets. |
Methodological Framework
Trade databases, customs records, and FSSAI fortification compliance filings formed the secondary backbone of this analysis. Primary interviews with extrusion plant managers, category buyers at convenience retail chains, supply planners at corn processing facilities, and regulatory affairs leads at multinational snack portfolios validated secondary findings. Bottom-up capacity modeling across India's PLI-subsidized greenfield sites and top-down revenue triangulation from Nielsen retail audit data converged on segment-level estimates.
Historical trendline analysis of corn price volatility, thermal efficiency adoption curves, and channel shift velocities informed projection mechanics. Segmentation modeling spanned product type, ingredient composition, packaging format, and distribution channel across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating FSSAI mandate implementation timelines and EFSA acrylamide protocol phase-ins. Forecast inputs included Midwest drought cycle frequency and biofuel diversion coefficients for corn supply scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH restriction expansions, palm oil substitution cost curves, and extrusion engineer pipeline recovery. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Sweet Potato Fries Market
Snacks
Low Fat Protein Snacks Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Trail Mix Market
Snacks
Snack Pellets Market
Snacks
Savory Snacks Market
Snacks
Savoury Biscuits Market
Snacks
Seafood Snacks Market
Snacks
Fried Potato Chips Market
Snacks
Europe Frozen Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Sweet Potato Chips Market
Snacks
High Fiber Snack Foods Market
Snacks
Tortilla Mix Market
Snacks
Low Calorie Snack Foods Market
Snacks
Pretzels (Savory Snacks) Market