
 High Carb Low Fat Snack Market | 2026-2036
High Carb Low Fat Snack Market Size, Share, and Industry Trends Forecast 2026-2036
High Carb Low Fat Snack Market Analytics
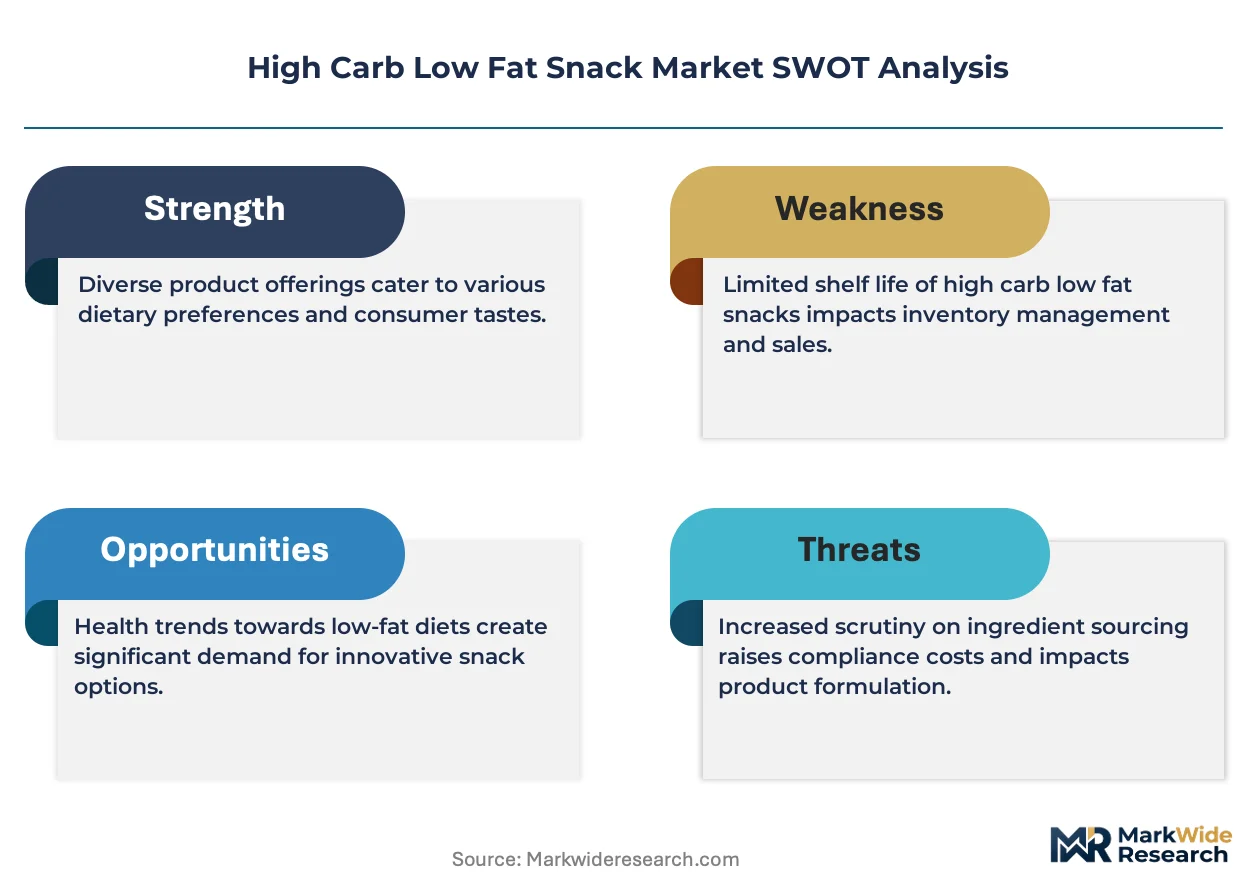
A capital-intensity divergence between shelf-stable manufacturing infrastructure and clean-label R&D investment is reorganizing competitive tiers in the High Carb Low Fat Snack Market. General Mills leverages its grain-milling assets and cereal bar production networks to maintain cost positions in mass retail. Kind LLC differentiates through whole-food ingredient transparency and minimal processing claims that command premium placement in health food shops. Calbee anchors Asian market presence with rice-based snack expertise adapted for export markets.
High carb low fat snacks are formulated products delivering carbohydrate energy exceeding fat content by weight ratio, typically manufactured through extrusion, popping, or cold-pressing processes that preserve structural integrity without oil frying, designed to provide rapid glycemic response for athletic performance or sustained energy in controlled-portion formats. Cereal bars and fruit snacks capture the largest volume share as portable formats align with on-the-go consumption patterns among working professionals. Rice cakes represent the fastest-growing product type as gluten-free positioning and savory flavor innovation expand addressable demand beyond traditional dietetic users. Popcorn occupies a mature margin pool where air-popping technology and heritage brand recognition defend shelf space against private label erosion.
The FDA governs nutrition labeling and health claim substantiation while the USDA administers organic certification standards that shape ingredient sourcing and premium pricing architecture in the United States. The EPA regulates agricultural pesticide residues that cascade into grain and fruit supply chains, affecting clean-label positioning and supplier qualification requirements. Stakeholders must monitor evolving added-sugar enforcement thresholds and state-level packaging waste regulations that could force reformulation or material substitution decisions ahead of compliance deadlines.
Market Dynamics
The FDA's added sugar disclosure mandates are compressing formulation timelines across the High Carb Low Fat Snack Market. Manufacturers must now re-engineer recipes to maintain clean-label positioning while preserving the rapid glycemic response that endurance athletes demand.
Growth Catalysts
- Endurance Sports Normalization:Collegiate athletic programs and sports dietitian recommendations in the United States are embedding carbohydrate-dense fueling into mainstream fitness culture. This institutional adoption creates stable demand pull for portable, portion-controlled formats.
- Clean-Label R&D Investment:Cold-pressing and air-popping technologies enable structural integrity without oil frying. Equipment upgrades at contract manufacturers are expanding capacity for minimal-processing claims that command premium retail placement.
- REACH Compliance in Europe:The ECHA's evolving substance restrictions on packaging materials are accelerating material substitution toward compostable films. Early movers in sustainable packaging capture shelf space in German and Dutch health food channels.
Market Restraints
- Grain Supply Concentration:North American milling infrastructure concentrates premium rice and oat supply among a handful of regional processors. Price volatility in these inputs compresses margin buffers for mid-tier brands.
- Technical Shelf-Life Limitation:Minimal processing claims conflict with moisture-sensitive carbohydrate matrices. Water activity control without synthetic preservatives remains an unsolved formulation constraint for clean-label bars.
- Substitution Threat from Fat-Adapted Diets:Ketogenic and low-carbohydrate eating patterns among recreational fitness participants divert snack occasions toward nut-based alternatives. This behavioral drift constrains addressable market expansion in casual consumer segments.
Strategic Opportunities
- Underpenetrated Japanese Market:METI's functional food claims framework permits carbohydrate-focused performance positioning that remains underexploited by Western exporters. Rice-based snack expertise from domestic players creates partnership openings for flavor innovation.
- Direct-to-Athlete Subscription Channels:Team nutrition programs and individual endurance coaches represent disintermediated purchasing nodes. Digital platforms bypassing traditional retail markup capture lifetime value from high-volume consumers.
- EU Green Deal Packaging Mandates:The European Commission's single-use plastic reduction targets create first-mover advantage for brands deploying home-compostable wrappers. Premium pricing for certified sustainable formats offsets material cost premiums.
Industry Challenges
- Extrusion Technician Scarcity:The specialized knowledge required for high-moisture extrusion of carbohydrate matrices without fat lubrication concentrates among aging workforces at legacy cereal manufacturers. Knowledge transfer gaps threaten production consistency.
- Organic Certification Timeline Compression:USDA organic supply chain verification for grain and fruit ingredients extends 18-24 months. Reformulation cycles outpace certification completion, forcing hold-and-wait inventory strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Carb Low Fat Snack Market |
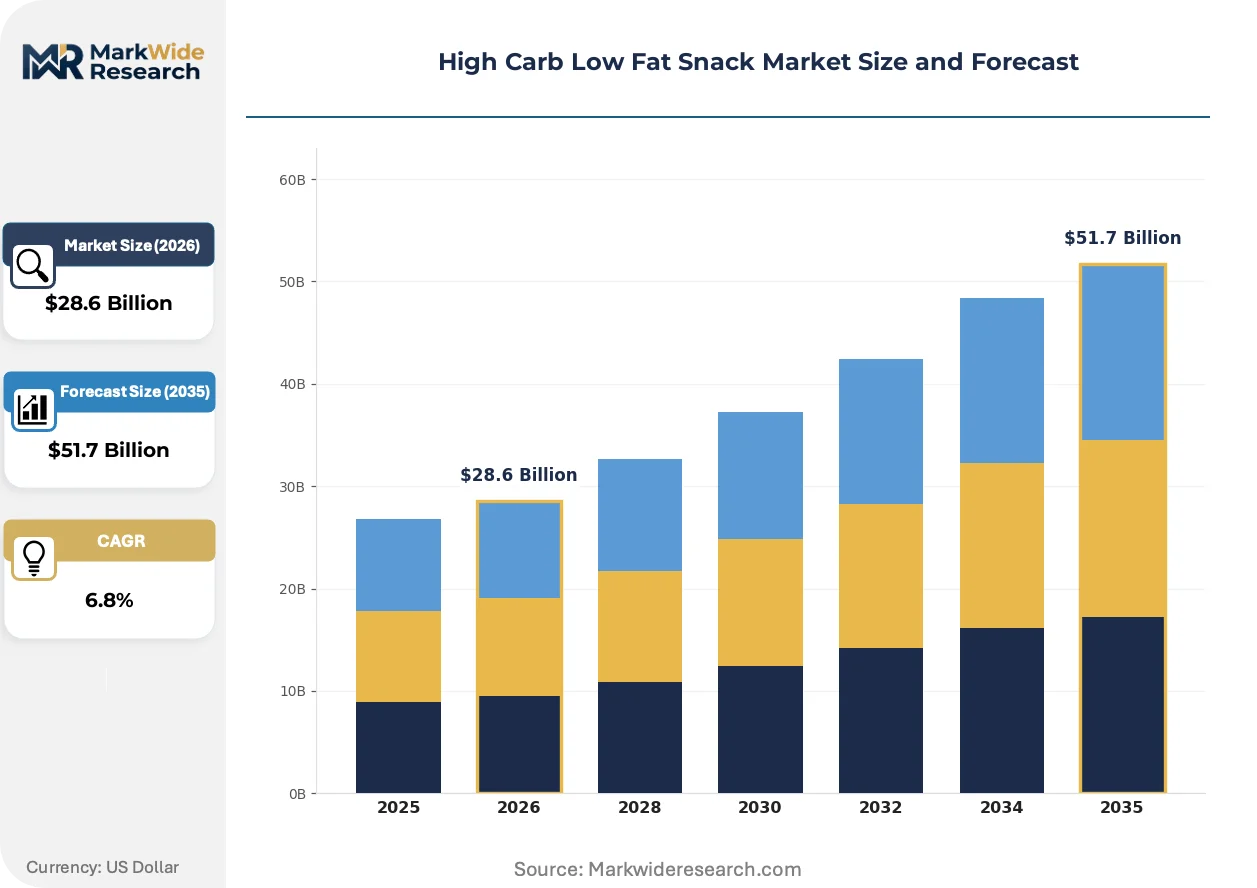
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Bars, Rice Cakes, Fruit Snacks, Popcorn Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops Customer Type: Fitness Enthusiasts, Health-Conscious Consumers, Students, Working Professionals Flavor Profile: Sweet, Savory, Spicy, Fruity |
| Companies Covered | General Mills, B&G Foods, Kellogg Company, The Hain Celestial Group, Kind LLC, Nestlé S.A., Calbee, Clif Bar & Company, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Carb Low Fat Snack Market Evolving Landscape
Reformulation pressures are fragmenting the competitive landscape between heritage brands with legacy manufacturing assets and agile challengers with clean-label supply chains. Technology adoption curves now diverge sharply by distribution channel and buyer sophistication.
Air-popping equipment with real-time moisture sensors is fragmenting production economics across the snack manufacturing base. Contract manufacturers serving private-label retailers adopt these systems fastest to defend volume contracts. The technology is fragmenting cost structures between capital-intensive automated lines and labor-dependent batch operations, squeezing mid-scale producers from both directions.
The FDA's updated Nutrition Facts label requirements are forcing disclosure granularity on added sugars versus naturally occurring carbohydrates. Reformulation teams must now source dried fruit and grain syrups with verifiable intrinsic sugar content. Sports nutrition brands targeting collegiate athletic programs face the steepest compliance burden, as these buyers demand documentation for dietitian review.
Endurance athletes are consolidating purchase decisions through sports dietitian gatekeepers rather than retail discovery. This channel compression redirects marketing spend toward professional education and sampling programs. The United States exhibits the most concentrated dietitian influence, with university athletic departments standardizing approved vendor lists for team nutrition.
High Carb Low Fat Snack Market Segmentation
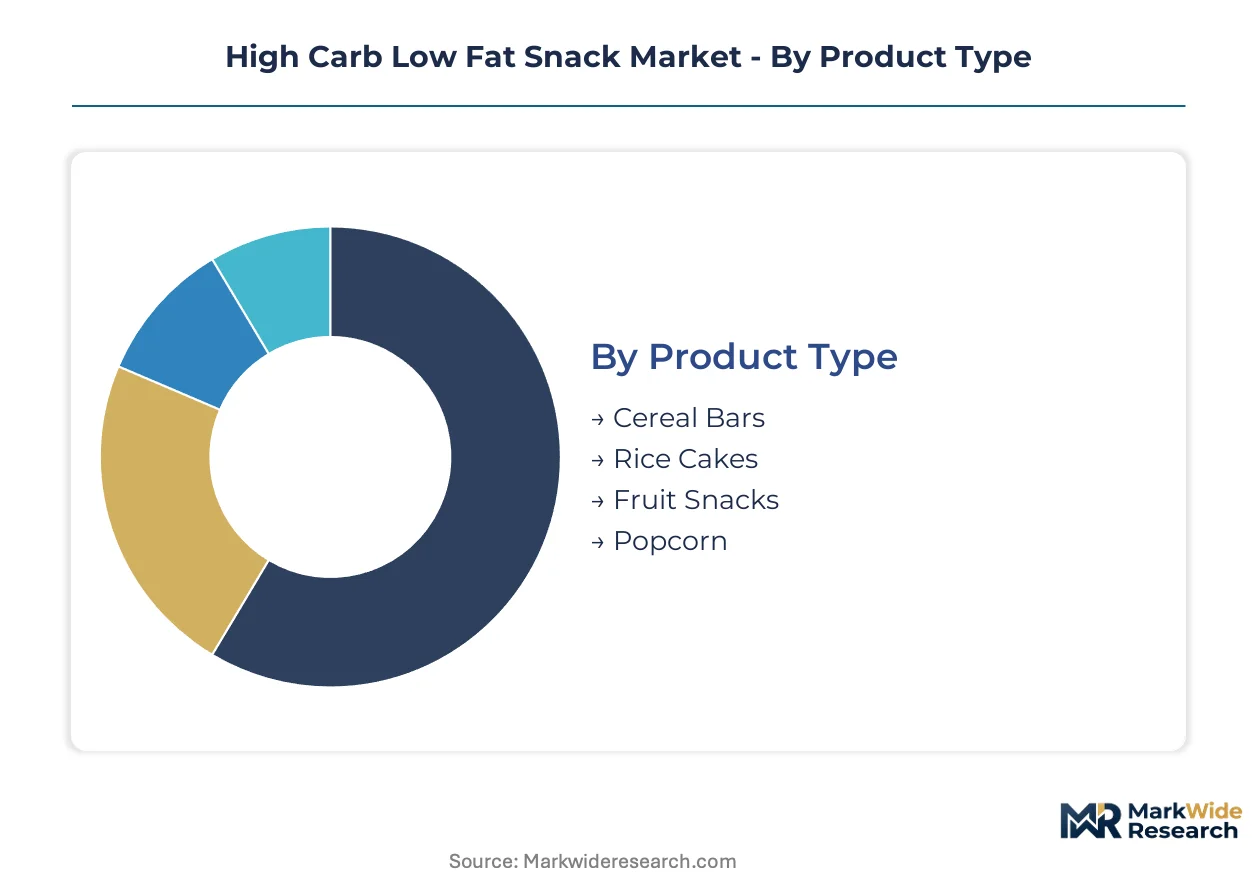
Segmentation in the High Carb Low Fat Snack Market reveals divergent compliance burdens and channel economics across product formats and buyer profiles. FDA disclosure mandates apply unevenly, forcing manufacturers to prioritize segments where reformulation costs align with pricing power.
Product Type:
Regulatory differentiation separates extruded formats from air-popped alternatives, with moisture-sensitive matrices facing steeper USDA organic certification timelines.
- Cereal Bars:Cold-pressed or extruded carbohydrate matrices bound with fruit syrups or grain pastes, delivering portion-controlled energy density. Collegiate athletic programs in the United States concentrate procurement through approved vendor lists, prioritizing documented glycemic response data for sports dietitian review. Cereal bars handle the majority of throughput; rice cakes are the fastest mover on share.
- Rice Cakes:Puffed rice discs manufactured through high-pressure extrusion without oil frying, achieving structural integrity through starch gelatinization. Gluten-free positioning expands demand beyond traditional dietetic users into mainstream health-conscious households, with savory flavor innovation driving repeat purchase in German and Dutch retail channels.
- Fruit Snacks:Dehydrated or pectin-gelled fruit pieces with controlled water activity for shelf stability.
- Popcorn:Air-popped heritage format defending mature margin pools against private label erosion through brand recognition.
Cost tier separation distinguishes capital-intensive extrusion infrastructure from flexible air-popping operations.
Distribution Channel:
Channel selection determines margin capture, with direct-to-athlete platforms bypassing traditional retail markups while supermarkets enforce slotting fee burdens.
- Supermarkets:Mass retail channels commanding volume through heritage brand placement and promotional calendar coordination. Working professionals in the United States drive impulse purchase at checkout displays, though slotting fees compress margins for mid-tier entrants lacking General Mills-scale leverage.
- Online Retail:Digital platforms enabling subscription-based replenishment for high-volume endurance athletes and team nutrition programs. Direct-to-consumer economics capture lifetime value through bypassed distributor margins, though cold-pressed bars face temperature-controlled shipping cost premiums.
- Convenience Stores:Grab-and-go occasions targeting students and commuters with single-serve portability.
- Health Food Shops:Premium placement for clean-label claims with minimal processing transparency.
Volume concentrates in supermarket chains; online retail climbs the fastest on penetration rate.
Customer Type:
Application focus separates performance-driven athletic fueling from discretionary wellness snacking, with institutional buyers demanding documentation that casual consumers ignore.
- Fitness Enthusiasts:Endurance athletes and recreational competitors prioritizing rapid glycemic response for training and event fueling. Sports dietitian gatekeepers in United States university athletic departments consolidate purchase decisions through standardized nutrition protocols, creating vendor stickiness for approved brands.
- Health-Conscious Consumers:Wellness-focused buyers selecting snacks based on ingredient transparency and processing minimalism. Clean-label R&D investment targets this segment with whole-food positioning that commands premium pricing in health food channels.
- Students:Price-sensitive demographic prioritizing portability and shelf stability for campus consumption.
- Working Professionals:On-the-go buyers aligning portable formats with commute and desk-based eating occasions.
Fitness enthusiasts anchor volume commitment; health-conscious consumers are expanding most quickly on wallet share.
Flavor Profile:
Margin structure varies by flavor complexity, with savory formulations requiring more expensive seasoning systems and extended R&D cycles.
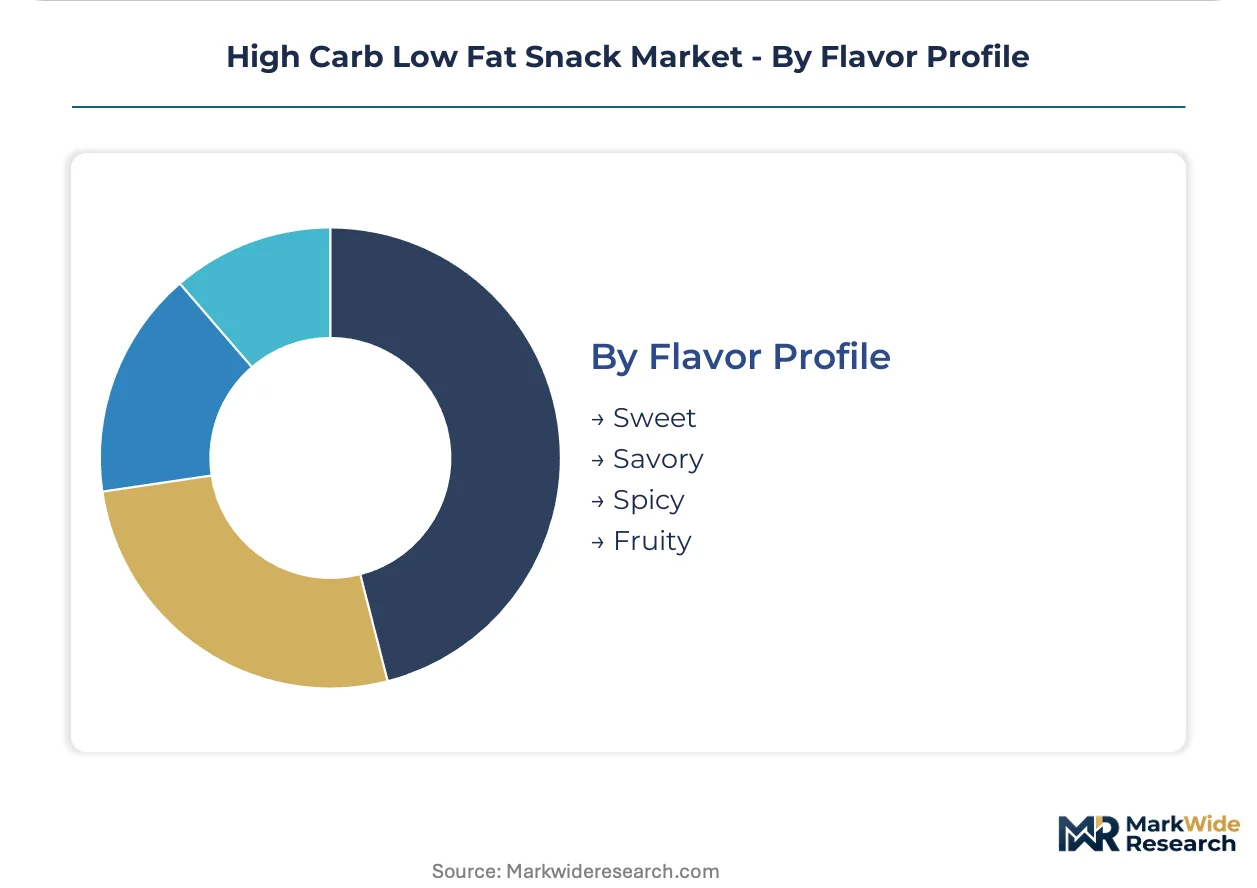
- Sweet:Traditional fruit syrups, honey, and grain-based sweeteners dominating legacy cereal bar portfolios. FDA added sugar disclosure mandates force reformulation toward dried fruit with verifiable intrinsic sugar content, extending development timelines for sports nutrition brands targeting dietitian-reviewed procurement.
- Savory:Herb, spice, and umami seasoning systems expanding rice cake appeal beyond breakfast occasions into all-day snacking. Japanese flavor innovation partnerships create differentiation in export markets, with soy sauce and seaweed variants capturing shelf space in Asian-adjacent retail clusters.
- Spicy:Chili and pepper-based heat profiles targeting adventurous younger demographics.
- Fruity:Berry and citrus natural flavor systems competing with synthetic alternatives on clean-label positioning.
Sweet profiles dominate current throughput; savory options gain share fastest on occasion expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize rapid glycemic response for athletic performance, while European markets emphasize clean-label minimalism and Asian consumers favor rice-based savory formats.
United States
Collegiate athletic programs and sports dietitian networks institutionalize carbohydrate-dense fueling protocols. The FDA's updated Nutrition Facts label requirements force reformulation toward verifiable intrinsic sugar content. Minneapolis-St. Paul anchors grain-milling infrastructure where legacy cereal manufacturers defend mass retail shelf space.
Germany
Health-conscious households drive savory rice cake demand beyond traditional dietetic users. The ECHA's REACH substance restrictions on packaging accelerate compostable film adoption. Berlin and Hamburg health food channels reward early movers in sustainable packaging with premium placement.
Japan
Rice-based snacking heritage creates export expertise adapted for Western markets. METI's functional food claims framework permits carbohydrate-focused performance positioning underexploited by foreign brands. Tokyo-Osaka corridor concentrates flavor innovation partnerships for soy sauce and seaweed variants.
Netherlands
EU Green Deal packaging mandates concentrate demand for home-compostable wrappers in Dutch retail. Amsterdam and Rotterdam distribution hubs service German and Belgian cross-border health food channels. Sustainable format certification commands pricing premiums that offset material cost increases.
United Kingdom
Working professionals align portable cereal bar formats with commute-based consumption. Sports nutrition brands targeting university athletic departments face documentation burdens for dietitian-reviewed procurement. London and Southeast England concentrate direct-to-athlete subscription platform development.
High Carb Low Fat Snack Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the High Carb Low Fat Snack Market. Heritage cereal manufacturers leverage grain-milling assets and extrusion infrastructure to defend mass retail volume. Agile clean-label challengers command premium placement through minimal-processing claims. The dominant competitive moves are portfolio diversification into savory flavor systems and strategic partnerships for sustainable packaging certification.
Within the integrated leader tier, General Mills exemplifies scale-driven manufacturing economics, while Kind LLC occupies a position emphasizing whole-food ingredient transparency. Among Asian specialists, Calbee represents rice-based snack expertise adapted for export market expansion.
| Leading Market Players |
|---|
| General Mills |
| B&G Foods |
| Kellogg Company |
| The Hain Celestial Group |
| Kind LLC |
| Nestlé S.A. |
| Calbee |
| Clif Bar & Company |
| PepsiCo |
| Others |
Value Network & Pricing Analysis
Compostable film substitution for conventional plastic packaging simultaneously relocates supplier relationships toward German and Dutch specialty converters and compresses margin buffers through material cost premiums that health food channels only partially absorb.
Pricing Analysis
Subscription-based replenishment for team nutrition programs and individual endurance athletes drives lifetime value through bypassed distributor markups. Three-tier pricing structure across premium clean-label, standard mass-market, and economy private-label levels separates buyers by certification grade and processing transparency claims. Pricing pressure stems from slotting fee burdens at supermarkets that compress mid-tier brand margins. Students exhibit highest price sensitivity while collegiate athletic programs demonstrate lowest sensitivity due to institutional procurement budgets.
Supply Chain Analysis
Inbound logistics costs for Asian rice and oat inputs fluctuate with container availability on transpacific trade lanes serving West Coast milling clusters. Premium grain supply concentrates in the United States, Thailand, and Vietnam. Raw material dependencies include specialty rice varieties, gluten-free oat streams, and dried fruit with verifiable intrinsic sugar content. Single-source vulnerability threatens organic certification timelines that extend eighteen to twenty-four months. Distribution runs through mass retail supermarkets, direct-to-athlete digital platforms, and health food specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Carb Low Fat Snack Market is experiencing high-growth disruption as FDA added sugar disclosure mandates force simultaneous reformulation across multiple product lines.
For Market Incumbents: Consolidate grain-milling assets and extrusion infrastructure through selective facility upgrades that preserve cost positions against private-label erosion. Acquire cold-pressing equipment capabilities to defend shelf space as clean-label R&D investment becomes table stakes. Channel control through approved vendor lists at collegiate athletic programs offers defensive moats against emerging entrants. For New Entrants and Emerging Players: Differentiate on savory flavor innovation for rice cakes in German and Dutch health food channels where incumbent coverage remains thin. Target direct-to-athlete subscription platforms as the most penetrable distribution node, bypassing slotting fees that constrain supermarket entry. Partner with Japanese flavor houses for soy sauce and seaweed variants that command premium placement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed clean-label challengers possessing minimal-processing supply chains but limited scale. Five-to-ten year viability hinges on sustainable packaging certification completion ahead of EU Green Deal mandates. Watch for extrusion technician scarcity forcing production consistency failures at legacy manufacturers as an inflection signal for distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Packaging Certification | EU Green Deal compliance unlocks premium placement in Amsterdam and Rotterdam distribution hubs. |
| Direct-to-Consumer Platform Launch | Bypassed retail markups capture lifetime value from high-volume endurance athletes and team nutrition programs. |
| Savory Flavor Portfolio Extension | Japanese METI partnerships enable soy sauce and seaweed variants for Asian-adjacent retail clusters. |
| Cold-Pressing Equipment Investment | Minimal-processing claims command premium shelf space in health food shops against heritage brand competition. |
| Organic Supply Chain Backward Integration | Captive grain sourcing compresses eighteen-to-twenty-four month USDA certification timelines for clean-label positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with sports dietitians, category buyers at health food retailers, extrusion equipment technicians, and supply chain managers at grain processors; and secondary validation through FDA guidance documents, USDA organic certification databases, ECHA REACH substance restriction updates, and Nielsen retail audit data. Bottom-up and top-down triangulation cross-checked volume estimates against production capacity at legacy cereal manufacturers and import records for Asian rice-based snack inputs.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product format, distribution channel, customer type, and flavor profile. CAGRs were derived from trend extrapolation of collegiate athletic program procurement data and sports dietitian recommendation patterns. Industry-specific forecast inputs incorporated cold-pressing equipment adoption curves and compostable packaging material cost trajectories.
Decision-makers should treat outputs as directional under assumptions of stable FDA enforcement thresholds and continued endurance sports participation growth; material deviation would warrant model refresh. Specific risks include ketogenic diet substitution accelerating beyond baseline assumptions or grain supply concentration triggering input price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Snack Foods Market
Snacks
South Africa Savory Snacks Market
Snacks
Low Fat Sweet Snacks Market
Snacks
North America Energy Bar Market
Snacks
Low Fat Crackers Market
Snacks
Middle East Snack Bar Market
Snacks
Dried Fruit Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Snack Subscription Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Granola Bars Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Popcorn Market
Snacks
North America Snack Bar Market