
 Peanut Butter Keto Snacks Market | 2026-2036
Peanut Butter Keto Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Peanut Butter Keto Snacks Market Analytics
Keto certification standards such as the Certified Ketogenic seal is rotating as a gatekeeper for shelf placement in premium retail channels. Justin's leverages its clean-ingredient heritage and direct farm relationships to sustain price premiums in the nut butter segment. Crazy Richard's anchors its competitive stance through single-ingredient positioning and minimal processing claims. Walmart competes on distribution density, controlling shelf space allocation across its supercenter network to capture impulse purchases.
Peanut butter keto snacks are shelf-stable food products formulated with high fat, moderate protein, and restricted net carbohydrate content, typically achieving ketogenic ratios through the exclusion of refined sugars and the incorporation of alternative sweeteners such as erythritol, monk fruit, or allulose. Their primary commercial purpose is to provide convenient, portion-controlled nutrition that maintains metabolic ketosis for consumers following carbohydrate-restricted dietary protocols. The product type dimension shows bars commanding the largest volume share due to portability and meal-replacement utility, while nut butters capture disproportionate margin pools through premium positioning and subscription recurrence. Ingredient source stratification reveals sugar-free claims generating the fastest velocity growth as diabetic and insulin-sensitive cohorts expand beyond traditional keto adopters.
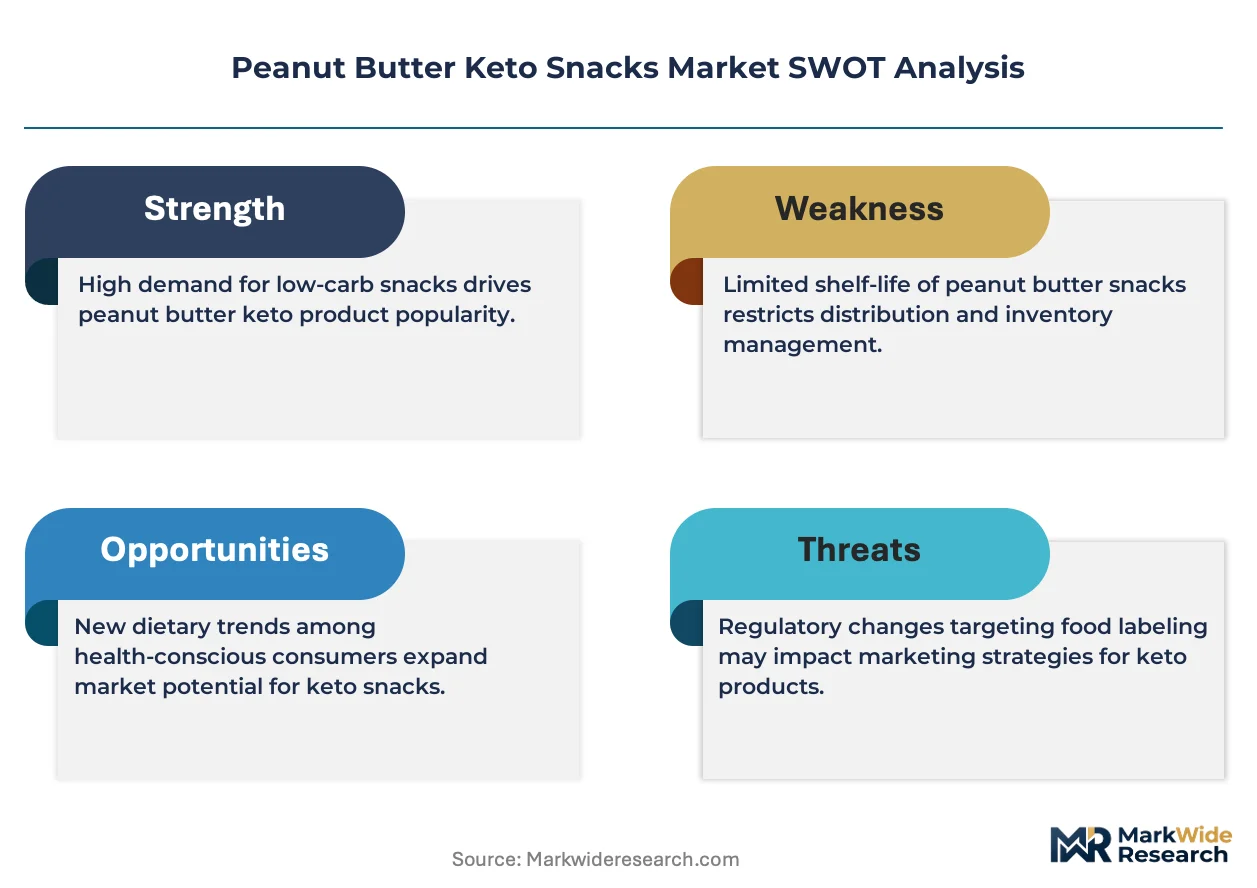
FDA oversight of nutrition labeling and net carbohydrate calculations directly shapes permissible marketing claims and reformulation costs for manufacturers seeking ketogenic positioning. USDA organic certification and Non-GMO Project verification add compliance layers that filter smaller entrants from national retail distribution. State-level cottage food laws and commercial kitchen regulations create fragmented production licensing requirements that influence regional supply patterns. Stakeholders must monitor evolving FDA guidance on allulose caloric valuation and emerging state restrictions on processed food retail taxation that could alter channel economics and consumer price sensitivity.
Market Dynamics
Clean-label formulation mandates from the FDA and USDA are forcing manufacturers to reformulate around restricted sweetener declarations and recalculated net carbohydrate methodologies, compressing margins for legacy players dependent on maltitol and sugar alcohol blends.
Growth Catalysts
- USDA Organic Certification:The USDA organic seal unlocks placement in premium natural retail channels and commands 15-30% price premiums over conventional positioning.
- Erythritol-to-Allulose Substitution:Allulose's FDA-exempt caloric status enables deeper carbohydrate reduction without digestive side effects, accelerating reformulation across bar and spread formats.
- Subscription Commerce Infrastructure:Direct-to-consumer platforms built on Shopify and Amazon Subscribe & Save capture recurring revenue with 40-60% higher lifetime value than brick-and-mortar acquisition.
Market Restraints
- Peanut Input Volatility:Georgia and Texas drought cycles create 18-24 month price swings in runner peanut futures, destabilizing cost structures for single-ingredient positioned brands.
- Allulose Supply Concentration:Domestic allulose production concentrates in two Iowa-based fermentation facilities, creating bottleneck risk for manufacturers scaling keto-certified lines.
- Net Carb Calculation Disputes:Absent FDA-mandated standardization, competing methodologies for fiber and sugar alcohol subtraction generate consumer confusion and class-action exposure.
Strategic Opportunities
- Certified Ketogenic Retail Placement:The Certified Ketogenic seal, administered by the Ketogenic Certification Foundation, functions as a gatekeeper for Whole Foods and Sprouts shelf allocation.
- Diabetic Cohort Expansion:Type 2 diabetes management protocols increasingly prescribe carbohydrate restriction, extending addressable market beyond fitness-oriented keto adopters.
- Monk Fruit-Erythritol Blending:Hybrid sweetener systems reduce cooling aftertaste and improve bake stability, enabling penetration into conventional snack aisles previously closed to alternative sweeteners.
Industry Challenges
- Clean-Label Reformulation Timelines:FDA nutrition label updates and state-level cottage food law variations force 12-18 month product development cycles for multi-state distribution.
- Co-Manufacturer Capacity Scarcity:Ketogenic-certified production lines require segregated equipment and allergen protocols, limiting available contract manufacturing capacity for mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanut Butter Keto Snacks Market |
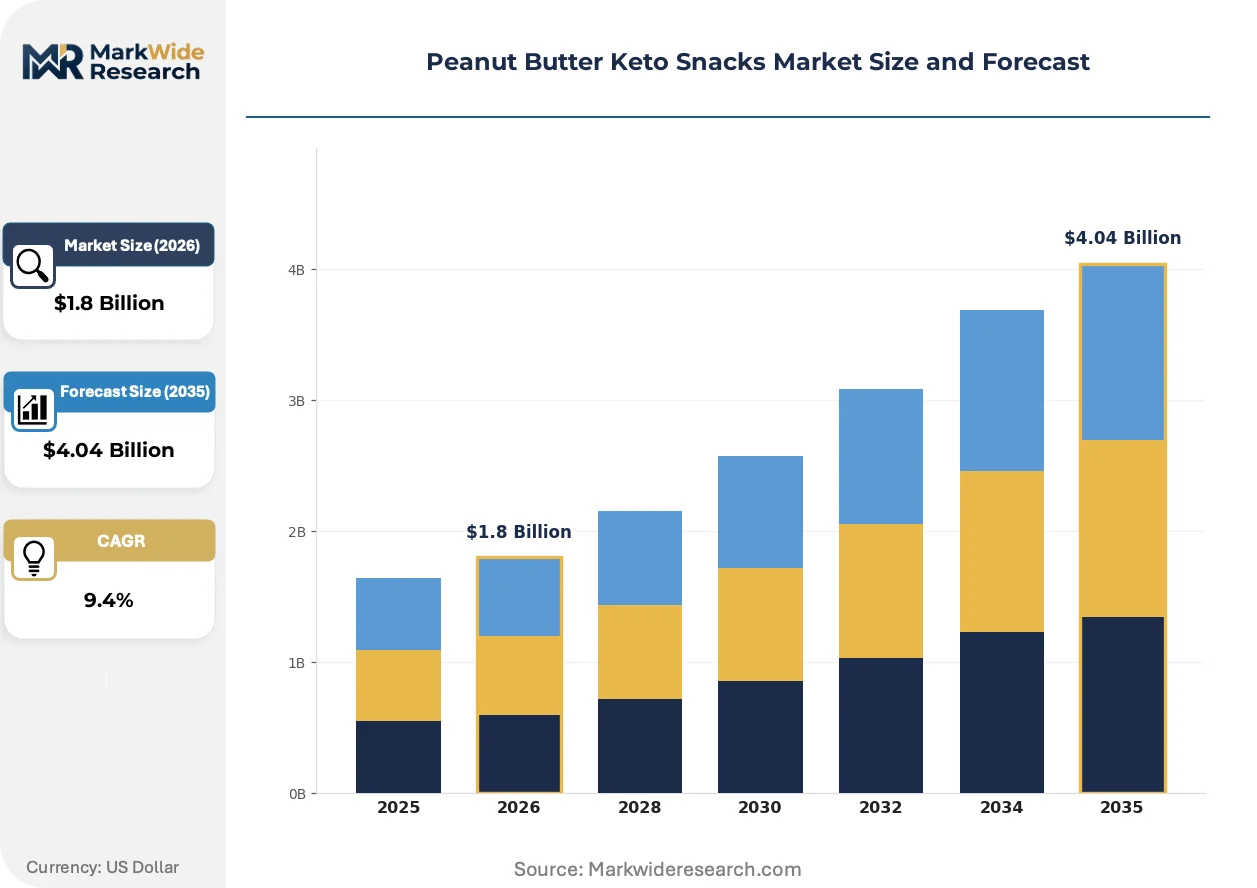
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Cookies, Nut Butters, Snacks Flavor Profile: Chocolate, Vanilla, Maple, Cinnamon Ingredient Source: Organic, Non-GMO, Gluten-Free, Sugar-Free Packaging Type: Bags, Boxes, Jars, Sachets |
| Companies Covered | Crazy Richard’s, Justin’s, Maranatha, Wonderspread, No Sugar Company, Walmart, Santa Cruz, Skippy, 365 by Whole Foods Market, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanut Butter Keto Snacks Market Evolving Landscape
Alternative protein and fat structuring technologies are displacing conventional peanut butter textures while regulatory pressure on sugar alcohol labeling forces transparency reforms. Consumer procurement patterns are fragmenting across subscription, specialty retail, and mass-market channels simultaneously.
Allulose fermentation-derived sweetening systems are displacing erythritol-dominant formulations in premium bar and spread applications. Brands targeting insulin-sensitive and diabetic consumers have accelerated adoption since the FDA's 2019 caloric exemption ruling. This displacement compresses demand for sugar alcohols with known digestive tolerability thresholds while enabling deeper carbohydrate reduction claims.
FDA draft guidance on allulose caloric valuation and net carbohydrate disclosure methodologies is reshaping permissible front-of-pack marketing claims. Manufacturers face reformulation costs and label redesign timelines to maintain ketogenic positioning compliance. The bar segment, with its meal-replacement utility and higher price points, absorbs these compliance costs most aggressively.
Subscription box curation and direct-to-consumer sampling are fragmenting traditional retail discovery pathways for new entrants. Fitness influencers and registered dietitians on TikTok and Instagram now function as primary gatekeepers for brand trial, displacing in-store demo programs. This channel shift concentrates most acutely among millennials and Gen Z consumers in coastal metropolitan markets.
Peanut Butter Keto Snacks Market Segmentation
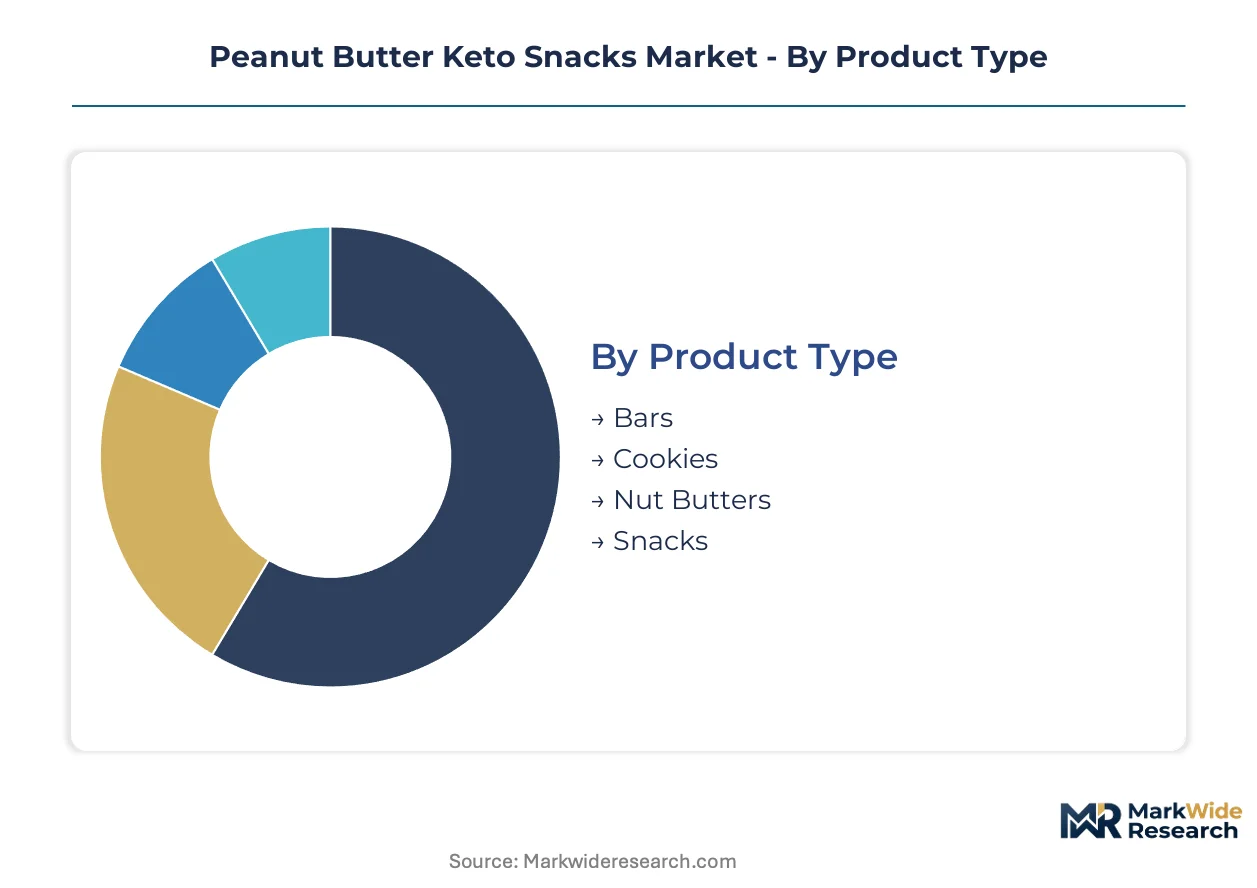
Segmentation in the Peanut Butter Keto Snacks Market reveals how formulation standards and packaging economics fragment commercial opportunity. FDA labeling requirements and USDA certification tiers create distinct addressable markets with divergent margin structures and channel access.
Product Type:
FDA net carbohydrate calculation methodologies favor certain formats over others in front-of-pack claim permissibility.
- Bars:Extruded or cold-pressed formats combining peanut butter with collagen or MCT oil achieve ketogenic macronutrient ratios in shelf-stable form. Meal-replacement utility concentrates demand among fitness consumers in California and Texas metropolitan corridors, with subscription recurrence driving lifetime value premiums over impulse formats.
- Nut Butters:Single-ingredient or dual-ingredient spreads rely on grinding consistency and oil separation control for texture differentiation. Premium positioning in natural retail channels commands price multiples over conventional peanut butter, though Georgia and Texas drought cycles introduce raw material volatility that compresses margins for unblended positioning.
- Cookies:Baked formats using alternative flours and sweeteners face bake-stability challenges that extend product development timelines.
- Snacks:Bite-sized or puffed formats target portability occasions with lower per-unit pricing and higher velocity turnover.
Bars handle the majority of throughput; nut butters are expanding most quickly on margin contribution.
Flavor Profile:
Consumer trial rates and repeat purchase patterns stratify sharply across taste categories, with certain profiles unlocking conventional retail placement previously closed to keto-positioned products.
- Chocolate:Cocoa powder and cocoa butter integration masks alternative sweetener aftertaste while delivering familiar indulgence cues. Mass-market grocery penetration concentrates in the Northeast and Midwest, where conventional snack aisle placement depends on monk fruit-erythritol blend stability in chocolate coatings.
- Vanilla:Clean-label vanilla extract or natural flavor positioning aligns with premium organic certification tiers. Direct-to-consumer subscription boxes in coastal metropolitan markets favor vanilla for its versatility in smoothie and baking applications beyond standalone consumption.
- Maple:Natural maple extract or allulose-based maple flavoring targets seasonal purchase occasions and breakfast substitution use cases.
- Cinnamon:Spice-forward positioning appeals to diabetic cohorts seeking glycemic control without dessert-category signaling.
Chocolate commands the volume base; maple is gaining share fastest through seasonal limited-release strategies.
Ingredient Source:
USDA and FDA compliance layers filter manufacturer participation, with certification stacking determining accessible retail tiers and permissible price positioning.
- Sugar-Free:Exclusion of all nutritive sweeteners through erythritol, allulose, or monk fruit formulations addresses insulin-sensitive and Type 2 diabetic consumers beyond traditional keto adopters. Velocity growth concentrates in pharmacy retail channels and healthcare practitioner recommendation networks, where glycemic impact claims undergo stricter evidentiary scrutiny.
- Organic:USDA certification requires peanut sourcing from certified organic operations with segregated handling protocols. Premium natural retail placement at Whole Foods and Sprouts demands organic certification as a baseline qualifier, with 15-30% price premiums over conventional positioning supporting reformulation and certification cost recovery.
- Non-GMO:Non-GMO Project verification provides mid-tier differentiation for conventional retail placement without full organic compliance cost burden.
- Gluten-Free:Gluten-free claims expand addressable market to celiac and gluten-sensitive consumers, though cross-contamination protocols add production line segregation requirements.
Sugar-free claims absorb the highest current investment; organic certification carries the steepest expansion trajectory in premium channel placement.
Packaging Type:
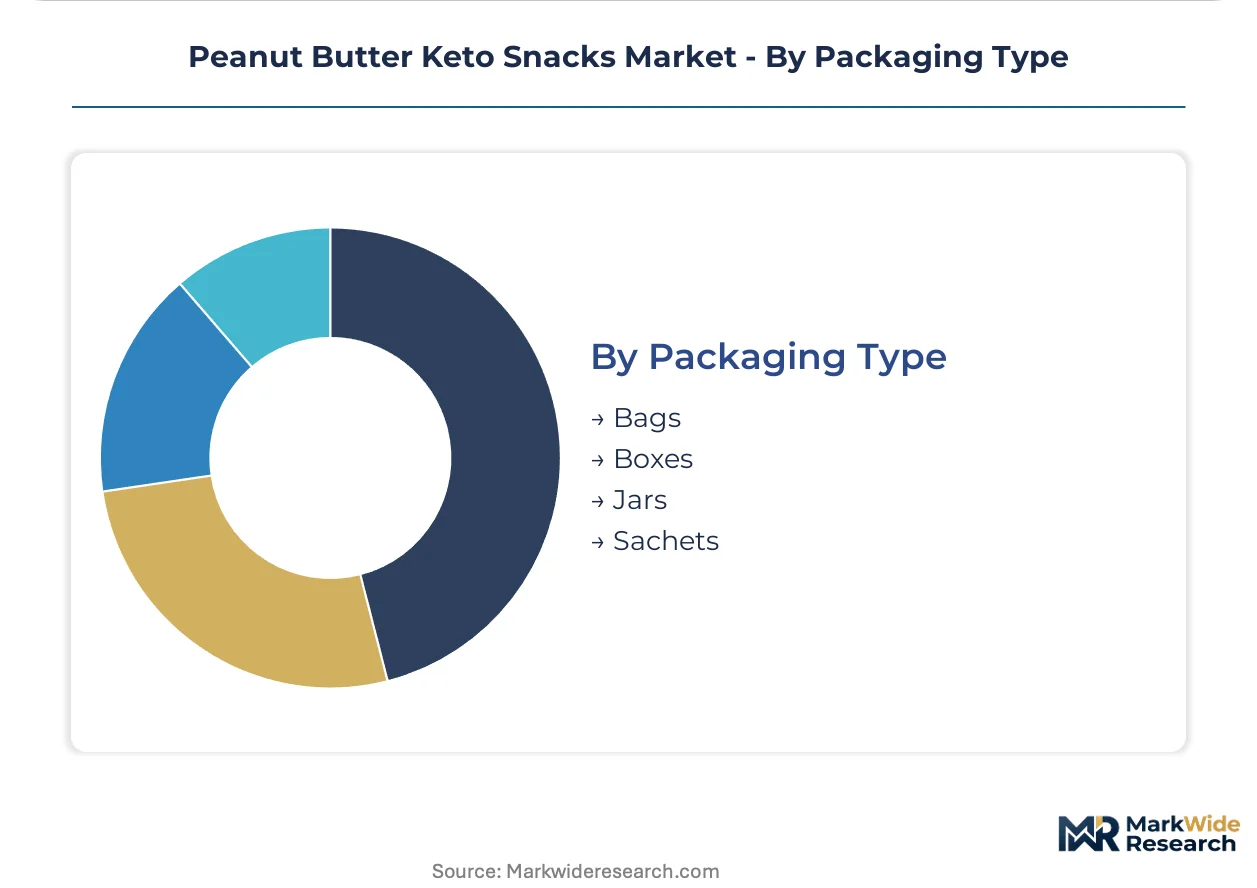
Packaging economics and shelf-life engineering dictate channel suitability, with format selection directly influencing distribution density and consumer occasion targeting.
- Bars:Individual flow-wrap or wrapper formats enable vending machine, convenience store, and gym placement with portion-controlled unit economics. Impulse purchase velocity in these channels outpaces household stock-up occasions, though per-unit packaging costs compress margins compared to multi-serve formats.
- Bags:Multi-serve flexible packaging for bite-sized or puffed formats targets household pantry stocking and cost-conscious volume purchasing.
- Jars:Glass or PET containers for nut butter spreads require shelf-stable oil stability and scooping viscosity control for repeat use occasions.
- Sachets:Single-serve flexible pouches for nut butter or spread formats target on-the-go consumption and airline or hospitality channel placement.
- Boxes:Rigid packaging for premium gift sets or subscription curation elevates unboxing experience and supports direct-to-consumer brand building.
Bars dominate unit volume throughput; sachets are climbing fastest as travel and hospitality channels recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification subsidies and FDA net carbohydrate labeling guidance are accelerating facility investments in peanut butter keto snack manufacturing clusters. Brazil and Argentina benefit from agricultural commodity advantages, while European clean-label regulations reshape import compliance requirements. Asian markets show emerging demand through diabetes management protocols and fitness subscription commerce.
United States
Ketogenic diet adherence rates and direct-to-consumer subscription infrastructure drive demand concentration in California and Texas metropolitan corridors. FDA nutrition labeling updates on allulose caloric valuation force reformulation timelines for manufacturers seeking ketogenic positioning. Georgia and Texas drought cycles in runner peanut growing regions create raw material price volatility that compresses margins for single-ingredient brands.
Brazil
Diabetes prevalence rates and carbohydrate-restricted clinical protocols expand addressable market beyond traditional fitness adopters in São Paulo and Rio de Janeiro. ANVISA food labeling regulations on alternative sweetener declarations add compliance layers for imported keto-positioned products. The São Paulo state industrial corridor hosts contract manufacturing capacity for South American distribution.
Germany
EFSA guidance on novel food approvals for allulose and monk fruit extracts shapes permissible ingredient portfolios for EU market entry. Clean-label consumer preferences in Bavaria and North Rhine-Westphalia drive organic certification stacking for premium retail placement. The Munich metropolitan area anchors natural products distribution infrastructure serving Central European markets.
India
Type 2 diabetes management protocols and rising fitness subscription commerce accelerate demand in Maharashtra and Karnataka. FSSAI food safety standards on alternative sweetener maximum limits and labeling requirements filter permissible formulations for domestic manufacturing. The Mumbai-Pune industrial corridor develops contract manufacturing capacity for export-oriented keto snack production.
Australia
TGA-aligned food standards on low-carbohydrate health claims and glycemic index labeling enable premium positioning in pharmacy retail channels. Fitness influencer commerce and CrossFit affiliate networks concentrate demand in Sydney and Melbourne metropolitan markets. The Victorian food manufacturing cluster hosts allergen-segregated production lines for ketogenic-certified exports.
Peanut Butter Keto Snacks Market Competitive Landscape
Player mix skews toward specialty nut butter heritage brands and mass-market private label operators with divergent margin structures. Consolidation pressure concentrates among mid-scale entrants facing co-manufacturer capacity scarcity and certification cost recovery challenges. Two strategic archetypes dominate: single-ingredient minimalists leveraging farm-direct sourcing, and multi-format portfolio builders capturing subscription recurrence. Competitive moves center on certified ketogenic retail gatekeeping and backward integration into peanut sourcing.
Within the heritage specialist tier, Crazy Richard's and Justin's exemplify divergent positioning strategies—Crazy Richard's anchors single-ingredient minimalism while Justin's leverages clean-label farm relationships for premium pricing. Walmart occupies the scale-driven private label vector, controlling shelf space allocation across its supercenter network to capture impulse purchases. Santa Cruz and 365 by Whole Foods Market sit within the natural retail certification tier, where USDA organic and Non-GMO Project verification function as baseline qualifiers for premium channel access.
| Leading Market Players |
|---|
| Crazy Richard's |
| Justin's |
| Maranatha |
| Wonderspread |
| No Sugar Company |
| Walmart |
| Santa Cruz |
| Skippy |
| 365 by Whole Foods Market |
| Others |
Value Network & Pricing Analysis
Allulose-to-erythritol substitution in premium formulations is redrawing supply geography toward Iowa fermentation clusters while compressing sweetener cost differentials across certification tiers. This input transition simultaneously elevates pricing power for domestic allulose producers and forces margin recalibration among legacy sugar alcohol-dependent brands.
Pricing Analysis
Cost-plus contracts indexed to runner peanut futures dominate raw material procurement, with Georgia and Texas drought cycles transmitting volatility directly into manufacturer cost structures. Pricing stratifies across Certified Ketogenic premium tiers, USDA organic mid-tiers, and conventional economy positioning, with certification stacking commanding 15-30% markups. Cost compression in the conventional tier is intensifying as private label operators exploit Walmart's shelf space leverage. Mass-market impulse buyers exhibit highest price sensitivity, while subscription-based fitness consumers demonstrate lowest elasticity.
Supply Chain Analysis
Inventory lead times for allulose inputs stretch 8-12 weeks due to fermentation capacity concentration in Iowa-based facilities. Runner peanut sourcing draws from Georgia, Texas, and Alabama growing regions, with organic segregation protocols adding handling complexity. Single-source vulnerability in domestic allulose production creates bottleneck exposure for keto-certified line scaling. Distribution runs through direct-to-consumer subscription platforms, natural retail channels, and mass-market supercenters simultaneously.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against almond and sunflower seed butter alternatives that threaten peanut-dominant positioning. Incumbents must navigate plant-based protein diversification while reinforcing ketogenic certification moats.
For Market Incumbents: Secure backward integration into Georgia and Texas peanut sourcing to insulate against drought-driven futures volatility. Lock in multi-year allulose supply agreements with Iowa fermentation facilities before capacity scarcity intensifies. Certified Ketogenic seal maintenance functions as the priority defensive lever against private label encroachment. For New Entrants and Emerging Players: Differentiate on diabetic-cohort targeting through pharmacy retail placement and healthcare practitioner recommendation networks. White-space concentrates in single-serve sachet formats for travel and hospitality channel recovery. Monk fruit-erythritol blending expertise enables conventional snack aisle penetration previously closed to alternative sweeteners. For Investors and Strategic Acquirers: FDA draft guidance on allulose caloric valuation reshapes the acquisition landscape toward reformulation-ready assets. Long-term viability favors mid-scale operators with captive organic peanut supply and ketogenic-certified production lines. Watch for FDA finalization on net carbohydrate standardization as the signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Ketogenic Seal Acquisition | Unlocks Whole Foods and Sprouts shelf allocation gatekeeping. |
| Allulose Supply Contracting | Secures Iowa fermentation capacity before bottleneck risk materializes. |
| Organic Peanut Sourcing Integration | Captures USDA certification premiums through Georgia farm-direct relationships. |
| Pharmacy Channel Expansion | Accesses diabetic cohort growth through healthcare practitioner networks. |
| Subscription Platform Buildout | Captures 40-60% lifetime value premiums over brick-and-mortar acquisition. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at natural retailers, co-manufacturing facility directors, and supply chain planners anchored the qualitative base. Primary interview insights combined with secondary validation from FDA guidance documents, USDA organic certification databases, Nielsen retail audit data, and runner peanut futures market records. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level assumptions.
Sensitivity analysis tested forecast robustness across alternative sweetener adoption curves and drought cycle scenarios over the projection horizon. Segmentation dimensions modeled include product format, certification tier, flavor profile, and channel structure alongside ketogenic adherence rate regional variation. CAGRs derived from trend extrapolation and substitution elasticity coefficients, with peanut input volatility and allulose supply concentration as key forecast inputs.
Material uncertainties — FDA finalization on net carbohydrate methodologies, Georgia-Texas drought frequency intensification, and allulose fermentation capacity expansion timing — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Asia-Pacific Snack Bar Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
Forti Flakes Market
Snacks
Low Calorie Dip Market
Snacks
Middle East Snack Bar Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Salty Puffed Snacks Market
Snacks
Australia Snack Bar Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Savory Snack Products Market
Snacks
United States Children's Snack Bar Market
Snacks
Asia Pacific Snack Food Market
Snacks
Spain Energy Bar Market
Snacks
Oat-Based Snacks Market