
 Red Berries Market | 2026-2036
Red Berries Market Size, Share, and Industry Trends Forecast 2026-2036
Red Berries Market Intelligence
Poland is fragmenting as new processing cooperatives challenge established export channels for frozen raspberries and currants. Ocean Spray Cranberries Inc. leverages its cooperative structure to sustain year-round supply contracts with North American juice bottlers. Berryhill Foods Inc. anchors its position through backward integration into controlled-atmosphere cold storage networks across Ontario and British Columbia. Dohler Group competes on formulation services, extending its ingredient portfolio into natural colorants derived from red berry anthocyanins.
Red berries encompass the edible fruits of Vaccinium, Rubus, Fragaria, and Prunus species, characterized by high polyphenol content, low pH ranges of 3.0 to 4.5, and perishability requiring rapid post-harvest cooling to 0-2°C for shelf-life extension. These fruits serve industrial buyers as natural flavoring systems, acidulants, and antioxidant carriers in processed goods. Strawberries occupy the largest volume share among product types, though cranberries command premium pricing through Ocean Spray's controlled supply architecture. The nutraceuticals end-user segment is outpacing food and beverage applications for anthocyanin extracts, while specialty stores and direct-to-processor channels capture margin pools that supermarkets cannot match due to their standardized procurement terms.
The FDA enforces pesticide residue tolerances under the Federal Food, Drug, and Cosmetic Act, while USDA organic certification shapes premium market access for cultivators converting to certified operations. EFSA evaluates novel health claims for berry polyphenols under the EU Nutrition and Health Claims Regulation, directly influencing nutraceutical formulation decisions. China's SAMR implements GB standards for imported frozen berries, creating compliance costs that filter supplier eligibility. Stakeholders must monitor how climate-driven harvest volatility in traditional growing zones reshapes contract structures and insurance requirements.
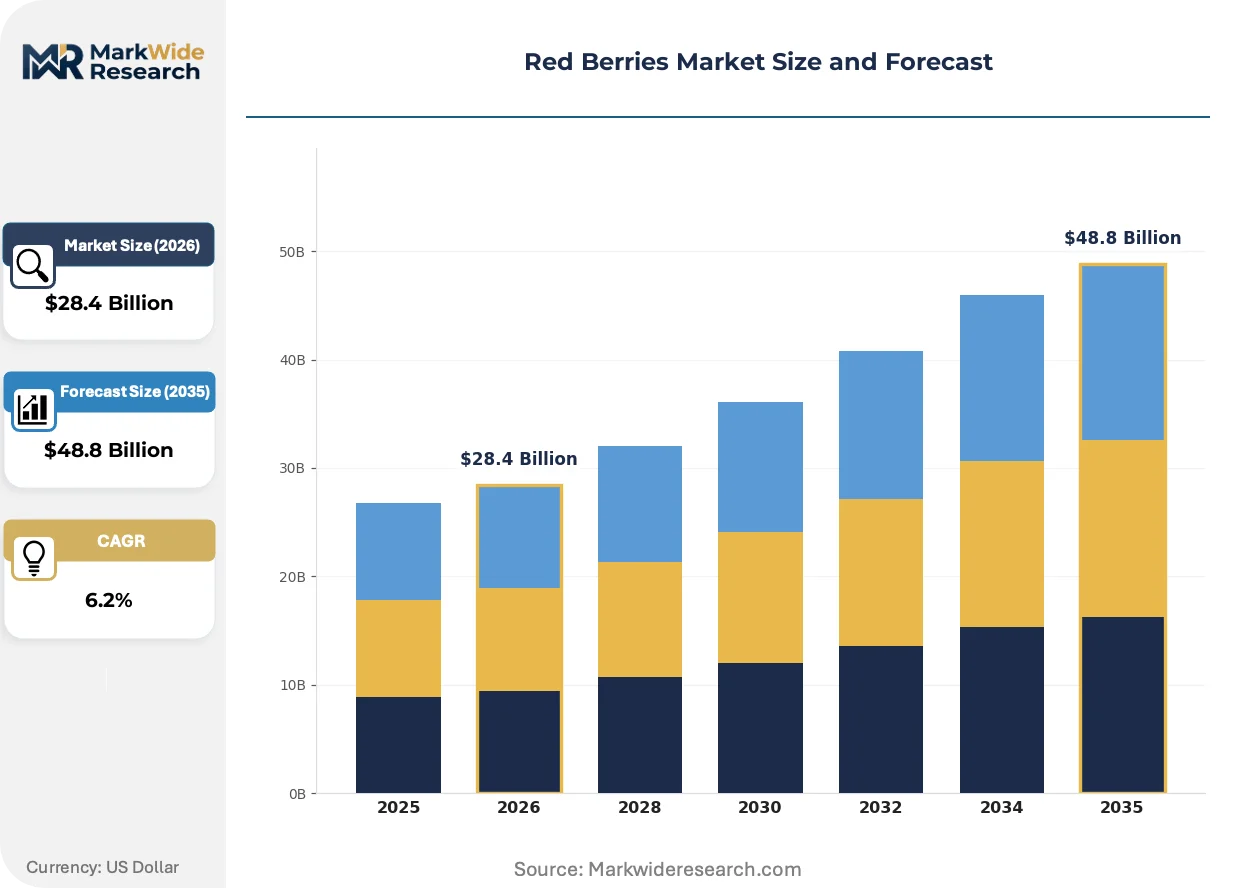
Market Dynamics
The EU's Farm to Fork Strategy is compressing residue limits and mandating organic conversion, forcing processors to rebuild procurement networks around certified cultivation clusters rather than conventional spot markets.
Growth Catalysts
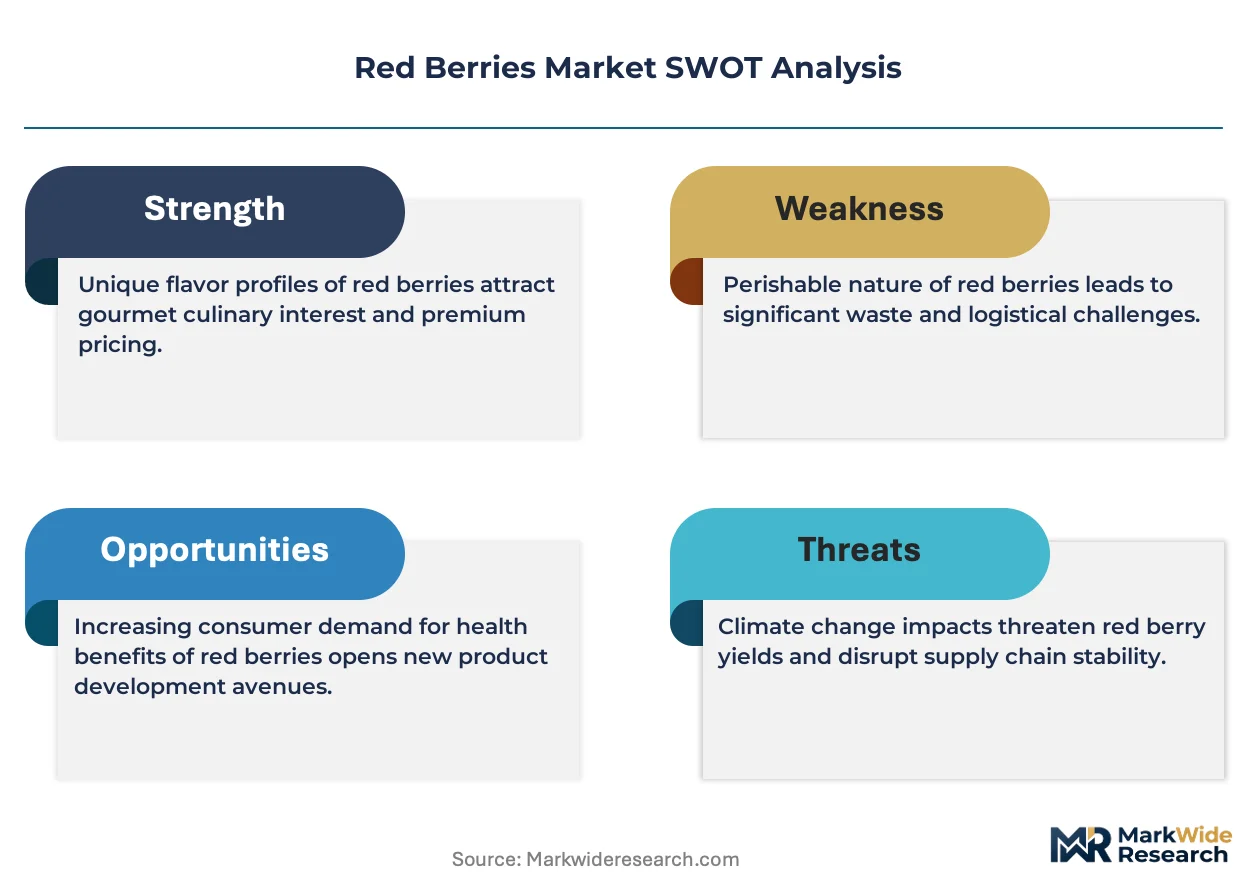
- Anthocyanin extraction demand:Nutraceutical formulators are expanding procurement of concentrated polyphenol inputs for functional supplement lines, pulling volume from traditional food channels.
- Controlled-atmosphere cold storage:Investment in 0-2°C rapid cooling infrastructure is extending post-harvest shelf life, reducing spoilage losses across Rubus and Vaccinium supply chains.
- Poland's cooperative expansion:New processing cooperatives in Masovian and Podlaskie voivodeships are fragmenting established export channels for frozen raspberries and currants.
Market Restraints
- Perishability cost structure:Mandatory 0-2°C cold chain maintenance from harvest through processing imposes energy-intensive logistics costs that spot-market suppliers cannot absorb.
- Serbian supply concentration:Sour cherry contract farming networks around Šumadija and Western Serbia create single-point vulnerability for European processors dependent on Balkan sourcing.
- GB standards compliance:China's SAMR import requirements for frozen berries filter supplier eligibility, excluding smaller cultivators lacking certification infrastructure.
Strategic Opportunities
- Freeze-dried functional beverages:Beverage manufacturers are formulating with concentrated red berry inputs, creating premium positioning for processors with spray-drying capabilities.
- Natural colorant substitution:EFSA evaluation of novel health claims under EU Nutrition and Health Claims Regulation is accelerating anthocyanin displacement of synthetic dyes in confectionery.
- Direct-to-processor channels:Specialty stores and farm-gate sales capture margin pools unavailable through supermarket standardized procurement terms.
Industry Challenges
- Organic conversion timelines:USDA organic certification requires three-year transition periods that strain grower cash flow before premium market access materializes.
- Climate volatility insurance:Harvest unpredictability in traditional growing zones is forcing contract renegotiation and weather-indexed coverage restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Red Berries Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $48.8 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strawberries, Raspberries, Cranberries, Cherries Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Specialty Stores End User: Food & Beverage Industry, Cosmetics Industry, Nutraceuticals, Household Consumers Application: Beverages, Desserts, Sauces, Snacks |
| Companies Covered | Berryhill Foods Inc., Ocean Spray Cranberries Inc., SunOpta Inc., Hortex Group, Dohler Group, Townsend Farms Inc., Northwest Berry Co-op, Milne Fruit Products Inc., KERR Concentrates Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Red Berries Market Strategic Shifts & Innovations
Digital traceability platforms and precision fermentation are compressing traditional supply architectures while regulatory tightening around residue limits reshapes cultivation geography.
Blockchain-enabled provenance tracking is virtualizing the documentation layer between Polish and Serbian cultivation clusters and European juice bottlers. Large processors are mandating farm-level data integration to satisfy EFSA audit requirements under tightened residue protocols. This virtualization is compressing the time between harvest verification and contract release, squeezing intermediaries who previously arbitraged information asymmetries.
REACH chemical safety evaluations are extending scrutiny to post-harvest treatments and processing aids used in anthocyanin extraction facilities. Industrial buyers now demand full substance disclosure across the extraction solvent chain, filtering supplier pools to those with compliant chemical management systems. German and Dutch formulators are most affected, accelerating substitution toward supercritical CO2 extraction methods.
Buyer concentration among North American juice bottlers is shortening contract renewal cycles from annual to quarterly terms, forcing Ocean Spray's cooperative structure toward more flexible volume commitments. Direct sourcing relationships are displacing traditional broker networks in cranberry procurement. This pattern is most visible across Wisconsin and Massachusetts growing regions where processor-owned receiving stations now dominate volume aggregation.
Red Berries Market Segmentation
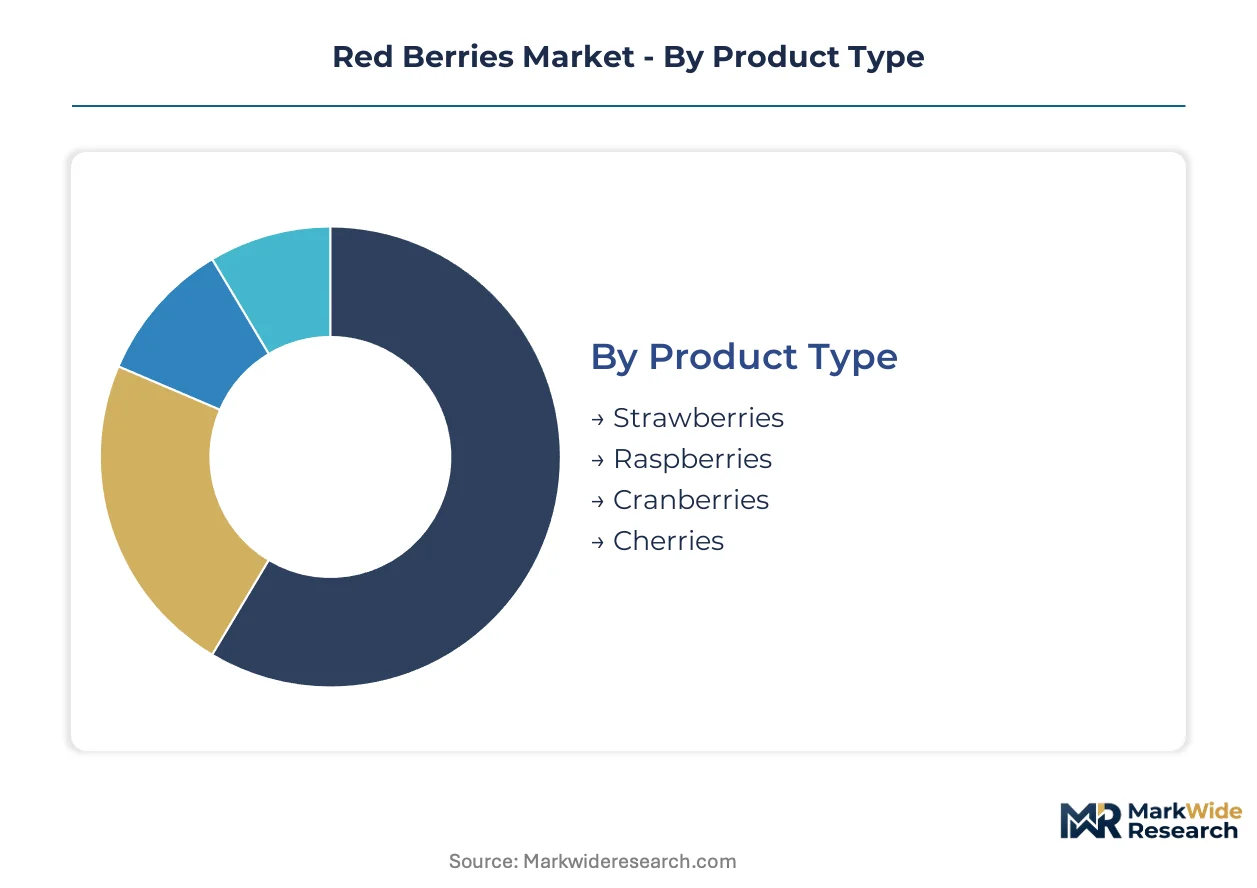
Red berry procurement patterns diverge sharply across product forms and buyer types, with industrial processors demanding frozen and concentrated inputs while retail channels compete on freshness windows and provenance credentials.
Product Type:
Post-harvest service intensity varies enormously by berry physiology—perishability dictates cooling infrastructure investment and contract structure rigidity.
- Strawberries:These fruits exhibit the highest respiration rates among temperate berries, demanding harvest-to-cooling intervals under four hours to prevent quality degradation. Volume concentrates in California's Central Valley and Spain's Huelva province, where field-adjacent processing stations enable just-in-time freezing for industrial buyers. Strawberries hold the largest share; momentum sits with cranberries.
- Cranberries:Vaccinium macrocarpon's unique buoyancy-harvesting method and extended cold-storage stability create cooperative-controlled supply architectures. Wisconsin and Massachusetts bogs supply North American juice bottlers through Ocean Spray's volume-pooling contracts, insulating growers from spot-price volatility.
- Raspberries:Rubus idaeus fruits collapse structurally within 48 hours without rapid cooling, concentrating procurement around Polish and Serbian processing cooperatives with captive freezing capacity.
- Cherries:Prunus avium and Prunus cerasus varieties split between fresh export channels and industrial sour-cherry concentrate production in Šumadija, Serbia.
Strawberries dominate volume throughput; cranberries command the steepest expansion trajectory in value-added extraction applications.
Distribution Channel:
Channel selection determines margin capture, with direct routes bypassing supermarket procurement standardization.
- Supermarkets:These retailers impose strict size-grading and residue documentation, filtering supplier eligibility to certified operations with traceability infrastructure. Chains in Germany and France now mandate blockchain-enabled provenance for organic lines.
- Specialty Stores:Independent retailers capture premium positioning through cultivar-specific sourcing and shortened supply chains, particularly for heritage raspberry varieties in Poland.
- Online Retail:Direct-to-consumer platforms compress delivery windows to under 24 hours for fresh berries, requiring urban cold-hub networks in London, Paris, and Berlin.
- Farmers' Markets:These channels enable price discovery outside commodity benchmarks for small-scale growers with cultivar differentiation.
Supermarkets retain volume dominance; specialty stores are gaining share fastest in premium organic segments.
End User:
Buyer sophistication shapes specification stringency, with nutraceutical extractors imposing the most demanding purity protocols.
- Food & Beverage Industry:Processors formulate with frozen purees and concentrated anthocyanin extracts for natural colorant and acidulant functions. German and Dutch confectionery manufacturers drive substitution of synthetic dyes under EFSA evaluation timelines.
- Nutraceuticals:Supplement formulators procure standardized polyphenol extracts with documented bioavailability, requiring supercritical CO2 extraction capabilities and REACH-compliant solvent chains.
- Cosmetics Industry:Skincare manufacturers incorporate berry seed oils and antioxidant fractions, with French formulators leading procurement of upcycled processing byproducts.
- Household Consumers:Fresh consumption concentrates in summer harvest windows, with import dependency rising for counter-seasonal supply.
Food and beverage commands current volume; nutraceuticals show the sharpest demand acceleration.
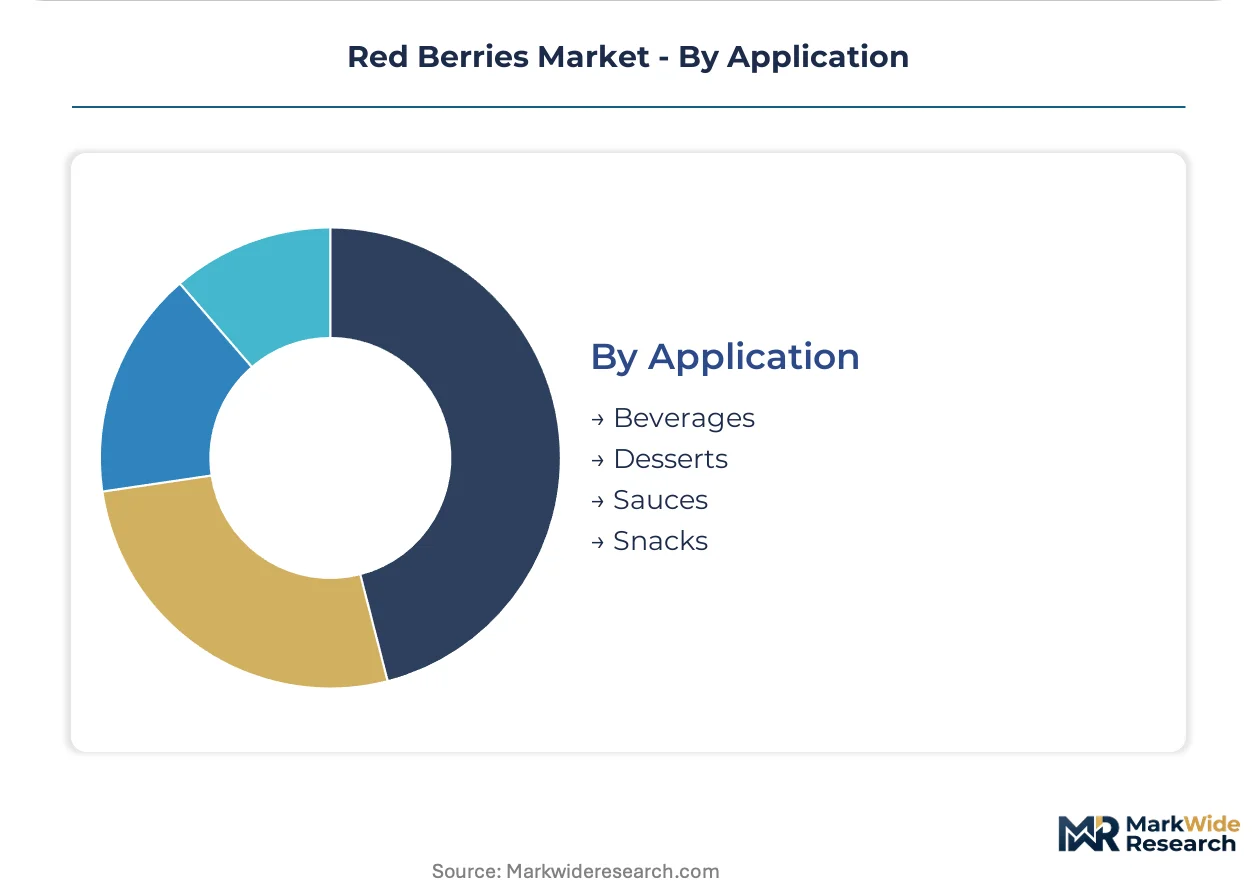
Application:
Formulation requirements dictate berry form—whole, pureed, dried, or extracted—driving processor specialization.
- Beverages:Juice bottlers blend cranberry and cherry concentrates for tartness profiles, with functional beverage startups incorporating whole-berry powders for fiber retention.
- Desserts:Frozen dairy and bakery applications demand IQF strawberries and raspberries with intact cell structure for texture preservation.
- Sauces:Cooked applications tolerate lower-grade fruit, enabling utilization of mechanically harvested berries with minor blemish.
- Snacks:Freeze-dried whole berries command shelf-stable positioning in trail mixes and cereal inclusions, with spray-drying capabilities differentiating processor competitiveness.
Beverages anchor industrial demand; snacks are expanding most quickly in functional positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: North American buyers prioritize year-round juice concentrate supply through cooperative structures, while European procurement concentrates on frozen IQF inputs for industrial processing, and Asian markets emphasize import compliance for freeze-dried nutraceutical applications.
United States
Wisconsin and Massachusetts cranberry bogs anchor North American concentrate production through cooperative volume-pooling arrangements. The FDA enforces pesticide residue tolerances under the Federal Food, Drug, and Cosmetic Act, shaping grower compliance investment. Ocean Spray Cranberries Inc. maintains controlled supply architectures with processor-owned receiving stations dominating volume aggregation across these growing regions.
Poland
Masovian and Podlaskie voivodeships drive frozen raspberry and currant exports through expanding processing cooperative networks. The EU's Farm to Fork Strategy under the European Green Deal tightens residue limits and mandates organic conversion timelines. New cooperatives fragment established export channels, challenging legacy intermediaries who previously arbitraged information asymmetries between growers and European juice bottlers.
Serbia
Šumadija and Western Serbia concentrate sour cherry contract farming for European industrial processors. EFSA evaluates novel health claims for berry polyphenols under the EU Nutrition and Health Claims Regulation, directly influencing regional formulation decisions. Processing infrastructure scaling around these cultivation clusters creates single-point vulnerability for Balkan-dependent supply chains.
China
Import demand for freeze-dried berry inputs accelerates as domestic nutraceutical formulators expand functional supplement lines. SAMR implements GB standards for imported frozen berries, filtering supplier eligibility through certification infrastructure requirements. Compliance costs exclude smaller cultivators, concentrating procurement relationships with processors possessing documented chemical management systems.
Canada
Ontario and British Columbia host controlled-atmosphere cold storage networks supporting year-round supply continuity. Health Canada and PMRA regulate pesticide residues and organic certification, shaping premium market access for converting operations. Berryhill Foods Inc. anchors regional positioning through backward integration into these storage and distribution infrastructures.
Red Berries Market Key Industry Players
Capability concentration sits with extraction and formulation specialists; scale advantage sits with cooperative-structured volume aggregators. The competitive terrain splits between processors commanding spray-drying and supercritical CO2 extraction technologies, and entities controlling cold-chain infrastructure for perishable throughput. Three archetypes dominate: cooperative-owned supply pools, vertically integrated processor-grower hybrids, and formulation-service ingredient houses. Capacity expansion in controlled-atmosphere storage and M&A targeting anthocyanin extraction capabilities represent the dominant competitive moves reshaping participant positioning.
Within the cooperative-structured tier, Ocean Spray Cranberries Inc. and Northwest Berry Co-op exemplify volume-pooling architectures that insulate growers from spot-price volatility. Among formulation-focused specialists, Dohler Group occupies a position emphasizing natural colorant and flavor system services. These entities represent contrasting strategic anchors: one prioritizing supply security through member-owned production bases, the other competing on technical formulation capabilities and REACH-compliant extraction methods.
| Leading Market Players |
|---|
| Berryhill Foods Inc. |
| Ocean Spray Cranberries Inc. |
| SunOpta Inc. |
| Hortex Group |
| Dohler Group |
| Townsend Farms Inc. |
| Northwest Berry Co-op |
| Milne Fruit Products Inc. |
| KERR Concentrates Inc. |
| Others |
Cost & Logistics Intelligence
Polish and Serbian cultivation clusters for raspberries and sour cherries concentrate upstream supply, feeding margin pools downstream to processors with captive freezing infrastructure and EFSA-compliant extraction capabilities. Contract structures linking these growing regions to German and Dutch formulators capture value that spot-market intermediaries cannot access.
Pricing Analysis
Long-term offtake agreements dominate procurement between Ocean Spray's cooperative members and North American juice bottlers, insulating growers from spot volatility. Price differentiation rests on organic certification tier and controlled-atmosphere cold storage access, with certified operations commanding substantial premiums. Cost compression in conventional frozen berry tiers is intensifying because energy-intensive 0-2°C logistics erode thin margins. Industrial nutraceutical buyers show least price sensitivity due to bioavailability specification stringency, while commodity food processors face acute margin pressure.
Supply Chain Analysis
Upstream feedstock for anthocyanin extraction draws from Wisconsin and Massachusetts cranberry bogs, Poland's Masovian raspberry cooperatives, and Serbia's Šumadija sour cherry networks. Critical inputs include Vaccinium and Rubus cultivars, supercritical CO2 extraction solvents, and REACH-compliant processing aids. Single-source vulnerability concentrates in Serbian sour cherry contract farming, where processing infrastructure scaling creates Balkan-dependent bottlenecks. Distribution runs through processor-owned receiving stations and cooperative volume-pooling arrangements rather than traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision-fermented polyphenol alternatives and synthetic colorant cost advantages, requiring defensive repositioning around provenance credentials and extraction technology.
For Market Incumbents: Insulate cooperative supply architectures by deepening backward integration into controlled-atmosphere storage across Ontario and British Columbia. Accelerate supercritical CO2 extraction capability investments to displace solvent-dependent competitors facing REACH scrutiny. Defend against precision-fermented substitutes by emphasizing blockchain-enabled provenance for EFSA audit compliance.
For New Entrants and Emerging Players: China's nutraceutical import channels show underpenetration by mid-tier processors lacking GB standards certification infrastructure. Target freeze-dried functional beverage formulations where spray-drying capability gaps exist among domestic Chinese suppliers. Establish direct sourcing relationships with Polish heritage raspberry cultivators bypassing fragmented cooperative intermediaries.
For Investors and Strategic Acquirers: Capital is best deployed toward extraction-technology specialists possessing REACH-compliant solvent chains and supercritical CO2 capabilities. Long-term viability across the projection horizon favors processors with demonstrated EFSA health claim submission experience. Monitor EFSA novel health claim evaluation timelines as inflection signals for anthocyanin extract demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Storage | Berryhill Foods anchors Ontario and British Columbia networks for year-round supply continuity. |
| Supercritical CO2 Extraction Scale-Up | German and Dutch formulators substitute REACH-scrutinized solvent methods under ECHA pressure. |
| Blockchain Provenance Implementation | Polish cooperatives satisfy tightened EFSA residue protocols and compress contract release cycles. |
| Organic Certification Conversion | USDA three-year transition timelines strain grower cash flow before premium market access materializes. |
| Direct-to-Processor Channel Development | Specialty stores capture margin pools unavailable through supermarket standardized procurement terms. |
Research Approach
A spread of perspectives from processing cooperative managers, nutraceutical formulators, cold storage operators, and EFSA regulatory affairs specialists converged on the working assumptions. Primary fieldwork with Polish and Serbian cultivation clusters combined with secondary validation from customs trade data, EU Farm to Fork Strategy documentation, FDA pesticide tolerance filings, and SEC processor disclosures. Bottom-up volume aggregation across berry species and top-down macroeconomic triangulation anchored the analytical framework.
Demand-supply-balance modeling across the analysis window incorporated product form segmentation, end-user specification tiers, and regional regulatory cluster differentiation. CAGRs derived from historical trade flow trajectories and projected cultivation area expansion under organic conversion mandates. Modeled inputs included climate volatility indices for harvest forecasting and EFSA health claim evaluation timelines for nutraceutical demand elasticity.
Practitioners should monitor EU residue limit compression schedules and precision fermentation technology cost curves for early signals of forecast revision. Climate-driven harvest unpredictability in traditional growing zones and REACH chemical safety evaluation extensions for processing aids represent specific risk factors. Cross-checking against EFSA novel health claim registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Global Jalapeno Pepper Market