
 Forti Flakes Market | 2026-2036
Forti Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Forti Flakes Market Analytics
Health-conscious consumers is rebalancing the Forti Flakes market as athlete-focused formulations gain shelf space against traditional family positioning. Nestlé S.A. leverages its nutrition science infrastructure to anchor premium fortified lines. WK Kellogg Co sustains manufacturing scale across North American production networks. General Mills Inc. differentiates through gluten-free specialization in health food channels.
Forti Flakes denote breakfast cereal products with added micronutrients, typically iron, B vitamins, and folic acid, manufactured through extrusion and subsequent coating or injection of nutrient slurries to achieve standardized fortification levels. These products serve commercial and retail markets seeking convenient nutrient delivery through daily consumption routines. The high-protein segment leads volume contribution as athletic and aging demographics prioritize muscle maintenance formulations. Organic positioning commands margin premiums despite constrained raw material availability. Online retailers represent the fastest-growing distribution vector as subscription models lock in recurring purchases.
The FDA governs nutrient content claims and fortification ceilings under 21 CFR 101, while the USDA Organic seal shapes premium tier access, and the EU Health Claims Regulation limits permissible marketing language across Atlantic trade corridors. Compliance with divergent trans-Atlantic standards raises reformulation costs for multinational portfolios. Stakeholders must monitor evolving micronutrient ceilings and clean-label certification requirements as regulatory fragmentation intensifies.
Market Dynamics
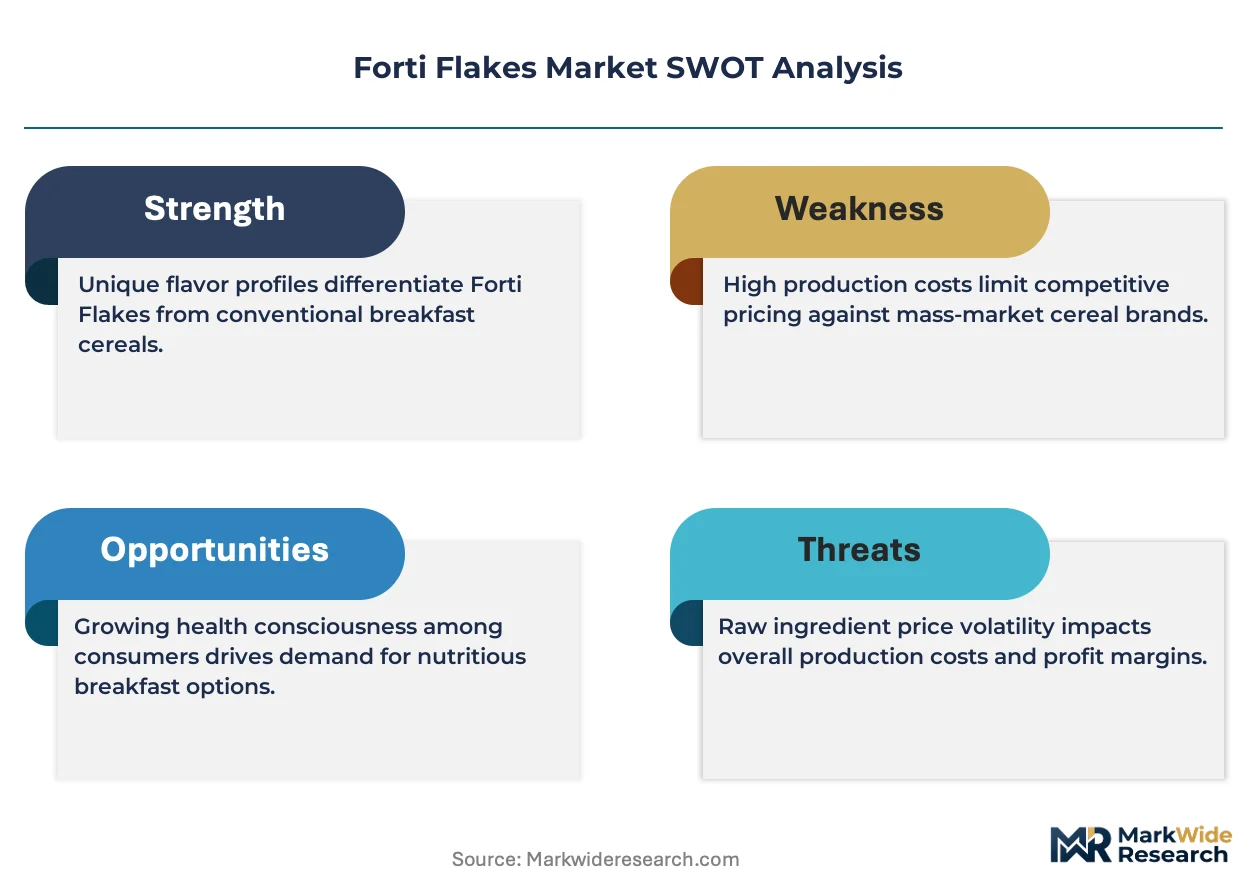
Clean-label fortification is restructuring competitive positioning as micronutrient delivery shifts from synthetic additives to bioavailable whole-food matrices, forcing reformulation across extrusion and coating infrastructure.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Standardized permissible marketing language reduces compliance fragmentation, enabling cross-border portfolio scaling for fortified cereal lines.
- Athletic nutrition demand:High-protein breakfast formulations capture recurring purchases from muscle-maintenance-focused demographics in Germany and the United States.
- Extrusion technology advancement:Precision nutrient injection systems improve bioavailability retention during thermal processing, expanding functional claim credibility.
Market Restraints
- Organic raw material scarcity:Certified grain supply concentrates in limited agricultural regions, constraining premium tier volume expansion.
- FDA fortification ceilings:21 CFR 101 micronutrient caps prevent super-fortification claims, compressing differentiation space against supplement alternatives.
- Refrigerated dairy alternatives:Greek yogurt and protein smoothies capture morning protein occasions, displacing shelf-stable cereal frequency.
Strategic Opportunities
- Subscription commerce models:Direct-to-consumer platforms lock recurring revenue through personalized fortification blends and auto-replenishment logistics.
- Aging demographic targeting:Bone-health and cognitive-function formulations address underpenetrated senior nutrition segments in Japan and Italy.
- USDA Organic certification tailwind:Premium positioning through dual organic-fortified claims commands shelf-space allocation in natural retail channels.
Industry Challenges
- Clean-label compliance timelines:Synthetic vitamin replacement with whole-food sources extends R&D cycles by 18-24 months.
- Legacy extrusion asset retrofitting:Temperature-sensitive nutrient coating requires capital-intensive line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forti Flakes Market |
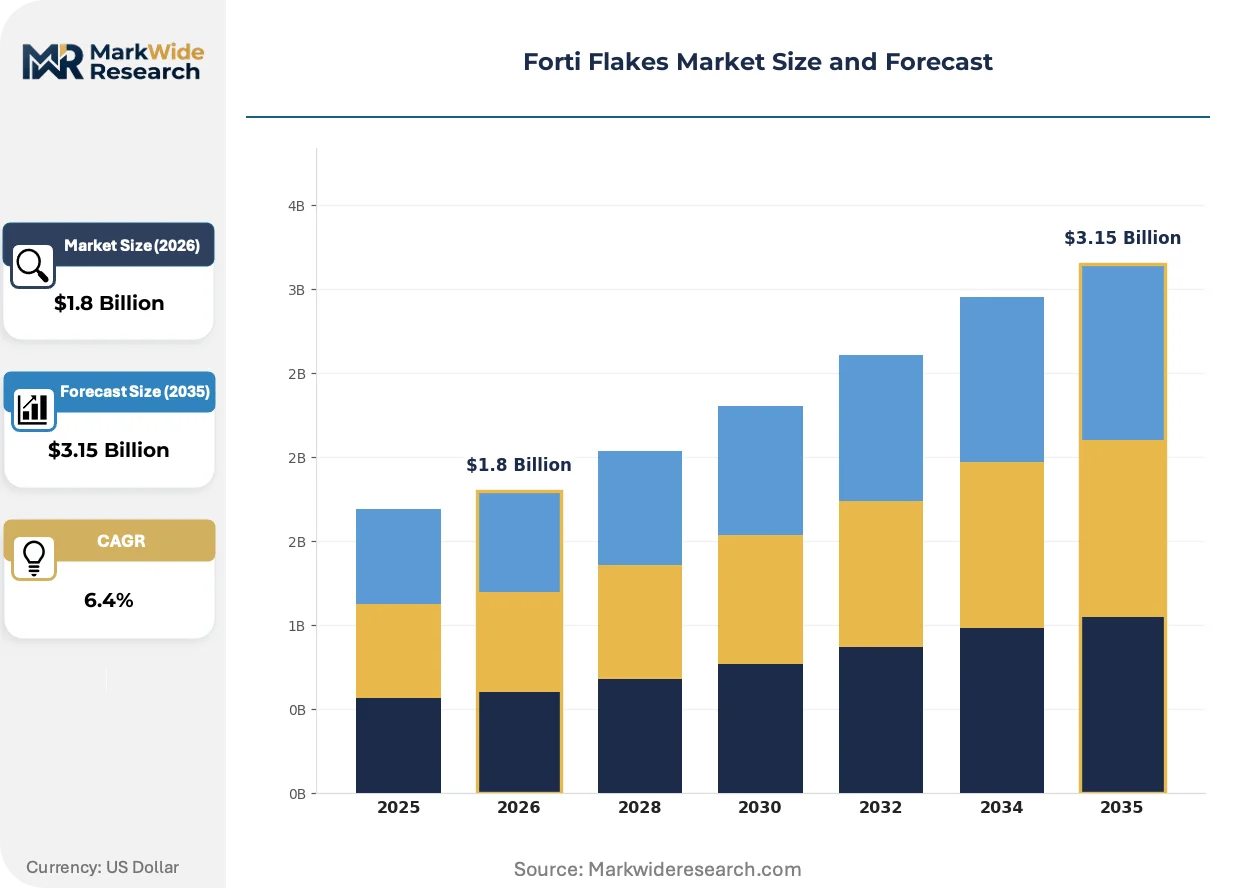
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, High-Protein, Organic, Fortified End User: Health-Conscious Consumers, Athletes, Families, Seniors Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Direct Sales Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | Nestlé S.A., WK Kellogg Co, General Mills Inc., PepsiCo Inc., Post Holdings Inc., Weetabix Limited, Quaker Oats Company, Conagra Brands Inc., Hain Celestial Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forti Flakes Market Evolving Landscape
Active fortification science is expanding beyond traditional micronutrient coverage into targeted metabolic health applications, reshaping how breakfast cereals compete with functional foods and supplements.
Microencapsulation technology is expanding into probiotic-fortified flake matrices, protecting live cultures through extrusion heat and gastric transit. Sports nutrition brands in Germany and Australia are piloting these formulations for gut-health positioning. This capability is expanding into premium private-label contracts previously reserved for pharmaceutical-grade supplements.
REACH chemical safety assessments are tightening scrutiny on synthetic vitamin precursors, compelling European manufacturers to document supply chain toxicity profiles. The regulation forces reformulation roadmaps for B vitamin complexes and iron compounds. German producers face the steepest compliance costs due to their concentration of organic-certified lines.
Subscription-based replenishment is displacing traditional retail stocking patterns among health-conscious households in the United States and United Kingdom. Direct channels now capture recurring purchases through personalized nutrient profiling and flexible delivery cadences. Athletic consumers in metropolitan clusters show highest retention rates for protein-fortified subscription tiers.
Forti Flakes Market Segmentation
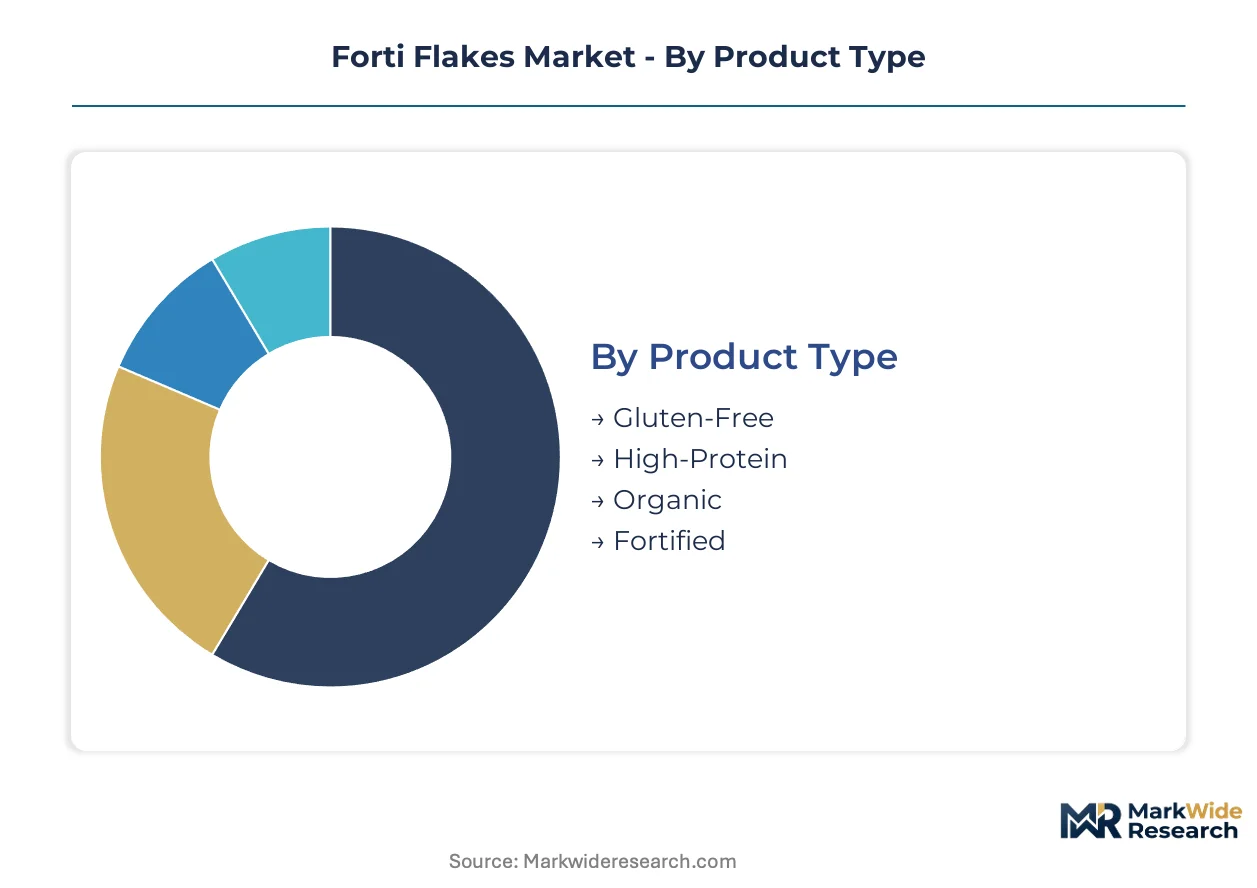
Forti Flakes manufacturers align product architectures with distinct consumption occasions and channel economics. Segmentation reveals where extrusion technology investments concentrate and which nutrient delivery formats command shelf-space premiums.
Product Type:
Reformulation cycles accelerate as clean-label mandates displace synthetic fortification across extrusion lines.
- High-Protein:Extruded grain matrices incorporate whey, pea, or collagen isolates to achieve 15-20g protein per serving. Athletes in Germany and the United States drive recurring purchases for muscle maintenance formulations.
- Organic:USDA Organic or EU Organic certification restricts synthetic additive use, forcing whole-food nutrient sourcing from certified grain suppliers. Constrained raw material availability limits volume scaling despite margin premiums.
- Gluten-Free:Sorghum, rice, and certified oat bases replace wheat in extrusion recipes.
- Fortified:Standard micronutrient injection delivers iron, B vitamins, and folic acid through coating slurries.
High-Protein sits at the top of the volume ranking, with Organic climbing the fastest.
End User:
Customer archetypes diverge sharply on price sensitivity, nutrient specificity, and purchase frequency.
- Athletes:Performance-oriented consumers prioritize protein density, glycemic control, and batch-tested certification for banned substances. Subscription retention runs highest among metropolitan fitness clusters in the United States.
- Health-Conscious Consumers:Clean-label scrutiny drives ingredient list analysis and rejection of artificial colors or synthetic vitamins. REACH assessments on B vitamin precursors intensify compliance costs for European brands serving this segment.
- Families:Multi-serve packaging and child-acceptable palatability balance fortification density with taste acceptance.
- Seniors:Bone-health and cognitive-function formulations remain underpenetrated despite expanding demographic weight in Japan and Italy.
Athletes generate the highest per-capita revenue, with Seniors expanding most quickly as manufacturers target age-specific formulations.
Distribution Channel:
Channel selection determines margin structure, data capture depth, and replenishment cadence.
- Online Retailers:Direct-to-consumer platforms enable personalized fortification blends, auto-replenishment logistics, and subscription lock-in. Athletic consumers show strongest retention for protein-fortified tiers.
- Supermarkets:Mass-market penetration requires slotting fee negotiations and promotional calendar alignment.
- Health Food Stores:Natural retail channels allocate premium shelf space to dual organic-fortified claims.
- Direct Sales:B2B institutional contracts serve healthcare and corporate wellness programs.
Supermarkets retain the largest transaction volume, with Online Retailers gaining share fastest through subscription models.
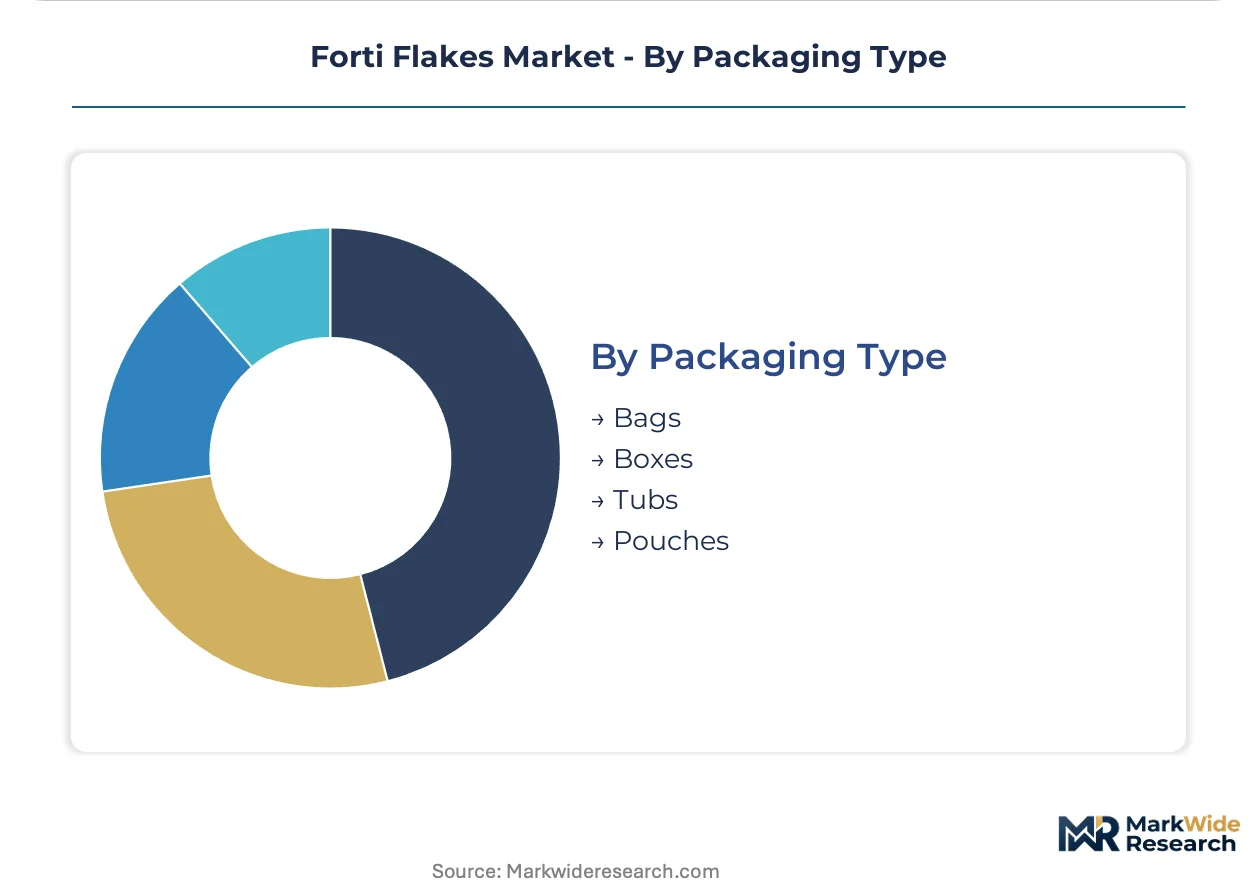
Packaging Type:
Packaging format selection balances shelf stability, portion control, and sustainability positioning.
- Boxes:Paperboard secondary packaging with inner liner bags dominates retail shelf presentation and supports brand billboard effects.
- Bags:Flexible film structures reduce material cost and shipping cube for value-tier positioning.
- Pouches:Single-serve or small-format flexible packaging serves on-the-go consumption and trial-size distribution.
- Tubs:Rigid plastic containers with resealable lids target bulk purchase and extended freshness for family households.
Boxes maintain category-standard volume leadership, with Pouches showing steepest expansion trajectory in convenience-oriented channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting Forti Flakes manufacturing toward jurisdictions with harmonized fortification standards, as divergent micronutrient ceilings between the FDA and EFSA inflate reformulation costs for multinational portfolios.
United States
Athletic nutrition demand and subscription commerce penetration concentrate in metropolitan fitness clusters across California and Texas. The FDA governs nutrient content claims under 21 CFR 101, capping fortification levels that constrain super-fortification positioning. Chicago anchors Midwest production networks where WK Kellogg Co maintains extrusion scale for mass-market distribution.
Germany
Functional breakfast adoption runs highest among mature European economies, with health-conscious consumers driving clean-label scrutiny. REACH chemical safety assessments tighten scrutiny on synthetic vitamin precursors, compelling documentation of supply chain toxicity profiles for B vitamin complexes. Bavaria concentrates organic-certified production lines facing steepest compliance costs.
Japan
Aging demographic weight creates underpenetrated opportunity for bone-health and cognitive-function formulations targeting senior nutrition segments. METI industrial standards shape manufacturing quality benchmarks for functional food exports. The Kanto region around Tokyo hosts precision extrusion technology providers serving probiotic-fortified flake development.
United Kingdom
Direct-to-consumer subscription models capture recurring purchases through personalized nutrient profiling and flexible delivery cadences. Post-Brexit regulatory divergence from EU Health Claims Regulation creates dual compliance burdens for cross-border portfolio scaling. London anchors health food channel distribution where dual organic-fortified claims command premium shelf-space allocation.
Australia
Sports nutrition brands pilot microencapsulation technology for gut-health positioning in probiotic-fortified matrices. The TGA therapeutic goods framework creates distinct pathways for functional claim substantiation compared to food-standard jurisdictions. Melbourne and Sydney concentrate athletic consumer clusters showing highest retention rates for protein-fortified subscription tiers.
Forti Flakes Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents rebalance between mass-market scale and premium health positioning. The vendor base stratifies across three tiers: multinational nutrition conglomerates with integrated R&D infrastructure, mid-cap specialists commanding organic certification premiums, and private-label manufacturers serving retail channel economics. Two strategic archetypes predominate: science-anchored premium fortification and manufacturing-scale value delivery. Competitive intensity concentrates on M&A activity targeting clean-label capability and geographic expansion into underpenetrated senior nutrition segments.
Within the multinational tier, Nestlé S.A. and General Mills Inc. exemplify divergent strategic anchors. Nestlé S.A. occupies a position representing nutrition science infrastructure integration, while General Mills Inc. exemplifies gluten-free specialization for health food channel differentiation. WK Kellogg Co sits within the manufacturing-scale archetype, anchoring North American production network coverage. These three entities collectively represent the competitive spectrum from premium fortification credibility to mass-market distribution efficiency.
| Leading Market Players |
|---|
| Nestlé S.A. |
| WK Kellogg Co |
| General Mills Inc. |
| PepsiCo Inc. |
| Post Holdings Inc. |
| Weetabix Limited |
| Quaker Oats Company |
| Conagra Brands Inc. |
| Hain Celestial Group Inc. |
| Others |
Value Network & Pricing Analysis
Precision extrusion engineers in Bavaria and Chicago concentrate clean-label fortification expertise, and labor-cost differentials between these engineering clusters widen spreads between premium organic tiers and mass-market standard lines. Buyers in Germany absorb higher shelf prices for REACH-compliant formulations while value-tier competition compresses margins in North American private-label contracts.
Pricing Analysis
Retailer slotting fees and promotional allowances consume margin layers before products reach household pantries. Three-tier pricing structure across premium organic, standard fortified, and economy private-label levels segments buyer archetypes by certification sensitivity and channel access. Pricing pressure stems from refrigerated dairy alternatives capturing morning protein occasions in metropolitan United States markets. Families show highest price elasticity, while athletic consumers in subscription tiers accept premium positioning for batch-tested certification.
Supply Chain Analysis
Dual-sourcing mandates from major retailers require qualified backup suppliers for organic grain and microencapsulated nutrient inputs. Certified organic wheat and oat supply concentrates in Germany, France, and Canada, while synthetic vitamin precursors draw from Chinese and Indian chemical manufacturers. Single-source vulnerability runs through European organic grain cooperatives facing climate yield variability. Distribution runs through supermarket central warehouses and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forti Flakes represents a late-cycle quality story as demand tilts toward clean-label formulations commanding shelf-space premiums over legacy synthetic-fortified lines.
For Market Incumbents: Deploy microencapsulation R&D partnerships to defend against probiotic-fortified entrants from pharmaceutical-grade supplement manufacturers. Nestlé S.A. and General Mills Inc. anchor positions through nutrition science infrastructure and gluten-free channel specialization respectively. Capacity retrofitting in existing extrusion assets preserves scale economies against greenfield organic-certified competitors. For New Entrants and Emerging Players: Senior nutrition segments in Japan and Italy remain underserved by age-specific bone-health and cognitive-function formulations. White-space concentration in probiotic-fortified matrices allows pilot-scale producers to capture gut-health positioning before multinational scale-up. Direct-to-consumer subscription platforms offer lowest customer acquisition cost for athletic demographic penetration. For Investors and Strategic Acquirers: Mid-cap nutrition conglomerates are the most active acquirer in this space, targeting clean-label capability gaps in their portfolio architectures. Five-to-ten year viability hinges on synthetic-to-whole-food fortification transition execution. Watch REACH enforcement intensity on B vitamin precursors as inflection indicator for European manufacturing cost structure reset.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Probiotic survival through extrusion heat opens gut-health positioning against supplement alternatives. |
| USDA Organic Certification Investment | Dual organic-fortified claims command premium shelf allocation in natural retail channels. |
| Subscription Commerce Platform Buildout | Auto-replenishment logistics lock recurring revenue from athletic metropolitan clusters. |
| REACH Compliance Documentation System | B vitamin precursor toxicity profiling satisfies tightening ECHA scrutiny on synthetic inputs. |
| Senior Nutrition Formulation Development | Bone-health and cognitive-function products address underpenetrated aging demographics in Japan. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Brand managers at WK Kellogg Co and General Mills Inc., category buyers at Whole Foods Market and Tesco, supply planners at organic grain cooperatives, and extrusion technology providers in Bavaria contributed interview data. FDA 21 CFR 101 filings, EFSA health claim registers, USDA Organic certification databases, and Nielsen retail audit data anchored secondary sourcing. Bottom-up volume builds by segment reconciled against top-down market sizing.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and packaging format, with regulatory cluster overlay for trans-Atlantic compliance cost differentials. CAGRs derived from historical trajectory analysis adjusted for clean-label transition acceleration and subscription commerce penetration curves. Extrusion technology advancement timelines and organic raw material availability constraints fed scenario-weighted outputs.
Underlying measurement precision varies by segment; high-protein and online retail channels carry tighter precision than emerging senior nutrition categories. Forecasts reflect assumptions on REACH enforcement trajectory and FDA fortification ceiling stability. Deviation in organic grain yield volatility or probiotic microencapsulation cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Global Vegetable Chips Market
Snacks
North America Energy Bar Market
Snacks
Organic Snacks Market
Snacks
Middle East Snack Bar Market
Snacks
Low Calorie Cookies Market
Snacks
Potato Chips Market
Snacks
Oat-Based Snacks Market
Snacks
Germany Energy Bar Market
Snacks
Snack Bar Market
Snacks
Roasted Corn Market
Snacks
Europe Cereal Bar Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Europe Snacks Food Market
Snacks
Low Calorie Granola Market
Snacks
United States Popcorn Market
Snacks
India Snack Bar Market