
 Pea Protein Market | 2026-2036
Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Protein Market Analysis
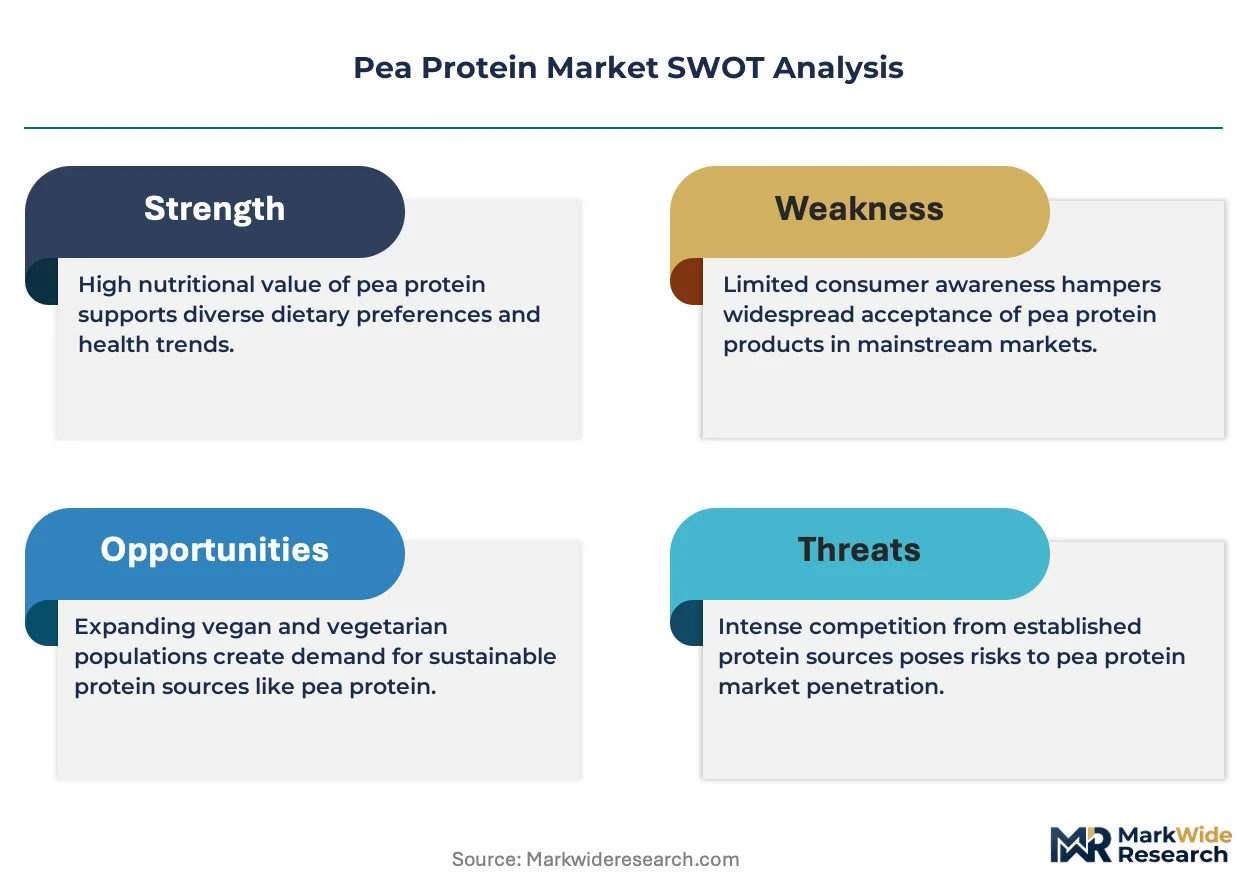
A capital-intensity divergence between wet-fractionation and dry-fractionation capabilities is redrawing competitive boundaries in pea protein supply. Roquette Frères leverages its decades of extrusion expertise to sustain premium isolate yields from European yellow pea varieties. PURIS anchors North American production through backward integration into organic pea farming across the Upper Midwest. Cargill competes on global procurement scale, extending its grain-trading infrastructure into protein fractionation.
Pea protein denotes the globulin-rich extract obtained from Pisum sativum through aqueous or dry separation, typically yielding 80-90% protein content in isolate form with balanced essential amino acid profiles for human nutrition. The ingredient serves primarily as a functional emulsifier and nutritional fortifier in plant-based meat analogues, dairy alternatives, and performance nutrition products. Isolate commands the highest margin pool among product types due to its superior solubility and neutral flavor profile, while textured formats are expanding fastest as meat-alternative brands demand fibrous mouthfeel solutions. Application demand concentrates in food and beverage, though dietary supplements represent the fastest-growing outlet as brands reformulate away from dairy and soy allergens.
Regulatory frameworks including FDA GRAS determinations, EFSA novel food approvals, and EU REACH compliance for processing aids govern market access and product labeling claims across major demand centers. These standards shape formulation choices, with EFSA's protein quality scoring methods directly influencing European product positioning and export eligibility. Stakeholders must monitor evolving allergen labeling thresholds and carbon-accounting disclosure requirements that will determine which fractionation technologies achieve preferred procurement status.
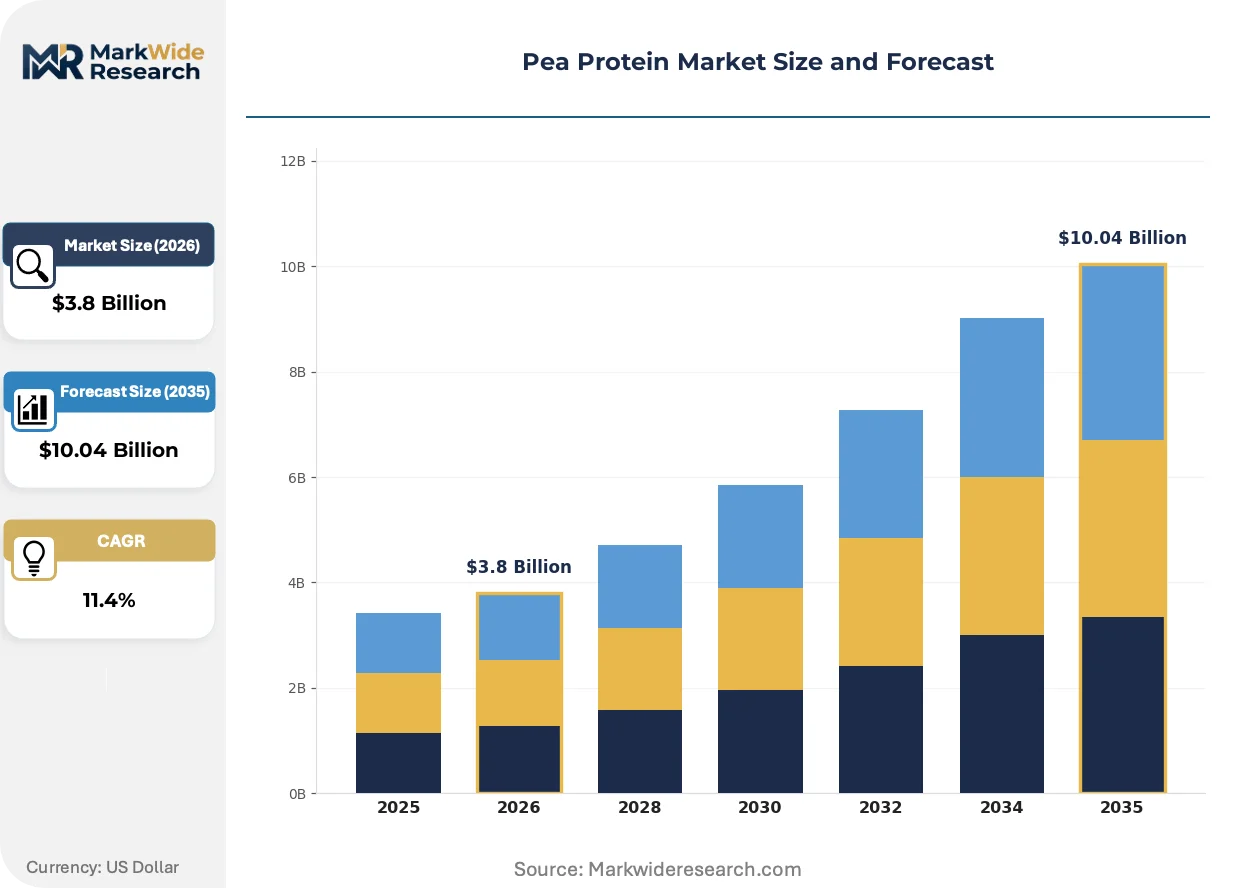
Market Dynamics
Fractionation technology divergence between wet and dry processing methods is redrawing competitive boundaries in pea protein supply, as capital requirements for aqueous extraction isolate production widen the gap between integrated processors and commodity traders.
Growth Catalysts
- EU Green Deal implementation:Carbon-accounting disclosure mandates are tilting procurement toward low-emission fractionation technologies, favoring processors with renewable energy sourcing.
- Sports nutrition reformulation:Performance brands are displacing whey and soy with pea isolates to capture allergen-sensitive consumers and clean-label positioning.
- Organic pea farming clusters:Backward integration into seed-to-protein operations in the Upper Midwest is securing non-GMO supply chains for premium isolate grades.
Market Restraints
- Yellow pea price volatility:Weather-driven harvest fluctuations in Canada and France transmit directly to isolate input costs, compressing margin stability for non-integrated processors.
- Technical limitation in flavor masking:Beany off-notes in standard isolates require expensive enzymatic treatment or masking systems, raising formulation costs for neutral-taste applications.
- Substitution threat from fava and chickpea proteins:Emerging fractionation capacity for alternative legumes is fragmenting plant-protein procurement pools among large food manufacturers.
Strategic Opportunities
- Textured protein white space:Meat-analogue brands are demanding fibrous extrudates with muscle-like bite, creating premium positioning for processors with twin-screw extrusion expertise.
- Dietary supplement channel expansion:Allergen-free positioning is opening sports nutrition and senior nutrition segments previously locked by dairy and soy dominance.
- EFSA novel food harmonization:Streamlined approval pathways for pea protein ingredients are accelerating European market entry for isolate exporters from North America.
Industry Challenges
- Fractionation engineer scarcity:Specialized expertise in aqueous protein extraction and spray-drying optimization is concentrated among legacy European processors, constraining new facility staffing.
- Capex intensity for isolate-grade capacity:Wet-fractionation lines with membrane filtration and chromatography polishing require substantial upfront investment, limiting mid-scale entrants.
- REACH compliance for processing aids:Registration requirements for enzymes and flocculants used in extraction are extending product development timelines for novel isolate variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Protein Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Flour Application: Food & Beverage, Dietary Supplements, Animal Feed, Pharmaceuticals Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Retailers Form: Powder, Granule, Liquid, Bar |
| Companies Covered | Roquette Frères, Ingredion, Cargill, Archer Daniels Midland Company, Burcon NutraScience Corporation, The Scoular Company, DuPont, PURIS, Cosucra Groupe Warcoing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Protein Market Emerging Trajectories
Pea protein processing is fragmenting across multiple technological frontiers simultaneously, as end-users demand ever-finer gradations of solubility, flavor neutrality, and functional performance that legacy fractionation methods cannot deliver.
Fermentation-assisted protein extraction is fragmenting conventional wet-fractionation economics. Biotech startups are deploying microbial enzymes to degrade polyphenol oxidases responsible for color and flavor defects, yielding isolates with superior sensory profiles. Plant-based dairy brands in Germany and the Netherlands are qualifying these enzymatically treated grades for barista-format beverages where visual clarity and neutral taste command premiums.
EFSA protein quality scoring methodology is reshaping European product positioning and export eligibility. The regulator's digestible indispensable amino acid score requirements are forcing reformulators to combine pea with rice or hemp proteins to achieve complete profiles, complicating single-ingredient labeling claims. Sports nutrition brands targeting EU distribution are restructuring supply agreements to secure blended isolate streams that satisfy these compositional thresholds.
Direct contracting between protein processors and regenerative farming cooperatives is displacing spot-market commodity purchasing. Large meat-alternative manufacturers in California and Illinois are securing multi-year offtake agreements with organic pea growers, embedding carbon-sequestration verification into procurement specifications. This relationship-based sourcing is most advanced in the Upper Midwest, where ingredient traceability supports premium retail pricing and ESG disclosure requirements.
Pea Protein Market Segmentation
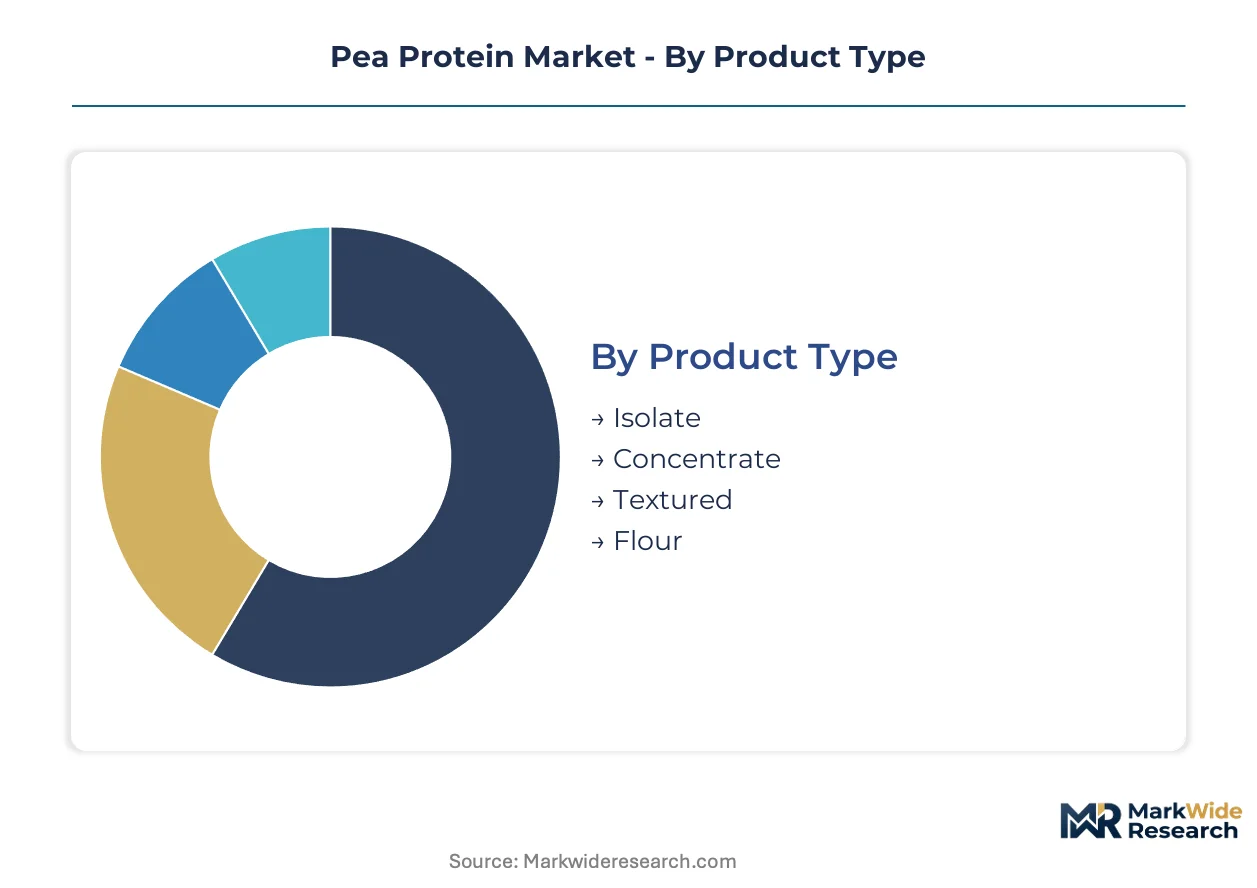
Pea protein procurement flows through distinct channel architectures that reshape margin capture and formulation access. Product grades, application specifications, and distribution pathways intersect to determine which processors capture premium positioning versus commodity volume.
Product Type:
Channel access stratifies sharply across purity grades, with foodservice and industrial buyers routing through different procurement pathways than retail-facing brands.
- Isolate:Contains 80-90% protein content with minimal fat and carbohydrate residues, achieved through aqueous extraction and membrane filtration. Premium beverage and sports nutrition brands in Germany and the Netherlands specify enzymatically treated isolates for neutral flavor profiles, though enzymatic processing adds cost layers that constrain mass-market penetration.
- Textured:Extruded fibrous structures produced via twin-screw extrusion to replicate muscle protein mouthfeel. Meat-analogue manufacturers in California and Illinois are securing dedicated textured protein supply through multi-year offtake agreements, embedding this format as the primary growth vector within alternative protein portfolios.
- Concentrate:Intermediate 60-75% protein grade serving cost-sensitive bakery and snack applications where full isolate functionality is not required.
- Flour:Whole-milled pea with 20-25% protein content, supplying gluten-free baking and pet food formulations through commodity ingredient distributors.
Isolate dominates installed base. Textured is where expansion concentrates.
Application:
Cost tier separation between premium-positioned finished goods and commodity-grade inputs determines which protein specifications achieve formulation approval.
- Food & Beverage:Encompasses plant-based dairy alternatives, meat analogues, and functional beverages requiring solubility and emulsification performance. Clean-label positioning in European retail chains is displacing soy and whey with pea isolates that satisfy EFSA protein quality scoring thresholds.
- Dietary Supplements:Sports nutrition powders, senior nutrition products, and clinical formulations demanding allergen-free certification. Brands previously locked into dairy and soy supply chains are reformulating around pea isolates to capture allergen-sensitive consumer segments.
- Animal Feed:Aquaculture and pet food applications utilizing lower-grade concentrates and flour for protein fortification.
- Pharmaceuticals:Emerging clinical nutrition and excipient applications subject to FDA GRAS and EMA quality documentation requirements.
Food & Beverage commands volume leadership. Dietary Supplements is climbing the fastest.
Distribution Channel:
Customer type fragmentation between industrial buyers, retail brands, and direct-to-consumer operators creates parallel channel structures with diverging service requirements.
- Online:Direct-to-consumer protein powders and subscription-based sports nutrition brands. E-commerce platforms enable small-batch processors to bypass traditional distribution markups and access niche allergen-free positioning.
- Supermarkets:Mass-market plant-based meat and dairy alternatives requiring consistent supply at scale. Retail consolidation in Germany and France is concentrating procurement power among fewer buyers with stringent ESG disclosure requirements.
- Health Food Stores:Premium organic and non-GMO certified isolates targeting clean-label consumers.
- Specialty Retailers:Sports nutrition and bodybuilding channels with technical formulation support and bulk purchasing options.
Supermarkets anchor volume throughput. Online is gaining share fastest.
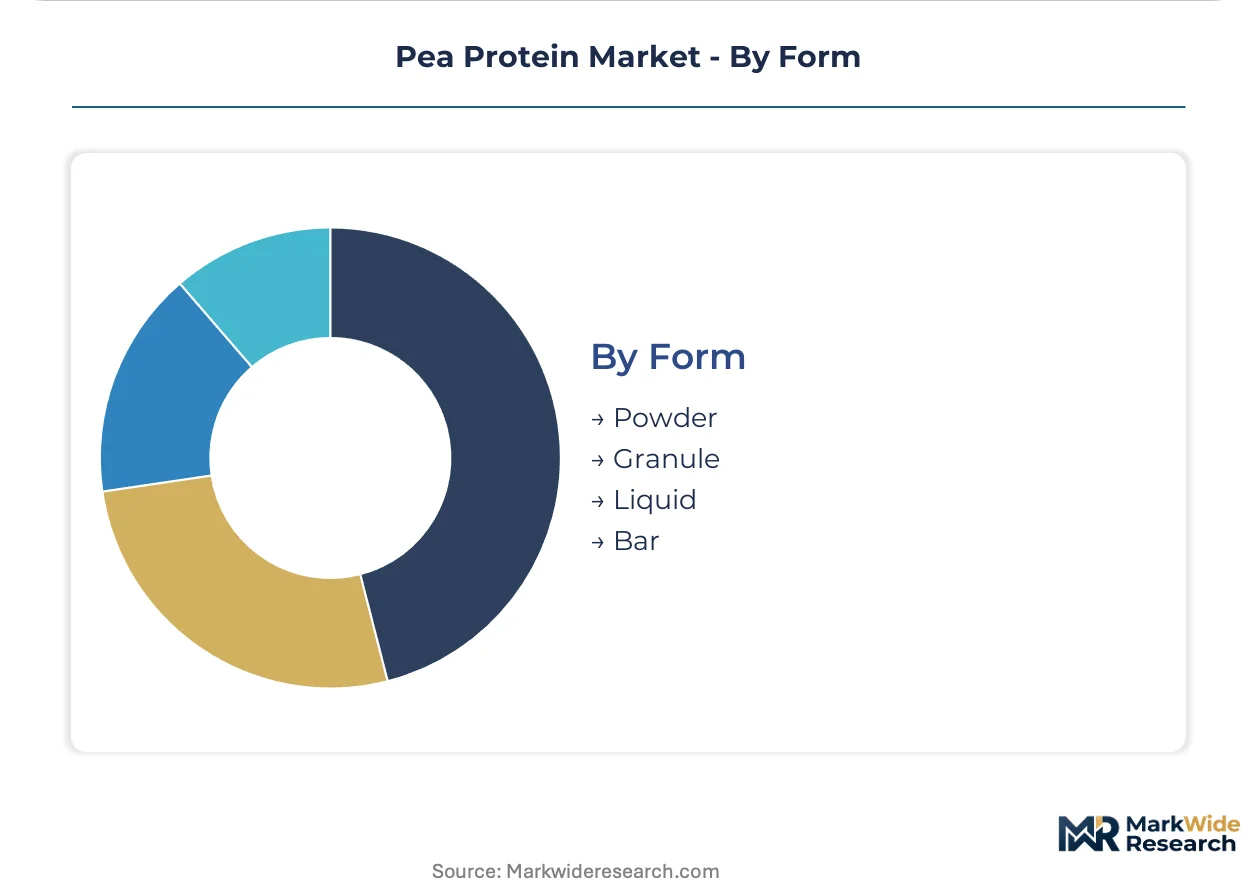
Form:
Supply concentration among spray-drying specialists in the Upper Midwest and northern France shapes availability across physical formats.
- Powder:Dominant format for isolate and concentrate, optimized for solubility and bulk handling. Spray-drying capacity constraints at isolate-grade specifications are creating allocation priority for long-term contract holders.
- Bar:Ready-to-eat protein bars requiring extrusion and binding compatibility with pea protein's water-binding characteristics. Sports nutrition brands are qualifying bar formats for on-the-go consumption occasions.
- Granule:Intermediate particle size for specific beverage dispersibility requirements and controlled-release applications.
- Liquid:Pre-hydrated protein solutions for beverage manufacturing, constrained by shelf stability and transportation economics.
Powder dominates installed base. Bar is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany while the United States captures volume throughput, creating a transatlantic asymmetry where European processors command premium isolate margins and American suppliers dominate textured protein scale.
Germany
EFSA protein quality scoring mandates are driving reformulation toward enzymatically treated isolates in sports nutrition and plant-based dairy. The EU Green Deal's carbon-accounting disclosure requirements favor processors with renewable energy sourcing. Hamburg and Cologne anchor ingredient manufacturing clusters where logistics corridors connect North Sea ports to Central European food brands.
United States
Meat-analogue manufacturers in California and Illinois are securing multi-year offtake agreements for textured pea protein with muscle-like bite characteristics. FDA GRAS determinations govern novel isolate variants entering dietary supplement channels. The Upper Midwest hosts backward-integrated organic pea farming operations that supply non-GMO isolate grades to premium sports nutrition brands.
France
Yellow pea harvest fluctuations transmit directly to isolate input costs, compressing margins for non-integrated processors dependent on spot-market purchasing. REACH compliance requirements for processing aids extend product development timelines for enzymatic extraction variants. Northern France maintains spray-drying capacity for isolate-grade powder specifications serving barista-format beverage applications.
Netherlands
Plant-based dairy brands are qualifying fermentation-assisted protein extracts for neutral-taste applications where visual clarity commands retail premiums. EFSA novel food approval pathways are streamlining market entry for North American isolate exporters targeting European distribution. Rotterdam's port infrastructure facilitates bulk pea imports from Canadian growing regions.
Canada
Weather-driven harvest volatility in prairie growing regions creates input cost instability for downstream protein fractionators. Health Canada and PMRA regulate processing aids and novel food ingredients entering domestic and export markets. Manitoba and Saskatchewan field pea production supplies North American and Asian processor demand through Vancouver and Prince Rupert export terminals.
Pea Protein Market Vendor Landscape
Concentration sits with legacy European processors and North American agricultural traders who have extended infrastructure into protein fractionation. The vendor base spans three tiers: integrated seed-to-protein operators commanding premium isolate margins, diversified ingredient conglomerates competing on procurement scale, and specialized biotech firms advancing enzymatic extraction technologies. Capacity expansion and backward integration into organic farming represent the dominant competitive moves reshaping supply security.
Among European heritage processors, Roquette Frères exemplifies the integrated archetype with decades of extrusion expertise sustaining premium isolate yields. Cargill occupies a position representing agricultural trading infrastructure extended into global protein fractionation scale. PURIS anchors the North American specialist tier through captive organic pea supply chains across the Upper Midwest.
| Leading Market Players |
|---|
| Roquette Frères |
| Ingredion |
| Cargill |
| Archer Daniels Midland Company |
| Burcon NutraScience Corporation |
| The Scoular Company |
| DuPont |
| PURIS |
| Cosucra Groupe Warcoing |
| Others |
Supply Flow & Price Mechanics
EFSA protein quality scoring mandates gate both supply qualification and price differentiation in European pea protein procurement, as enzymatically treated isolates command premiums while standard grades face margin compression. This regulatory filter simultaneously determines which processors achieve formulation approval and which capture tiered pricing power across sports nutrition and plant-based dairy channels.
Pricing Analysis
The customization-premium spread separates enzymatically treated isolates for neutral-taste applications from standard grades with residual beany off-notes. Three-tier pricing structure across premium enzymatic isolates, standard membrane-filtered grades, and economy concentrates reflects certification levels and solubility performance. Pricing pressure stems from yellow pea harvest volatility in Canada and France transmitting directly to input costs. Mass-market meat-analogue manufacturers exhibit highest price sensitivity, while premium sports nutrition brands prioritize allergen-free positioning over unit economics.
Supply Chain Analysis
Inventory lead times stretch longest for isolate-grade specifications where spray-drying capacity constraints in the Upper Midwest and northern France create allocation priority for contract holders. Supply concentrates in Canada, France, and the United States, with prairie growing regions and European processing clusters anchoring global output. The chain draws from yellow pea cultivation, aqueous extraction equipment, and enzymatic treatment inputs. Single-source vulnerability runs through membrane filtration and chromatography polishing capacity controlled by legacy European processors. Distribution runs through multi-year offtake agreements displacing spot-market commodity purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea protein sits in early-cycle expansion as sports nutrition reformulation accelerates displacement of whey and soy alternatives, creating penetration headroom previously locked by allergen-sensitive consumer segments.
For Market Incumbents: Secure backward integration into organic pea farming across the Upper Midwest to insulate margin stability from weather-driven harvest fluctuations in Canadian prairie regions. Anchor enzymatic treatment capacity to defend premium isolate positioning against emerging fava and chickpea protein substitutes threatening procurement fragmentation.
For New Entrants and Emerging Players: Fermentation-assisted extraction capabilities represent the service-layer gap where legacy processors under-serve plant-based dairy brands demanding visual clarity and neutral taste for barista-format beverages. Target textured protein supply to meat-analogue manufacturers in California and Illinois through twin-screw extrusion expertise. Pursue direct-to-consumer sports nutrition channels where e-commerce platforms bypass traditional distribution markups.
For Investors and Strategic Acquirers: EU Green Deal carbon-accounting disclosure mandates reshape the acquisition landscape toward processors with renewable energy sourcing and regenerative farming verification. Long-term viability favors integrated seed-to-protein operators with captive organic supply chains over commodity traders dependent on spot-market purchasing. Monitor EFSA novel food approval timelines as inflection indicators for North American isolate export eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farming | Captive pea supply secures non-GMO isolate grades for premium sports nutrition brands. |
| Enzymatic Treatment Capacity Addition | Neutral-flavor isolates qualify for EFSA protein quality scoring thresholds in European retail. |
| Textured Protein Extrusion Scale-Up | Fibrous structures with muscle-like bite meet meat-analogue manufacturer procurement specifications. |
| Regenerative Farming Certification Program | Carbon-sequestration verification supports ESG disclosure requirements for supermarket procurement. |
| Long-term Supply Agreement Structuring | Multi-year offtake contracts with meat-alternative brands displace volatile spot-market purchasing. |
Methodological Framework
Initial hypotheses were tested against primary input from fractionation technology directors, sports nutrition brand formulators, organic farming cooperative managers, and ingredient procurement leads at meat-alternative manufacturers, then refined through secondary validation. Sources included EFSA novel food submission databases, FDA GRAS determination filings, EU REACH compliance registries, and customs trade data on pea protein concentrate and isolate shipments. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile volume estimates.
Variance decomposition across product type, application specification, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro protein displacement trends. Modeled inputs included enzymatic treatment adoption curves, textured protein extrusion capacity buildout, and EFSA protein quality scoring implementation timelines.
Underlying assumptions cover fractionation technology maturation and regulatory approval pathway stability, with deviation risk concentrated in yellow pea harvest volatility and substitute legume protein commercialization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Veggie Meals Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Global Textured Vegetable Protein Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Fermented Plant-Based Food Market