
 Better for You Snacks Market | 2026-2036
Better for You Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Better for You Snacks Market Insights
Asset-light co-manufacturing and contract packaging arrangements is reshaping how emerging brands enter the Better for You Snacks space without owning production facilities. PepsiCo leverages its global distribution infrastructure to secure shelf placement across multiple retail formats. KIND Snacks anchors its portfolio in transparent ingredient sourcing and visible nutritional claims. Nature's Bakery specializes in soft-baked, non-GMO bars that appeal to allergen-sensitive households.
Better for You Snacks comprise formulated food products engineered with reduced sodium, sugar, or fat profiles, enhanced protein or fiber content, and minimal artificial additives, produced through extrusion, baking, or air-popping methods rather than conventional frying. The ingredient focus dimension shows organic and high-protein claims commanding premium positioning, while gluten-free and low-sugar variants are expanding fastest among lifestyle-driven purchasers. Distribution channel dynamics reveal health food chains and online retailers capturing disproportionate margin pools as consumers bypass conventional grocery for curated discovery.
FDA nutrition labeling requirements and the USDA organic certification framework govern product claims and substantiation protocols in the United States, while EFSA health claim regulations constrain permissible marketing language across European markets. These standards compel reformulation investments and third-party verification spending that filter out smaller unqualified competitors. Stakeholders must monitor evolving definitions of "healthy" as regulatory bodies finalize updated criteria that could disqualify current portfolio positioning.
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are forcing manufacturers to strip artificial additives while maintaining shelf stability, compressing R&D timelines and elevating third-party verification costs across the supply chain.
Growth Catalysts
- FDA Nutrition Labeling Modernization:Updated serving-size definitions and added-sugar callouts are compelling brands to reformulate with natural sweeteners like monk fruit and allulose.
- Corporate Wellness Programs:Fortune 500 employers are subsidizing low-sugar, high-protein snack options in campus cafeterias and vending networks.
- Extrusion Technology Advances:Twin-screw extrusion systems now enable protein fortification above 20% without compromising texture or mouthfeel.
Market Restraints
- Organic Ingredient Supply Concentration:Domestic organic oat and nut sourcing clusters in California and the Pacific Northwest, exposing brands to drought-driven price volatility.
- Clean-Label Preservation Limits:Removal of synthetic preservatives shortens finished-goods shelf life from 12 months to 90-120 days, constraining distribution radius.
- Almond Milk Powder Substitution Threat:Dairy-alternative protein bases are displacing traditional whey in certain bar applications, forcing equipment reconfiguration.
Strategic Opportunities
- USDA Organic Certification Tailwind:Federal procurement guidelines now award preferential scoring to organic-certified snacks in school nutrition programs.
- Direct-to-Consumer Subscription Channels:Curated monthly boxes bypass conventional slotting fees while capturing recurring revenue and first-party consumption data.
- Air-Popping and Freeze-Drying Convergence:Hybrid thermal processes reduce oil content below 5% while preserving volatile flavor compounds lost in conventional baking.
Industry Challenges
- Food Science Talent Scarcity:Formulation chemists skilled in natural emulsifier systems command premium salaries and extended search timelines.
- Co-Packer Certification Bottlenecks:SQF and BRC audits require 6-9 month lead times, delaying new product launches for emerging brands without captive facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Better for You Snacks Market |
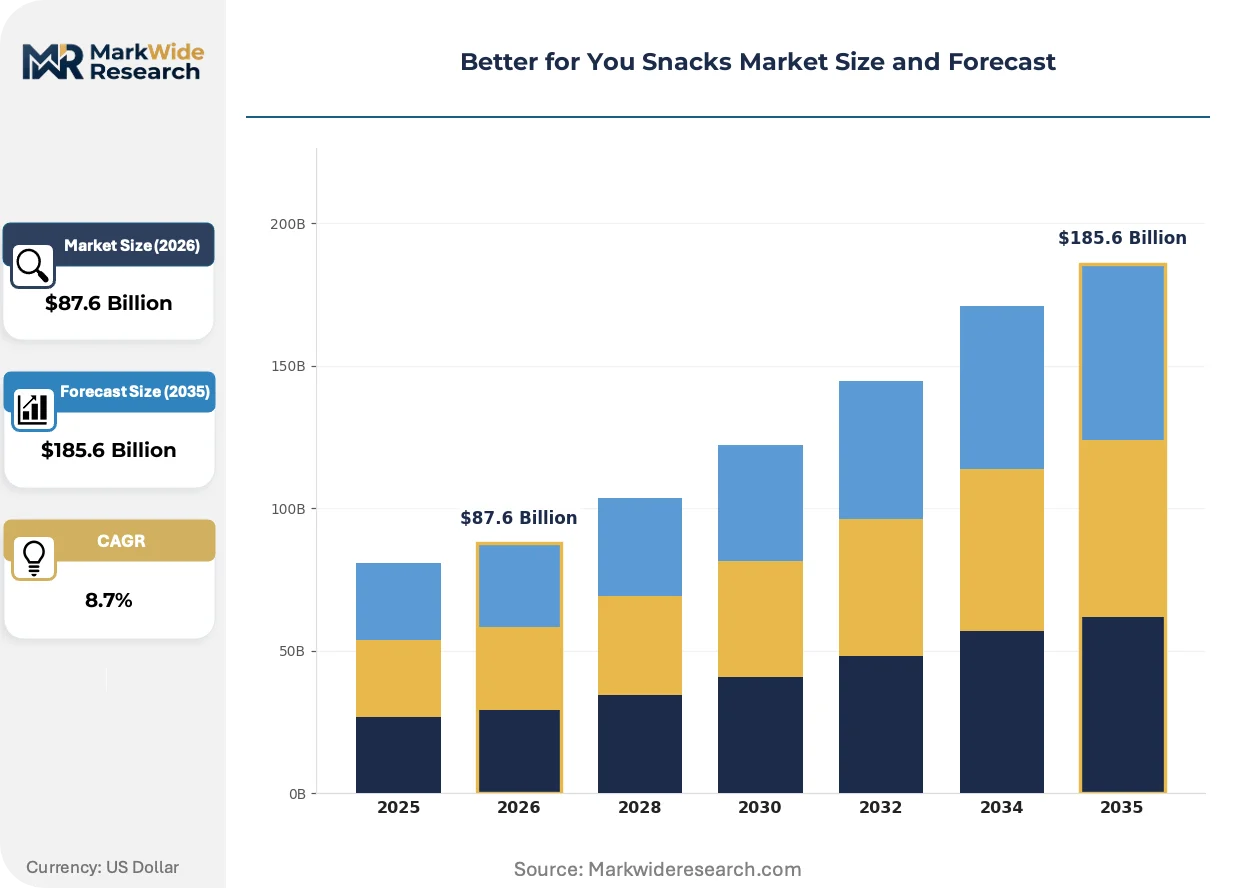
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Baked Chips, Dried Fruits, Vegetable Crisps, Nut Mixes Ingredient Focus: Organic, High Protein, Low Sugar, Gluten Free, Non-GMO, Vegan Packaging Format: Single Serve, Multi Pack, Resealable Bags, Portion Controlled Packs, Bulk Bags Distribution Channel: Specialty Stores, Online Retailers, Convenience Stores, Health Food Chains, Corporate Vending |
| Companies Covered | PepsiCo, Nestlé, Mondelēz International, General Mills, Kellanova, The Hain Celestial Group, Campbell Soup Company, Nature’s Bakery, KIND Snacks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Better for You Snacks Market Trends and Innovations
Reformulation science and supply chain transparency tools are compressing the gap between niche health claims and mass-market accessibility, reshaping how consumers discover and validate nutritional positioning.
Blockchain-enabled ingredient traceability is digitizing provenance documentation from farm to finished good. Specialty retailers and direct-to-consumer brands are adopting these systems fastest, pressured by liability concerns and consumer litigation risk. This technology is digitizing audit workflows that previously required manual paper trails and third-party site visits.
EFSA's 2024 guidance on nutrient profiling restricts "high protein" and "natural" claims unless substantiated by standardized analytical methods. Manufacturers serving EU export markets are retooling label inventories and reformulating borderline products. Plant-based bar categories face the steepest compliance burden given protein-content variability in crop-sourced inputs.
Discovery patterns have rotated sharply toward algorithmic curation. Health-conscious millennials now encounter new brands through TikTok and Instagram rather than traditional grocery aisle browsing. This behavioral shift concentrates launch success in coastal metropolitan zones where digital-native consumers cluster and share purchase validation through social proof.
Better for You Snacks Market Segmentation
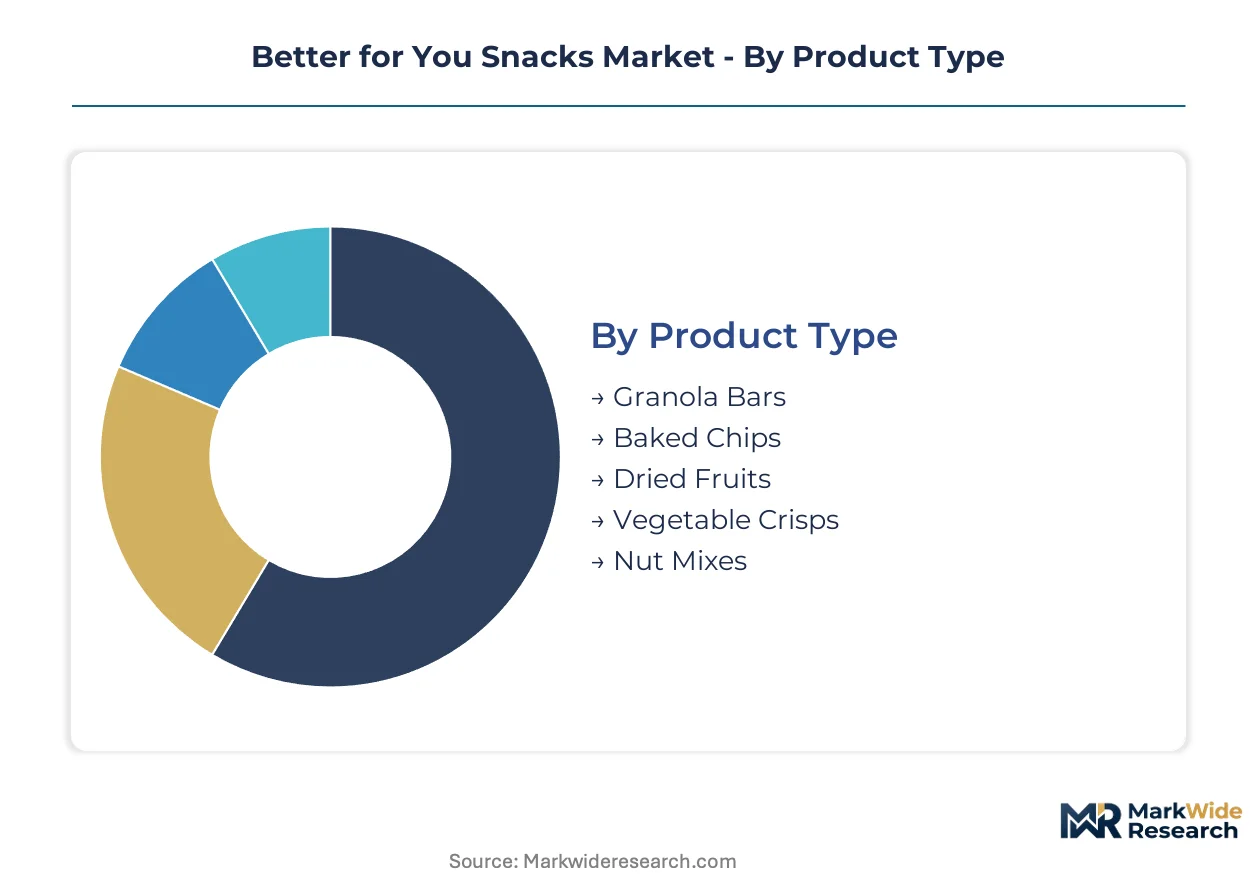
Segmentation in the Better for You Snacks market reveals distinct velocity patterns across product lifecycles and purchase occasions. Reformulation cycles compress to 8-12 months for trend-responsive categories while staple formats maintain 24-36 month stability windows.
Product Type:
Granola bars and baked chips turn inventory fastest at 45-60 days, while bulk nut mixes and vegetable crisps rotate slower due to seasonal demand clustering and higher price points.
- Granola Bars:Extruded and cold-pressed formats with protein fortification above 15g per serving. Demand clusters in corporate wellness programs and university dining contracts where portion control and nutritional transparency are mandated procurement criteria.
- Baked Chips:Air-popped or oven-baked potato, cassava, and legume bases with oil content below 8%. Coastal metropolitan markets in the United States drive volume through specialty retail and direct-to-consumer discovery channels.
- Dried Fruits:Low-temperature dehydrated berries and tropical varieties without added sulfites.
- Vegetable Crisps:Vacuum-fried or baked root vegetable slices targeting allergen-sensitive households.
- Nut Mixes:Raw and dry-roasted combinations with functional ingredient inclusions like adaptogens.
Granola bars dominate installed base. Baked chips are where expansion concentrates.
Ingredient Focus:
Cost tier stratification separates premium-positioned organic and high-protein claims from accessible low-sugar and gluten-free variants that scale through conventional retail.
- Organic:USDA-certified ingredient sourcing with full traceability documentation and third-party verification. School nutrition programs and federal procurement channels in the United States award preferential scoring, concentrating institutional demand.
- High Protein:Whey, pea, or collagen fortification achieving 20g+ protein per serving with acceptable texture profiles. Fitness-oriented consumers and corporate wellness subsidies in Fortune 500 campuses drive repeat purchase velocity.
- Low Sugar:Monk fruit, allulose, and stevia-sweetened formulations reducing added sugar below 5g per serving.
- Gluten Free:Oat, nut, and seed-based products certified below 20ppm gluten threshold.
- Non-GMO:Verified supply chains excluding genetically modified corn, soy, and canola derivatives.
- Vegan:Plant-exclusive formulations replacing honey with maple or agave and excluding all animal derivatives.
Organic claims command the highest margin tier. Low sugar is climbing the fastest among lifestyle-driven purchasers.
Packaging Format:
Volume concentration favors single-serve units for on-the-go consumption while multi-pack and resealable formats capture pantry-stocking occasions with higher per-transaction value.
- Single Serve:Individually wrapped 1-2oz portions for immediate consumption. Convenience stores and corporate vending networks in urban United States markets drive placement density and impulse purchase frequency.
- Multi Pack:4-6 count boxes for household pantry stocking and lunchbox preparation. Club retail and online subscription channels concentrate demand through bulk pricing and recurring delivery models.
- Resealable Bags:Zip-lock or press-to-close flexible packaging extending shelf life post-opening.
- Portion Controlled Packs:Pre-measured sub-units within larger containers for calorie-conscious consumers.
- Bulk Bags:1-5lb foodservice and institutional formats for cafeterias and hospitality.
Single serve dominates installed base. Multi pack is gaining share fastest through e-commerce penetration.
Distribution Channel:
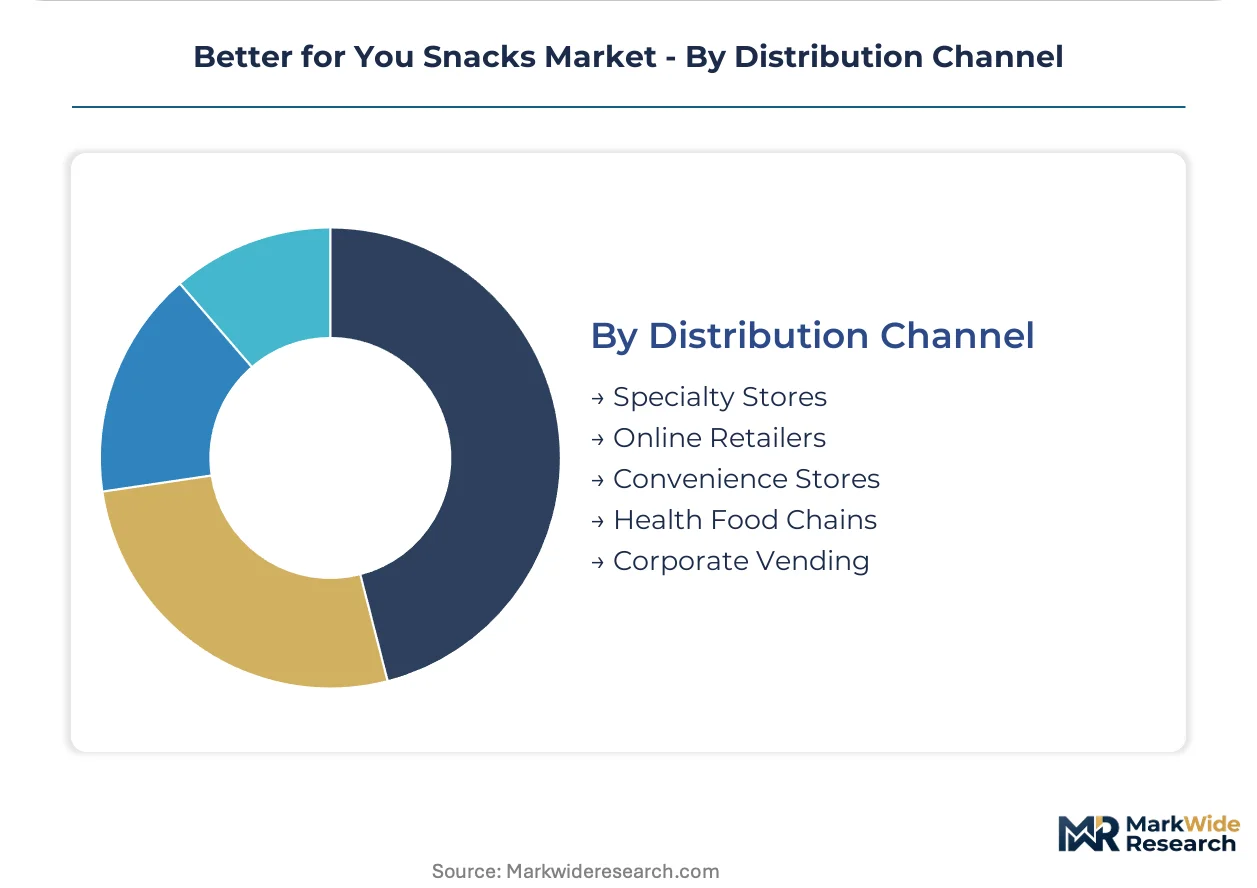
Customer type stratification separates discovery-oriented health food chains and online retailers from convenience-driven vending and convenience store placement with lower engagement but higher location density.
- Specialty Stores:Curated independent and regional chains emphasizing local and emerging brands. Urban United States markets with educated, health-conscious demographics drive premium pricing acceptance and brand trial rates.
- Online Retailers:Direct-to-consumer and marketplace platforms capturing first-party data and subscription revenue. Algorithmic curation through social media discovery concentrates launch success among millennial and Gen Z segments.
- Convenience Stores:Limited assortment grab-and-go placement in high-traffic locations.
- Health Food Chains:National specialty retailers with private label and exclusive brand partnerships.
- Corporate Vending:Subsidized or full-price automated retail in workplace campuses.
Specialty stores dominate installed base. Online retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement guidelines awarding preferential scoring to organic-certified snacks in US school nutrition programs are accelerating institutional demand. Clean-label mandates from EFSA and FDA are forcing cross-border reformulation investments. Distribution infrastructure investments in cold-chain logistics and direct-to-consumer fulfillment are reshaping regional competitive positions.
United States
Corporate wellness programs at Fortune 500 employers subsidize low-sugar, high-protein options in campus cafeterias and vending networks. FDA nutrition labeling modernization compels reformulation with natural sweeteners like monk fruit and allulose. The Pacific Northwest organic oat and nut sourcing cluster concentrates supply exposure to drought-driven price volatility.
Germany
EFSA's 2024 nutrient profiling guidance restricts "high protein" and "natural" claims without standardized analytical substantiation. The country's national food safety regulator enforces strict health claim verification protocols. Berlin and Munich metropolitan zones drive premium pricing acceptance for clean-label products through specialty retail density.
United Kingdom
Algorithmic curation through TikTok and Instagram concentrates brand discovery among millennial and Gen Z consumers in London and Southeast England. The country's food standards agency maintains strict additive approval lists that exceed baseline EU requirements. Health food chains in urban centers capture disproportionate margin pools through curated local and emerging brand partnerships.
Japan
METI's promotion of functional food claims creates regulatory pathways for protein-fortified and low-sugar positioning. The country's national standards body governs organic certification equivalency with USDA and EU frameworks. Tokyo and Osaka metropolitan markets demonstrate high acceptance for portion-controlled single-serve formats in convenience retail channels.
Australia
Freeze-drying and air-popping technology adoption reduces oil content below 5% while preserving volatile flavor compounds for export-oriented production. The country's national food regulator enforces strict labeling requirements for allergen and nutritional claims. Sydney and Melbourne coastal markets concentrate direct-to-consumer subscription channel penetration among health-conscious professional demographics.
Better for You Snacks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented shelf space allocation. The vendor base spans multinational conglomerates with global distribution infrastructure, mid-sized organic specialists with transparent sourcing narratives, and emerging direct-to-consumer brands leveraging algorithmic discovery. Three archetypes dominate: scale-driven portfolio diversifiers, clean-label purists with ingredient transparency positioning, and digital-native challengers bypassing conventional retail slotting fees. Competitive moves concentrate on co-manufacturing partnerships to avoid captive facility investments and subscription channel buildout to capture recurring revenue and first-party consumption data.
Within the scale-driven tier, PepsiCo occupies a position exemplifying global distribution leverage across multiple retail formats. KIND Snacks and Nature's Bakery sit within the clean-label specialist archetype, anchoring transparent ingredient sourcing and visible nutritional claims. These three companies represent the spectrum from conglomerate channel control to emerging brand authenticity positioning that characterizes competitive dynamics in this space.
| Leading Market Players |
|---|
| PepsiCo |
| Nestlé |
| Mondelēz International |
| General Mills |
| Kellanova |
| The Hain Celestial Group |
| Campbell Soup Company |
| Nature's Bakery |
| KIND Snacks |
| Others |
Pricing and Supply Chain Analysis
Intermodal freight corridors connecting California's Central Valley organic nut clusters to East Coast distribution hubs concentrate cost dynamics, amplifying price spreads between USDA-certified premium tiers and conventional alternatives while forcing mid-market brands toward contract manufacturing to bypass captive facility investments.
Pricing Analysis
Certification level creates the primary spread between USDA Organic and conventional positioning, with third-party verification costs and traceability documentation adding margin compression at the premium tier. Three-tier pricing structure across premium organic, standard clean-label, and economy conventional levels stratifies the market, with subscription direct-to-consumer channels capturing least price-sensitive wellness-focused households while convenience store single-serve formats face acute sensitivity among impulse purchasers. Pricing pressure stems from drought-driven volatility in domestic organic oat and almond inputs. Corporate procurement offices at Fortune 500 campuses demonstrate lowest price elasticity due to wellness program subsidies.
Supply Chain Analysis
Organic oat and nut feedstocks draw from concentrated California and Pacific Northwest sourcing clusters, with secondary dependence on Canadian prairie organic grain networks. Raw material inputs hinge on almond, cashew, and pea protein isolates, with monk fruit and allulose sweeteners increasingly substituting conventional sugar. Single-source vulnerability in domestic organic certification capacity creates bottleneck risk for emerging brands. Distribution runs through hybrid direct-to-consumer fulfillment centers and specialty retail consolidation points, with cold-chain logistics investments reshaping regional reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern discovery and retention, with algorithmic curation on TikTok and Instagram collapsing traditional slotting-fee barriers and enabling emerging brands to build subscriber ecosystems before securing retail placement.
For Market Incumbents: Pre-empt digital-native challengers by acquiring direct-to-consumer subscription capabilities and first-party data assets. Secure exclusive co-manufacturing partnerships with SQF-certified facilities to constrain emerging brand production access. Invest in blockchain traceability infrastructure to defend premium positioning against transparency-focused entrants.
For New Entrants and Emerging Players: Corporate vending networks in secondary US metropolitan zones offer underpenetrated placement density with lower slotting-fee competition than coastal health food chains. Target university dining contracts and regional healthcare campus cafeterias where nutritional procurement mandates create structural demand. Lead with single-serve protein-fortified formats that align with portion-control wellness protocols.
For Investors and Strategic Acquirers: Clean-label specialists with captive organic sourcing relationships and established school nutrition program contracts represent priority acquisition archetypes. Long-term viability rests on regulatory navigation capabilities as FDA and EFSA definitions of "healthy" evolve. Watch for EFSA nutrient profiling enforcement actions as inflection signals for EU export market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses conventional slotting fees while capturing recurring revenue and consumption data from wellness-focused households. |
| USDA Organic Certification Investment | Unlocks federal procurement preferential scoring in school nutrition programs and institutional channels. |
| Co-Manufacturing Partnership Expansion | Enables asset-light scale without captive facility capital deployment or SQF audit lead time exposure. |
| Blockchain Traceability Implementation | Digitizes provenance documentation for liability protection and premium claim substantiation under FDA guidance. |
| Corporate Wellness Channel Penetration | Secures subsidized placement in Fortune 500 campus networks with mandated low-sugar procurement criteria. |
Research Methodology
Cross-validation between primary interviews with category buyers at specialty retailers and secondary validation through Nielsen retail audit data anchors the qualitative findings. Conversations with formulation chemists, co-manufacturing operations directors, and corporate wellness procurement officers supplied forward-looking perspective on reformulation timelines and channel dynamics. Regulatory filings with FDA and EFSA, USDA organic certification databases, and customs trade records provided foundational supply-side parameters. Bottom-up SKU-level modeling and top-down category spend analysis were reconciled through iterative triangulation.
Calibration against historical volume trajectories and input cost indices informed projection mechanics across the modeling period. Segmentation dimensions include product type, ingredient focus, packaging format, and distribution channel, with protein fortification level and clean-label claim intensity as category-specific stratifiers. CAGRs were derived from regression-weighted trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporate organic commodity price volatility assumptions and digital channel penetration curves.
Practitioners should monitor EFSA nutrient profiling enforcement, FDA "healthy" definition updates, and drought severity indices for early signals of forecast deviation. Cross-checking against USDA organic acreage reports and specialty retail scanner data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Asia-Pacific Snack Bar Market
Snacks
North America Frozen Snacks Market
Snacks
Savoury Biscuits Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Low Fat Crackers Market
Snacks
Plant-Based Snacks Market
Snacks
North America Extruded Snack Food Market
Snacks
Roasted Snacks Market
Snacks
Europe Snacks Market
Snacks
North America Pretzel Market
Snacks
Gluten Free Snacks Market
Snacks
Kale Chips Market
Snacks
Spain Energy Bar Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Nutritional Bar Market
Snacks
Asia Pacific Snack Food Market