
 Global Low Calorie Food Market | 2026-2036
Global Low Calorie Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Calorie Food Market Foresight
Buyer concentration in the low calorie food sector is shifting as mass-market retailers and direct-to-consumer subscription services fragment historical dominance by weight-loss clinic networks. Groupe Danone SA leverages its fermented dairy expertise to anchor shelf presence in European and North American light dairy segments. Abbott Laboratories competes through medical nutrition credibility, sustaining physician and dietitian referral channels that reinforce trust in reduced-calorie therapeutic formulations. Nestlé S.A. dominates ambient grocery distribution, controlling end-cap placements and seasonal promotional cycles that determine trial rates for new low-calorie entrants.
Low calorie foods are formulated products delivering reduced energy density per serving through substitution of sugars and fats with non-nutritive sweeteners, bulking agents, or modified starches, typically achieving calorie reductions of one-third to one-half versus conventional equivalents while maintaining acceptable sensory profiles through emulsion stabilization and flavor masking technologies. Their primary commercial purpose centers on enabling sustained caloric deficit without portion restriction, supporting adherence in clinical weight management and consumer self-directed dietary protocols. Frozen meals and low sugar beverages represent the most mature revenue pools, while sports nutrition applications within the application dimension capture the fastest margin expansion as gym members and amateur athletes adopt physique-targeting diets. Light dairy products sustain premium positioning in European refrigerated cases, where clean-label fermentation credentials command price multiples over standard reduced-fat alternatives.
The FDA governs nutrient content claims and health claims on low calorie packaging through its Food Labeling Guide, while the European Food Safety Authority evaluates novel sweetener approvals under EU 2015/2283, collectively determining which reformulated products achieve market access. Japan's Ministry of Health, Labour and Welfare maintains distinct FOSHU (Foods for Specified Health Uses) standards that create additional compliance burdens for multinational portfolios. Stakeholders must monitor evolving sweetener safety assessments and front-of-pack labeling mandates to anticipate reformulation costs and regional portfolio prioritization decisions.
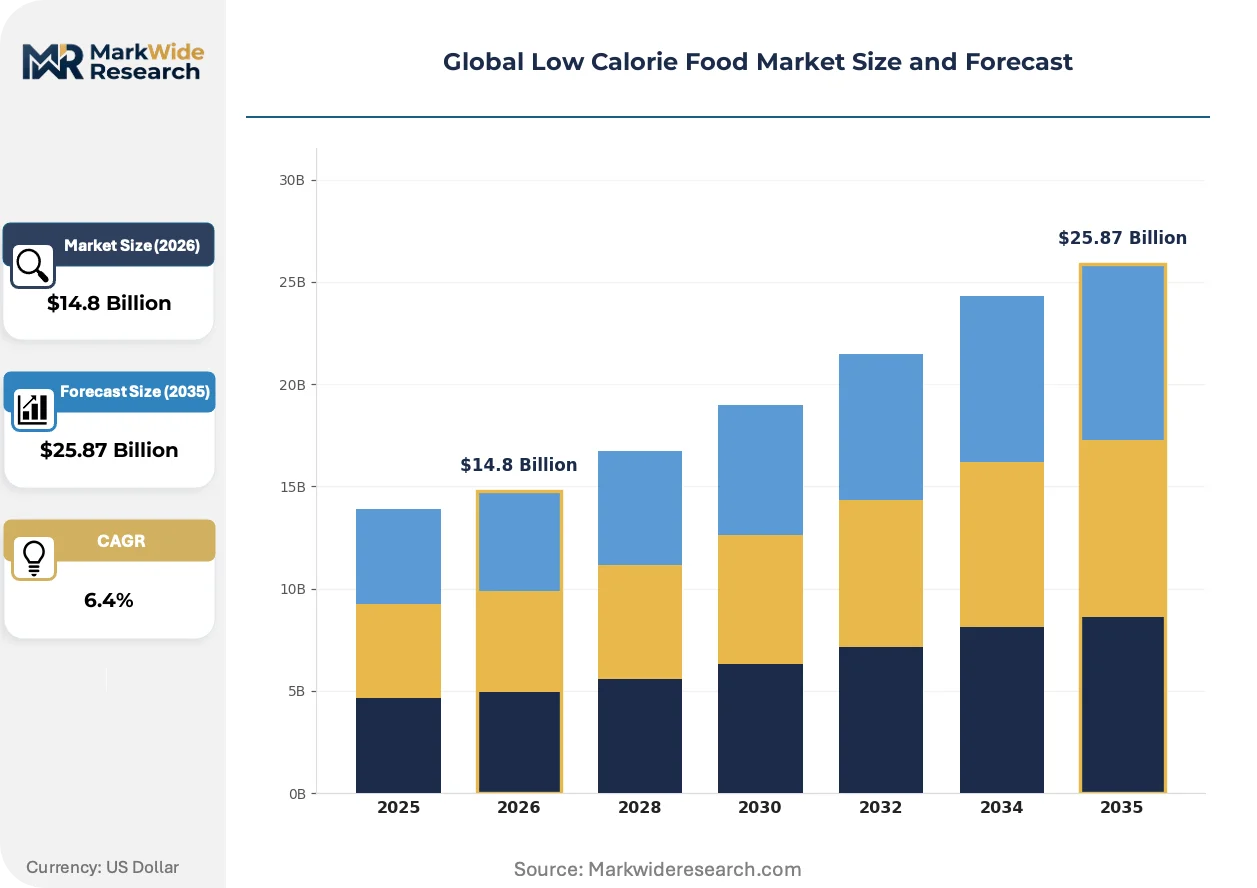
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements and the European Union's front-of-pack calorie disclosure mandates are forcing simultaneous reformulation across multinational branded portfolios, compressing development timelines and raising compliance costs for legacy product lines.
Growth Catalysts
- Regulatory transparency mandates:The FDA's calorie disclosure rules and EFSA's novel sweetener evaluations under EU 2015/2283 accelerate clean-label reformulation investments.
- Health-conscious generational demand:Millennial and Gen Z consumers in the United States and Germany expand retail grocery purchases of reduced-calorie packaged foods.
- Fermentation technology maturation:Advanced starter cultures and enzymatic processing enable calorie reduction in dairy without texture degradation.
Market Restraints
- Input cost volatility:Stevia and monk fruit extract prices fluctuate with agricultural yields in China and Southeast Asia.
- Supply concentration risk:Three suppliers control global erythritol production, creating vulnerability to plant outages.
- Technical sensory limitations:Bitterness masking in high-intensity sweetener formulations remains unresolved for coffee applications.
Strategic Opportunities
- Underpenetrated sports nutrition:Amateur athletes in Brazil and Mexico represent untapped demand for physique-targeting low-calorie meal solutions.
- Direct-to-consumer subscription channels:Personalized nutrition platforms bypass traditional retail slotting fees and capture lifetime value data.
- Japan's FOSHU framework:Functional food claims approval creates premium positioning for reduced-calorie therapeutic formulations.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise in non-nutritive sweetener synergy commands salary premiums that strain R&D budgets.
- Cross-border compliance timelines:Divergent safety assessments for novel bulking agents between FDA and EFSA delay multi-region launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Calorie Food Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Bars, Frozen Meals, Ready-to-Eat Cereals, Low Sugar Beverages, Light Dairy Products Application: Weight Management, Diabetic Nutrition, Sports Nutrition, Healthy Snacking, Weight Loss Programs Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops, Pharmacies End User: Gym Members, Dietitians, Weight Control Clinics, Fitness Coaches, Nutritionists |
| Companies Covered | Groupe Danone SA, Abbott Laboratories, Nestlé S.A., Ajinomoto Co. Inc., Cargill Incorporated, PepsiCo Inc., General Mills Inc., Beneo Group, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Calorie Food Market Shifts & Advancements
Reformulation science is advancing through precision fermentation, novel protein structuring, and AI-driven flavor mapping that compresses sensory optimization cycles from years to months.
Precision fermentation-derived proteins and fats are overtaking traditional plant-based substitutes in low-calorie dairy analogs. European and North American refrigerated case buyers now prioritize fermentation credentials over conventional reduced-fat positioning. This technology is overtaking legacy hydrocolloid stabilization by delivering superior mouthfeel at lower calorie density.
The European Union's CSRD sustainability reporting requirements and nutrient profiling schemes are reshaping portfolio prioritization decisions. Manufacturers must now document Scope 3 emissions from agricultural sweetener supply chains. Light dairy and frozen meal segments face the steepest reformulation costs as sugar reduction targets tighten.
Gym members and amateur athletes are consolidating purchasing around physique-targeting subscription services that bundle low-calorie meals with biometric coaching. Traditional retail grocery channels lose traffic to these integrated platforms in the United States and United Kingdom. This behavioral pivot concentrates margin capture with vertically integrated wellness brands.
Global Low Calorie Food Market Segmentation
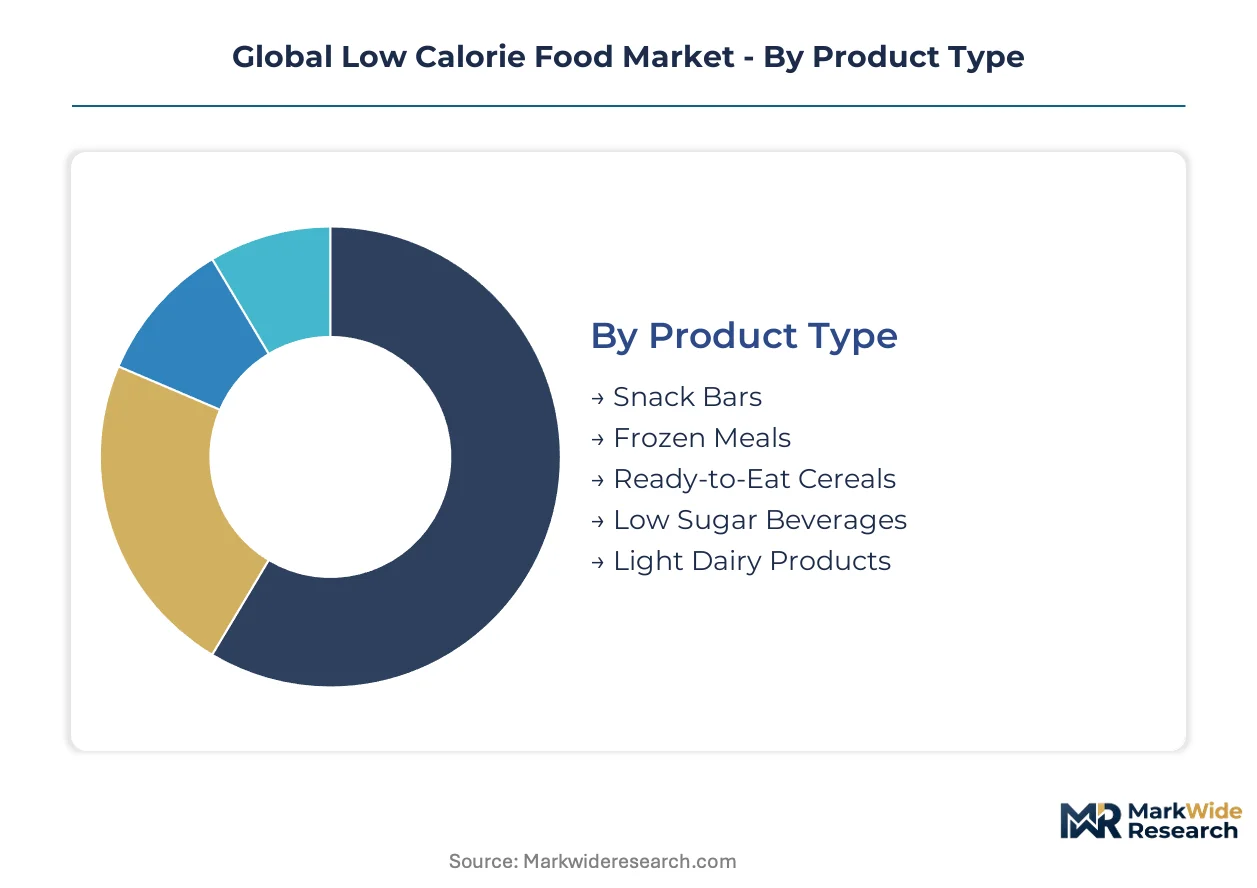
Low calorie food markets fragment across consumption occasions, therapeutic needs, and purchase contexts that determine formulation priorities and channel economics. Understanding these segment boundaries clarifies where R&D investments concentrate and which distribution partnerships yield shelf access.
Product Type:
Standalone packaged formats dominate retail velocity, while ingredient systems embed into foodservice and co-manufactured applications.
- Snack Bars:Protein-fortified and fiber-dense formulations achieve portability without refrigeration. Demand clusters with gym members in the United States and Germany who prioritize macronutrient transparency on front-of-pack labels.
- Frozen Meals:Controlled-portion entrees rely on modified starch gels and emulsion stabilization to replicate mouthfeel at reduced calorie density. Kroger and Albertsons private-label lines capture shelf space from legacy diet brands in North American frozen cases.
- Ready-to-Eat Cereals:Extruded grain matrices with bulking agents replace sugar-sweetened heritage formulations. Breakfast occasion competition intensifies against overnight oats and Greek yogurt alternatives.
- Low Sugar Beverages:Carbonated and still formats using stevia or monk fruit extracts face bitterness masking challenges in coffee applications. EFSA novel sweetener evaluations under EU 2015/2283 determine European market access timelines.
- Light Dairy Products:Fermentation-derived protein structuring enables texture parity with full-fat equivalents. European refrigerated case buyers pay premiums for clean-label fermentation credentials over conventional reduced-fat positioning.
Volume placements concentrate in frozen meals and low sugar beverages; the faster expansion belongs to light dairy products.
Application:
Clinical protocols demand precise macronutrient specifications, while lifestyle applications tolerate broader formulation ranges.
- Weight Management:Medically supervised programs require documented caloric deficit maintenance through portion-controlled meal replacements. Physician and dietitian referral channels at Abbott Laboratories reinforce trust in therapeutic formulations.
- Diabetic Nutrition:Glycemic control formulations prioritize resistant starches and non-glycemic sweeteners to blunt postprandial glucose spikes. FDA nutrient content claims govern permissible health messaging on packaging.
- Sports Nutrition:Physique-targeting diets among amateur athletes in Brazil and Mexico drive demand for high-protein, low-calorie meal solutions. Subscription platforms bypass traditional retail slotting fees and capture lifetime value data.
- Healthy Snacking:Between-meal consumption occasions favor portable formats with clean-label ingredient decks. Millennial and Gen Z consumers in retail grocery channels expand purchases of reduced-calorie packaged foods.
- Weight Loss Programs:Commercial clinic networks and direct-to-consumer platforms fragment historical dominance by traditional weight-loss clinic networks. Groupe Danone SA leverages fermented dairy expertise to anchor shelf presence.
Revenue concentrates in weight management and diabetic nutrition; sports nutrition climbs the fastest as gym culture penetrates emerging markets.
Distribution Channel:
High-velocity retail captures impulse purchases, while professional channels sustain premium pricing through credentialing.
- Supermarkets:End-cap placements and seasonal promotional cycles determine trial rates for new low-calorie entrants. Nestlé S.A. dominates ambient grocery distribution in this channel.
- Health Food Stores:Curated assortments favor clean-label and organic-certified reduced-calorie options. Staff expertise drives conversion for unfamiliar reformulated products.
- Online Retailers:Personalized nutrition platforms bypass geographic constraints and capture repeat purchase data. Direct-to-consumer subscription channels concentrate margin capture with vertically integrated wellness brands.
- Specialty Shops:Ethnic and gourmet formats serve niche dietary protocols requiring specific ingredient exclusions. Limited SKU counts prioritize depth over breadth.
- Pharmacies:Medical nutrition credibility sustains physician and dietitian referral channels. Abbott Laboratories competes through therapeutic formulation trust in this channel.
Transaction volume concentrates in supermarkets and online retailers; health food stores gain share fastest as clean-label preferences harden.
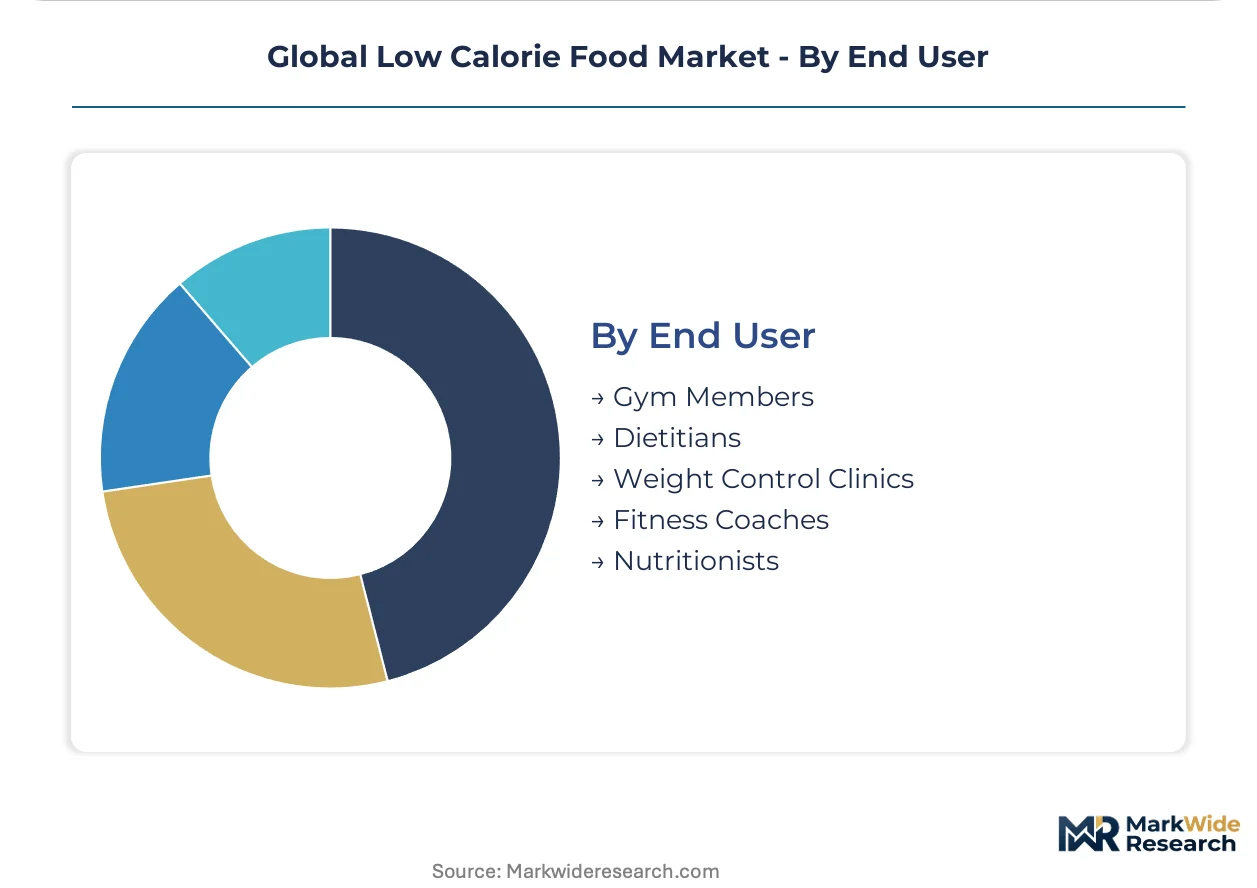
End User:
Professional intermediaries influence purchase decisions even when consumers execute transactions.
- Gym Members:Physique-targeting subscription services bundle low-calorie meals with biometric coaching. Traditional retail grocery channels lose traffic to these integrated platforms in the United States and United Kingdom.
- Dietitians:Clinical credibility requirements favor medical nutrition brands with documented outcomes data. Referral influence extends to retail purchase recommendations.
- Weight Control Clinics:Historical channel dominance fragments as mass-market retailers and direct-to-consumer services capture patient volume. Program adherence depends on sensory acceptability of reduced-calorie formulations.
- Fitness Coaches:Social media presence converts training clients to affiliated nutrition products. Commission structures align product recommendations with physique goals.
- Nutritionists:Holistic practice models prioritize ingredient quality narratives over calorie minimization alone. European practitioners emphasize fermentation credentials in dairy recommendations.
Prescriptive authority concentrates with dietitians and weight control clinics; fitness coaches expand their influence fastest through digital client relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for reduced-calorie packaged foods concentrates most visibly in the United States, where private-label expansion at Kroger and Albertsons fragments legacy brand dominance. Reformulation investments accelerate across Germany, Japan, and Brazil as regulatory transparency mandates and gym culture penetration reshape purchase patterns.
United States
Millennial and Gen Z consumers in retail grocery channels expand purchases of reduced-calorie packaged foods. The FDA's updated Nutrition Facts labeling requirements pressure reformulation across branded portfolios. End-cap placements at Kroger and Albertsons determine trial rates for new low-calorie entrants in North American frozen cases.
Germany
Health-conscious consumers prioritize clean-label fermentation credentials in European refrigerated cases. EFSA evaluates novel sweetener approvals under EU 2015/2283, determining reformulated product market access timelines. Berlin and Munich anchor light dairy premium positioning where price multiples exceed standard reduced-fat alternatives.
Japan
Gym members and amateur athletes adopt physique-targeting diets through subscription platforms. The Ministry of Health, Labour and Welfare maintains distinct FOSHU standards creating compliance burdens for multinational portfolios. Tokyo and Osaka concentrate functional food claims approval for reduced-calorie therapeutic formulations.
Brazil
Amateur athletes in São Paulo and Rio de Janeiro represent untapped demand for physique-targeting low-calorie meal solutions. ANVISA governs nutrient content claims on reduced-calorie packaging. Direct-to-consumer subscription channels bypass traditional retail slotting fees and capture lifetime value data.
United Kingdom
Integrated wellness platforms bundle low-calorie meals with biometric coaching, diverting traffic from traditional retail grocery channels. The Food Standards Agency implements front-of-pack calorie disclosure mandates. London anchors digital client relationships where fitness coaches expand influence fastest.
Global Low Calorie Food Market Competitive Landscape
North American producers anchor one tier; European specialists hold fermentation-derived positioning. The vendor base spans multinational conglomerates with ambient grocery distribution dominance, medical nutrition credentialing firms, and precision fermentation technology developers. Three strategic archetypes define competitive positioning: scale-driven shelf-space capturers, clinical credibility sustainers, and clean-label fermentation innovators. M&A activity concentrates on acquiring novel sweetener supply chains and precision fermentation capabilities.
Within the multinational conglomerate tier, Groupe Danone SA and Nestlé S.A. represent divergent geographic anchoring strategies, with the former leveraging fermented dairy expertise and the latter dominating ambient grocery distribution. Abbott Laboratories occupies a distinct position among medical nutrition credentialing firms, sustaining physician and dietitian referral channels. These three companies exemplify how competitive positioning fragments across clinical, retail, and technology-driven archetypes rather than consolidating around uniform scale advantages.
| Leading Market Players |
|---|
| Groupe Danone SA |
| Abbott Laboratories |
| Nestlé S.A. |
| Ajinomoto Co. Inc. |
| Cargill Incorporated |
| PepsiCo Inc. |
| General Mills Inc. |
| Beneo Group |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Stevia leaf and monk fruit extract price indices in China and Southeast Asia cascade through formulation costs into three-tier pricing structures across premium, standard, and economy levels. Contract manufacturers pass agricultural volatility to branded portfolios, while private-label lines at Kroger and Albertsons compress margin structures for legacy diet brands.
Pricing Analysis
High-volume frozen meals and low sugar beverages operate on thin margins, while precision fermentation-derived light dairy commands premium multiples. Price differentiation rests on clean-label certification tier and fermentation credential transparency. Cost compression in standard-tier formulations is intensifying because erythritol supply concentration limits buyer leverage. Private-label supermarket buyers exhibit highest price sensitivity; sports nutrition subscription members tolerate premium positioning for physique-targeting protocols.
Supply Chain Analysis
Refrigerated freight costs from European dairy processing clusters to North American retail distribution centers constrain shelf-life economics for light yogurt formats. Agricultural supply concentrates in China for stevia and monk fruit, in Thailand for tapioca-derived bulking agents, and in the United States for corn-based modified starches. Raw material dependencies draw from high-intensity sweetener extracts, precision fermentation protein isolates, and enzymatically modified starch systems. Single-source vulnerability in erythritol production creates outage exposure. Distribution runs through temperature-controlled logistics networks anchored in regional cold-chain hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global low calorie food markets face supply-constrained dynamics where three suppliers control global erythritol capacity, propping input costs and sustaining pricing power for fermentation-credentialed portfolios.
For Market Incumbents: Extend precision fermentation capabilities into sports nutrition applications before emerging biotech entrants capture amateur athlete subscription relationships. Lock in long-term offtake agreements with Chinese stevia processors to buffer agricultural yield volatility. Channel control through direct-to-consumer platforms reduces slotting fee exposure at Kroger and Albertsons. For New Entrants and Emerging Players: The mid-tier price gap between premium fermentation-credentialed dairy and economy private-label frozen meals offers white-space positioning. Target Brazil and Mexico gym culture penetration with high-protein, low-calorie meal solutions. Bypass traditional retail through biometric-coaching subscription bundles that capture lifetime value data. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation technology developers in European and North American geographies where clean-label credentials command sustainable premiums. Long-term viability centers on therapeutic formulation credibility and captive sweetener supply chains. Monitor ANVISA and FOSHU approval timelines as inflection indicators for emerging market access.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables texture parity in light dairy without hydrocolloid stabilization at lower calorie density. |
| Direct-to-Consumer Platform Launch | Bypasses Kroger and Albertsons slotting fees while capturing biometric data for personalization. |
| Novel Sweetener Supply Agreement | Secures stevia and monk fruit extract offtake from Chinese agricultural processors. |
| FOSHU Claims Approval Pathway | Unlocks premium positioning in Japan's functional food market for therapeutic formulations. |
| Sports Nutrition Brand Extension | Captures physique-targeting demand from Brazil and Mexico amateur athletes. |
Research Methodology
Multi-period observation of reformulation investment flows, regulatory submission timelines, and retail shelf-space allocations anchored the trend analysis, supplemented by interviews with flavor chemists, dairy processing engineers, supermarket category buyers, and sports nutrition subscription platform operators. Secondary validation drew from FDA Food Labeling Guide updates, EFSA novel food evaluations under EU 2015/2283, FOSHU approval databases, and Nielsen retail audit data. Bottom-up SKU-level modeling triangulated against top-down category spending estimates.
Input-output matrices mapped calorie-reduction technology adoption rates against end-use segment growth patterns across the analysis window. Segmentation dimensions modeled include product format, therapeutic application, distribution channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of clean-label penetration rates and fermentation technology maturation curves. Forecast inputs incorporated sweetener price volatility indices and cold-chain logistics capacity expansion.
Inputs from regulatory filing databases and retail point-of-sale systems were available through the study window; gaps in private-label manufacturer cost structures introduce uncertainty bands around margin compression scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Probiotic Drink Market