
 Organic Chips Market | 2026-2036
Organic Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Chips Market Outlook
Subscription-based snack box services is pivoting how organic chips reach repeat buyers, bundling limited-edition flavors with predictable replenishment cycles. Kettle Foods leverages its Pacific Northwest manufacturing base to sustain regional ingredient sourcing. The Hain Celestial Group anchors shelf presence through health-food store exclusivity agreements. Rhythm Superfoods differentiates with air-crisped processing rather than conventional frying.
Organic chips are thin-sliced or extruded snack products manufactured from certified organic tubers, grains, or vegetables, processed without synthetic pesticides or genetically modified inputs, and typically cooked in organic oils at controlled temperatures to achieve specified moisture content below four percent for shelf stability. Potato variants dominate volume due to established consumer familiarity and lower organic input costs, while kale chips command premium positioning through nutrient-density claims and smaller batch production. Supermarkets and hypermarkets control the largest share of distribution channel value, though online retail is expanding fastest as direct-to-consumer platforms capture subscription renewals and trial-size conversions.
The USDA National Organic Program governs certification and labeling integrity across the United States, while the EU Organic Regulation enforces equivalent standards for products entering European retail channels. The FSSAI in India is developing parallel organic certification protocols that will determine market access for imported snack brands. Stakeholders must monitor how evolving compostable packaging mandates from the EU Green Deal interact with existing organic certification requirements to avoid compliance conflicts that could restrict product launch timelines.
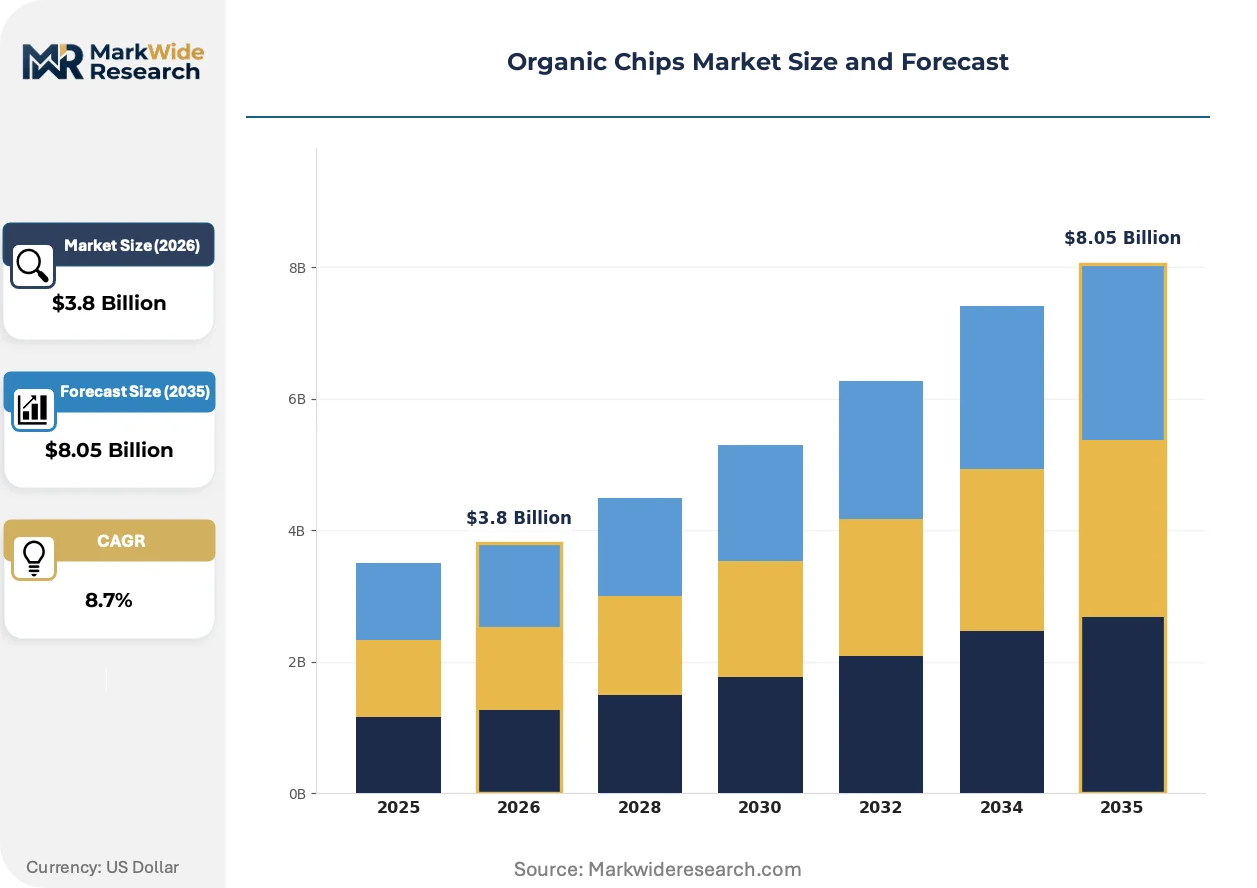
Market Dynamics
Ingredient traceability mandates from the USDA National Organic Program and EU organic labeling standards are compressing supplier qualification timelines and forcing contract renegotiations across the value chain.
Growth Catalysts
- EU Green Deal packaging mandates:Compostable packaging requirements under the EU Green Deal are accelerating R&D investment in biodegradable barrier films for organic chip producers targeting European retail channels.
- Subscription snack box services:Direct-to-consumer replenishment models are capturing repeat purchase behavior among college students and young professionals through limited-edition flavor bundling.
- German discounter expansion:Dedicated organic snack aisle rollouts by Aldi Süd and Lidl in Germany are concentrating demand and validating price premiums for certified organic variants.
Market Restraints
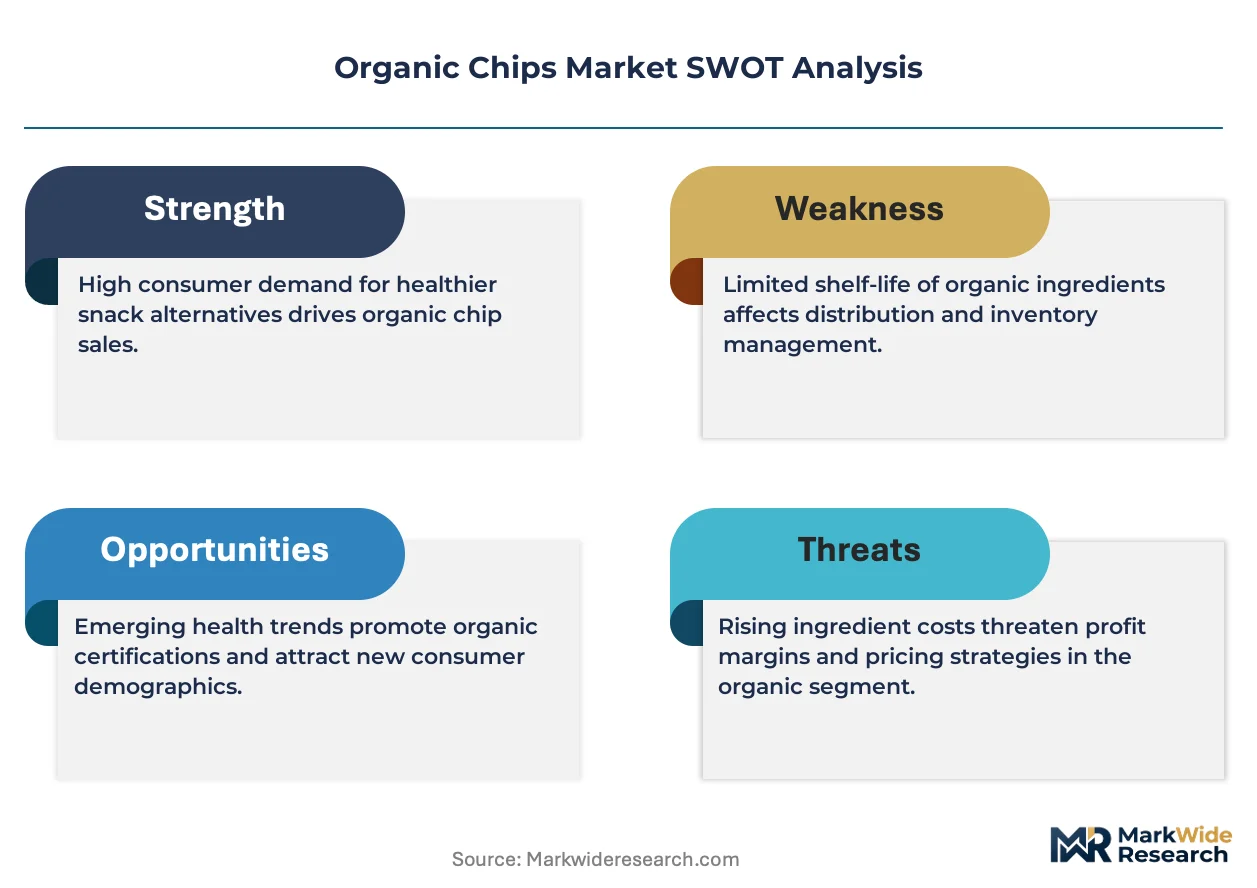
- Organic oil input volatility:Sunflower and coconut oil prices fluctuate with climate-driven harvest variability, compressing gross margins for kettle-cooked producers dependent on organic lipid inputs.
- Pacific Northwest sourcing concentration:Regional ingredient dependence around Kettle Foods' manufacturing base creates geographic supply risk during wildfire seasons and transportation disruptions.
- Moisture content technical ceiling:Shelf stability requirements below four percent moisture constrain processing innovation and limit adoption of alternative base materials with higher intrinsic water content.
Strategic Opportunities
- FSSAI certification protocol development:India's pending organic certification framework creates first-mover positioning for brands establishing local supply partnerships ahead of formal market access rules.
- Air-crisped processing convergence:Combination of radiant heat and vacuum dehydration technologies enables oil-free production claims that differentiate premium positioning from conventional frying.
- On-the-go snack pack sizing:Single-serve portion formats are penetrating convenience retail and campus vending channels previously dominated by conventional chip brands.
Industry Challenges
- USDA NOP certification timeline compression:Three-year land conversion requirements and documentation audits delay new product launches and strain working capital for emerging brands.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking mandates require middleware development that fragments IT budgets and extends implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Chips Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato, Corn, Beetroot, Kale Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Packaging Type: Bags, Resealable Pouches, Bulk Containers, Snack Packs Flavor Profile: Sea Salt, Barbecue, Cheddar, Sour Cream & Onion |
| Companies Covered | Tyrrells Potato Crisps, Rhythm Superfoods, Luke’s Organic, Cape Cod Potato Chips, General Mills, Kettle Foods, Popchips, Boulder Canyon, The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Chips Market Strategic Shifts
Processing technology and packaging material evolution are reshaping how organic chips achieve shelf stability while meeting tightening environmental compliance requirements across multiple jurisdictions.
Air-crisped vacuum dehydration is decentralizing production economics for oil-free organic chip manufacturing. Health-food retailers and specialty grocers are adopting these SKUs at triple-digit velocity in coastal US markets. The technology is decentralizing capital requirements by enabling smaller-batch production without industrial fryer infrastructure.
The EU Green Deal's compostable packaging mandates are forcing material substitutions across imported snack categories. Industrial consequence includes accelerated partnerships between organic chip brands and cellulose-based barrier film developers. German retail chains are most affected, with Rewe and Edeka demanding compliance documentation ahead of enforcement deadlines.
College students and young professionals are consolidating snack purchases around subscription replenishment models with predictable flavor rotation. Campus bookstores and airport convenience channels are losing traffic to direct-to-consumer platforms offering trial-size conversion incentives. This behavioral pivot is most visible in urban US markets and German metropolitan corridors where delivery density supports economical fulfillment.
Organic Chips Market Segmentation
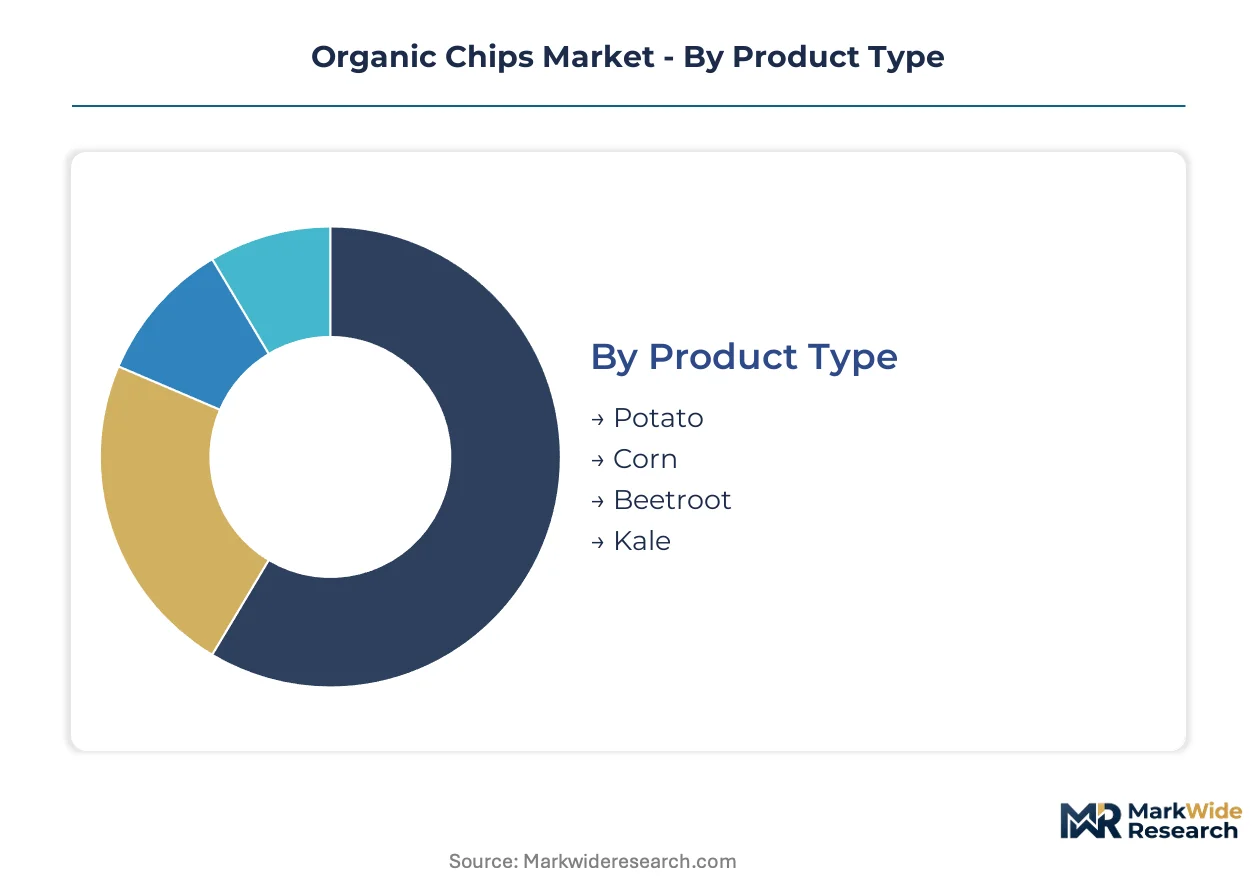
Segmentation in organic chips reveals how certification tiers, channel access, and portion formats create distinct margin profiles. Manufacturers configure production lines around these divides to optimize working capital and shelf placement.
Product Type:
Standardization dominates at the commodity end while premium positioning requires ingredient differentiation and batch-scale flexibility.
- Potato:Thin-sliced tuber base cooked in organic oils at controlled temperatures below four percent moisture. Volume concentrates in German discounter chains where Aldi Süd and Lidl have expanded dedicated organic aisles, though sunflower oil price volatility compresses margins for kettle-cooked variants.
- Kale:Dehydrated leaf structure processed through air-crisped or vacuum technologies without oil submersion. Demand clusters in coastal US health-food retailers where nutrient-density claims support triple-digit velocity, constrained by smaller batch economics and higher organic input costs.
- Corn:Extruded or tortilla-style formats from certified organic maize.
- Beetroot:Sliced root vegetable with natural pigmentation for visual differentiation.
Leading the category by volume: Potato. Growing fastest: Kale.
Distribution Channel:
Channel selection determines working capital intensity and traceability system requirements.
- Supermarkets:Largest value share with standardized shelving fees and centralized procurement. Rewe and Edeka in Germany are demanding EU Green Deal packaging compliance documentation ahead of enforcement deadlines, forcing material substitutions for imported brands.
- Online Retail:Direct-to-consumer platforms capture subscription renewals and trial-size conversions among college students and young professionals. Campus bookstores lose traffic to replenishment models with predictable flavor rotation in urban US and German metropolitan corridors.
- Health Food Stores:Regional exclusivity agreements anchor shelf presence with tighter margin structures.
- Convenience Stores:Single-serve snack pack sizing penetrates vending channels previously dominated by conventional brands.
Dominant by value: Supermarkets. Expanding most quickly: Online Retail.
Packaging Type:
Packaging configuration shapes shelf stability investment and regulatory compliance exposure.
- Bags:Standard barrier film construction for shelf-stable distribution. EU Green Deal compostable mandates are accelerating R&D partnerships with cellulose-based film developers, particularly for German retail entry.
- Snack Packs:Single-serve portions for on-the-go consumption accelerating adoption among college students and young professionals.
- Resealable Pouches:Zip-seal mechanisms for multi-occasion household use.
- Bulk Containers:Food-service and institutional formats with reduced per-unit packaging cost.
Highest volume: Bags. Steepest expansion trajectory: Snack Packs.
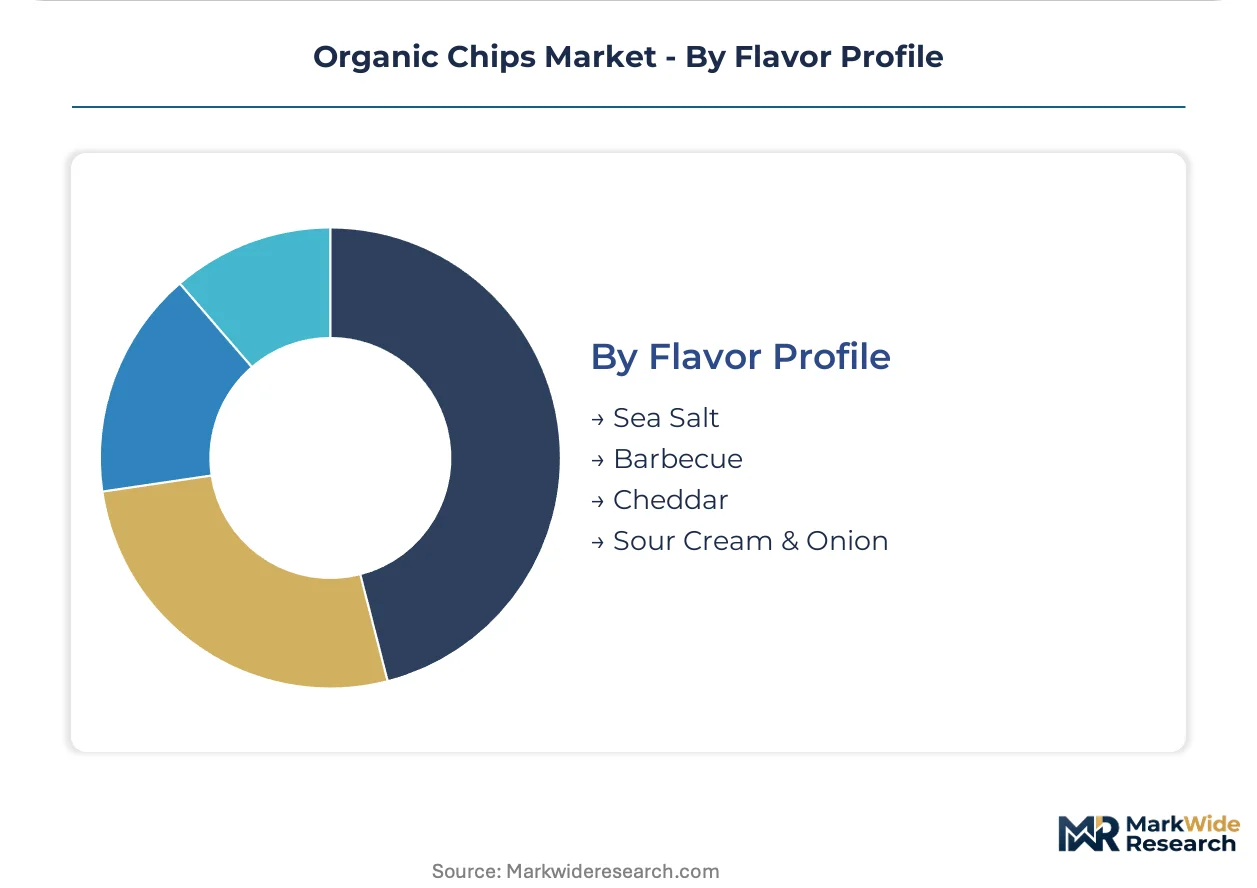
Flavor Profile:
Flavor development balances familiar comfort positioning against limited-edition trial generation.
- Sea Salt:Minimal ingredient declaration supporting clean-label positioning. Subscription snack box services bundle this baseline variant with rotating limited-edition releases to sustain predictable replenishment cycles.
- Barbecue:Smoked and sweetened profiles requiring organic spice and natural sweetener sourcing.
- Cheddar:Organic dairy powder integration for cheese-forward positioning.
- Sour Cream & Onion:Dairy and allium compound layering for flavor complexity.
Baseline volume leader: Sea Salt. Gaining share fastest: Barbecue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in agricultural processing corridors while consumption tilts toward urban agglomerations with higher disposable income and health-conscious demographics. Germany absorbs disproportionate import volume through discounter channel expansion, whereas domestic manufacturing anchors supply in North American organic potato-growing regions.
United States
College students and young professionals drive subscription snack box adoption through direct-to-consumer platforms. The USDA National Organic Program governs certification integrity with three-year land conversion requirements. Pacific Northwest manufacturing bases source regional tuber inputs, though wildfire seasons introduce geographic supply risk.
Germany
Aldi Süd and Lidl have expanded dedicated organic snack aisles, concentrating demand and validating price premiums. The EU Green Deal mandates compostable packaging compliance documentation ahead of enforcement deadlines. Rewe and Edeka retail chains in metropolitan corridors demand barrier film substitutions for imported brands.
India
Urban health-conscious consumers in Delhi-NCR and Mumbai metro areas generate trial-size conversion through online retail channels. The FSSAI is developing parallel organic certification protocols that will determine market access for imported snack brands. Maharashtra and Karnataka agricultural belts are establishing local supply partnerships ahead of formal rules.
United Kingdom
Health-food retailers in London and Southeast England capture triple-digit velocity for air-crisped kale variants. The UK Organic Regulation enforces equivalent standards to EU requirements for labeling integrity. Scottish potato-growing regions supply thin-sliced tuber bases for kettle-cooked production.
Canada
Metropolitan Toronto and Vancouver markets show concentration of subscription replenishment behavior among young professionals. Health Canada maintains organic certification alignment with USDA NOP standards for cross-border trade. Ontario agricultural processing corridors support regional ingredient sourcing for domestic brands.
Organic Chips Market Competitive Environment
Top-tier vendors anchor supermarket and hypermarket shelf presence, while mid-tier specialists occupy health-food retail exclusivity and direct-to-consumer subscription channels. The vendor base stratifies across three functional tiers: diversified food conglomerates with organic portfolio divisions, dedicated organic snack specialists with regional manufacturing concentration, and emerging air-crisped technology adopters with smaller-batch economics. Dominant competitive moves include backward integration into organic oil and tuber supply chains, plus R&D partnerships with cellulose-based barrier film developers for EU Green Deal compliance.
Within the specialist tier, Kettle Foods and Rhythm Superfoods exemplify divergent processing philosophies. Kettle Foods occupies a position tied to Pacific Northwest manufacturing geography and regional ingredient sourcing. Rhythm Superfoods represents the air-crisped technology vector, differentiating through vacuum dehydration rather than conventional frying. The Hain Celestial Group sits within the diversified health-food conglomerate archetype, leveraging portfolio breadth across multiple organic categories.
| Leading Market Players |
|---|
| Tyrrells Potato Crisps |
| Rhythm Superfoods |
| Luke's Organic |
| Cape Cod Potato Chips |
| General Mills |
| Kettle Foods |
| Popchips |
| Boulder Canyon |
| The Hain Celestial Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up snack specialists anchor supply discipline through captive organic oil contracts and long-term tuber offtake agreements, converting certification compliance into pricing power that resists conventional commodity erosion.
Pricing Analysis
Margin tightening in the premium tier reflects sunflower and coconut oil harvest variability compressing kettle-cooked producer economics. Three-tier pricing structure across premium, standard, and economy levels stratifies by USDA NOP certification grade and batch-scale flexibility, with air-crisped kale variants commanding the widest spreads. Price differentiation traces to organic input cost pass-through and health-food retail exclusivity premiums. German discounter buyers show highest price sensitivity, while US coastal health-food consumers demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-consumer channels handle subscription replenishment demand from college students and young professionals, bypassing traditional wholesale distribution. Geographic supply concentrates in the United States Pacific Northwest, Germany, and India's Maharashtra and Karnataka agricultural belts. Raw material dependencies center on certified organic tubers, sunflower oil, and coconut oil. Single-source vulnerability around Pacific Northwest manufacturing bases intensifies during wildfire seasons. Distribution runs through supermarket central procurement, online retail platforms, and health-food store exclusivity agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where USDA National Organic Program three-year land conversion requirements create barrier-to-entry moats for certified incumbents.
For Market Incumbents: Lock in backward integration into organic oil and tuber supply chains to defend against input volatility. Secure EU Green Deal packaging compliance documentation ahead of enforcement deadlines to maintain German retail access. Prioritize R&D partnerships with cellulose-based barrier film developers as the critical lever.
For New Entrants and Emerging Players: Enter via India's pending FSSAI certification protocol development ahead of formal market access rules. Target urban health-conscious consumers in Delhi-NCR and Mumbai through online retail trial-size conversion. Pursue air-crisped processing technology adoption as the differentiated go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor air-crisped technology adopters with smaller-batch economics in US coastal markets. Long-term viability across the analysis window hinges on regulatory compliance infrastructure and channel control depth. Monitor EU Green Deal enforcement deadline adherence as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Inputs | Captive supply of sunflower oil and tubers insulates Kettle Foods from harvest volatility. |
| EU Green Deal Packaging Compliance | Cellulose-based barrier film partnerships secure Rewe and Edeka shelf placement for imported brands. |
| Air-Crisped Processing Scale-Up | Vacuum dehydration technology enables Rhythm Superfoods to bypass industrial fryer capital requirements. |
| Subscription Snack Box Launch | Predictable replenishment cycles capture college students and young professionals from campus bookstores. |
| FSSAI Certification Pre-Positioning | Early supply partnerships in Maharashtra agricultural belts establish first-mover advantage ahead of formal rules. |
Study Parameters
Multi-period observation of organic certification timelines, compostable packaging R&D pipelines, and subscription renewal velocities anchored the trend analysis, supplemented by interviews with organic snack brand managers, supermarket category buyers, health-food retail procurement leads, and FSSAI regulatory affairs specialists. Secondary validation drew from USDA National Organic Program certification databases, EU Organic Regulation enforcement notices, Nielsen retail audit data, and customs import records. Bottom-up volume modeling triangulated against top-down market sizing.
Segment-weighting across product type, distribution channel, packaging format, and flavor profile dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical adoption curves and penetration saturation thresholds. Industry-specific forecast inputs included organic oil price volatility indices and EU Green Deal compliance timeline assumptions.
Revisions become necessary when FSSAI certification protocols materialize with unexpected stringency, or when EU compostable packaging mandates accelerate enforcement timelines. Forecasts reflect documented assumptions on substitution elasticity between conventional and organic snack categories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
United States Popcorn Market
Snacks
Fiber Bars Market
Snacks
Forti Flakes Market
Snacks
Fruit Jerky Market
Snacks
China Snack Bar Market
Snacks
Sweet Potato Chips Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Europe Snack Pellets Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
South East Asia Snack Bar Market
Snacks
Spain Energy Bar Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Low Calorie Crackers Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Nachos Market