
 United States Snack Bar Market | 2026-2036
United States Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
United States Snack Bar Market Analytics
Post-workout recovery consumption among amateur athletes is rebalancing the customer mix away from traditional convenience snacking. General Mills Inc. sustains broad retail shelf presence through multi-brand portfolio depth. Clif Bar & Company specializes in organic ingredient sourcing that commands premium positioning in specialty channels. Mondelēz International Inc. leverages global snack R&D infrastructure to transfer European formulation expertise into US product lines.
The United States snack bar comprises a shelf-stable, individually wrapped baked or extruded food item typically containing grains, proteins, sweeteners, and binding agents, manufactured through cold-press or bake-and-coat processes to achieve a moisture content below fifteen percent for ambient stability. Its primary commercial purpose is to deliver portable, portion-controlled nutrition or indulgence between meals. Protein bars currently lead product type revenue contribution due to sports nutrition crossover appeal, while online retail distribution posts the fastest structural expansion as direct-to-consumer subscription models capture repeat purchase loyalty. Granola bars occupy a mature volume position with thinner margin pools, whereas nut bars concentrate higher per-unit profitability through premium ingredient positioning.
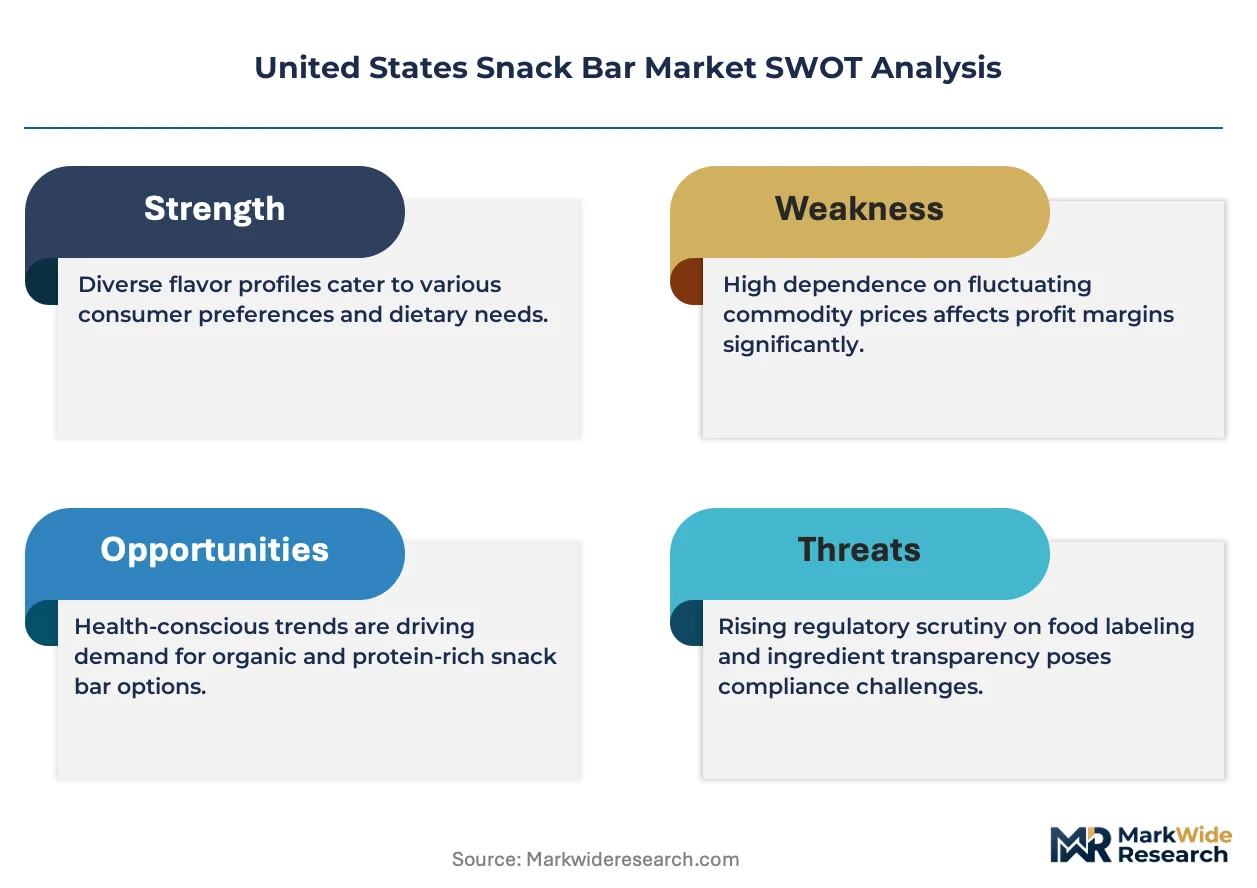
The FDA governs nutrition labeling and health claim substantiation for snack bars, while USDA Organic certification shapes ingredient sourcing requirements and price architecture. The FTC monitors advertising claims around protein content and functional benefits, creating compliance costs that favor established players with legal infrastructure. Stakeholders must monitor evolving FDA guidance on added-sugar thresholds and state-level packaging waste regulations that could mandate material transitions before the forecast horizon closes.
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing reformulation across the entire snack bar category. Manufacturers must rebalance sweetness profiles while maintaining taste parity, compressing R&D timelines and ingredient procurement flexibility.
Growth Catalysts
- Post-workout nutrition adoption:Amateur athletes in California's metropolitan corridors are replacing traditional convenience snacking with functional recovery bars. Specialty retail density in Los Angeles and San Francisco supports premium positioning.
- USDA Organic certification pull:Ingredient sourcing requirements under this framework command price premiums in natural food channels. Certified organic positioning opens shelf space in Whole Foods and Sprouts networks.
- Cold-press manufacturing scale-up:Equipment automation is reducing per-unit production costs for ambient-stable bars. Texas and Colorado processing facilities are expanding capacity for this low-moisture format.
Market Restraints
- Protein input cost volatility:Whey and plant-based protein isolate prices fluctuate with dairy commodity cycles and pea protein harvest yields. Margin compression hits mid-tier brands hardest.
- Supply concentration in almond sourcing:California Central Valley growers supply eighty percent of domestic almond volume. Water allocation disputes and drought cycles threaten ingredient security.
- FTC advertising claim friction:Protein content substantiation and functional benefit language face heightened scrutiny. Compliance legal infrastructure favors established players with dedicated regulatory teams.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail distribution is capturing repeat purchase loyalty outside traditional grocery slotting. Custom flavor profiles and delivery cadence personalization reduce customer acquisition costs.
- State-level packaging waste regulations:California's extended producer responsibility mandates are creating first-mover advantage for compostable wrapper adoption. Material innovation partnerships with flexible packaging converters open differentiation.
- Functional ingredient convergence:Adaptogenic botanicals and nootropic compounds are merging with traditional sports nutrition formulations. This crossover appeals to cognitive performance seekers in urban professional segments.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning bake-and-coat and cold-press processes commands premium compensation. Mid-size manufacturers struggle to retain R&D leadership against CPG conglomerates.
- Dual certification timeline compression:Simultaneous FDA nutrition label compliance and USDA Organic recertification strains quality assurance bandwidth. Audit scheduling bottlenecks delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Snack Bar Market |
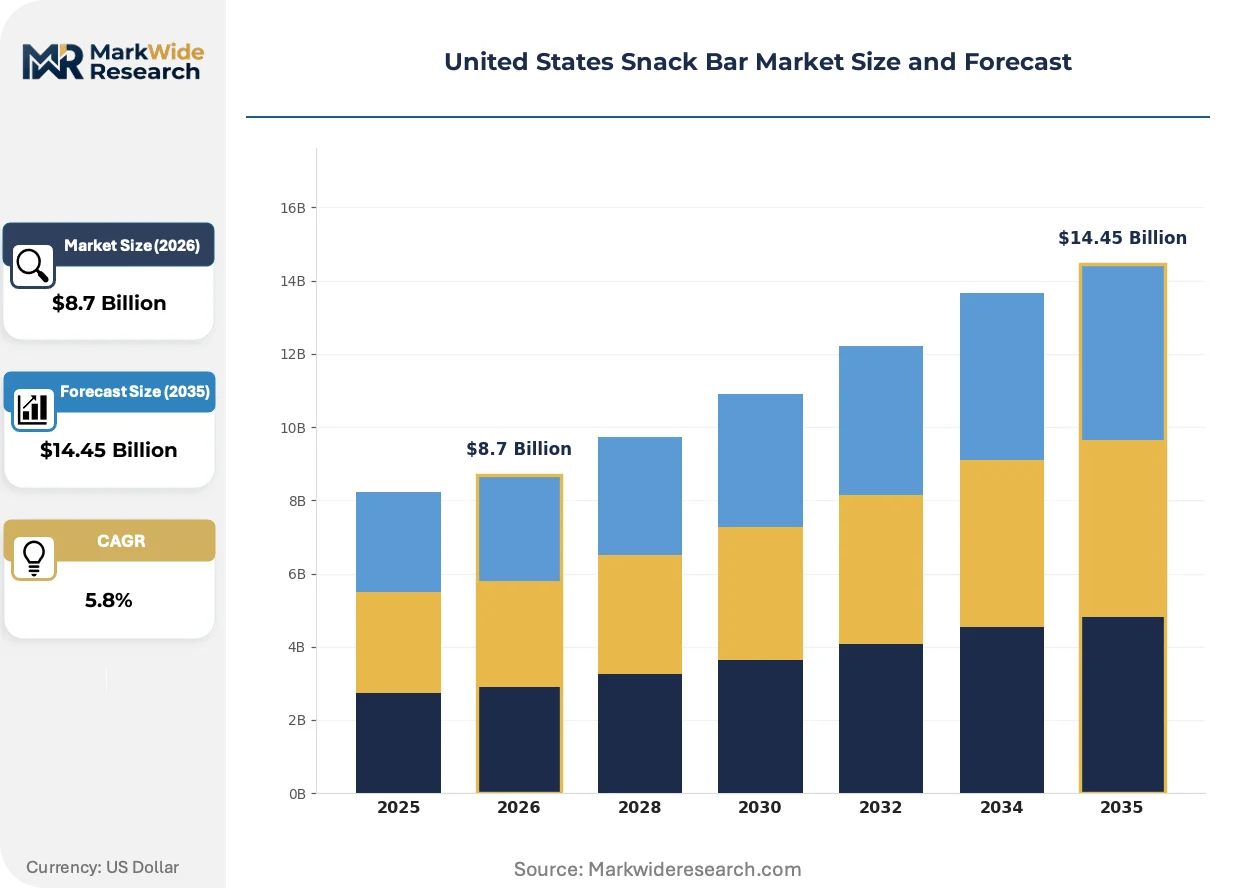
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Nut Bars, Snack Cakes Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Health Conscious Consumers, Busy Professionals, Students, Athletes Flavor Profile: Chocolate, Fruit, Vanilla, Savory |
| Companies Covered | General Mills Inc., Mars Inc., Mondelēz International Inc., Kellanova, PepsiCo Inc., The Simply Good Foods Co., Clif Bar & Company, The Quaker Oats Company, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Snack Bar Market Evolving Landscape
Reformulation priorities are pivoting around sugar reduction technologies and clean-label binding systems. Manufacturers face compressed development cycles as regulatory deadlines approach.
Cold-press extrusion technology is consolidating control over texture and shelf stability in protein-dense formulations. Sports nutrition brands are adopting this equipment at accelerated pace. The shift is compressing reliance on traditional bake-and-coat infrastructure and enabling higher inclusion rates of heat-sensitive functional ingredients.
The FDA's added-sugar disclosure mandate is restructuring front-of-package communication strategies. Manufacturers must recalibrate sweetness architectures using monk fruit, allulose, and fiber-based bulking agents. Protein bars targeting amateur athletes face the steepest reformulation burden as these buyers scrutinize nutritional transparency.
Amateur athlete purchasing patterns are fragmenting across specialty running stores, CrossFit affiliates, and direct subscription platforms. Traditional grocery slotting fees lose leverage as these alternative channels capture trial and loyalty. California's functional food retail corridor exhibits the most pronounced channel diversification, with Los Angeles and San Francisco metro areas leading subscription adoption rates.
United States Snack Bar Market Segmentation
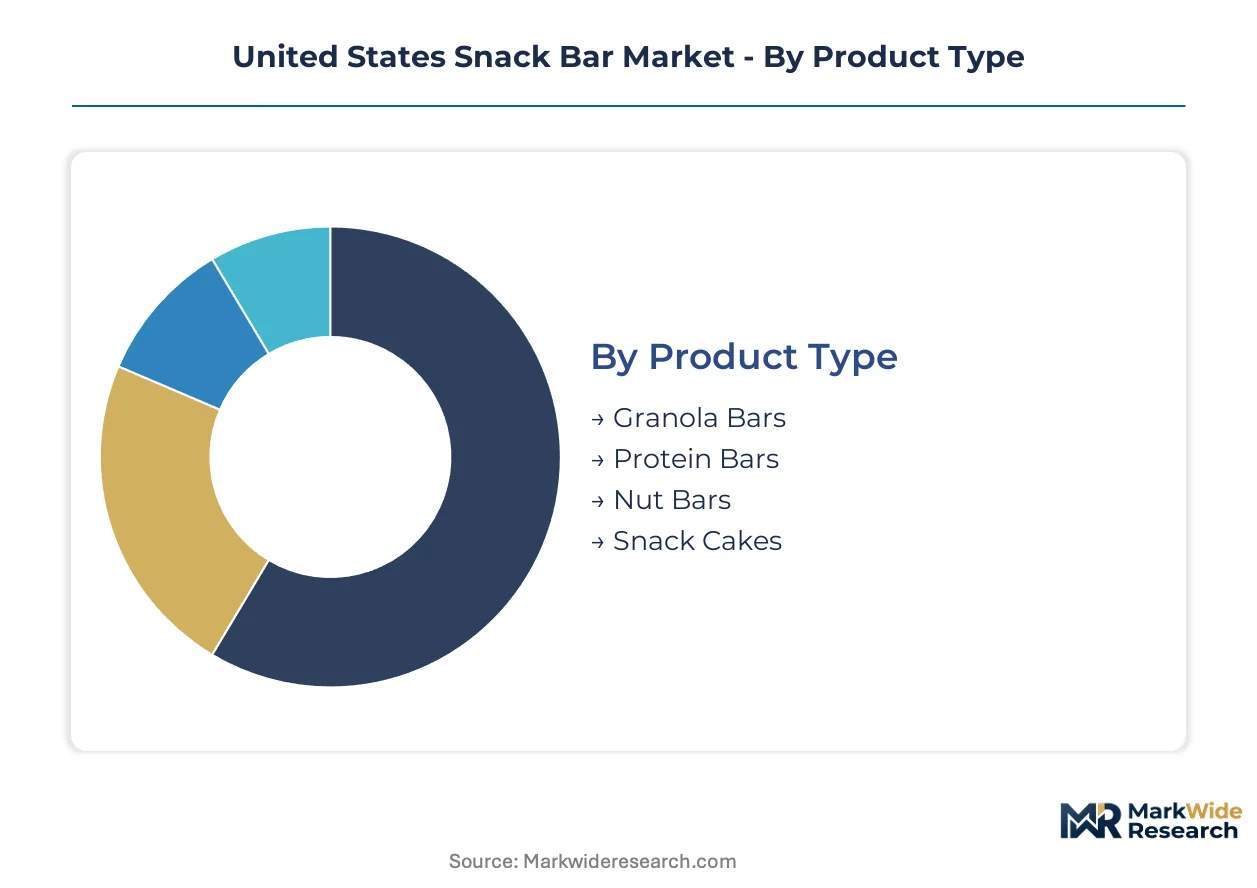
Segmentation in the United States snack bar market reveals how distinct buyer motivations reshape product development and channel strategy. Each dimension exposes tension between convenience-driven mass consumption and premium functional positioning.
Product Type:
Buyers in this category separate by nutritional intent versus indulgence preference, with ingredient density and protein content driving price tolerance.
- Protein Bars:Cold-press extruded formulations achieve sub-fifteen percent moisture for ambient stability. Amateur athletes in California's metropolitan corridors favor these for post-workout recovery, with specialty retail density in Los Angeles and San Francisco supporting premium positioning.
- Granola Bars:Bake-and-coat processing with oat and honey bases delivers familiar texture at accessible price points. Volume concentrates in traditional grocery channels, though margin compression limits innovation investment.
- Nut Bars:Almond and cashew-dense formulations command ingredient cost premiums. California Central Valley sourcing concentration creates supply vulnerability during drought cycles.
- Snack Cakes:Indulgence-positioned baked goods with higher sugar content face FDA added-sugar disclosure pressure. Reformulation toward clean-label binding systems is accelerating.
Granola bars lead volumes today; protein bars are gaining share fastest.
Distribution Channel:
Channel selection reflects purchase occasion frequency and buyer willingness to trade immediate access against subscription convenience.
- Online Retail:Direct-to-consumer subscription models capture repeat purchase loyalty through custom flavor profiles and delivery cadence personalization. Customer acquisition costs fall as data-driven targeting improves.
- Specialty Stores:Whole Foods and Sprouts networks demand USDA Organic certification as table stakes. Shelf placement requires proven velocity or exclusive SKUs.
- Supermarkets:Slotting fees and promotional calendars favor multi-brand portfolios with marketing scale. Private label pressure intensifies in standard granola formats.
- Convenience Stores:Impulse-driven single-serve purchases prioritize brand recognition and packaging visibility. Protein bars are displacing traditional candy in urban locations.
Supermarkets dominate transaction volume; online retail is climbing the fastest.
Customer Type:
Distinct usage occasions separate buyers by time-of-day consumption patterns and nutritional scrutiny intensity.
- Athletes:Amateur competitors in CrossFit affiliates and running clubs prioritize post-workout recovery macros. These buyers scrutinize FDA nutrition labels for protein content substantiation.
- Health Conscious Consumers:Clean-label seekers drive organic ingredient premiums and reject artificial sweeteners. Monk fruit and allulose adoption concentrates in formulations targeting this segment.
- Busy Professionals:Meal replacement occasions favor portion-controlled calorie density. Urban professional segments show rising interest in adaptogenic and nootropic ingredient convergence.
- Students:Price-sensitive trial buyers favor multi-pack value formats. Brand switching rates exceed other segments during promotional periods.
Health conscious consumers anchor category value; athletes are expanding most quickly.
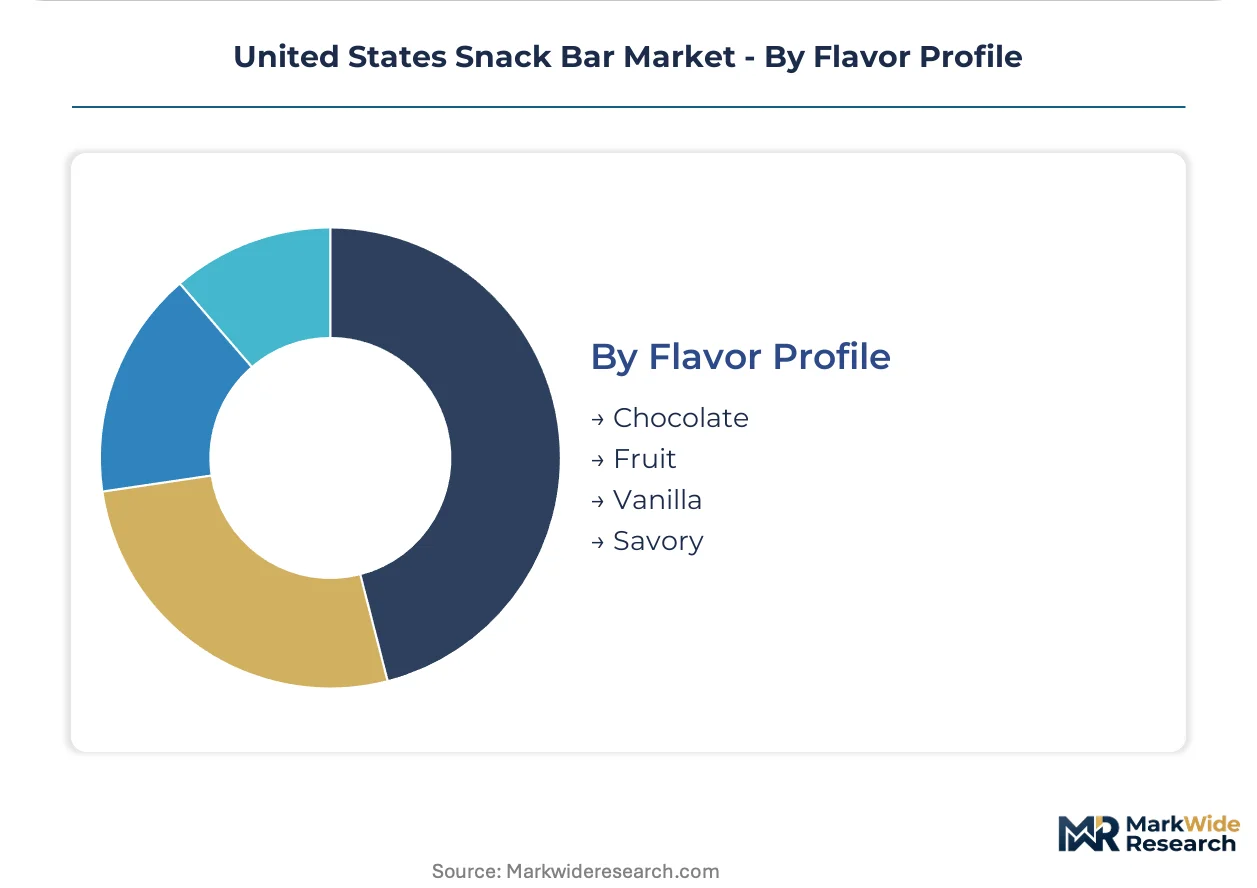
Flavor Profile:
Taste architecture decisions intersect with sugar reduction mandates and clean-label binding system limitations.
- Chocolate:Cocoa-based coatings mask protein aftertaste in high-inclusion formulations. Allulose and fiber-based bulking agents replace sucrose to meet FDA disclosure thresholds.
- Fruit:Dried fruit inclusions provide natural sweetness and texture contrast. Supply concentrates in Pacific Northwest berry processors and Turkish fig importers.
- Vanilla:Neutral base supports functional ingredient layering without flavor competition. Popular in adaptogenic formulations targeting cognitive performance seekers.
- Savory:Emerging profile in nut bars and seed-heavy formats. Seaweed, herb, and spice inclusions appeal to snacking occasions outside traditional sweet consumption windows.
Chocolate dominates current formulation runs; savory is showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as FDA compliance costs concentrate production in states with lower operational overhead. Water allocation disputes in California's Central Valley are accelerating ingredient sourcing diversification.
California
Amateur athlete density in Los Angeles and San Francisco metros drives premium protein bar demand through specialty retail channels. The state's extended producer responsibility mandates for packaging waste are forcing compostable wrapper adoption ahead of other regions. Almond sourcing concentration in the Central Valley creates drought-vulnerable supply chains that manufacturers are actively hedging.
Texas
Cold-press manufacturing capacity is expanding across Dallas-Fort Worth and Austin processing corridors to serve national distribution networks. The Texas Commission on Environmental Quality oversees air quality permits for expanded bakery and extrusion facilities. Houston's port infrastructure supports imported ingredient flows from Latin American nut and dried fruit suppliers.
Colorado
Outdoor recreation culture in Denver and Boulder anchors demand for organic-certified sports nutrition products. The Colorado Department of Public Health and Environment regulates food manufacturing licensing with streamlined pathways for small-batch producers. Fort Collins has emerged as a cluster for craft protein bar innovation targeting trail running and cycling segments.
Pacific Northwest
Clean-label ingredient sourcing from Oregon and Washington berry processors supplies natural sweetness alternatives to reformulating manufacturers. State-level organic certification support programs reduce compliance friction for emerging brands. Seattle's tech workforce sustains direct-to-consumer subscription adoption rates above national averages.
Midwest
Grain processing infrastructure in Illinois and Minnesota underpins cost-efficient granola bar manufacturing for mass retail channels. The Illinois Department of Agriculture coordinates with FDA on food safety modernization act implementation. Chicago's logistics hub position enables just-in-time distribution to eastern seaboard markets.
United States Snack Bar Market Competitive Landscape
Portfolio diversification dominates the current landscape as conglomerates absorb specialty brands to capture functional food premiums. The market structure exhibits tiered consolidation with three distinct player categories. Multi-brand CPG conglomerates leverage grocery slotting fee scale against mid-tier organic specialists commanding specialty channel premiums. Emerging direct-to-consumer startups exploit subscription loyalty mechanics outside traditional retail. Dominant competitive moves include strategic brand acquisitions and cold-press capacity expansion in Texas and Colorado processing corridors.
Within the conglomerate tier, General Mills Inc., Mars Inc., and Mondelēz International Inc. exemplify scale-driven positioning through multi-brand portfolio depth. These players anchor mass retail presence while absorbing compliance costs that strain smaller competitors. The mid-tier organic specialists occupy premium positioning through USDA Organic certification and specialty channel relationships. Direct-to-consumer startups represent the fastest-growing archetype as subscription models capture repeat purchase loyalty with personalized flavor and delivery cadence options.
| Leading Market Players |
|---|
| General Mills Inc. |
| Mars Inc. |
| Mondelēz International Inc. |
| Kellanova |
| PepsiCo Inc. |
| The Simply Good Foods Co. |
| Clif Bar & Company |
| The Quaker Oats Company |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Premium-mass bifurcation between USDA Organic certified lines and conventional formulations manifests in divergent margin architectures and sourcing footprints across the United States snack bar market. Organic certification commands ingredient premiums that flow through specialty retail channels, while commodity granola formats compete on scale economies through Midwest grain processing corridors.
Pricing Analysis
Distributor margin layers absorb the steepest compression in mass-market granola bars, where private label pressure and slotting fee structures constrain net realized prices. Three-tier pricing structure across premium organic, standard natural, and economy conventional levels separates Clif Bar positioning from Quaker Oats volume plays. Cost compression in protein-dense formats is intensifying because whey and pea protein isolate inputs fluctuate with dairy commodity cycles. Students represent the most price-sensitive buyer archetype, while amateur athletes in California metros tolerate premium positioning for post-workout recovery formulations.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale demand from Walmart and Kroger networks, while specialty distributors serve Whole Foods and Sprouts with smaller-batch organic SKUs. Almond sourcing concentrates in California's Central Valley, with secondary flows from Spain and Australia hedging drought exposure. Whey protein isolate draws from Wisconsin dairy processing, plant proteins from Canadian pea protein extraction facilities. Single-source vulnerability in California almond supply creates ingredient security risk during water allocation disputes. Distribution runs through Chicago logistics hubs for eastern seaboard markets and Dallas-Fort Worth for southwestern coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States snack bar market functions as a stable compounder anchored by persistent post-workout nutrition adoption among amateur athletes. Functional food retail density in California metros sustains premium pricing power that offsets commodity input volatility.
For Market Incumbents: Lock in cold-press manufacturing capacity in Texas and Colorado corridors before equipment lead times extend. Secure long-term almond supply contracts with Central Valley growers to hedge drought-driven price spikes. Defensive consolidation of mid-tier organic brands preserves shelf space leverage against direct-to-consumer subscription entrants.
For New Entrants and Emerging Players: Cold-press extrusion technology with adaptogenic ingredient integration offers white-space positioning in cognitive performance bars for urban professionals. Target Pacific Northwest subscription adoption rates above national averages through Seattle tech workforce penetration. Savory flavor profiles in nut bars represent the most penetrable segment outside traditional sweet consumption windows.
For Investors and Strategic Acquirers: Asymmetric upside sits with direct-to-consumer startups possessing proprietary subscription algorithms and custom flavor personalization capabilities. Five-to-ten year viability favors brands with USDA Organic certification moats and established specialty channel velocity. Watch FDA added-sugar threshold guidance evolution as inflection indicator for reformulation cost burdens that favor scaled players.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Capacity Expansion | Texas and Colorado facilities reduce per-unit costs for ambient-stable protein bars. |
| USDA Organic Certification Investment | Opens shelf placement in Whole Foods and Sprouts networks with velocity requirements. |
| Direct-to-Consumer Subscription Launch | Captures repeat purchase loyalty outside traditional grocery slotting fee structures. |
| Compostable Wrapper Material Transition | California extended producer responsibility mandates create first-mover differentiation. |
| Adaptogenic Ingredient Integration | Functional convergence appeals to cognitive performance seekers in urban professional segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged brand managers at CPG conglomerates, category buyers at Kroger and Albertsons, supply planners at co-manufacturing facilities, and regulatory affairs leads navigating FDA nutrition label compliance. Secondary validation drew from Nielsen retail audit data, USDA organic certification databases, FDA guidance documents, and SEC 10-K filings from publicly traded snack bar parent companies. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates from consumer panel data.
Segment-weighting approaches assigned differential growth coefficients across protein bars, granola bars, nut bars, and snack cakes based on amateur athlete penetration rates and organic certification adoption curves. Distribution channel splits modeled online retail acceleration against supermarket and convenience store velocity trends. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory deadline impacts and ingredient cost cycles. Cold-press manufacturing capacity buildouts and California water allocation scenarios served as industry-specific scenario inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA added-sugar threshold adjustments and almond supply disruption frequency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Cookies Market
Snacks
Baked Chips Market
Snacks
Edible Flakes Market
Snacks
Italy Energy Bar Market
Snacks
Europe Popcorn Market
Snacks
Sweet Potato Fries Market
Snacks
Low Fat Crackers Market
Snacks
North America Extruded Snack Food Market
Snacks
India Energy Bar Market
Snacks
Gluten Free Snacks Market
Snacks
Meat Snacks Market
Snacks
Corn Chips Market
Snacks
Europe Snack Pellets Market
Snacks
Germany Snack Bar Market
Snacks
Specialty Snacks Market
Snacks
Low Fat Sweet Snacks Market