
 Organic Snacks Market | 2026-2036
Organic Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Snacks Market Intelligence
The distinction between premium, functional snacks and basic, private-label organic offerings is hardening. The Hain Celestial Group, Inc. leverages its diverse portfolio to compete across multiple price points and product categories. Clif Bar & Company specializes in the performance nutrition segment, targeting fitness enthusiasts with high-protein bars. Meanwhile, large players like General Mills, Inc. utilize extensive distribution networks to push their organic lines into mainstream retail channels.
Organic snacks are food items produced without synthetic pesticides, fertilizers, or genetically modified organisms, intended for consumption between main meals. Their primary purpose is to offer convenient, clean-label nutrition that meets consumer demand for sustainable and healthy food choices. Within product types, granola bars and nut mixes represent mature segments, while vegetable chips are gaining traction. A significant shift in distribution channels sees online retailers and direct-to-consumer models capturing market share from traditional health food chains.
Market access is governed by stringent certification frameworks, including the USDA's National Organic Program, the EU's 'Euro-leaf' logo, and Japan's Agricultural Standard (JAS). These regulations establish non-negotiable standards for production and labeling, directly influencing supply chain integrity and consumer confidence. Stakeholders must now navigate emerging regulations on sustainable packaging and the verification of claims related to regenerative agricultural practices.
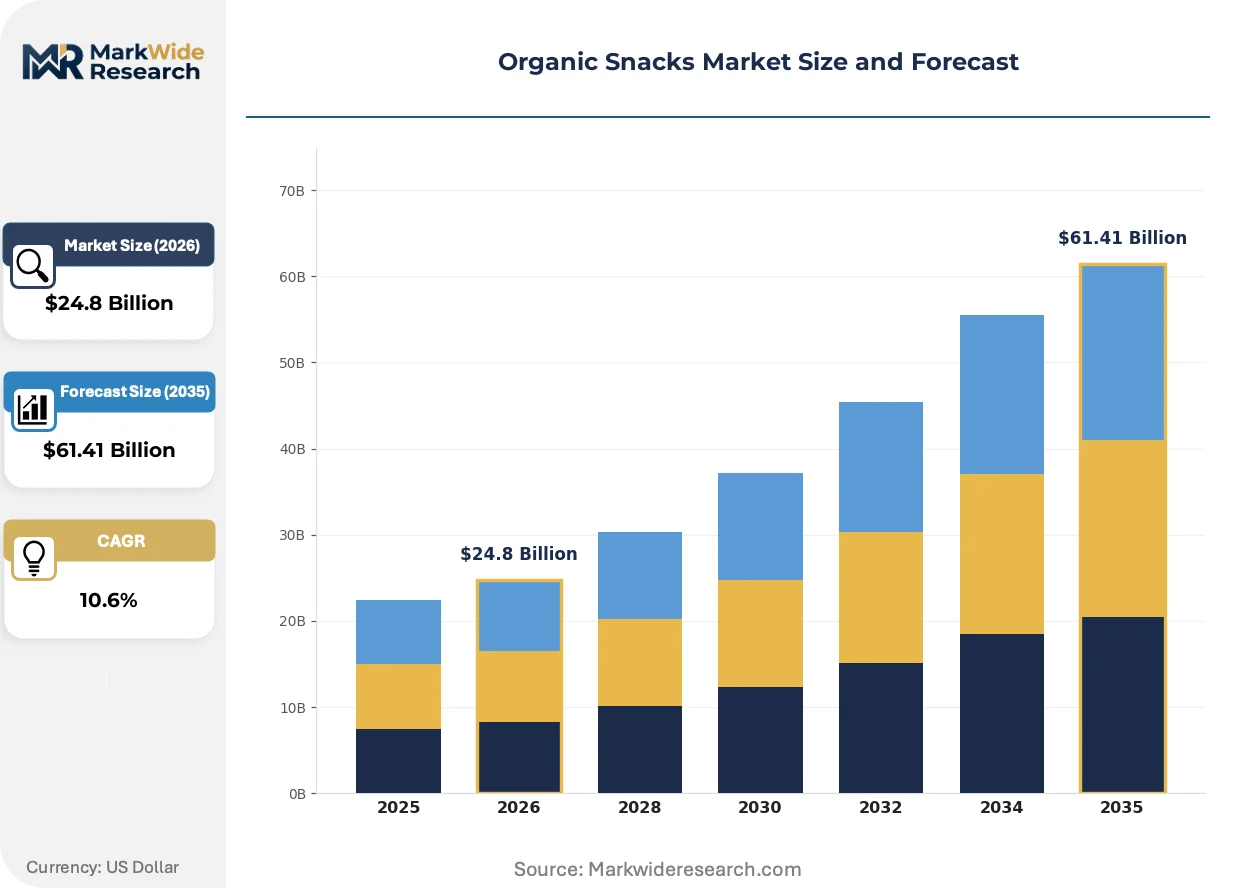
Market Dynamics
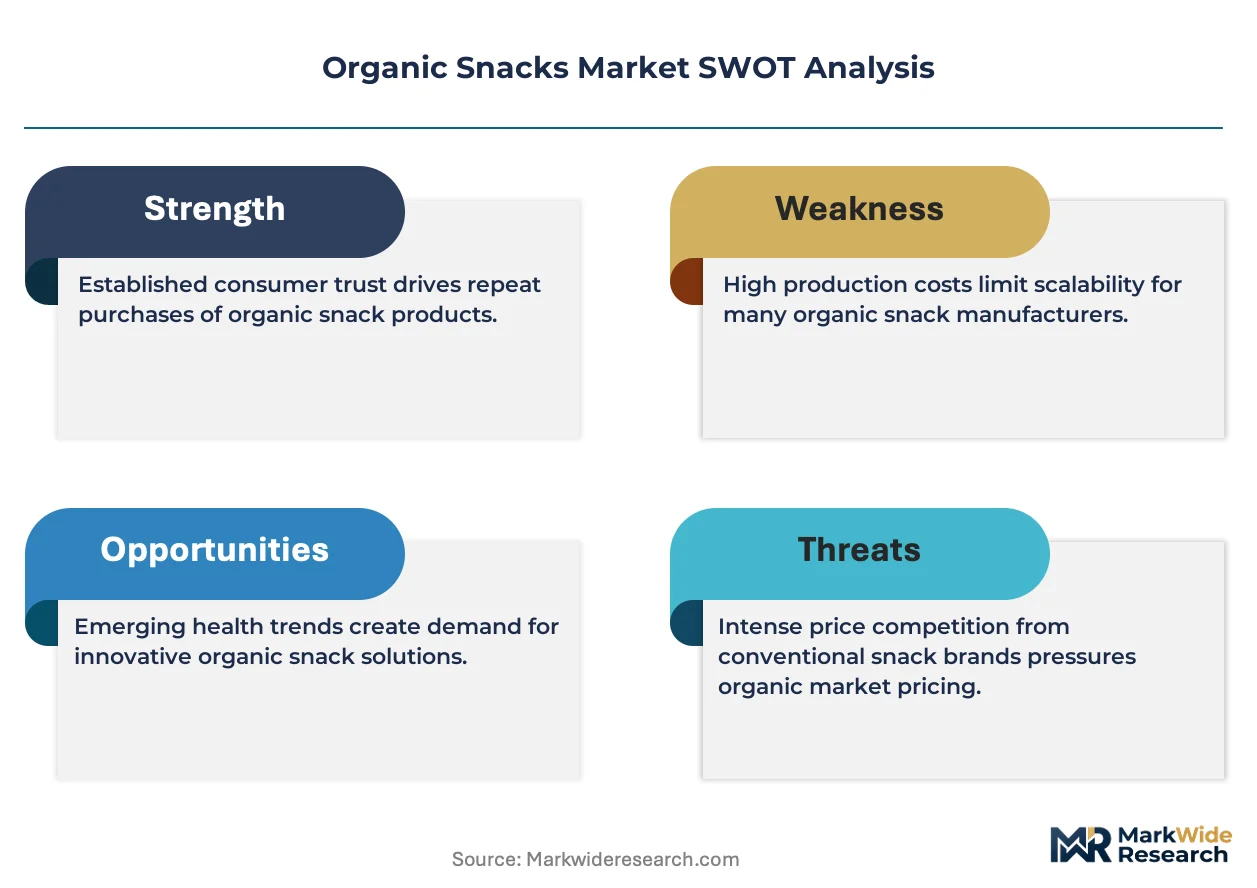
The organic snacks market is defined by the tension between mainstream consumer demand for convenient, healthy options and the stringent, often costly, agricultural and processing standards required for certification. This dynamic forces a clear separation between high-volume, lower-margin products in mass retail and premium, functionally-differentiated offerings in specialty channels.
Growth Catalysts
- Harmonized Standards:The increasing alignment between regulatory frameworks, such as the USDA's National Organic Program and the EU's organic farming rules, simplifies cross-border trade and expands market access for certified producers into new geographic territories.
- Consumer Health Consciousness:Heightened consumer focus on clean-label ingredients and preventative health, particularly among working professionals in developed economies like Germany and France, fuels demand for certified organic snacks as a trusted dietary choice.
- Channel Diversification:The expansion of online retail and direct-to-consumer (DTC) platforms lowers the barrier to entry for niche brands, allowing them to reach targeted consumer segments without competing for limited shelf space in traditional grocery stores.
Market Restraints
- Price Premiums:The higher cost of organic farming practices, including the use of natural fertilizers and pest control, coupled with certification fees, results in a significant price gap compared to conventional snacks, limiting accessibility for price-sensitive consumers.
- Supply Chain Volatility:Organic ingredient supply chains are often less resilient than conventional ones, with greater susceptibility to climate events and pest outbreaks, leading to price fluctuations and potential shortages for key inputs like nuts and ancient grains.
- Substitution from "Natural" Products:Competition from products marketed as "natural" or "clean-label" but lacking official organic certification creates consumer confusion and presents a lower-cost alternative that erodes market share for certified organic goods.
Strategic Opportunities
- Functional Formulations:There is significant white space for developing organic snacks fortified with functional ingredients like probiotics, adaptogens, or plant-based proteins, catering to consumers seeking specific health outcomes beyond basic nutrition.
- Sustainable Packaging:Innovating in compostable or recyclable packaging materials provides a key differentiator, appealing to environmentally conscious consumers and aligning with emerging regulations on packaging waste in jurisdictions like the European Union.
- Geographic Expansion:Targeting middle-class consumers in emerging markets across Asia and Latin America, where disposable incomes and health awareness are rising, offers a substantial new growth frontier for established organic snack brands.
Industry Challenges
- Certification Complexity:Navigating and maintaining compliance with the diverse and evolving certification standards across multiple jurisdictions, including the USDA NOP, EU 'Euro-leaf', and Japanese Agricultural Standard (JAS), represents a significant operational and administrative burden.
- Fraud Prevention:Ensuring supply chain integrity and preventing fraudulent claims of organic status require substantial investment in traceability technologies and rigorous auditing, posing a challenge for producers sourcing ingredients globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Snacks Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $61.41 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Dried Fruits, Nut Mixes, Vegetable Chips, Rice Cakes Packaging Type: Resealable Pouches, Boxes, Tubs, Compostable Wraps, Glass Jars Distribution Channel: Specialty Stores, Health Food Chains, Online Retailers, Direct-to-Consumer, Pharmacies Customer Type: Fitness Enthusiasts, Children, Working Professionals, Seniors, Students |
| Companies Covered | Nature’s Path Organic Foods Inc., Nestlé S.A., Clif Bar & Company, Danone S.A., Conagra Brands, Inc., General Mills, Inc., The Hain Celestial Group, Inc., SunOpta Inc., Kellanova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Snacks Market Strategic Shifts & Innovations
The market's evolution is marked by a push beyond foundational organic claims toward holistic value propositions. This includes an emphasis on regenerative agricultural practices, ingredient circularity, and transparent sourcing narratives that resonate with educated consumers.
Upcycled ingredients, which transform food manufacturing byproducts into valuable nutritional inputs, are gaining traction. Niche and premium brands are leading the adoption of these materials, such as spent grain from brewing or fruit pulp from juicing, to appeal to environmentally-focused consumers. This innovation is rewriting the economics of food waste, creating a new value stream while enhancing the sustainability credentials of finished snack products.
New regulations focused on packaging sustainability, particularly mandates within the EU Green Deal, are altering material choices. These rules compel manufacturers to move away from non-recyclable multi-layer films commonly used to preserve freshness in snacks. The savory snacks category, including organic chips and crackers, is most impacted and is actively investing in the development of viable paper-based and certified compostable flexible packaging solutions.
A distinct behavioral shift sees consumers moving from large, consolidated grocery trips to smaller, more targeted purchases through digital channels. This trend is disrupting the dominance of traditional supermarkets, with direct-to-consumer websites and curated subscription boxes capturing significant market share. This channel disintermediation is most visible among younger consumer cohorts in major North American and Western European metropolitan areas.
Organic Snacks Market Segmentation
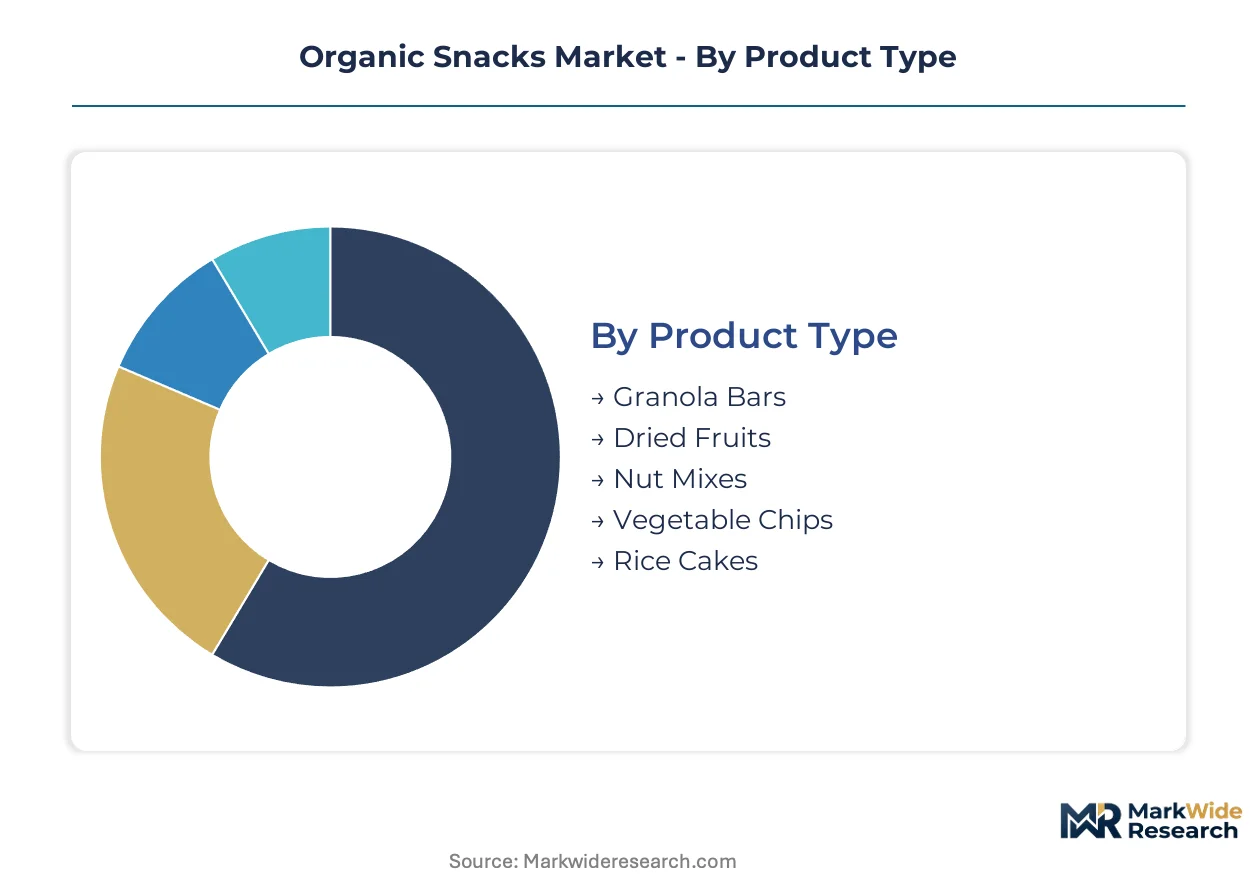
Market segmentation clarifies the distinct consumption patterns and operational requirements within the organic snacks industry. Understanding these divisions helps stakeholders tailor product development, optimize distribution strategies, and refine marketing efforts. This granular analysis reveals where value accrues and how different consumer needs are being met across various product types and channels.
Product Type:
The organic snacks market exhibits a clear divergence between high-volume, established product categories and newer, premium offerings that command higher price points.
- Granola Bars:These items combine rolled oats, nuts, and dried fruit, often bound with honey or syrup, providing sustained energy. Demand concentrates among working professionals in urban centers like Berlin and London, driven by the need for convenient, on-the-go nutrition.
- Vegetable Chips:These snacks are typically made from thinly sliced and dehydrated root vegetables or leafy greens, offering a savory, nutrient-dense alternative. Consumer interest in these products is particularly high in health-conscious markets such as Sweden and Australia, fueled by clean-label ingredient preferences.
- Dried Fruits:These products include dehydrated berries, apples, or mangoes, serving as naturally sweet and portable snack options.
- Nut Mixes:Blends of various organic nuts and seeds provide protein-rich snacking, appealing to consumers seeking satiety and healthy fats.
- Rice Cakes:These puffed rice discs offer a light, gluten-free base for toppings, popular among individuals managing dietary restrictions.
Mature deployment sits with Granola Bars. Newer deployment is concentrated in Vegetable Chips.
Packaging Type:
Packaging solutions for organic snacks differentiate products based on their functional attributes, influencing shelf life, convenience, and environmental impact.
- Compostable Wraps:These innovative materials, often plant-based, biodegrade under specific conditions, addressing consumer and regulatory demands for sustainability. Adoption is growing significantly in regions like the European Union, where the EU Green Deal mandates reductions in plastic waste.
- Resealable Pouches:These flexible plastic or multi-layer film bags feature a zipper closure, preserving freshness and offering convenience for multi-serving snacks. Their widespread use in the US and Canada reflects consumer preference for practicality and extended product viability.
- Boxes:Cardboard or paperboard boxes provide structural integrity and branding space, commonly used for multi-pack granola bars or individual snack portions.
- Tubs:Rigid plastic or paperboard tubs offer robust protection for bulk snacks like nuts or dried fruit, facilitating easy storage and access.
- Glass Jars:Glass containers present a premium, reusable option for organic snacks, appealing to consumers prioritizing aesthetic and environmental considerations.
Cost-effective packaging solutions dominate the mass market, while premium, sustainable options are gaining share fastest among environmentally conscious consumers.
Distribution Channel:
The channels through which organic snacks reach consumers are diversifying, reflecting shifts in purchasing habits and brand strategies for market penetration.
- Online Retailers:E-commerce platforms provide extensive reach and convenience, enabling consumers to access a broad assortment of organic snack brands from home. This channel is experiencing rapid expansion across North America and Western Europe, driven by digital literacy and logistical efficiencies.
- Direct-to-Consumer:Brands sell organic snacks directly to consumers via their own websites or subscription services, fostering brand loyalty and offering personalized experiences. Niche brands leverage this model to bypass traditional retail barriers, particularly in markets like the United Kingdom and Germany.
- Specialty Stores:These retailers focus on curated selections of organic and gourmet foods, catering to consumers seeking unique or high-quality ingredients.
- Health Food Chains:Dedicated health food supermarkets offer a wide range of organic products, serving as a primary destination for health-conscious shoppers.
- Pharmacies:A limited but growing number of pharmacies stock organic snacks, positioning them as health-supporting products for wellness-focused individuals.
Traditional brick-and-mortar channels maintain foundational sales, but digital platforms are increasingly disrupting established market access paradigms.
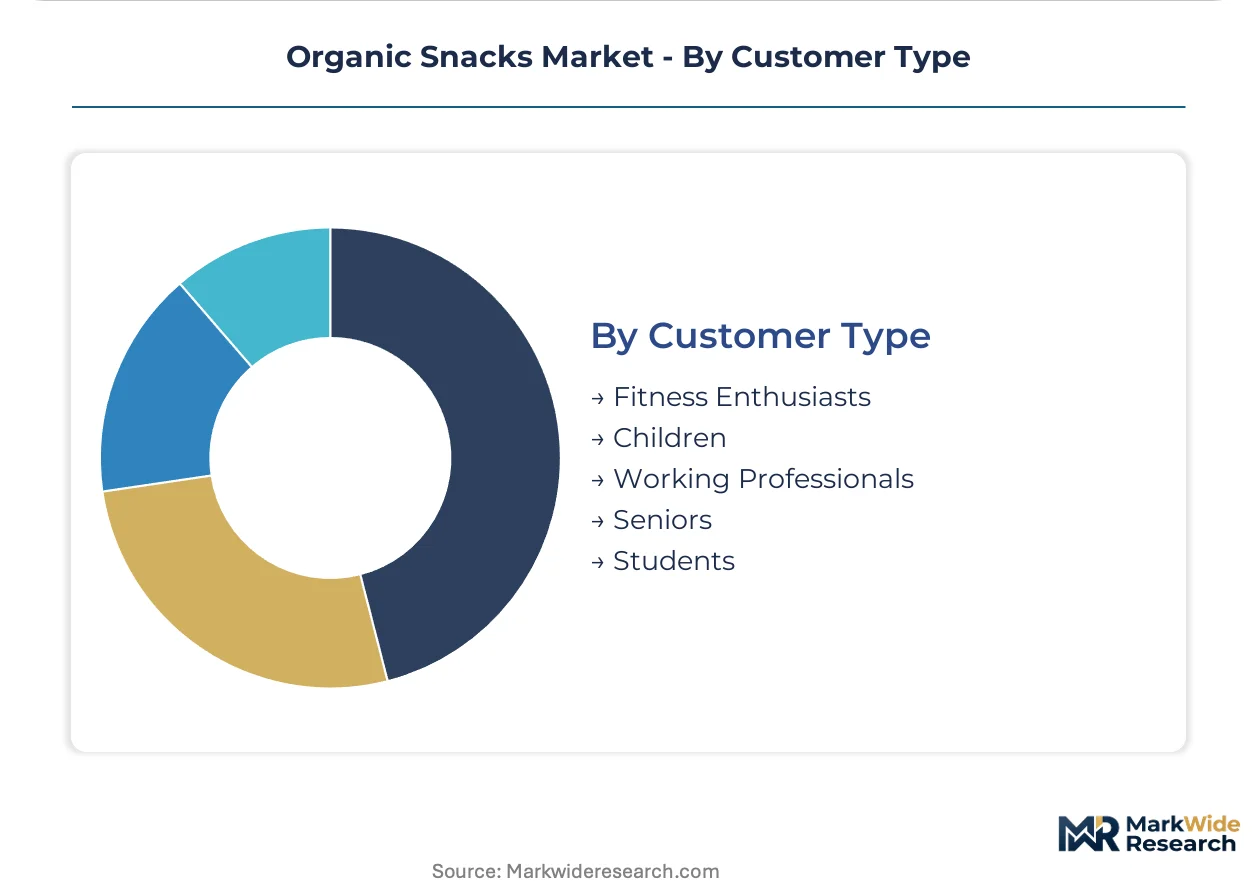
Customer Type:
Organic snack consumption patterns are heavily influenced by specific demographic and psychographic profiles, each driven by distinct health and lifestyle motivations.
- Working Professionals:This demographic seeks convenient, clean-label snack options that fit demanding schedules and support sustained energy levels. Demand is strong in developed economies like France and Japan, where long working hours necessitate efficient nutritional solutions.
- Fitness Enthusiasts:Individuals focused on physical performance and recovery gravitate towards organic snacks fortified with protein or specific functional ingredients. This segment shows high engagement in markets with strong wellness cultures, including Canada and Australia, supporting active lifestyles.
- Children:Parents prioritize organic snacks for children to ensure consumption of products free from artificial additives and synthetic ingredients.
- Seniors:Older adults seek organic snacks that are easy to digest, nutrient-dense, and contribute to overall well-being and preventative health.
- Students:This group values affordable, portable, and energy-boosting organic snacks for consumption between classes or during study periods.
The market addresses established health-conscious consumer groups while progressively attracting new segments through targeted functional benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin's growing health consciousness anchors demand for organic snacks across Europe and beyond. This market's regional dynamics reflect varied consumer preferences, regulatory environments, and distribution channel maturity. Developed economies with high disposable incomes and established organic food cultures lead consumption patterns.
Germany
Consumer health consciousness drives strong demand for organic snacks among working professionals in Germany. The EU Green Deal influences product development towards sustainable packaging materials. Munich serves as a hub for both organic food production and innovative snack development, catering to affluent consumers.
United States
Demand for clean-label, convenient organic snacks remains high across the United States, particularly among younger demographics. The USDA's National Organic Program sets the standard for certification and consumer trust. California's robust wellness culture and large consumer base make it a primary market for new product launches.
Japan
Working professionals in Japan seek convenient, healthy organic snack options to support busy lifestyles. Japan's Agricultural Standard (JAS) ensures strict quality control and consumer confidence in organic products. The Tokyo metropolitan area represents a concentrated market for premium and imported organic snack brands.
Australia
Fitness enthusiasts and health-conscious consumers fuel the organic snack market in Australia, prioritizing protein-rich and functional formulations. The country's food standards agencies oversee organic claims, maintaining product integrity. Sydney and Melbourne are key distribution points for both local and international organic snack manufacturers.
France
Working professionals in France prioritize organic snacks for their clean ingredients and nutritional benefits. The EU's organic farming rules provide a harmonized framework for production and labeling. Paris, with its strong culinary tradition and focus on quality, drives premium organic snack consumption.
Organic Snacks Market Key Industry Players
Premium-margin players sit above commodity-margin players across product differentiation and distribution channels. The market structure exhibits a clear tiering, with large diversified food conglomerates at one end and agile, niche brands at the other. Strategic archetypes include specialized performance nutrition providers, broad portfolio organic brands, and mass-market organic line extensions. Dominant competitive moves involve portfolio diversification into new product categories and expansion of digital distribution networks.
Specialists in performance nutrition, Clif Bar & Company, exemplify a targeted approach to fitness enthusiasts. The Hain Celestial Group, Inc. represents a diversified organic portfolio, spanning multiple price points and product types. General Mills, Inc. occupies a position among large food conglomerates, leveraging extensive distribution networks to integrate organic lines into mainstream retail channels.
| Leading Market Players |
|---|
| Nature’s Path Organic Foods Inc. |
| Nestlé S.A. |
| Clif Bar & Company |
| Danone S.A. |
| Conagra Brands, Inc. |
| General Mills, Inc. |
| The Hain Celestial Group, Inc. |
| SunOpta Inc. |
| Kellanova |
| Others |
Cost & Logistics Intelligence
Working professionals' demand for clean-label options influences the value-based pricing prevalent in the organic snacks market. This dynamic ensures that premium offerings, differentiated by their organic certification and functional benefits, command higher price points compared to mass-market alternatives.
Pricing Analysis
Value-based pricing, anchored to perceived health benefits and clean-label assurances, defines the organic snack market. Organic certification and brand premium serve as primary price differentiation drivers. Pricing pressure intensifies for basic organic offerings due to competition from "natural" products lacking official certification. Price-sensitive consumers in mass retail channels represent the most sensitive segment, while health-conscious buyers prioritize quality over cost.
Supply Chain Analysis
Workforce availability in agricultural regions across the United States and Europe impacts organic ingredient sourcing. The supply chain relies on key inputs like nuts and ancient grains, which are susceptible to climate events. Supply chain volatility, stemming from pest outbreaks and weather fluctuations, represents a significant structural risk. Omnichannel distribution, encompassing online retailers, direct-to-consumer platforms, and traditional health food chains, defines the downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic snacks market presents a cost-of-compliance story, where stringent frameworks like the USDA's National Organic Program create a barrier-to-entry moat for compliant players.
For Market Incumbents:
Anticipate continued pressure from "natural" product alternatives by investing in advanced organic certification and functional ingredient R&D. Diversify portfolios into new product categories, such as adaptogen-fortified snacks, to capture emerging consumer needs. Expand digital distribution networks to maintain market share against agile niche brands. Strengthen supply chain resilience against climate events through diversified sourcing strategies.
For New Entrants and Emerging Players:
Direct-to-consumer websites offer a powerful route to market for niche organic snack brands. Target the white space in functional formulations, such as probiotics or plant-based proteins, appealing to fitness enthusiasts. Focus on sustainable packaging innovations to attract environmentally conscious younger consumer cohorts in Western European metropolitan areas. Leverage curated subscription boxes to build brand loyalty and bypass traditional retail gatekeepers.
For Investors and Strategic Acquirers:
The window for entry favors agile, niche brands demonstrating strong growth in specific functional segments. Long-term viability rests on sustained consumer health consciousness and the global expansion of organic product demand. Target specialized performance nutrition providers or brands with established regenerative agricultural practices. Growth in functional organic snack sales serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach by offering organic snacks across varied price points and customer types. |
| Digital Channel Expansion | Captures younger consumer cohorts and bypasses traditional retail gatekeepers, enhancing market access. |
| Sustainable Packaging Innovation | Appeals to environmentally conscious consumers and aligns with emerging EU Green Deal regulations. |
| Functional Ingredient Integration | Addresses specific health outcomes sought by fitness enthusiasts and working professionals. |
| Regenerative Agriculture Adoption | Enhances brand sustainability credentials and secures long-term, ethical ingredient sourcing. |
Research Approach
Independent corroboration across primary interviews, secondary market intelligence, and statistical modeling underwrites the qualitative findings. This study integrates insights from brand managers, supply chain directors, retail category buyers, and food scientists. Secondary data sources include USDA National Organic Program reports, EU Green Deal documents, company annual reports, and trade association publications, triangulated through bottom-up and top-down analyses.
Comparable historical market performance and macroeconomic indicators anchored the forecast window for the organic snacks market. The analytical framework modeled segmentation dimensions including product type, packaging type, distribution channel, customer type, and regional consumption patterns. Compound annual growth rates were derived through regression analysis and expert consensus, incorporating organic ingredient availability and consumer health spending trends as key inputs.
The model holds under current market conditions; deviation in climate change impacts on organic harvests or evolving regulatory landscapes would shift projections. Forecasts reflect documented assumptions and acknowledge specific risk factors inherent to agricultural supply chains. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Potato Chips Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Europe Popcorn Market
Snacks
Low Calorie Cookies Market
Snacks
Low Calorie Snacks Market
Snacks
Global Snack Food Market
Snacks
Fruit and Vegetable Chips Market
Snacks
South America Frozen Snacks Market
Snacks
High Fiber Snack Foods Market
Snacks
Snack Food Packaging Market
Snacks
Qatar Potato Chips Market
Snacks
Low Fat Protein Snacks Market
Snacks
Better for You Snacks Market
Snacks
Energy Bar Market
Snacks
Middle East Snack Bar Market