
 North America Cereal Bar Market | 2026-2036
North America Cereal Bar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cereal Bar Market Analytics
Canadian oat processing capacity is shifting toward higher-value extrusion for cereal bar bases, tightening regional ingredient supply. General Mills Inc. leverages its Minneapolis R&D campus to sustain grain innovation pipelines for chewy texture platforms. Kellanova anchors its Battle Creek manufacturing network around dual-texture bar systems. Clif Bar & Company specializes in organic supply chains that dominate the outdoor recreation channel.
A North America cereal bar is a shelf-stable, cold-formed or extruded snack comprising cereals, binders, and functional additives, typically containing 10-25 grams of carbohydrates and 3-10 grams of protein per serving, designed for portable nutrition and sustained energy release. Protein bars command premium shelf positioning as athletes and gym-goers trade up from commodity granola. Health-conscious busy professionals gravitate toward single-serving nut-based formats in online retail channels, where subscription models capture recurring revenue with higher lifetime value than impulse supermarket purchases.
The FDA enforces allergen labeling under FALCPA and monitors health claims through its food labeling regulations, while USDA organic certification creates tiered market access for premium positioning. Health Canada and CFIA standards govern cross-border trade, particularly for products containing novel proteins or CBD-adjacent ingredients. Stakeholders must monitor evolving sugar reduction mandates and front-of-package labeling proposals that could force rapid reformulation across existing SKUs.
Market Dynamics
FDA's updated Nutrition Facts labeling requirements and USDA dietary guideline revisions are compressing formulation timelines across North American cereal bar portfolios, forcing simultaneous sugar reduction and protein fortification investments.
Growth Catalysts
- Protein fortification technology:Extrusion-based protein integration systems enable 15-25 gram protein loads without textural degradation, attracting gym-oriented consumers in California and the U.S. Northeast corridor.
- USDA organic certification:Tiered premium positioning through certified organic supply chains unlocks outdoor recreation channel expansion and subscription-based recurring revenue models.
- Canadian oat processing:Higher-value extrusion capacity for cereal bar bases is tightening regional ingredient supply and pulling investment toward captive sourcing arrangements.
Market Restraints
- Canadian oat supply concentration:Regional processing capacity shifts toward extrusion are constraining base ingredient availability for U.S. manufacturers dependent on cross-border sourcing.
- FALCPA allergen compliance:FDA enforcement of labeling mandates creates reformulation costs and line-changeover downtime for multi-SKU producers.
- CBD-adjacent ingredient uncertainty:Health Canada and CFIA standards for novel proteins create cross-border trade friction and inventory holding risks.
Strategic Opportunities
- Subscription e-commerce:Direct-to-consumer channels capture higher lifetime value than impulse supermarket purchases, particularly for single-serving nut-based formats targeting busy professionals.
- Front-of-package labeling readiness:Early alignment with proposed FDA sugar reduction mandates creates first-mover advantage before forced reformulation deadlines.
- Dual-texture systems:Convergence of chewy and crunchy layer technologies opens premium positioning in the athlete segment currently trading up from commodity granola.
Industry Challenges
- Organic supply chain certification timelines:USDA organic verification for multi-ingredient bars extends procurement cycles and complicates just-in-time manufacturing.
- Legacy R&D facility reconfiguration:Minneapolis and Battle Creek campuses require capital-intensive line upgrades to accommodate simultaneous low-sugar and high-protein formulation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cereal Bar Market |
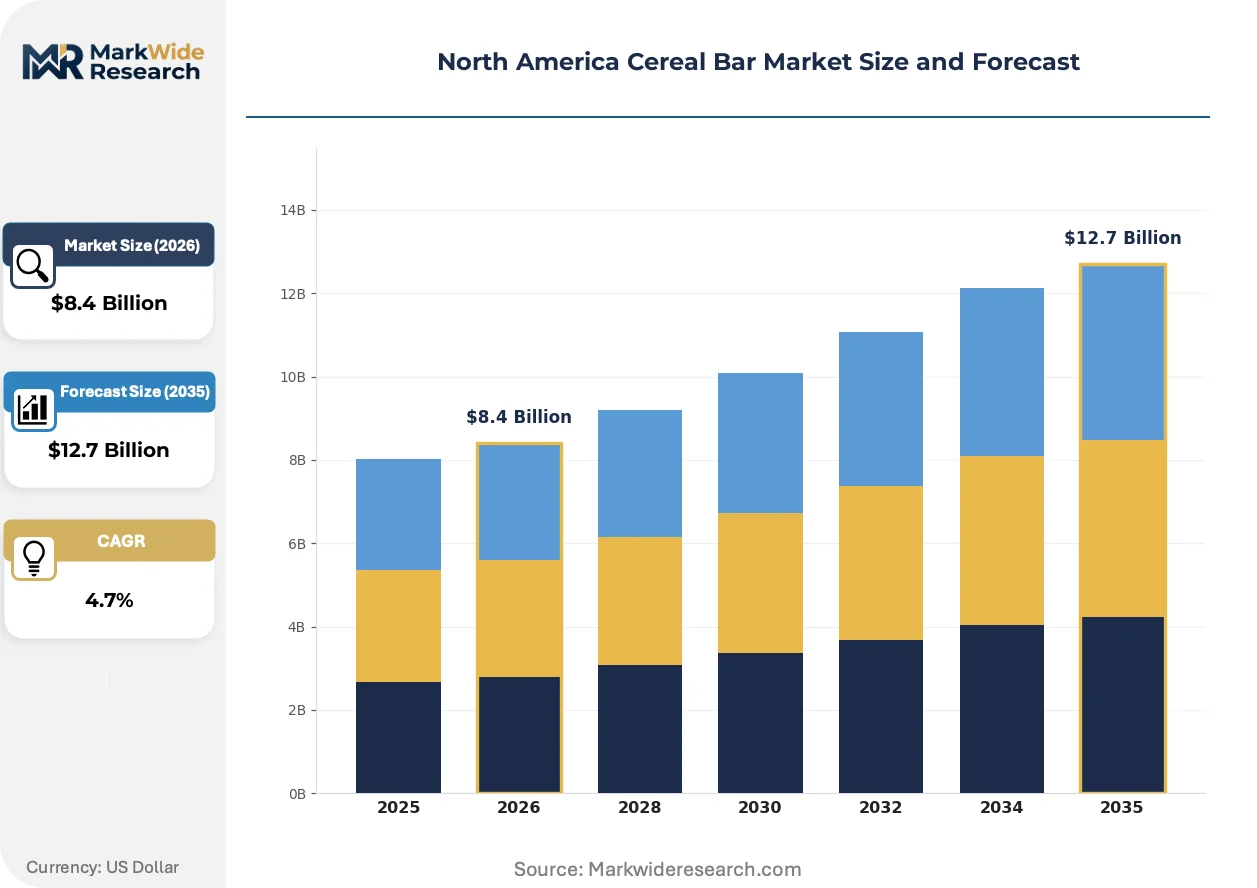
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-based, Fruit & Nut, Protein, Granola Consumer Segment: Health-conscious, Athletes, Children, Busy Professionals Sales Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Packaging Type: Single-serving, Multi-pack, Bulk, Eco-friendly |
| Companies Covered | General Mills Inc., Kellanova, PepsiCo, Inc., Mars, Incorporated, Mondelez International, Inc., Clif Bar & Company, McKee Foods Corporation, Kind LLC, Atkins Nutritionals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cereal Bar Market Evolving Landscape
Cold-formed and extruded bar technologies are converging with functional ingredient delivery systems, reshaping how sustained energy release is engineered and communicated to health-conscious buyers.
Pea and fava protein isolates are absorbing moisture-binding functions previously handled by sugar syrups, enabling cleaner-label formulations. Fitness-oriented consumers in metropolitan California clusters are adopting these reformulations at accelerated rates. The technology is absorbing shelf-space from legacy granola formats as retailers reallocate premium positioning toward protein-dense alternatives.
FDA enforcement of updated Nutrition Facts panels is compressing allowable serving-size declarations for sugar-dense legacy products. Manufacturers face line-by-line reformulation to maintain permissible health claims. The U.S. Northeast corridor's urban professional segment is responding fastest, with retail buyers in this geography penalizing SKUs that trigger added-sugar callouts.
Subscription-based procurement is displacing impulse purchasing in the professional demographic, with auto-replenishment platforms capturing predictable demand patterns. Online retail channels are consolidating this shift through algorithm-driven personalization. Canada and the U.S. Pacific Northwest display the highest concentration of this behavioral transition, particularly among outdoor recreation enthusiasts seeking portable nutrition continuity.
North America Cereal Bar Market Segmentation
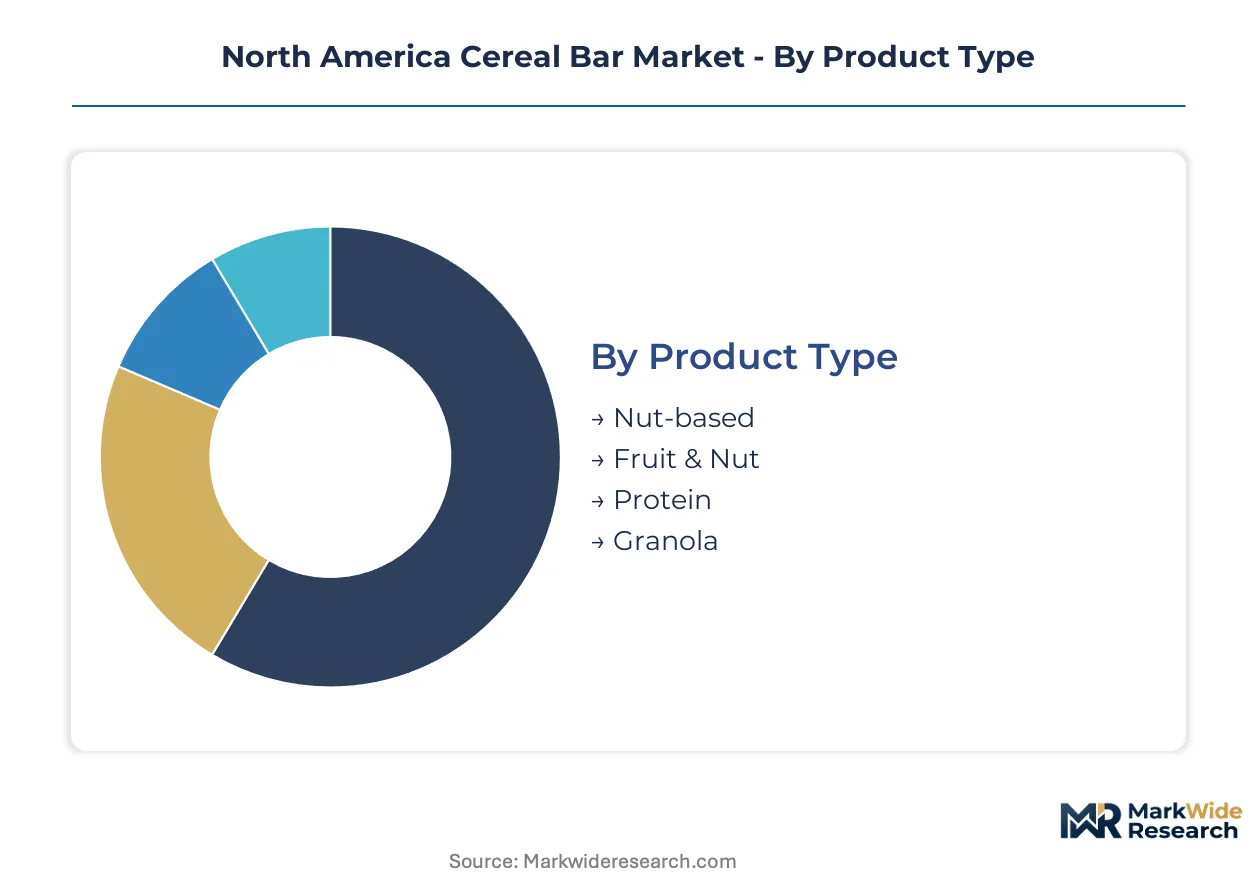
Cereal bar manufacturers calibrate formulation, packaging, and channel strategy against distinct usage occasions and buyer archetypes. The North America Cereal Bar Market fragments across four critical dimensions that determine pricing power, margin structure, and regulatory exposure.
Product Type:
Extrusion and cold-forming technologies define the functional performance and shelf stability of each formulation platform.
- Protein:Extrusion-based protein integration delivers 15-25 gram protein loads with sustained energy release profiles. Athletes in California metropolitan clusters trade up from commodity granola toward these denser formulations. FDA health claim compliance pressures force simultaneous sugar reduction in this segment.
- Nut-based:Cold-formed bars leverage almond, cashew, and peanut butter binders for cleaner-label positioning. Health-conscious busy professionals in the U.S. Northeast corridor drive subscription e-commerce adoption of single-serving formats. Moisture-binding functions shift from sugar syrups to pea and fava protein isolates.
- Fruit & Nut:Dual-texture systems combine chewy dried fruit layers with crunchy nut inclusions for portable nutrition occasions.
- Granola:Legacy baked clusters face compression as retailers reallocate premium shelf space toward protein-fortified alternatives.
Protein leads on scale; nut-based leads on momentum.
Consumer Segment:
Purchase frequency and channel preference vary sharply across demographic and lifestyle cohorts, reshaping distribution investment priorities.
- Health-conscious:USDA organic certification and front-of-package labeling awareness drive premium willingness-to-pay. Outdoor recreation enthusiasts in Canada and the U.S. Pacific Northwest display the highest subscription platform penetration.
- Busy Professionals:Auto-replenishment algorithms capture predictable demand patterns with higher lifetime value than impulse supermarket purchases. Urban professionals in the U.S. Northeast corridor penalize SKUs triggering FDA added-sugar callouts.
- Athletes:Gym-oriented consumers demand dual-texture systems with rapid glycemic response and post-workout recovery positioning.
- Children:School lunch compliance and allergen labeling under FALCPA constrain formulation flexibility for this demographic.
Health-conscious buyers dominate absolute volume; busy professionals climb the fastest on digital channel migration.
Sales Channel:
Inventory velocity and margin capture diverge meaningfully between physical and digital fulfillment architectures.
- Online Retail:Direct-to-consumer platforms consolidate algorithm-driven personalization and subscription lock-in. Nut-based single-serving formats achieve recurring revenue multiples exceeding impulse purchase economics.
- Supermarkets:Protein bars command premium shelf positioning through slotting fee investments and velocity guarantees.
- Convenience Stores:Grab-and-go occasions favor single-serving packaging with immediate consumption positioning.
- Health Food Stores:USDA organic certification creates tiered access for premium SKUs targeting outdoor recreation continuity.
Supermarkets retain the largest transaction footprint; online retail gains share fastest on subscription model adoption.
Packaging Type:
Unit economics and sustainability credentials shape procurement decisions across institutional and household buyers.
- Single-serving:Portion-controlled formats dominate professional demographic adoption and convenience channel velocity. California and U.S. Northeast corridor urban clusters display the highest per-capita consumption.
- Eco-friendly:Compostable films and reduced-plastic structures respond to front-of-package labeling proposals and municipal waste regulations.
- Multi-pack:Warehouse club and pantry-stocking occasions favor value-engineered bundling for household replenishment.
- Bulk:Foodservice and institutional channels require extended shelf-life specifications and modified atmosphere packaging.
Single-serving commands the widest distribution; eco-friendly packaging expands most quickly on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as manufacturers weigh FDA compliance costs against Health Canada and CFIA requirements. Cross-border ingredient sourcing tightens around Canadian oat processing capacity. Mexico's manufacturing cost advantages attract contract production for U.S. distribution.
United States
California metropolitan clusters and the U.S. Northeast corridor concentrate health-conscious professional demand for protein-fortified and low-sugar formats. FDA's updated Nutrition Facts labeling requirements and evolving USDA dietary guidelines compress formulation timelines for domestic portfolios. Minneapolis anchors General Mills' grain innovation R&D campus, while Battle Creek, Michigan sustains Kellanova's dual-texture manufacturing network.
Canada
Oat processing capacity shifts toward higher-value extrusion for cereal bar bases, tightening regional ingredient supply for cross-border trade. Health Canada and CFIA standards govern novel protein approvals and CBD-adjacent ingredient uncertainty, creating inventory holding risks. Prairie Provinces concentrate oat cultivation, while Ontario and Quebec process higher-value extruded bases for captive sourcing arrangements.
Mexico
Cost-efficient contract manufacturing capacity attracts U.S. brand owners seeking tariff-advantaged production for re-export. Mexico City Metro and Nuevo León industrial corridors develop co-manufacturing infrastructure for shelf-stable snack formats. COFEPRIS food safety standards align with FDA frameworks, reducing regulatory friction for North American integrated supply chains.
North America Cereal Bar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue organic certification and direct-to-consumer subscription channels. The vendor base clusters around three strategic archetypes: diversified multinational food conglomerates with grain innovation pipelines, specialized organic supply chain operators targeting outdoor recreation channels, and private-label contract manufacturers serving retail brands. Dominant competitive moves include backward integration into captive oat sourcing and portfolio diversification into dual-texture protein formats.
Within the diversified conglomerate tier, General Mills Inc. and Kellanova exemplify scale-driven R&D campus models, while Clif Bar & Company occupies a position within the organic specialist archetype. These three anchors represent distinct competitive vectors: Minneapolis-based grain innovation, Battle Creek manufacturing network density, and certified organic supply chain dominance in outdoor recreation channels.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellanova |
| PepsiCo, Inc. |
| Mars, Incorporated |
| Mondelez International, Inc. |
| Clif Bar & Company |
| McKee Foods Corporation |
| Kind LLC |
| Atkins Nutritionals, Inc. |
| Others |
Value Network & Pricing Analysis
USDA organic certification gates qualified supply access and premium-tier pricing power, compressing margins for uncertified producers while rewarding captive sourcing investments with tiered market positioning.
Pricing Analysis
Retailer markup layers absorb slotting fee investments and velocity guarantees, with protein bars commanding premium positioning against legacy granola formats. Price differentiation rests on USDA organic certification and dual-texture performance tiering. Cost compression in the standard tier intensifies as pea protein isolates displace sugar syrups. Busy professionals in subscription channels display lowest price sensitivity; convenience channel impulse buyers remain most elastic.
Supply Chain Analysis
Single-source vulnerability sits with Canadian Prairie Provinces oat cultivation, where extrusion capacity shifts tighten cross-border ingredient flows. The supply chain draws from Canadian oat processors, U.S. Midwest grain elevators, and Mexican contract manufacturers. Tariff exposure runs through NAFTA-origin qualification for re-export production. Distribution feeds through supermarket slotting networks, direct-to-consumer subscription platforms, and health food store tiered access systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Cereal Bar Market functions as a stable compounder, with protein fortification technology sustaining steady portfolio expansion across health-conscious demographic clusters.
For Market Incumbents: Lock in captive oat sourcing arrangements before Canadian extrusion capacity tightens further, and accelerate dual-texture R&D pipeline conversion to defend against emerging organic specialists. Backward integration into Prairie Provinces cultivation secures ingredient continuity against cross-border trade friction. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Pacific Northwest outdoor recreation enthusiasts, where USDA organic certification unlocks highest lifetime value economics. White-space concentration sits with single-serving nut-based formats for busy professionals in Northeast corridor urban clusters. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale organic specialists because Health Canada and CFIA compliance creates fragmented regulatory moats that scale advantages can consolidate. Five-to-ten year viability hinges on front-of-package labeling readiness. The signal to watch is FDA sugar reduction mandate timing against existing SKU reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Oat Sourcing Integration | Backward integration into Canadian Prairie Provinces cultivation secures extrusion-grade supply against cross-border tightening. |
| Dual-Texture Platform Launch | Convergence of chewy and crunchy layer technologies captures athlete segment trade-up from commodity granola. |
| Subscription Channel Expansion | Auto-replenishment algorithms capture predictable demand patterns with higher lifetime value than impulse supermarket economics. |
| USDA Organic Certification Acceleration | Tiered premium positioning unlocks health food store access and outdoor recreation channel expansion. |
| Front-of-Package Labeling Readiness | Early alignment with proposed FDA sugar reduction mandates creates first-mover advantage before forced reformulation deadlines. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market gathered through interviews with cereal bar brand managers, retail category buyers, oat processing procurement leads, and outdoor recreation channel distributors. Secondary validation draws from FDA labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and Health Canada novel food approval records. Bottom-up volume estimates triangulate against top-down category spending benchmarks.
Rate-of-change decomposition isolates protein fortification adoption curves, sugar reduction compliance timelines, and subscription channel migration patterns across the projection horizon. Segmentation dimensions modeled include product type, consumer archetype, sales channel, and packaging format. CAGRs derive from fitted growth curves against historical velocity data and regulatory milestone assumptions.
Several conditions sit outside the modeled scope, including CBD-adjacent ingredient approval pathways and potential front-of-package labeling mandate reversals. Forecasts reflect documented assumptions about FDA enforcement timelines and Canadian oat processing capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Seafood Snacks Market
Snacks
Edible Flakes Market
Snacks
Europe Snack Bar Market
Snacks
North America Pretzel Market
Snacks
India Energy Bar Market
Snacks
Italy Snack Bar Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Dried Fruit Snacks Market
Snacks
Gluten Free Snacks Market
Snacks
Organic Chips Market
Snacks
US Potato Chips Market
Snacks
South Africa Savory Snacks Market
Snacks
Super Low Calorie Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Popcorn Market