
 Fortified Cereal Market | 2026-2036
Fortified Cereal Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Cereal Market Analysis
The EU Green Deal is pivoting fortified cereal demand toward lower-carbon grain sourcing and recyclable packaging commitments. General Mills sustains its R&D intensity through in-house micronutrient stabilization labs in Minnesota. Nestlé anchors European positioning with reformulated recipes that comply with Nutri-Score A and B thresholds. Kellogg Company dominates North American retail shelf space through direct-store-delivery networks that control in-store merchandising.
Fortified cereals are processed grain products with added vitamins, minerals, and macronutrients, typically produced through extrusion cooking at 120-180°C followed by micronutrient coating or spraying to preserve heat-sensitive compounds like folic acid and vitamin D; their primary purpose is to address dietary deficiencies in mass-market breakfast consumption. Whole grain formulations lead volume but command thinner margins than gluten-free and organic segments where ingredient costs and certification premiums create deeper profit pools. Online retail channels are expanding fastest among distribution pathways, though supermarkets still capture the majority of health-conscious adult purchases through dedicated wellness aisles.
The FDA governs nutrient content claims and fortification ceilings under 21 CFR 101, while EFSA sets European upper limits for voluntary micronutrient addition; both frameworks directly constrain formulation latitude and label messaging. India's FSSAI mandates iron and folic acid fortification in mass-market cereals distributed through public health channels. Stakeholders must monitor evolving front-of-pack regulations across multiple jurisdictions to anticipate reformulation timelines and avoid stranded inventory in non-compliant markets.
Market Dynamics
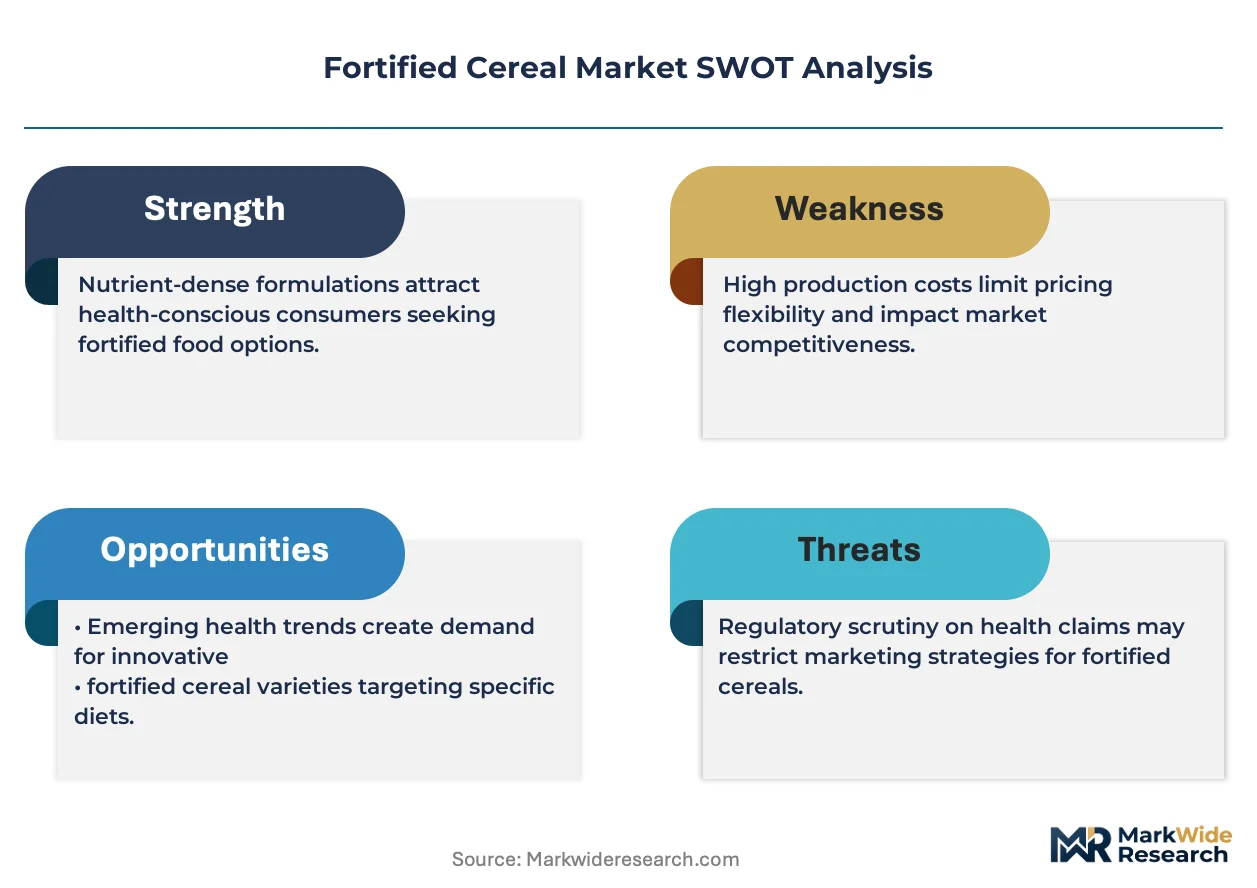
Reformulation pressures from front-of-pack labeling mandates are compressing formulation timelines and forcing simultaneous sugar reduction, micronutrient retention, and clean-label compliance across production networks.
Growth Catalysts
- School Nutrition Procurement:Public breakfast programs across the United States and United Kingdom are expanding volume commitments for iron-fortified and vitamin-enriched offerings, creating institutional demand anchors.
- EU Green Deal Packaging Mandates:Recyclable packaging commitments are accelerating capital deployment into fiber-based and mono-material formats that align with circular economy frameworks.
- Micronutrient Deficiency Burden:India's FSSAI mandates for iron and folic acid fortification in mass-market cereals distributed through public health channels are driving mandatory volume expansion.
Market Restraints
- Heat-Sensitive Nutrient Degradation:Extrusion cooking at 120-180°C degrades folic acid and vitamin D, requiring expensive encapsulation or post-extrusion spraying that elevates unit costs.
- Organic Grain Supply Concentration:Certified organic wheat and oat sourcing concentrates in the United States Great Plains and Canadian prairie provinces, creating geographic supply vulnerability.
- Clean-Label Certification Friction:Non-GMO Project verification and USDA Organic timelines extend 12-18 months, straining working capital for reformulation cycles.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Online retail channels are capturing health-conscious adult cohorts through personalized micronutrient stacking and recurring delivery mechanics.
- Precision Fermentation Proteins:Convergence of biotechnology and cereal matrices enables novel amino acid fortification without allergen cross-contamination risks.
- German Reformulation Incentives:Nutri-Score A and B threshold compliance unlocks preferential retail placement and public procurement eligibility across German-speaking markets.
Industry Challenges
- Cross-Functional Talent Scarcity:Food science expertise spanning extrusion engineering, micronutrient stability, and regulatory compliance commands premium compensation and extended recruitment cycles.
- Legacy Equipment Retrofit Costs:Existing extrusion lines require coating system upgrades and temperature-zone modifications to preserve heat-labile vitamins, demanding seven-figure capital commitments per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Cereal Market |
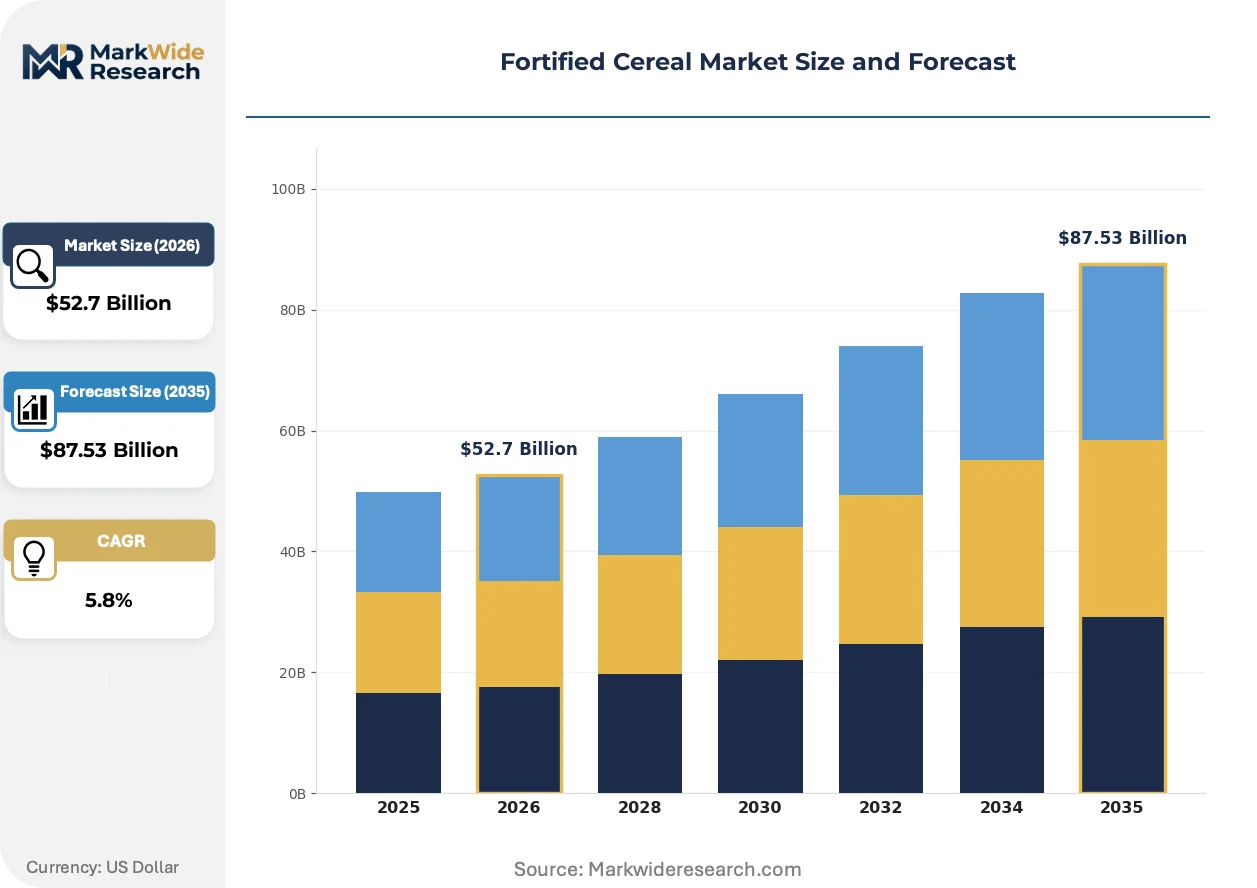
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $87.53 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Instant, Flakes, Puffed Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Target Consumer: Children, Health-Conscious Adults, Athletes, Seniors Formulation: Sugar-Free, Organic, Gluten-Free, High Fiber |
| Companies Covered | Kellogg Company, General Mills Inc., Nestlé S.A., PepsiCo Inc., Post Holdings Inc., Quaker Oats Company, Weetabix Limited, Bob's Red Mill Natural Foods, Cereal Partners Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Cereal Market Emerging Trajectories
Extrusion technology advances and front-of-pack regulatory diffusion are compressing product development cycles while expanding the technical frontier for bioavailable micronutrient delivery.
Microencapsulation of heat-sensitive vitamins using lipid and alginate matrices is consolidating as the dominant stabilization approach for extruded cereals. Manufacturers serving school nutrition and maternal health programs are adopting these systems at accelerated pace. The technology is consolidating competitive advantage around in-house stabilization capabilities versus outsourced ingredient supply.
The FDA's updated nutrition labeling requirements under 21 CFR 101 are tightening nutrient content claim thresholds and fortification ceilings. Reformulation investments now prioritize dual compliance with FDA ceilings and EU Nutri-Score thresholds to enable cross-border inventory fungibility. Gluten-free and organic segments face the steepest compliance burden due to existing premium positioning constraints.
Health-conscious adult buyers are migrating toward dedicated wellness aisles and online subscription channels that enable micronutrient customization. Supermarket wellness aisle placement is displacing conventional cereal aisle positioning for premium fortified lines. This behavioral shift concentrates most visibly in United States coastal metropolitan markets and United Kingdom urban centers.
Fortified Cereal Market Segmentation
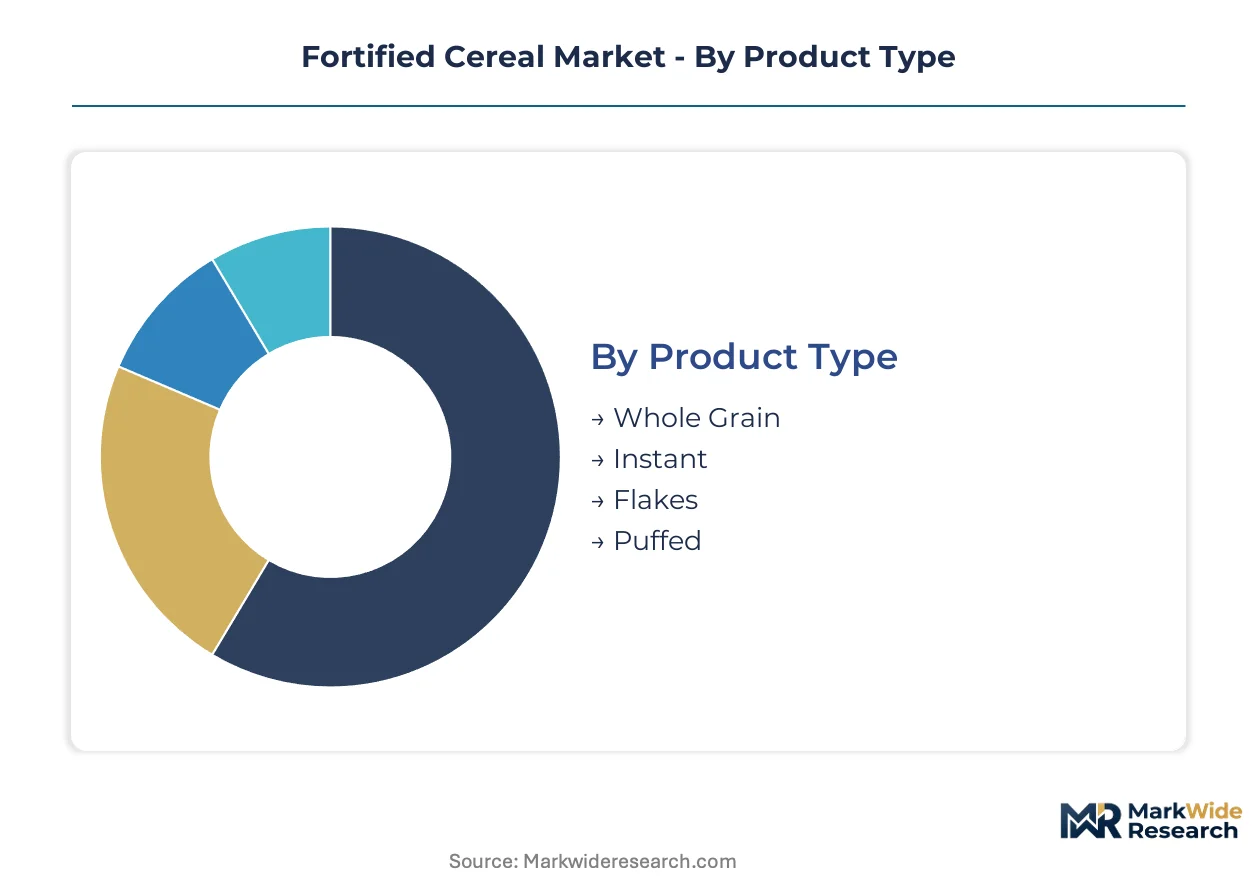
Extrusion equipment configurations and coating system investments vary dramatically across fortified cereal formats, creating divergent capital deployment strategies for manufacturers. Segmentation reveals where micronutrient stability technology commands premium infrastructure spending versus commodity-scale production.
Product Type:
Whole grain extrusion lines demand the heaviest upfront capital, with multi-zone temperature control and post-extrusion micronutrient spray systems representing seven-figure facility investments per production site.
- Whole Grain:Requires intact bran and germ preservation through lower-shear extrusion at 120-140°C, limiting throughput speed but commanding shelf space in United States wellness aisles where fiber content drives procurement from school nutrition programs.
- Instant:Pre-cooked and dehydrated formats utilize higher-temperature extrusion followed by rapid cooling tunnels; heat-sensitive vitamin degradation necessitates expensive microencapsulation, concentrating production among manufacturers with in-house stabilization labs in Minnesota.
- Flakes:Rolled and toasted formats employ flaking mills and drying ovens with moderate capital requirements.
- Puffed:Gun-puffing or extrusion-puffing equipment operates at high pressure differentials with shorter production runs per batch.
Most installed capacity flows through Whole Grain. Expansion is steepest in Instant.
Distribution Channel:
Channel selection determines working capital intensity, with direct-store-delivery networks locking up receivables for 45-60 days while subscription models front-load customer acquisition costs against predictable recurring revenue.
- Online Retail:Direct-to-consumer subscription mechanics enable personalized micronutrient stacking and recurring delivery; customer acquisition costs concentrate in United States coastal metropolitan markets where health-conscious adult cohorts dominate.
- Supermarkets:Direct-store-delivery networks control in-store merchandising and dedicated wellness aisle placement, requiring field sales forces and inventory financing that strain smaller manufacturers.
- Health Food Stores:Specialty retail commands certification premiums for Non-GMO Project and USDA Organic verification.
- Convenience Stores:Single-serve and on-the-go formats prioritize packaging durability and extended shelf stability over micronutrient density.
Supermarkets retain the majority of volume. Online Retail is gaining share fastest among health-conscious adult purchases.
Target Consumer:
Consumer cohort segmentation drives formulation complexity, with pediatric and senior nutrition demands imposing the strictest micronutrient density and palatability requirements.
- Children:Iron and folic acid fortification targets developmental needs; palatability engineering through flavor masking and color retention adds formulation layers that extend R&D cycles and require sensory testing panels.
- Health-Conscious Adults:Clean-label positioning and reduced-sugar mandates drive reformulation investments targeting FDA nutrition labeling compliance and EU Nutri-Score A and B thresholds.
- Athletes:Protein and amino acid fortification converges with precision fermentation technologies for novel supplementation.
- Seniors:Vitamin D and calcium bioavailability requirements influence coating system specifications for enhanced absorption.
Health-Conscious Adults generate the highest per-unit margins. Children anchor institutional procurement volume through school breakfast programs.
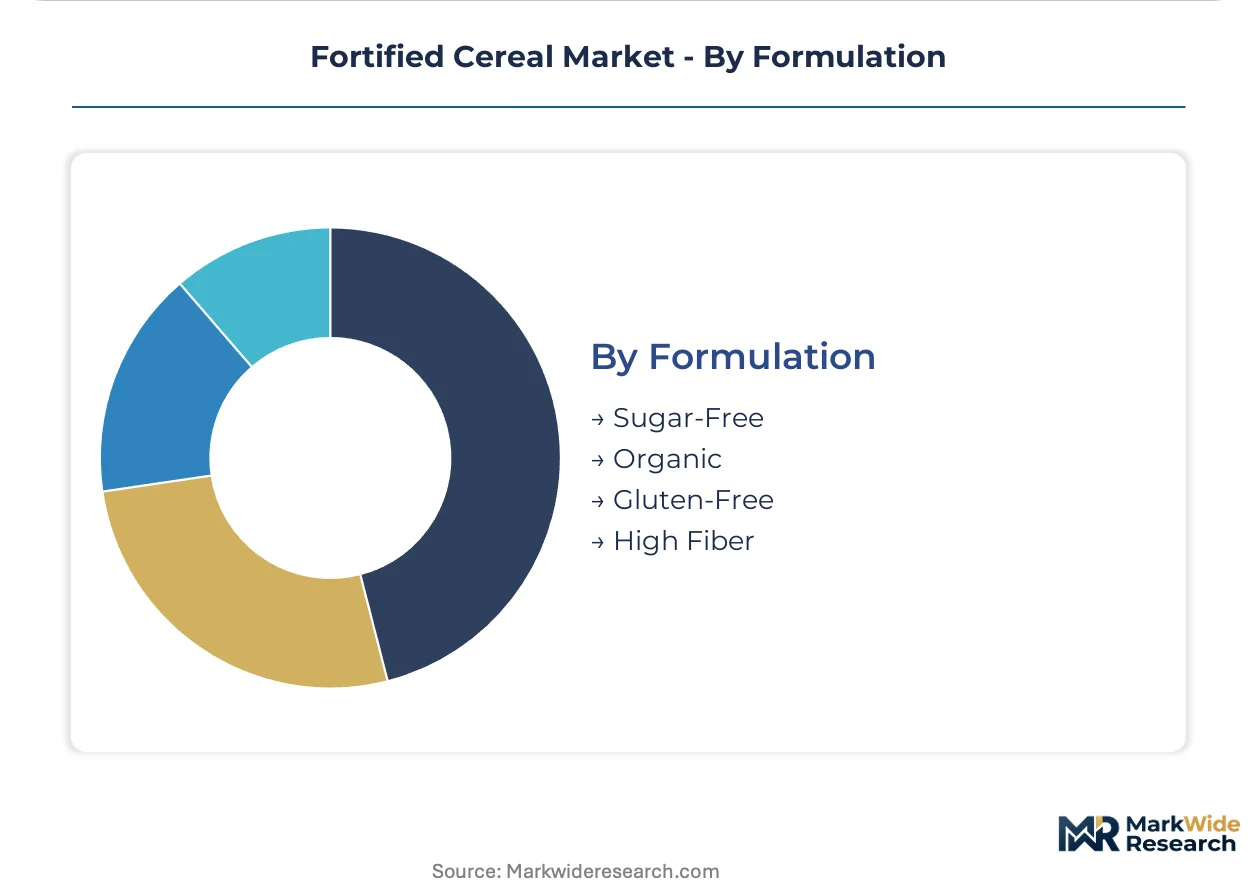
Formulation:
Certification requirements create tiered cost structures, with organic and gluten-free segments demanding 12-18 month verification timelines that strain working capital and concentrate supply among certified manufacturers.
- Organic:Certified organic wheat and oat sourcing concentrates in the United States Great Plains and Canadian prairie provinces, creating geographic supply vulnerability and elevating ingredient costs through certification premiums that deepen profit pools relative to conventional whole grain.
- Gluten-Free:Dedicated extrusion lines and allergen control protocols eliminate cross-contamination risks; sorghum, rice, and millet sourcing requires separate supply chain infrastructure that limits supplier options and extends procurement cycles.
- Sugar-Free:Natural and artificial sweetener alternatives impose flavor stability challenges through shelf life.
- High Fiber:Bran incorporation and prebiotic additive integration targets digestive health positioning.
Organic commands the steepest certification burden. Gluten-Free faces the tightest supply concentration constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fortification of breakfast cereals traces its industrial origins to the United States during the 1930s, when wheat flour enrichment programs established the technical and regulatory foundation for mass-market micronutrient delivery through processed grain products.
United States
School breakfast programs and institutional procurement anchor domestic volume, with the FDA's updated nutrition labeling requirements under 21 CFR 101 tightening fortification ceilings and sugar reduction mandates. Minneapolis-St. Paul hosts concentrated R&D infrastructure where in-house micronutrient stabilization labs support reformulation timelines.
Germany
Nutri-Score A and B threshold compliance unlocks preferential retail placement across German-speaking markets, driving reformulation investments toward reduced-sugar positioning. The EU Green Deal packaging mandates accelerate capital deployment into recyclable mono-material formats from production facilities in North Rhine-Westphalia.
India
FSSAI mandates for iron and folic acid fortification in mass-market cereals distributed through public health channels create mandatory volume expansion. Maharashtra and Gujarat concentrate manufacturing capacity where reformulation targets maternal health program specifications.
United Kingdom
Public breakfast program procurement across England and Scotland sustains institutional demand for vitamin-enriched offerings. London and Southeast England urban centers drive health-conscious adult migration toward dedicated wellness aisle placement and subscription channel adoption.
Canada
Certified organic wheat and oat sourcing concentrates in the Prairie Provinces, creating geographic supply vulnerability that elevates ingredient costs through certification premiums. Health Canada regulations align with FDA frameworks to enable cross-border inventory fungibility.
Fortified Cereal Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fortified cereal landscape, with integrated manufacturers owning extrusion infrastructure and coating systems while brand-focused firms outsource production to contracted facilities. The market structure consolidates around three to five dominant multinational players controlling retail shelf space through direct-store-delivery networks. Strategic archetypes include vertically integrated nutrition platforms, brand-licensing specialists, and private-label contract manufacturers. Competitive intensity concentrates on M&A-driven portfolio diversification and in-house micronutrient stabilization capabilities that compress reformulation timelines.
Among North American integrated manufacturers, General Mills Inc., Kellogg Company, and Post Holdings Inc. exemplify the capital-intensive archetype where captive production infrastructure supports rapid response to FDA and EU regulatory shifts. Nestlé S.A. anchors European positioning through reformulated recipes engineered for Nutri-Score compliance. These entities represent the dominant competitive tier where scale economies in extrusion technology and micronutrient delivery systems create defensive moats against mid-cap challengers.
| Leading Market Players |
|---|
| Kellogg Company |
| General Mills Inc. |
| Nestlé S.A. |
| PepsiCo Inc. |
| Post Holdings Inc. |
| Quaker Oats Company |
| Weetabix Limited |
| Bob's Red Mill Natural Foods |
| Cereal Partners Worldwide |
| Others |
Supply Flow & Price Mechanics
Family-owned grain cooperatives across the United States Great Plains and Canadian prairie provinces anchor upstream sourcing, translating geographic supply concentration into asymmetric pricing power for certified organic inputs while forcing reformulation-driven manufacturers to absorb certification premiums or surrender margin.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified offerings from conventional whole grain and private-label economy tiers. Price differentiation rests on Non-GMO Project verification and USDA Organic certification timelines that extend 12-18 months. Cost compression in the premium tier is intensifying because microencapsulation investments for heat-sensitive vitamin stabilization elevate unit production costs. School nutrition programs exhibit the highest price sensitivity due to fixed institutional budgets, while health-conscious adult subscribers through direct-to-consumer channels demonstrate the lowest sensitivity.
Supply Chain Analysis
India's FSSAI domestic-content mandates for iron and folic acid fortification in public health channel distribution are reshaping sourcing patterns toward local grain procurement. Supply concentrates in the United States, Canada, and India for certified organic wheat and oat inputs. Raw material dependencies include sorghum, rice, and millet for gluten-free formulations, plus lipid and alginate matrices for microencapsulation systems. Single-source vulnerability concentrates in Minnesota-based in-house micronutrient stabilization labs. Distribution runs through direct-store-delivery networks that control supermarket wellness aisle placement and in-store merchandising.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fortified cereal market functions as a stable compounder anchored by mandatory fortification mandates in public health channels that institutionalize volume regardless of consumer discretionary pressure.
For Market Incumbents: Anticipate escalating reformulation timelines from simultaneous FDA nutrition labeling compliance and EU Nutri-Score threshold convergence. Defensive priorities center on backward integration into in-house micronutrient stabilization capabilities that compress product development cycles, alongside capacity retention in Minnesota and North Rhine-Westphalia R&D clusters to outpace mid-cap challengers lacking captive extrusion infrastructure. For New Entrants and Emerging Players: Capture white-space opportunity in precision fermentation protein fortification for athlete nutrition segments where novel amino acid delivery escapes allergen cross-contamination risks. The most penetrable terrain sits in German-speaking markets where Nutri-Score A and B compliance unlocks preferential retail placement. A direct-to-consumer subscription go-to-market angle bypasses direct-store-delivery network barriers that incumbent field sales forces control. For Investors and Strategic Acquirers: Valuations sit cheapest among private-label contract manufacturers lacking brand equity but possessing certified organic extrusion lines. Long-term viability over a 5-10 year window favors targets with established FSSAI compliance for Indian public health channel access. The signal to watch is front-of-pack labeling mandate diffusion beyond EU borders, which would trigger accelerated reformulation capital deployment and consolidate advantage around in-house stabilization capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Investment | In-house vitamin stabilization labs in Minnesota compress reformulation timelines against outsourced competitors. |
| Nutri-Score Compliance Reformulation | Reduced-sugar recipes achieving A and B thresholds unlock preferential German retail placement and procurement eligibility. |
| Direct-to-Consumer Subscription Launch | Personalized micronutrient stacking captures health-conscious adult cohorts in United States coastal metropolitan markets. |
| Recyclable Packaging Transition | Fiber-based mono-material formats align with EU Green Deal circular economy mandates from North Rhine-Westphalia facilities. |
| Precision Fermentation Partnership | Novel amino acid fortification targets athlete nutrition without gluten-free extrusion line cross-contamination protocols. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion engineering directors, micronutrient formulation scientists, school nutrition procurement officers, and supermarket category buyers with secondary validation against FDA 21 CFR 101 filings, EFSA scientific opinions, FSSAI fortification directives, Nielsen retail audit data, and EU Green Deal implementation trackers. Bottom-up facility capacity assessments and top-down category spend estimates were triangulated to anchor volume and value outputs.
Segment-weighting approaches distributed value across product type, distribution channel, target consumer, and formulation certification tiers throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating school breakfast program expansion rates, online retail channel penetration trajectories, and regulatory compliance cost pass-through assumptions. Industry-specific inputs included extrusion temperature-zone modification capital requirements and microencapsulation ingredient cost curves.
Regulatory timeline acceleration, organic grain supply disruption, and front-of-pack labeling mandate diffusion beyond current jurisdictions are the dominant revision risks that could compress or extend projected value expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Pantothenic Acid Market