
 Baked Savoury Snacks Market | 2026-2036
Baked Savoury Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Baked Savoury Snacks Market Analysis
Asset-light co-manufacturing and private-label financing is fragmenting competitive barriers in baked savoury snacks, allowing regional entrants to challenge legacy portfolios without capital-heavy production investments. PepsiCo Inc. leverages its direct-store-delivery infrastructure to sustain shelf dominance across convenience and club channels. Mondelez International anchors its position through biscuit-to-snack technology transfer and European formulation expertise. Calbee Inc. differentiates via Asian flavor specialization and grain-forward recipes that compete in North American specialty retail.
Baked savoury snacks comprise dry, shelf-stable products manufactured through forced-air or radiant-heat thermal processing rather than oil immersion, typically achieving moisture content below four percent to deliver crisp texture and extended ambient stability for retail and foodservice distribution. The cracker segment leads volume contribution due to its breakfast and entertaining versatility, while the chips category captures faster growth as potato and vegetable-based baked alternatives displace fried equivalents in convenience stores. Pouch packaging dominates material efficiency and resealability requirements, though tube formats command premium placement in European specialty shops where portion control drives purchase behavior.
The FDA oversees sodium disclosure and nutrient-content claims that shape reformulation priorities, while the USDA administers organic certification standards governing ingredient sourcing for premium-positioned lines. The EU Green Deal and associated Farm-to-Fork targets are forcing ingredient traceability upgrades across export-bound portfolios. Stakeholders must monitor evolving front-of-pack labeling requirements across multiple jurisdictions to anticipate compliance-driven portfolio restructuring.
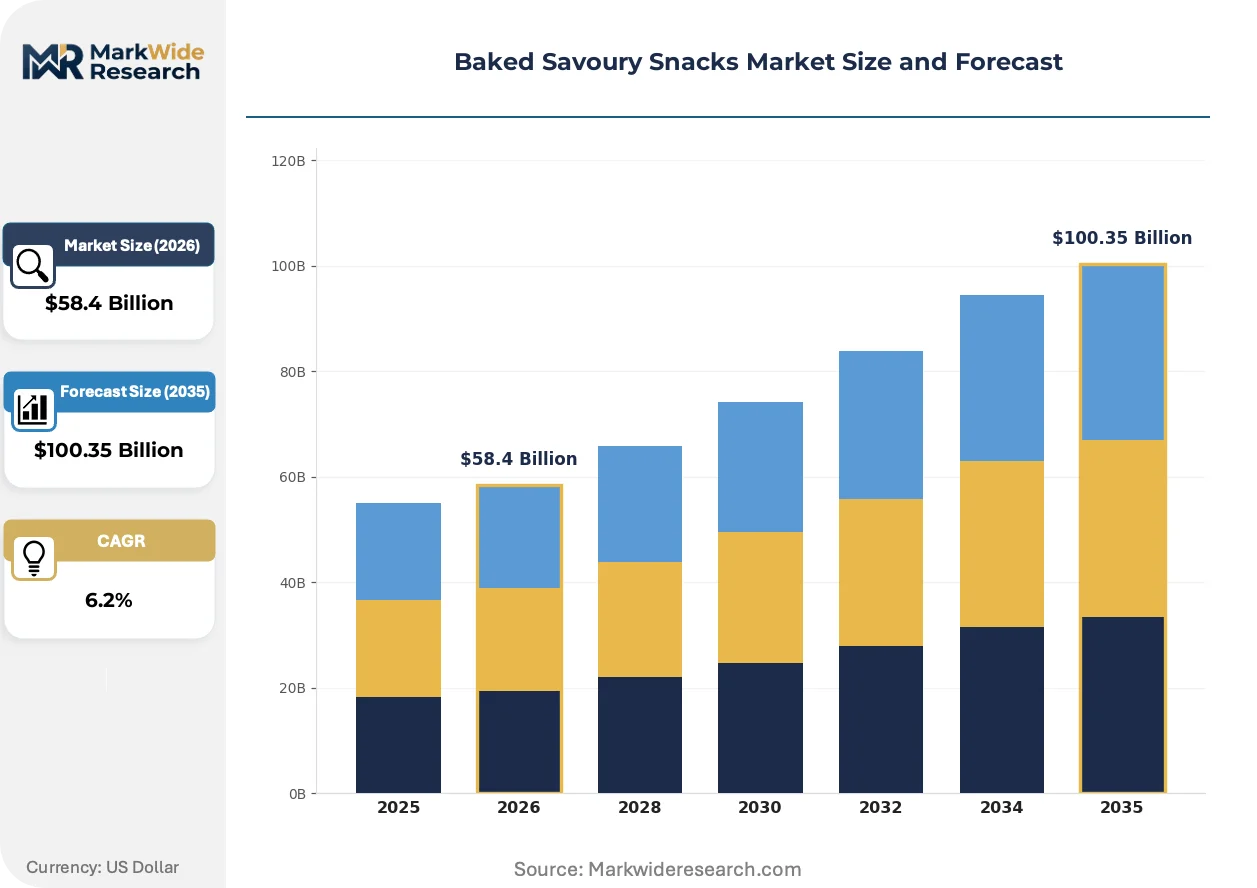
Market Dynamics
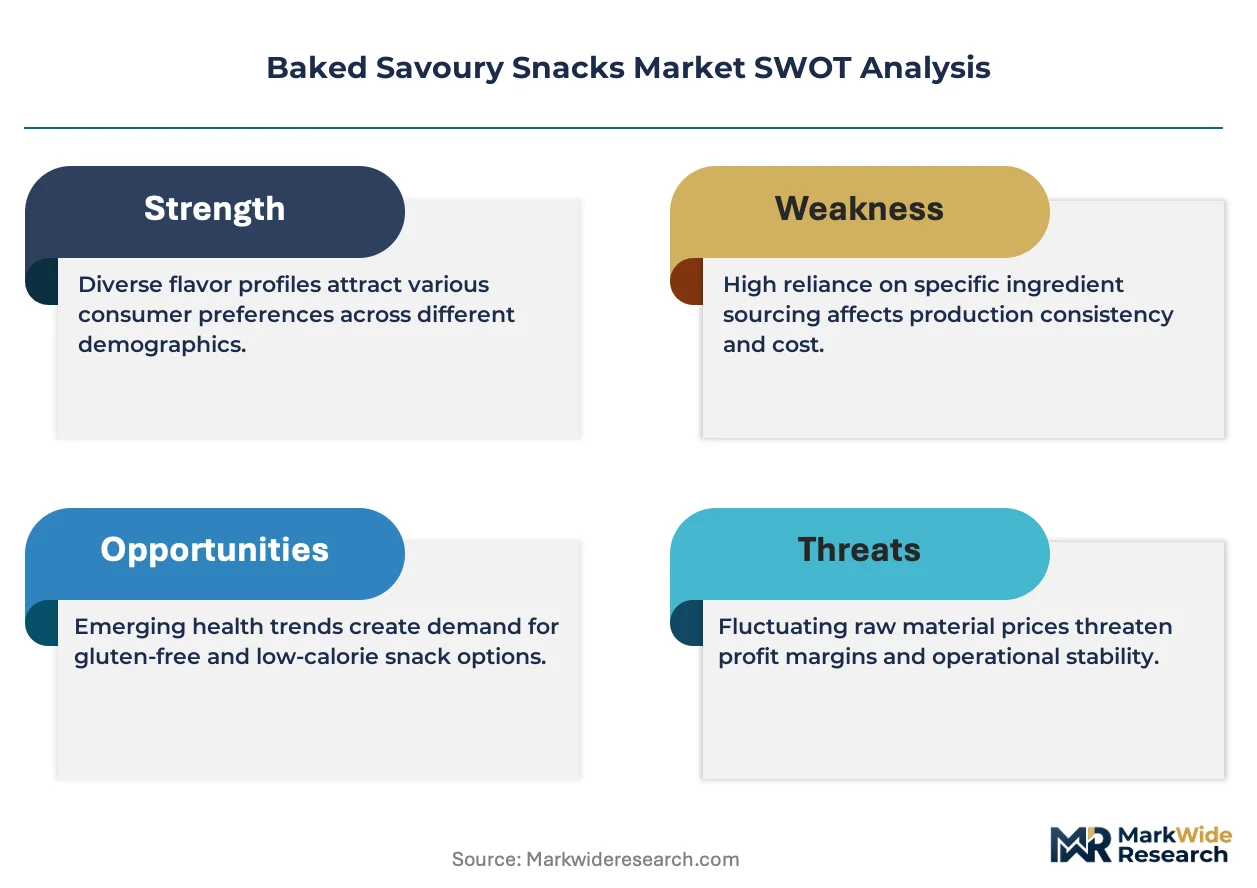
Clean-label sodium reduction mandates from the FDA are forcing accelerated ingredient reformulation across baked savoury snacks, compressing legacy formulation cycles and redistributing competitive advantage toward suppliers with proprietary salt-replacement technologies.
Growth Catalysts
- Club-channel penetration:Warehouse club expansion in the United States is creating dedicated shelf space for bulk-format baked alternatives, driving volume commitments from co-manufacturers.
- EU Green Deal traceability:Export-bound portfolios are upgrading ingredient sourcing documentation to meet Farm-to-Fork targets, differentiating premium-positioned lines in North American specialty retail.
- Forced-air thermal processing:Advances in radiant-heat oven efficiency are reducing energy intensity per unit output, improving margin structure for regional entrants.
Market Restraints
- Potato flake input volatility:Weather-driven supply fluctuations in major growing regions are compressing gross margins for chip-format producers without long-term contracting.
- Supply concentration in pouch films:Specialty high-barrier packaging substrates rely on a limited supplier base in East Asia, creating vulnerability to logistics disruptions.
- Moisture-content technical floor:Four-percent moisture thresholds constrain texture innovation, limiting product differentiation versus fried alternatives in convenience channels.
Strategic Opportunities
- Indian urban convenience retail:Modern trade expansion in tier-one cities offers white space for baked cracker formats adapted to local spice palates.
- Tube-format premium placement:European specialty-shop channel conventions around portion-controlled packaging present licensing opportunities for North American brands.
- USDA organic certification tailwind:Premium private-label programs are mandating certified ingredient sourcing, rewarding early compliance investments.
Industry Challenges
- Sensory scientist talent scarcity:Cross-functional expertise in salt reduction without flavor degradation remains concentrated at a handful of ingredient technology firms.
- Clean-label capex intensity:Natural preservative systems require accelerated production line turnover, straining regional co-manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baked Savoury Snacks Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $100.35 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crackers, Chips, Breadsticks, Pretzels Flavor Profile: Spicy, Cheese, Herb, Savory Packaging Type: Bags, Boxes, Pouches, Tubes Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Kellanova, Campbell Soup Company, PepsiCo Inc., The Hain Celestial Group Inc., Conagra Brands Inc., Mondelez International, Calbee Inc., Nestlé S.A., General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baked Savoury Snacks Market Emerging Trajectories
Formulation science and thermal processing hardware are converging to redefine texture and shelf-stability benchmarks, while regulatory disclosure requirements and channel-specific packaging norms are segmenting competitive capabilities.
Advanced enzyme-based dough conditioning is migrating from artisan bakery applications into high-throughput cracker production, enabling cleaner ingredient decks without structural compromise. Mid-sized co-manufacturers in the Midwest are piloting these systems to secure club-channel contracts. The technology is migrating from niche premium lines toward mainstream private-label supply, compressing the innovation gap between legacy brands and regional challengers.
The FDA's updated sodium disclosure rules are reshaping front-of-pack claim strategies, forcing reformulation timelines that outpace traditional R&D cycles. Manufacturers are accelerating partnerships with salt-replacement ingredient suppliers to maintain permissible nutrient-content claims. Baked chip formats in US convenience stores face the steepest compliance burden, driving consolidation of formulation expertise among fewer technical service providers.
Resealable pouch specifications are tightening as convenience-store chains demand extended shelf-life performance without preservatives. Brand owners are specifying oxygen-scavenging substrates and laser-perforation patterns that were previously limited to premium European imports. This specification escalation is most visible in the US club-channel, where bulk-format expectations now match single-serve freshness windows.
Baked Savoury Snacks Market Segmentation
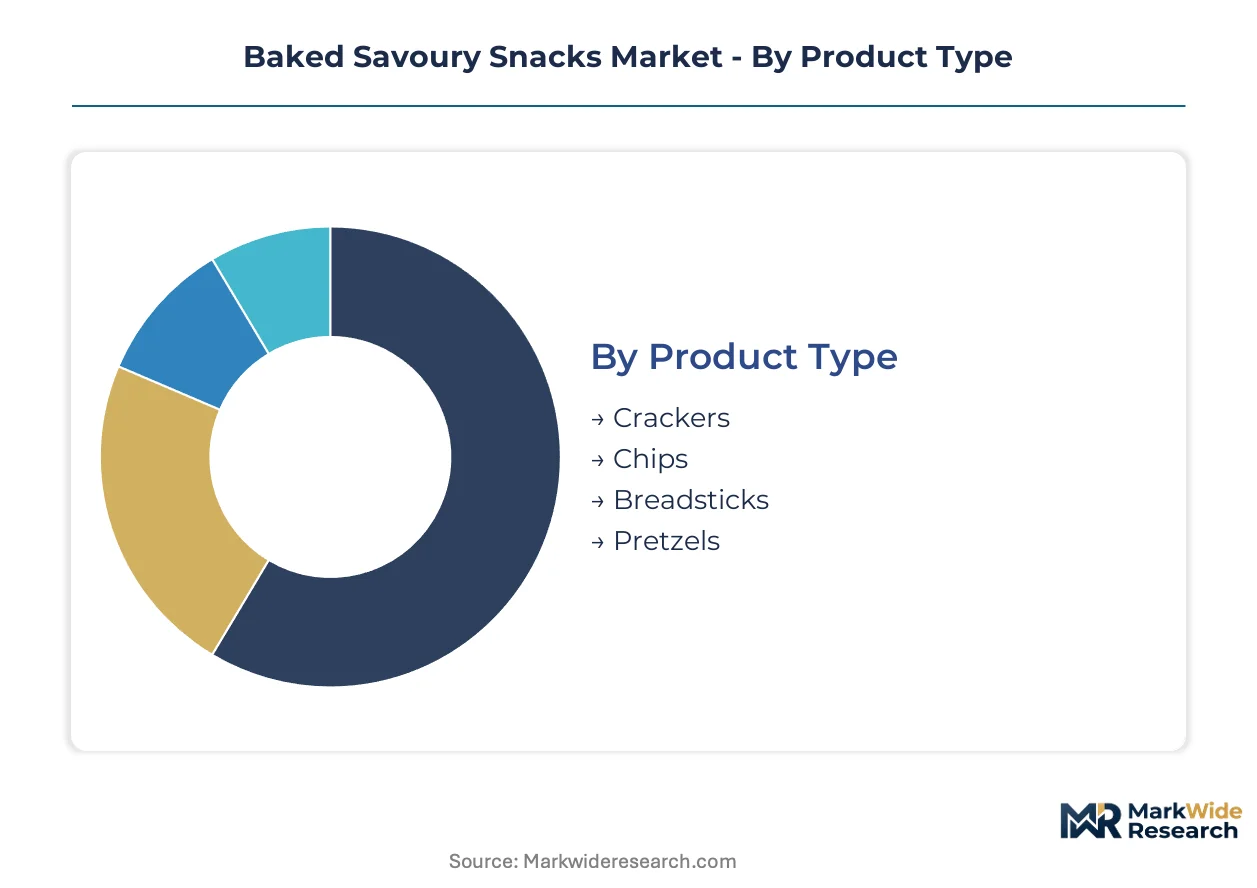
Segmentation in baked savoury snacks reflects divergent consumption rituals across channels and occasions. Product format determines thermal processing investment and margin structure, while packaging geometry shapes shelf-life engineering and retail placement economics.
Product Type:
The use-case spectrum spans breakfast accompaniment, entertaining platters, on-the-go fuel, and bar-snack occasions across household and foodservice contexts.
- Crackers:Thin, crisp flatbreads manufactured through lamination or rotary molding, achieving moisture content below three percent for extended ambient stability. Demand concentrates in US club channels where bulk formats serve entertaining occasions, though sodium-reduction mandates from the FDA complicate traditional formulation architectures.
- Chips:Sliced potato or vegetable substrates processed through forced-air radiant heat rather than oil immersion. US convenience stores are displacing fried alternatives with these formats, yet the four-percent moisture floor constrains texture parity and drives sensory scientist scarcity at reformulation partners.
- Breadsticks:Extruded or sheeted dough rods with elongated geometry demanding specialized oven conveyance systems.
- Pretzels:Alkaline-boiled and baked knot formats with distinctive Maillard crust chemistry and higher sodium baselines.
Established volume favors crackers; emerging adoption favors chips.
Flavor Profile:
Cost tier stratification separates commodity base flavors from premium positioning through ingredient provenance and complexity layering.
- Spicy:Capsicum-derived heat systems ranging from mild paprika to high-Scoville extracts, requiring flavor encapsulation to prevent lipid oxidation in low-moisture matrices. US specialty retail and Asian export markets concentrate demand, with Calbee's grain-forward Asian recipes establishing benchmark intensity levels.
- Cheese:Dehydrated dairy powders, enzyme-modified concentrates, and nutritional yeast blends delivering umami depth without moisture compromise. Club-channel bulk formats in the United States mandate cost-optimized cheese flavor systems that withstand extended warehouse holding periods.
- Herb:Dried botanical inclusions and essential oil encapsulates targeting Mediterranean and garden-positioned lines.
- Savory:Base umami platforms including yeast extract, hydrolyzed proteins, and fermented seasonings for clean-label reformulation.
Mainstream velocity clusters around cheese; premium expansion tracks spicy.
Packaging Type:
Application context determines barrier specifications, with convenience channels demanding resealability and specialty retail privileging portion control aesthetics.
- Pouches:Flexible laminated films with oxygen-scavenging substrates and laser perforation patterns, specified increasingly for US club-channel bulk formats requiring single-serve-equivalent freshness windows. The supply concentration in East Asian high-barrier film substrates creates logistics vulnerability.
- Tubes:Rigid paperboard cylinders with foil or plastic ends, commanding premium placement in European specialty shops where portion control drives purchase behavior and licensing opportunities exist for North American brands.
- Bags:Standard flexible packaging with twist-tie or zip-lock closures for value-tier positioning.
- Boxes:Folding carton secondary packaging for multi-serve retail and pantry storage visibility.
Volume economics favor pouches; margin capture favors tubes.
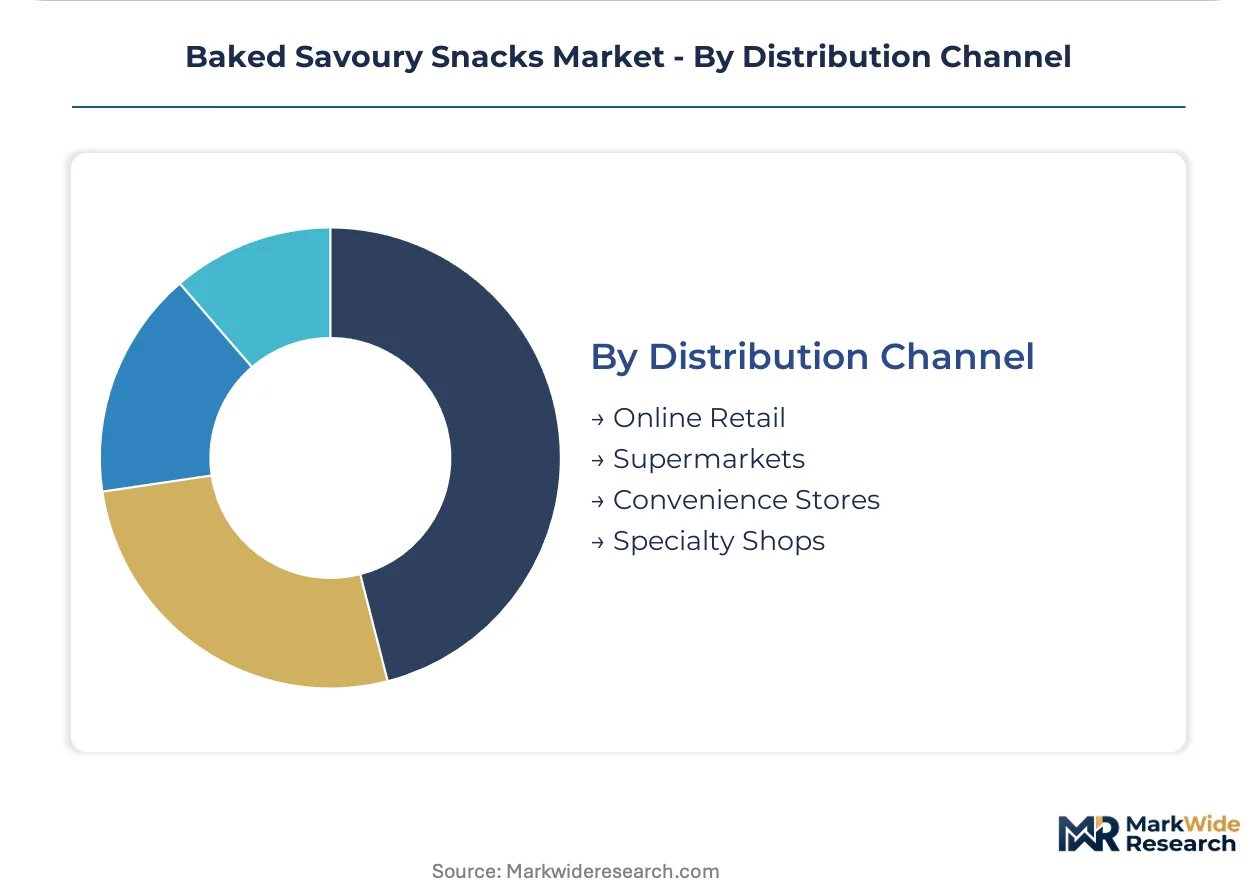
Distribution Channel:
Customer type fragmentation separates mission-driven pantry stockers from impulse purchasers and experiential specialty seekers.
- Supermarkets:Full-assignment retail with shelf-space negotiations determining SKU breadth, where private-label programs are deepening category development through asset-light co-manufacturing partnerships. PepsiCo's direct-store-delivery infrastructure sustains dominance here.
- Convenience Stores:Immediate-consumption channels expanding shelf space for baked alternatives as consumers shift from fried options, with resealable pouch specifications tightening to match extended freshness expectations without preservatives.
- Online Retail:Direct-to-consumer and platform-mediated fulfillment with damage-rate and freshness-window complications.
- Specialty Shops:Curated assortment channels in European and North American urban centers, where EU Green Deal traceability documentation differentiates premium-positioned lines.
Transaction density concentrates in supermarkets; growth velocity clusters in convenience stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-bound baked savoury snack portfolios from North American and European manufacturers are upgrading ingredient traceability documentation to satisfy divergent regulatory regimes, while import-dependent markets in Asia-Pacific and the Middle East concentrate demand for shelf-stable formats adapted to local palates and storage conditions.
United States
Club-channel expansion and private-label program deepening drive volume concentration, with warehouse retailers mandating bulk-format specifications that match single-serve freshness windows. The FDA's updated sodium disclosure rules are compressing reformulation timelines for chip-format producers. Chicago and Minneapolis-St. Paul anchor co-manufacturing clusters where enzyme-based dough conditioning systems are migrating from artisan applications into high-throughput cracker production.
Germany
Premium tube-format positioning in specialty retail channels commands licensing interest from North American brands seeking European market entry. The EU Green Deal's Farm-to-Fork targets are forcing ingredient sourcing documentation upgrades across export-bound portfolios. The Baden-Württemberg region hosts formulation technology providers specializing in salt-replacement systems for clean-label reformulation.
Japan
Grain-forward recipes and Asian flavor specialization from domestic manufacturers are establishing benchmark intensity levels for export markets. METI standards on food manufacturing efficiency are accelerating radiant-heat oven technology adoption. The Kanto region around Tokyo concentrates R&D facilities for high-barrier packaging substrates with oxygen-scavenging specifications.
India
Modern trade expansion in tier-one cities offers white space for baked cracker formats adapted to local spice palates and ambient storage conditions. FSSAI labeling requirements are tightening disclosure standards for nutrient-content claims. Maharashtra and Karnataka host pilot production facilities testing forced-air thermal processing adaptations for tropical humidity environments.
United Kingdom
Specialty retail channels in London and Southeast England curate premium-positioned lines differentiated by EU Green Deal traceability documentation. The Competition and Markets Authority's scrutiny of private-label supply arrangements is reshaping co-manufacturing contract structures. The Midlands region concentrates biscuit-to-snack technology transfer capabilities serving European export markets.
Baked Savoury Snacks Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: multinational CPG conglomerates with direct-store-delivery infrastructure, mid-sized co-manufacturers with flexible production assets, and regional specialists with flavor or format-specific expertise. Strategic archetypes include scale-driven shelf-space dominators, asset-light private-label enablers, and premium-positioned innovation boutiques. Competitive moves concentrate on co-manufacturing partnerships to bypass capital-heavy production investments and on club-channel contract acquisition to secure volume commitments.
Within the multinational conglomerate tier, PepsiCo Inc., Mondelez International, and Calbee Inc. occupy positions that exemplify divergent competitive vectors. PepsiCo leverages direct-store-delivery infrastructure across convenience and club channels. Mondelez anchors its presence through technology transfer capabilities spanning biscuit and snack formats. Calbee represents the specialist archetype with grain-forward formulation expertise and Asian flavor specialization competing in North American specialty retail.
| Leading Market Players |
|---|
| Kellanova |
| Campbell Soup Company |
| PepsiCo Inc. |
| The Hain Celestial Group Inc. |
| Conagra Brands Inc. |
| Mondelez International |
| Calbee Inc. |
| Nestlé S.A. |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Midwest co-manufacturing clusters is compressing contract pricing for private-label baked savoury snacks while simultaneously accelerating supplier consolidation around enzyme-based dough conditioning capabilities. This utilization dynamic rewards buyers with volume commitments and punishes regional entrants lacking club-channel scale.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the baked savoury snacks market. Price differentiation rests on certification grade—USDA organic tiers command substantial premiums—and volume scale, with warehouse club commitments securing lowest unit economics. Cost compression in the economy tier is intensifying because potato flake input volatility has transferred margin pressure downstream. Convenience store chains exhibit highest price sensitivity due to thin category margins, while specialty retailers demonstrate lowest sensitivity when traceability documentation justifies premium positioning.
Supply Chain Analysis
Upstream feedstock concentration in the United States, Canada, and Germany shapes ingredient security for baked savoury snack manufacturers. Potato flake and grain inputs draw from North American agricultural processing hubs, while specialty high-barrier pouch films hinge on East Asian substrate suppliers. Single-source vulnerability in packaging substrates creates exposure to logistics disruptions across Pacific routes. Distribution runs through direct-store-delivery networks for multinational incumbents and third-party logistics for private-label co-manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among warehouse club operators and convenience store chains, fragmenting supplier leverage and forcing asset-light production models across the baked savoury snacks category.
For Market Incumbents: Build formulation expertise moats through captive salt-replacement technology partnerships to defend against regional challengers exploiting enzyme-based dough conditioning. Secure club-channel contract renewals before co-manufacturing capacity consolidates further. Prioritize FDA sodium disclosure compliance investments to maintain permissible nutrient-content claims. For New Entrants and Emerging Players: Indian tier-one urban convenience retail represents the most penetrable entry point for baked cracker formats adapted to local spice palates and ambient storage conditions. European specialty shop tube-format licensing offers second-mover premium positioning without capital-heavy production investments. Pursue co-manufacturing partnerships with Midwest facilities piloting radiant-heat oven efficiency upgrades. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among co-manufacturers with multi-year private-label supply agreements and club-channel volume commitments. Over a five-to-ten-year horizon, acquisition targets should demonstrate proprietary thermal processing adaptations or regional flavor specialization. Monitor FDA enforcement patterns on sodium disclosure as an inflection indicator for reformulation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | Salt-replacement technology alliances with FDA-compliant ingredient suppliers compress R&D cycles for chip-format producers. |
| Club-Channel Contract Acquisition | Warehouse club volume commitments in the United States secure utilization rates for Midwest co-manufacturing clusters. |
| EU Green Deal Traceability Upgrade | Farm-to-Fork documentation investments differentiate premium lines in German and British specialty retail channels. |
| Asian Flavor Portfolio Extension | Grain-forward recipes adapted from Japanese formulation benchmarks capture North American specialty retail growth. |
| High-Barrier Packaging Specification Escalation | Oxygen-scavenging substrates and laser-perforation patterns match European freshness standards for US club-channel bulk formats. |
Methodological Framework
A standing panel of category buyers at warehouse clubs, convenience store chain procurement directors, co-manufacturing plant managers, and sensory scientists at ingredient technology firms provided ongoing calibration throughout this study. Primary interview insights were cross-referenced against secondary sources including FDA sodium disclosure filings, USDA organic certification databases, Nielsen retail audit data, and EU Farm-to-Fork traceability documentation. Bottom-up volume modeling from segment-level consumption patterns was reconciled with top-down category expenditure estimates.
Scenario-bracketing around regulatory enforcement intensity and input cost volatility framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product format, flavor profile, packaging geometry, and distribution channel, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from trend extrapolation adjusted for structural shift probabilities, incorporating forced-air thermal processing efficiency curves and club-channel penetration trajectories as industry-specific inputs.
Practitioners should monitor FDA sodium disclosure enforcement patterns, potato flake supply contract renegotiation cycles, and East Asian high-barrier film logistics disruptions for early signals requiring forecast revision. Cross-checking against Nielsen retail velocity data and club-channel SKU proliferation rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
No-Fat Peanut Butter Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
North America Fruit Snacks Market
Snacks
Middle East Snack Bar Market
Snacks
South America Frozen Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
United States Children's Snack Bar Market
Snacks
United States Snack Bar Market
Snacks
Healthy Snacks Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Italy Energy Bar Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Snack Products Market
Snacks
UK Snack Market
Snacks
Jerky Snacks Market
Snacks
Australia Snack Bar Market