
 North America Pretzel Market | 2026-2036
North America Pretzel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pretzel Market Intelligence
Bakery technician availability across the Great Lakes and Mid-Atlantic manufacturing belt is collapsing, forcing pretzel producers to automate mixing and twisting lines faster than workforce pipelines refill. Snyder's of Hanover leverages its Pennsylvania heritage to anchor brand authenticity in hard pretzel segments. Utz Brands sustains regional manufacturing scale across multiple Mid-Atlantic facilities. J&J Snack Foods Corp. dominates soft pretzel distribution through its captive food-service channel network.
North America pretzels are wheat-flour-based baked goods formed into knot shapes or extruded forms, typically finished with alkaline lye or baking soda dips that create their signature mahogany crust and chewy interior texture; they serve as shelf-stable snacks, food-service accompaniments, and portable meal components. Hard pretzels retain moisture below four percent, enabling extended retail distribution through supermarkets where margin pools concentrate on multi-flavor variety packs. Soft pretzels command premium positioning through food-service channels where cheese and cinnamon sugar flavor profiles drive impulse purchases. Online retailers represent the fastest-expanding distribution vector for specialty and artisanal pretzel formats.
The FDA governs sodium labeling and nutrient content claims for packaged pretzels, while USDA standards apply to institutional food-service procurement contracts that shape bulk purchasing requirements. State-level cottage food laws across Texas, California, and New York create fragmented pathways for artisanal pretzel makers entering retail. Stakeholders must monitor how clean-label ingredient mandates and front-of-package warning systems in Canada and select US states reshape formulation priorities and consumer communication strategies.
Market Dynamics
Bakery technician shortages across the Great Lakes and Mid-Atlantic manufacturing belt are forcing pretzel producers to accelerate automation timelines, compressing the window for workforce-dependent mixing and twisting operations.
Growth Catalysts
- Convenience store expansion:Quick-service restaurant chains and c-store operators are widening pretzel menu placements, creating captive demand for both hard and soft formats.
- USDA institutional procurement:Federal food-service contracts for schools and military facilities sustain bulk volume commitments that stabilize production scheduling.
- Online retail velocity:Direct-to-consumer channels for artisanal and specialty pretzel formats are capturing incremental margin pools beyond traditional supermarket distribution.
Market Restraints
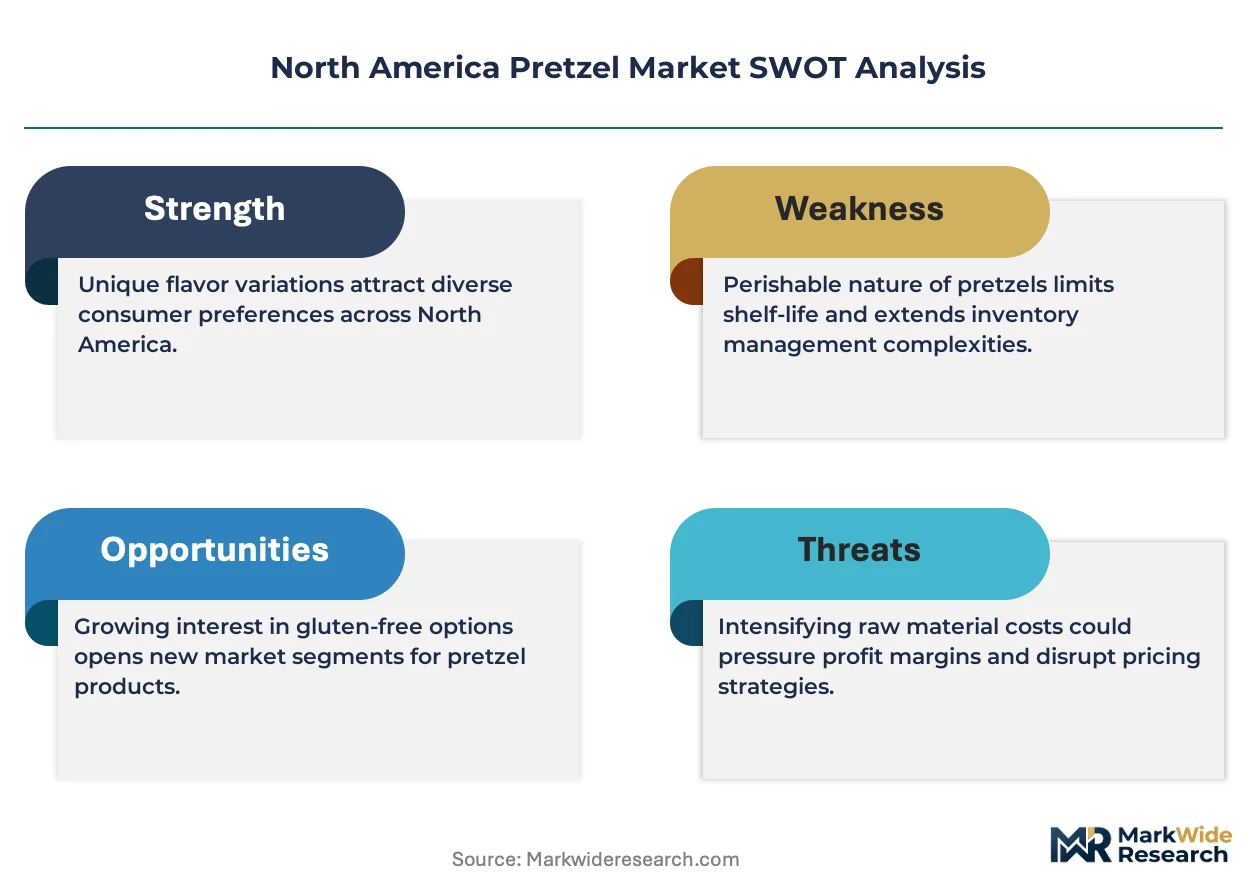
- Wheat input volatility:Hard red winter wheat prices fluctuate with drought cycles across the US Great Plains, compressing bakery margin structures.
- FDA sodium mandates:Updated federal reduction targets for packaged snacks are forcing reformulation investments that lag consumer taste acceptance curves.
- Regional labor concentration:Pretzel manufacturing expertise clusters in Pennsylvania and adjacent states, creating geographic vulnerability to localized workforce disruptions.
Strategic Opportunities
- Texas cottage food pathways:State-level home-kitchen licensing laws enable artisanal producers to test regional flavor profiles before scaling to commercial facilities.
- Clean-label ingredient convergence:Fermented flour processes and natural browning agents are opening premium positioning against conventional alkaline-dip formulations.
- Food-service equipment integration:Compact convection ovens with pretzel-specific humidity controls are expanding soft pretzel penetration into non-traditional retail environments.
Industry Challenges
- Mechatronics skill scarcity:Automated twisting and glazing lines require technicians cross-trained in PLC programming and food-grade sanitation protocols.
- Legacy equipment retrofit costs:Existing Pennsylvania and Maryland facilities face seven-figure capital outlays to integrate vision-guided quality inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pretzel Market |
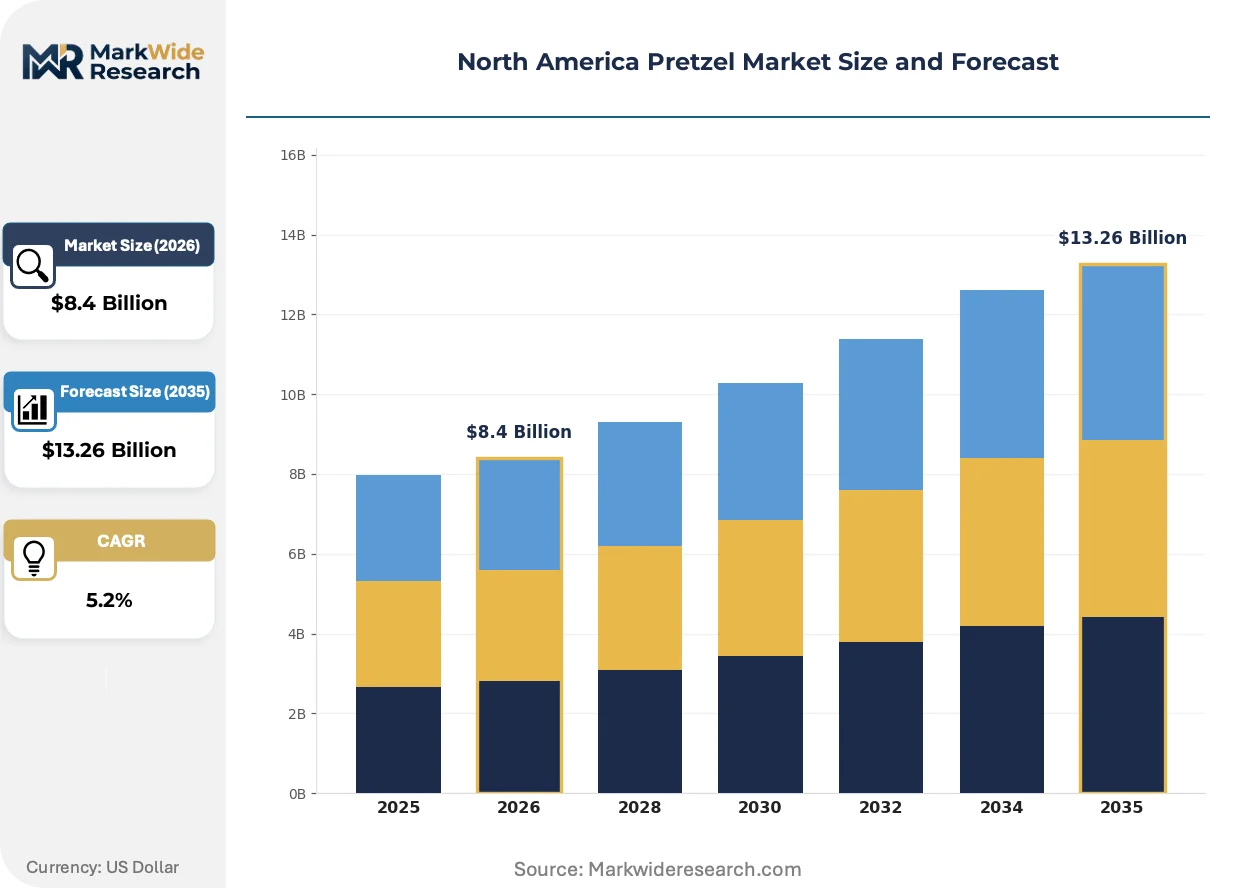
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Pretzels, Hard Pretzels, Pretzel Bites, Pretzel Sticks Flavor Profile: Sea Salt, Garlic, Cheese, Cinnamon Sugar Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Food Service Packaging Type: Bags, Boxes, Vaults, Tubs |
| Companies Covered | Auntie Anne's, Utz Brands, PepsiCo, The Hershey Company, Snyder's of Hanover, Frito-Lay, J&J Snack Foods Corp., Herr Foods, ConAgra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pretzel Market Strategic Shifts & Innovations
Reformulation pressures and channel fragmentation are reshaping how pretzel producers balance heritage authenticity against operational scalability and regulatory compliance.
Enzymatic browning systems using fungal amylase and glucose oxidase are supplanting traditional lye dips in artisanal production lines. Regional craft bakeries across New York and California are adopting these enzymatic approaches to bypass hazardous chemical handling requirements. The shift is compressing batch-to-batch color variation while extending equipment maintenance intervals.
FDA front-of-package sodium disclosure proposals are forcing portfolio segmentation between compliant formulations and heritage recipes. Mid-Atlantic producers are running parallel production lines to preserve traditional taste profiles for regional consumers while developing reduced-sodium variants for national distribution. Hard pretzel variety packs face the steepest reformulation timelines given their shelf-stable concentration in retail channels.
Food-service buyers are consolidating pretzel procurement through broadline distributors rather than direct manufacturer relationships. Regional restaurant chains across the Midwest are shifting from captive bakery supply to frozen dough programs managed by specialized distributors. This pattern concentrates most visibly in Ohio and Illinois, where multi-unit operators prioritize labor reduction over in-house production control.
North America Pretzel Market Segmentation
Pretzel producers navigate four distinct segmentation axes where channel access, formulation costs, and regional taste preferences intersect. Each dimension shapes capital allocation decisions and margin capture potential differently.
Product Type:
Channel-mix dynamics split sharply across these four formats, with hard varieties dominating retail shelf space while soft formats anchor food-service throughput.
- Soft Pretzels:Moisture content above 15% requires frozen or refrigerated distribution chains. Demand concentrates in Northeast and Midwest stadiums, malls, and quick-service outlets where impulse cheese-dip attachments drive ticket averages. Labor-intensive shaping operations constrain throughput at smaller bakeries.
- Hard Pretzels:Low-moisture baking below 4% enables ambient distribution through supermarkets and convenience stores. Pennsylvania and Maryland production clusters supply national retail networks with extended shelf-stable windows. Seasoning adherence technologies differentiate competing brands in crowded snack aisles.
- Pretzel Bites:Bite-sized formats target lunchbox and on-the-go consumption through single-serve packaging. School food-service contracts in Texas and California specify portion-controlled counts.
- Pretzel Sticks:Linear geometry suits automated dipping and coating lines. Bar and restaurant channels in Illinois and Ohio specify stick formats for shared-plate presentations.
By volume, Hard Pretzels leads. By growth pace, Soft Pretzels is expanding most quickly.
Flavor Profile:
Cost-tier stratification separates commodity formulations from premium positioning, with ingredient sourcing geography determining margin structures.
- Sea Salt:The baseline formulation across all channels. Great Plains-sourced salt minimizes input cost volatility for high-volume producers. Midwest consumers show strongest loyalty to traditional sea-salt profiles.
- Garlic:Dehydrated and roasted garlic variants command 15-25% price premiums in specialty retail. California garlic processors supply artisanal bakeries with single-origin ingredient storytelling.
- Cheese:Powdered cheese coatings dominate mass-market bags while liquid cheese accompaniments anchor food-service attachment sales. Wisconsin and Vermont dairy linkages support regional brand differentiation.
- Cinnamon Sugar:Sweet positioning captures afternoon snack occasions beyond traditional savory pretzel consumption. Northeast mall-based retailers report strongest per-unit margins on fresh-baked cinnamon sugar formats.
Sea Salt captures the largest volume base. Cinnamon Sugar is climbing the fastest as producers target dessert-snack occasion expansion.
Distribution Channel:
Customer-type concentration shapes service-level requirements, with institutional buyers demanding contract stability and direct-to-consumer channels prioritizing fulfillment velocity.
- Supermarkets:Multi-flavor variety packs and seasonal displays drive category management negotiations. Slotting fee structures in California and New York metro markets concentrate volume with top-three producers.
- Convenience Stores:Single-serve bags at price points below $2.00 dominate impulse purchase patterns. Texas and Florida c-store chains are expanding private-label pretzel placements.
- Online Retailers:Direct-to-consumer channels enable artisanal producers to bypass traditional distribution markups. Subscription box integrations in Pacific Northwest metro areas support specialty flavor testing.
- Food Service:Frozen dough programs and pre-baked formats reduce labor requirements for restaurant operators. Ohio and Illinois broadline distributors are consolidating pretzel procurement across multi-unit chains.
Supermarkets lead by volume. Online Retailers show the steepest expansion trajectory as specialty producers build direct customer relationships.
Packaging Type:
Supply concentration in flexible film and rigid container manufacturing shapes procurement leverage for pretzel producers.
- Bags:Flexible film dominates hard pretzel retail with high-speed form-fill-seal compatibility. Midwest flexible packaging converters serve Pennsylvania and Maryland bakery clusters.
- Boxes:Corrugated and paperboard formats support gift and seasonal premium positioning. Northeast retail destinations specify box formats for private-label holiday assortments.
- Vaults:Rigid resealable containers protect fragile stick and twist geometries through distribution. PET and PP resin cost exposure tracks Gulf Coast petrochemical pricing.
- Tubs:Rigid containers with snap-fit lids target food-service and club-store bulk formats. Texas and California dairy-pretzel combination packs favor tub presentation.
Bags lead by volume. Vaults are gaining share fastest as producers invest in breakage reduction for premium tier products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply, with United States consumers driving premium soft-pretzel food-service attachments while Canadian buyers favor hard-pretzel retail variety packs and Mexican demand concentrates on private-label export manufacturing.
United States
Stadium concessions and quick-service restaurants in the Northeast and Midwest generate the highest per-capita soft-pretzel consumption. FDA sodium reduction mandates are compressing reformulation timelines for packaged snack portfolios. Pennsylvania's Lancaster County and adjacent Maryland manufacturing clusters anchor hard-pretzel production capacity serving national retail networks.
Canada
Supermarket private-label programs in Ontario and Quebec absorb substantial hard-pretzel import volumes from United States producers. Health Canada's front-of-package sodium warning labels are accelerating clean-label product development cycles. Greater Toronto Area distribution hubs coordinate cross-border logistics for seasonal promotional volumes.
Mexico
Maquiladora operations in Nuevo León and Baja California process pretzel ingredients for re-export to United States retail chains. Mexican federal food-labeling regulations under COFEPRIS align with evolving North American trade compliance requirements. Guadalajara's baking equipment sector supplies automated twisting machinery to regional producers.
North America Pretzel Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale-driven manufacturers controlling supermarket shelf space while regional craft operators capture food-service and direct-to-consumer channels. The structure rewards backward integration into wheat milling and seasoning production. Two archetypes dominate: heritage-brand regionalists leveraging geographic authenticity, and diversified snack conglomerates optimizing cross-category distribution density. Competitive moves center on frozen dough program partnerships with broadline distributors and enzymatic browning technology licensing for clean-label reformulations.
Within the heritage-regionalist tier, Snyder's of Hanover and Utz Brands exemplify Pennsylvania-origin positioning that commands price premiums in hard-pretzel segments. J&J Snack Foods Corp. occupies the food-service specialist position, anchoring soft-pretzel distribution through captive channel networks rather than retail competition. These three companies represent the dominant strategic configurations: geographic authenticity defense, diversified snack portfolio leverage, and vertical channel control.
| Leading Market Players |
|---|
| Auntie Anne's |
| Utz Brands |
| PepsiCo |
| The Hershey Company |
| Snyder's of Hanover |
| Frito-Lay |
| J&J Snack Foods Corp. |
| Herr Foods |
| ConAgra Brands |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Pennsylvania and Maryland pretzel manufacturing clusters shapes both supply concentration and price floors for hard pretzel retail formats. Automated twisting lines require seven-figure capital commitments that smaller regional bakeries cannot match, compressing competitive entry and stabilizing contract pricing for supermarket variety packs.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between major producers and broadline distributors serving Midwest quick-service restaurant chains. Price differentiation separates heritage-brand hard pretzels with Pennsylvania-origin storytelling from private-label economy tiers and enzymatic-browning premium lines targeting clean-label consumers. Cost compression in the economy segment is intensifying because Texas and Florida c-store chains are expanding private-label placements. School food-service buyers exhibit highest price sensitivity, while stadium concession operators accept premium positioning for fresh-baked soft pretzel attachments.
Supply Chain Analysis
Inbound logistics costs from Great Plains wheat belt to Mid-Atlantic baking clusters fluctuate with railcar availability and Ohio River barge congestion. Supply concentration centers on the United States for hard red winter wheat flour, with Canada supplying malt extracts and California providing dehydrated garlic for specialty seasonings. Single-source vulnerability exists for automated twisting machinery manufactured in Guadalajara. Distribution runs through broadline distributors consolidating frozen soft pretzel programs for Ohio and Illinois restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where Pennsylvania heritage positioning creates regulatory entrenchment through FDA facility registration requirements that artisanal entrants struggle to navigate.
For Market Incumbents: Secure frozen dough program partnerships with broadline distributors before channel consolidation locks out secondary suppliers. Expand enzymatic browning licensing to premium private-label manufacturers seeking clean-label reformulation pathways. Vertical integration into wheat milling buffers margin pressure from drought-driven input volatility.
For New Entrants and Emerging Players: Anchor in Texas cottage food licensing pathways to test regional flavor profiles with minimal capital exposure. Target Pacific Northwest subscription box channels for specialty and artisanal format validation before scaling to commercial facilities. Leverage fermented flour processes as a go-to-market differentiator against established alkaline-dip heritage brands.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors food-service equipment integrators with compact convection oven platforms expanding soft pretzel penetration into non-traditional retail environments. Five-to-ten year viability hinges on automation adoption rates among regional craft bakeries facing technician scarcity. Monitor FDA front-of-package sodium disclosure implementation as an inflection indicator for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Browning Technology Licensing | Clean-label reformulation bypasses hazardous lye handling requirements for New York and California artisanal producers. |
| Frozen Dough Program Expansion | Broadline distributor partnerships in Ohio and Illinois reduce labor requirements for multi-unit restaurant operators. |
| Backward Integration into Wheat Milling | Captive flour supply insulates margin structures from drought-driven hard red winter wheat price cycles. |
| Compact Convection Oven Platform Launch | Pretzel-specific humidity controls enable stadium and c-store operators to add fresh-baked formats without captive bakery investment. |
| Regional Heritage Brand Extension | Pennsylvania-origin storytelling commands price premiums in hard pretzel segments where authenticity drives consumer loyalty. |
Research Approach
Cross-validation between primary interviews with bakery operations managers and secondary analysis of FDA facility registration databases anchors the qualitative findings. Conversations with broadline distributor procurement heads, food-service equipment manufacturers, and artisanal bakery owners in Texas and California supplemented trade data from USDA procurement records and Nielsen retail audit information. Bottom-up volume modeling triangulates against top-down category expenditure estimates.
Sensitivity analysis around wheat input cost assumptions and automation adoption timelines informs the projection framework. Segmentation dimensions span product type, flavor profile, distribution channel, and packaging format across the analysis window. CAGRs derive from regression analysis of historical volume trajectories adjusted for channel shift patterns and regulatory compliance timelines. Enzymatic browning adoption curves and frozen dough program penetration rates serve as industry-specific forecast inputs.
Material uncertainties — FDA sodium mandate implementation timing, drought severity across the Great Plains, and mechatronics technician pipeline recovery — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and input cost normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Seafood Snacks Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Brazil Snack Bar Market
Snacks
Snack Subscription Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Fat Free Snacks Market
Snacks
North America Potato Chips Market
Snacks
Granola Bars Market
Snacks
Snack Food Packaging Market
Snacks
Europe Cereal Bar Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Sweet Potato Fries Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Premium Snacks Market
Snacks
Europe Nuts and Cereal Snacks Bar Market