
 Device-Embedded Biometric Authentication Market | 2026-2036
Device-Embedded Biometric Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Device-Embedded Biometric Authentication Market Outlook
A capital-intensity divergence between foundry-dependent sensor suppliers and in-house semiconductor designers is reorganizing competitive tiers in device-embedded biometric authentication. Samsung Electronics leverages captive semiconductor fabrication to control ultrasound sensor yields and pricing. Apple Inc. sustains proprietary facial recognition ecosystems through vertical silicon design. Fingerprint Cards AB specializes in capacitive modules for Android OEMs, occupying a cost-optimized niche against integrated rivals.
Device-embedded biometric authentication integrates fingerprint, facial, iris, or voice recognition sensors directly into hardware substrates such as smartphone displays, laptop power buttons, or payment terminals, operating at authentication speeds under 500 milliseconds with false acceptance rates below 0.001%. Its primary purpose is to replace password-based access with physiological or behavioral identifiers that remain bound to the physical device. Fingerprint scanner modules still dominate volume shipments across consumer electronics, though facial recognition is displacing them in premium banking and government deployments where liveness detection matters. Embedded systems integration captures the highest margin pools as OEMs demand turnkey sensor-plus-algorithm packages rather than discrete components. Ultrasound technology represents the fastest-growing sensor category, penetrating under-display applications where optical and capacitive methods fail.
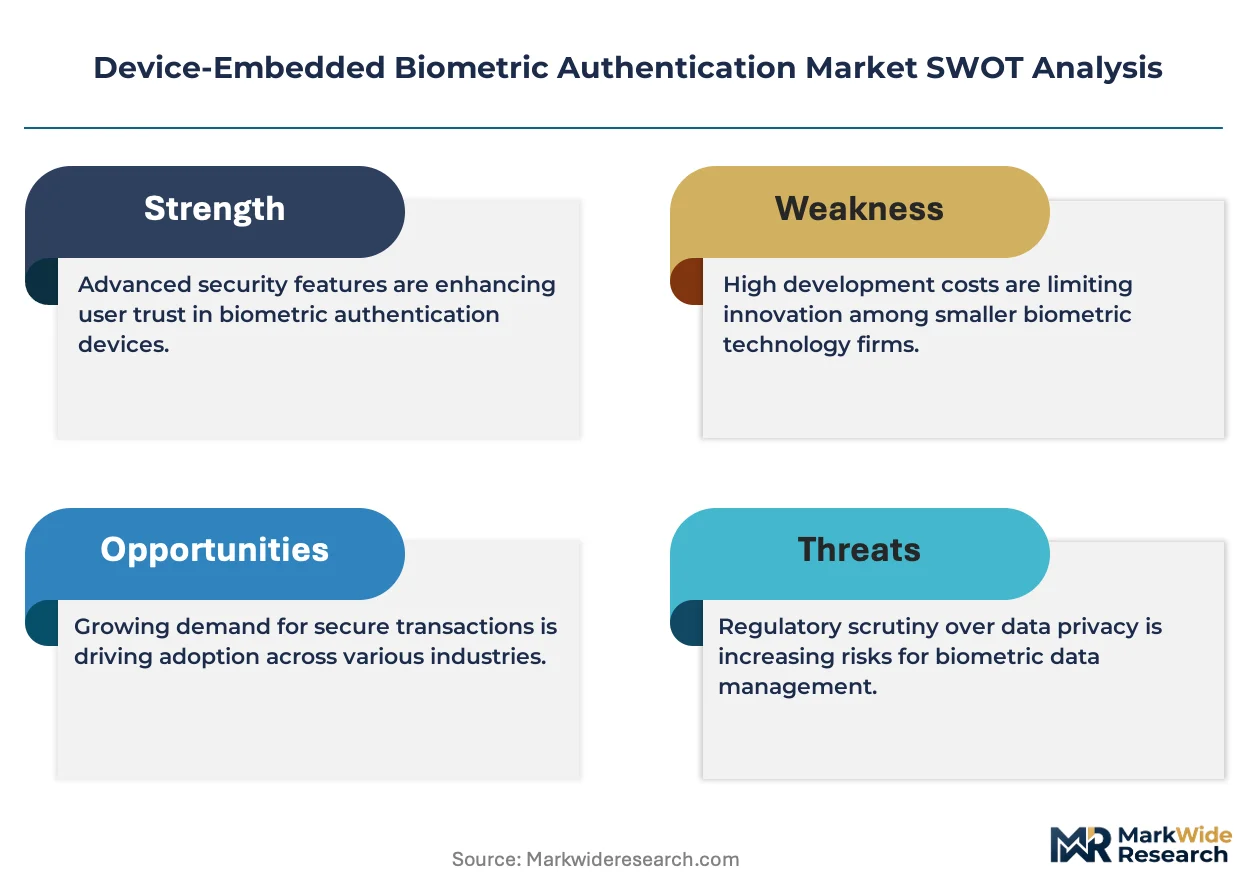
The EU AI Act, GDPR, and NIST frameworks collectively mandate on-device processing, encrypted template storage, and algorithmic bias auditing for biometric systems sold into Europe and US federal channels. China's NMPA and GB standards enforce separate domestic certification pathways for facial recognition hardware, fragmenting compliance costs for multinational suppliers. Stakeholders must monitor whether regional encryption backdoor requirements splinter product architectures or whether interoperable privacy certifications emerge as a competitive differentiator.
Market Dynamics
On-device processing mandates from the EU AI Act and GDPR are forcing sensor suppliers to abandon cloud-dependent architectures, compressing margins for foundry-dependent vendors while rewarding captive silicon designers.
Growth Catalysts
- EU AI Act compliance deadlines:European banking regulators now require liveness detection in payment terminals, pulling ultrasound and structured-light modules into high-volume deployment cycles.
- China's mid-tier smartphone refresh:Domestic OEMs embed capacitive fingerprint sensors at scale, creating sustained demand for cost-optimized module suppliers serving the sub-premium tier.
- Behavioral biometrics convergence:Keystroke dynamics and gait analysis layer onto existing hardware substrates, expanding authentication modalities without incremental sensor costs.
Market Restraints
- Foundry capacity concentration:Taiwan-based semiconductor fabrication bottlenecks constrain ultrasound sensor yields, extending lead times for under-display fingerprint modules.
- GDPR template storage requirements:Encrypted on-device biometric vaults demand specialized secure-element silicon, raising bill-of-materials costs for entry-tier device manufacturers.
- Optical sensor commoditization:Mature capacitive and optical technologies face pricing pressure from substitute authentication methods including PIN fallback and wearable-based verification.
Strategic Opportunities
- India's financial inclusion mandates:Aadhaar-linked biometric POS terminals for rural banking create demand for ruggedized fingerprint modules with offline template matching.
- Automotive cabin authentication:Driver identification via iris and facial recognition integrates with personalized seat, mirror, and infotainment profiles in premium electric vehicles.
- Healthcare device integration:NMPA-certified facial recognition for patient identity verification streamlines hospital workflows and reduces insurance fraud in Chinese medical systems.
Industry Challenges
- Algorithmic bias audit complexity:NIST FRVT and EU conformity assessment requirements demand diverse training datasets, extending product validation timelines for facial recognition vendors.
- Secure-element supply fragmentation:Multiple proprietary trusted execution environments complicate firmware development, forcing sensor suppliers to maintain parallel software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Device-Embedded Biometric Authentication Market |
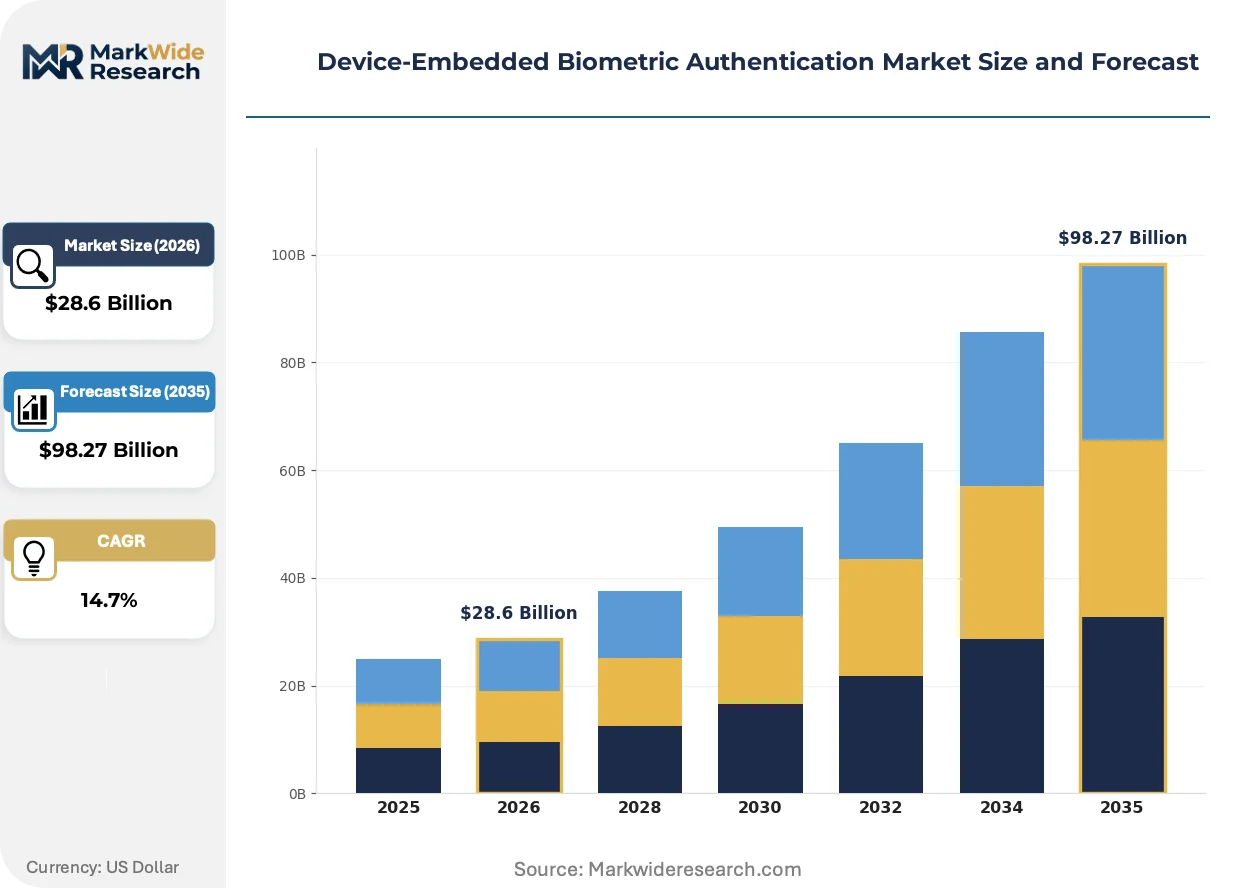
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $98.27 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Scanner, Facial Recognition, Iris Scanner, Voice Recognition End User: Consumer Electronics, Banking Institutions, Government Agencies, Healthcare Facilities Integration Level: Standalone Devices, Embedded Systems, Cloud-Based Solutions, Hybrid Models Technology: Optical Sensors, Capacitive Sensors, Ultrasound Technology, Thermal Sensors |
| Companies Covered | Samsung Electronics, Apple Inc., Qualcomm Incorporated, Huawei Technologies, NEC Corporation, Thales Group, HID Global, Fingerprint Cards AB, IDEMIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Device-Embedded Biometric Authentication Market Strategic Shifts
Authentication architectures are pivoting from centralized template databases toward edge-resident processing, compressing the attack surface while fragmenting supplier ecosystems across competing secure-compute standards.
Ultrasound fingerprint sensing is fragmenting the under-display biometric market by enabling authentication through contaminated or wet surfaces where optical methods fail. Banking terminal manufacturers in Europe and East Asia adopt this technology fastest, prioritizing liveness detection over cost. The technology is fragmenting procurement patterns as OEMs abandon single-sensor strategies in favor of multi-modal redundancy.
GDPR Article 9 and the EU AI Act's biometric identification classification impose strict purpose limitation and data minimization obligations on device manufacturers. These rules compress permissible use cases for behavioral analytics, forcing redesigns of cloud-connected voice recognition systems. Premium smartphone and laptop segments respond fastest, embedding dedicated neural processing units to isolate biometric inference from network exposure.
Enterprise buyers now unbundle hardware procurement from algorithm licensing, pressuring sensor suppliers to open their matching engines or face displacement by independent software vendors. This pattern concentrates in North American financial services and government contracting channels where interoperability certifications dominate vendor selection. Modular procurement accelerates as buyers seek to swap biometric modalities without hardware refresh cycles.
Device-Embedded Biometric Authentication Market Segmentation
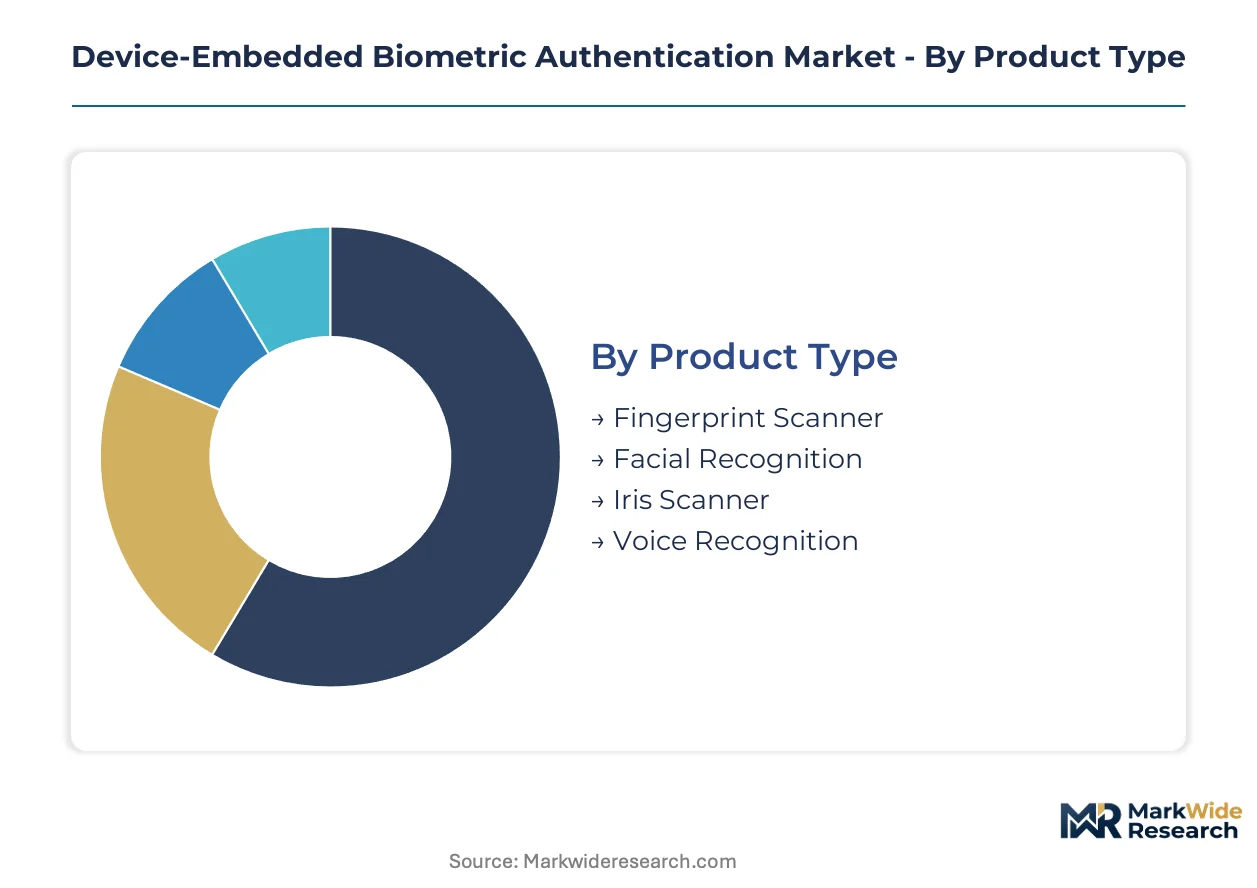
Segmentation in device-embedded biometric authentication reveals how regulatory pressure, hardware integration depth, and sensor physics create distinct procurement patterns across banking, government, and consumer channels. Each dimension exposes different margin structures and compliance burdens.
Product Type:
GDPR Article 9 and the EU AI Act impose stricter conformity assessment on facial recognition than fingerprint systems, bifurcating certification costs across modalities.
- Fingerprint Scanner:Capacitive and ultrasound modules authenticate through smartphone displays, laptop power buttons, and payment terminals at speeds under 500 milliseconds. Banking institutions in Europe embed these to satisfy PSD2 strong customer authentication mandates while keeping templates local.
- Facial Recognition:Structured-light and time-of-flight sensors enable liveness detection for high-security government and financial deployments. China's NMPA certification requirements for facial recognition hardware fragment compliance pathways for multinational suppliers.
- Iris Scanner:Near-infrared imaging penetrates contact lenses and glasses for authentication in healthcare and high-security facilities.
- Voice Recognition:Behavioral biometrics layer onto existing microphones, reducing incremental hardware costs for call center and smart speaker applications.
Fingerprint scanner modules handle the majority of throughput; facial recognition is gaining share fastest on liveness detection requirements.
End User:
Cost tier differentiation separates premium integrated solutions from economy discrete-component procurement across customer categories.
- Consumer Electronics:Smartphone and laptop OEMs demand turnkey sensor-plus-algorithm packages with false acceptance rates below 0.001%. China's mid-tier refresh cycle sustains volume for cost-optimized capacitive modules.
- Banking Institutions:Payment terminal manufacturers prioritize ultrasound and structured-light modules for liveness detection under EU AI Act compliance deadlines.
- Government Agencies:NIST FRVT certification requirements extend validation timelines for facial recognition vendors serving federal channels.
- Healthcare Facilities:Patient identity verification systems in China require NMPA-certified facial recognition to streamline hospital workflows.
Consumer electronics absorbs the highest unit volumes; banking institutions show the steepest expansion trajectory on regulatory pull-through.
Integration Level:
Application-specific architectures determine whether biometric processing occurs at the edge, in centralized infrastructure, or across hybrid topologies.
- Embedded Systems:Dedicated neural processing units isolate biometric inference from network exposure, capturing the highest margin pools as OEMs reject discrete components.
- Standalone Devices:Ruggedized fingerprint modules with offline template matching serve India's Aadhaar-linked rural banking mandates.
- Cloud-Based Solutions:Centralized template storage faces GDPR Article 9 purpose limitation constraints, forcing redesigns of voice recognition architectures.
- Hybrid Models:Edge-cloud split processing balances latency against update flexibility in enterprise access control systems.
Embedded systems command premium pricing; hybrid models are expanding most quickly as enterprises seek modality flexibility without hardware refresh.
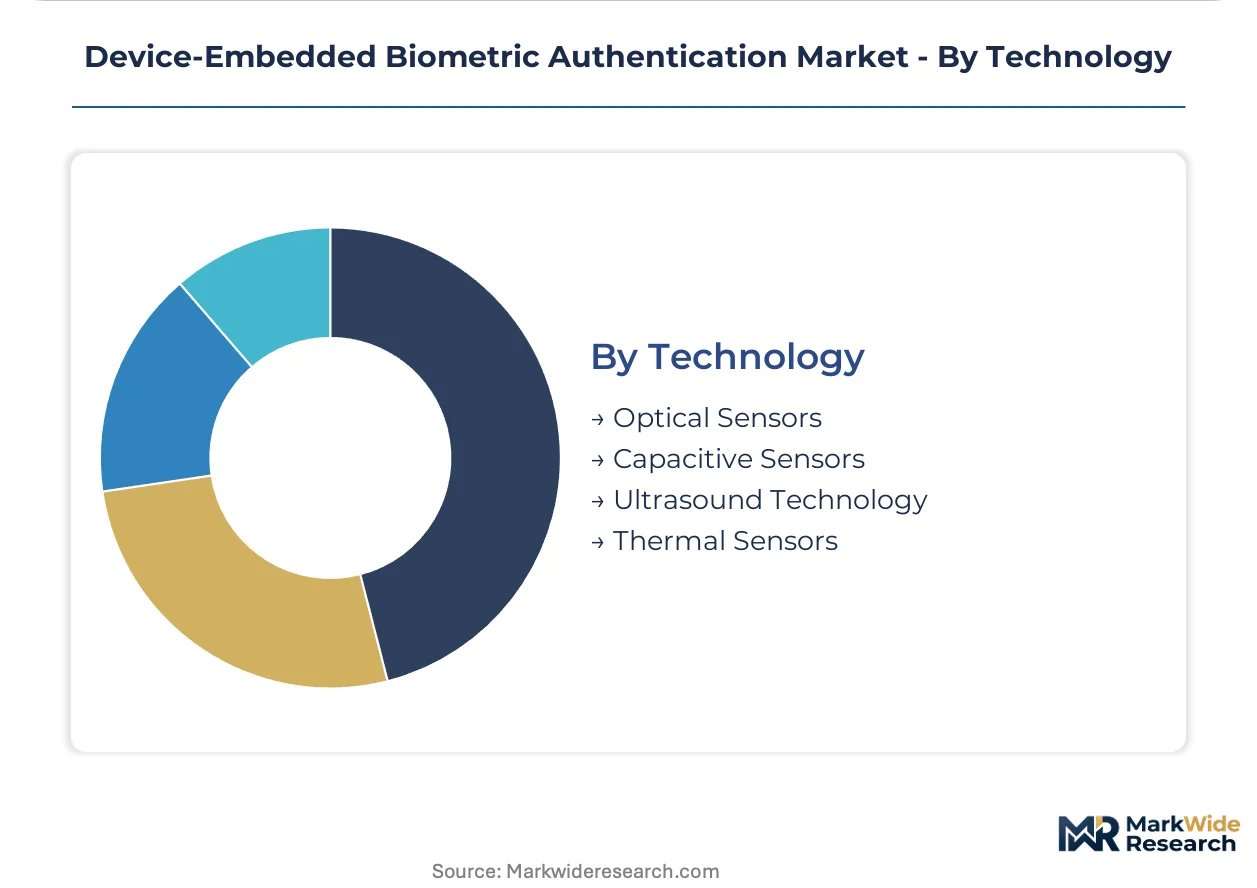
Technology:
Supply concentration in Taiwan-based semiconductor fabrication constrains yields for advanced sensor categories, extending lead times for under-display applications.
- Ultrasound Technology:Piezoelectric transducers authenticate through contaminated, wet, or thick display substrates where optical methods fail. European banking terminal manufacturers adopt this technology fastest for liveness detection compliance.
- Capacitive Sensors:Ridge-and-valley electrical field detection dominates mid-tier smartphone volumes with mature, cost-optimized manufacturing.
- Optical Sensors:CMOS-based fingerprint imaging faces commoditization pressure from PIN fallback and wearable-based verification substitutes.
- Thermal Sensors:Subsurface blood flow detection provides auxiliary liveness signals in high-security government deployments.
Capacitive sensors maintain the installed base; ultrasound technology is climbing the fastest on under-display penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean and Chinese manufacturing clusters where captive semiconductor fabrication controls ultrasound sensor yields, while European banking terminal procurement absorbs premium margins under compliance-driven specifications.
United States
NIST FRVT certification requirements extend validation timelines for facial recognition vendors serving federal government contracting channels. The FDA and Department of Homeland Security coordinate biometric standards for healthcare and border applications. Silicon Valley and Austin semiconductor design clusters anchor neural processing unit development for edge-resident authentication.
Germany
Automotive OEMs in Baden-Württemberg integrate iris and facial recognition into premium electric vehicle cabin systems for driver personalization. The KBA and BSI enforce strict algorithmic bias auditing under EU AI Act conformity assessment procedures. Munich's industrial automation corridor demands ruggedized fingerprint modules for factory-floor access control systems.
China
Domestic OEMs in the Pearl River Delta embed capacitive fingerprint sensors at scale across mid-tier smartphone refresh cycles. NMPA and MIIT enforce separate certification pathways for facial recognition hardware through GB standards and dual carbon compliance frameworks. Shenzhen's sensor manufacturing ecosystem supplies cost-optimized modules for banking terminal exports across Southeast Asia.
India
RBI mandates and Aadhaar-linked financial inclusion programs drive demand for ruggedized fingerprint POS terminals in rural banking corridors. The BIS and CDSCO regulate biometric hardware for healthcare patient identity verification. Karnataka's Bangalore-Tumkur electronics manufacturing cluster assembles offline template-matching devices for last-mile distribution.
Japan
METI promotes behavioral biometrics convergence through keystroke dynamics integration into existing enterprise hardware substrates. The PMDA and JIS standards govern medical device authentication for hospital workflow streamlining. Tokyo-Osaka corridor semiconductor houses develop thermal sensor arrays for high-security government facility deployments.
Device-Embedded Biometric Authentication Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where captive silicon designers command premium positioning against foundry-dependent module suppliers. The market fragments across integrated system vendors, specialized sensor fabricators, and algorithm licensing houses. Three archetypes dominate: vertically integrated electronics conglomerates with in-house semiconductor fabrication, dedicated biometric sensor specialists serving Android OEM ecosystems, and diversified technology holding companies with security-focused subsidiaries. Competitive intensity centers on M&A activity consolidating algorithm portfolios and strategic partnerships securing foundry capacity for under-display ultrasound sensors.
Within the captive fabrication tier, Samsung Electronics exemplifies upstream control over ultrasound sensor yields and pricing architecture. Apple Inc. occupies a position representing proprietary ecosystem lock-in through vertical silicon design. Fingerprint Cards AB anchors the cost-optimized specialist segment, serving mid-tier Android OEM procurement patterns with capacitive module supply. These three entities represent the structural divergence between integrated and modular competitive strategies.
| Leading Market Players |
|---|
| Samsung Electronics |
| Apple Inc. |
| Qualcomm Incorporated |
| Huawei Technologies |
| NEC Corporation |
| Thales Group |
| HID Global |
| Fingerprint Cards AB |
| IDEMIA |
| Others |
Value Chain & Pricing Dynamics
Ultrasound sensor displacement of optical modules in under-display applications simultaneously concentrates procurement leverage in Taiwan-based foundries and compresses margins for fabless vendors unable to secure captive capacity. This substitution dynamic redistributes pricing power toward semiconductor fabricators while forcing module suppliers to absorb certification and secure-element integration costs.
Pricing Analysis
The customization-premium spread separates turnkey sensor-plus-algorithm packages from discrete component procurement across banking and consumer channels. Three-tier pricing structure across premium, standard, and economy levels reflects NIST FRVT certification grade, EU AI Act conformity status, and volume scale. Pricing pressure stems from optical sensor commoditization in mid-tier smartphones, where Android OEMs drive hard bargains on capacitive modules. Banking institutions show least price sensitivity, prioritizing liveness detection compliance over unit economics.
Supply Chain Analysis
Taiwan Strait shipping lanes and foundry concentration in Hsinchu Science Park anchor global ultrasound sensor supply, with South Korean and Chinese captive fabricators holding secondary positions. Piezoelectric transducer materials, CMOS image sensors, and secure-element silicon draw from specialized chemical and semiconductor feedstocks. Single-source vulnerability in Taiwan-based 12-inch wafer production exposes lead time volatility for under-display modules. Distribution runs through direct OEM contracting for premium tiers, with module aggregators serving mid-volume Android manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where unbundling of hardware from algorithm licensing fragments supplier power and rewards interoperability-focused entrants. The shift toward modular procurement in North American financial services exemplifies how enterprise buyers now swap biometric modalities without hardware refresh cycles.
For Market Incumbents: Consolidate algorithm portfolios through targeted acquisition of liveness-detection specialists to defend against independent software vendors displacing sensor suppliers. Secure foundry capacity commitments in Taiwan and South Korea to maintain yield control as ultrasound penetration accelerates. Lock in certification dual-tracking for EU AI Act and NIST FRVT pathways to preserve banking terminal access. For New Entrants and Emerging Players: Anchor in India's Aadhaar-linked rural banking corridor, where ruggedized offline fingerprint modules face limited incumbent saturation and government procurement favors cost-optimized domestic assembly. Target automotive cabin authentication as white-space territory, where iris and facial recognition integration with electric vehicle personalization systems remains underdeveloped. Pursue hospital system partnerships in China as the fastest certification pathway for NMPA-compliant facial recognition hardware. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors algorithm-software specialists over hardware-commoditized module vendors. Long-term viability hinges on edge-AI inference capabilities and multi-modal fusion IP rather than discrete sensor manufacturing. Watch for EU AI Act enforcement actions against cloud-dependent biometric architectures as the inflection signal triggering valuation repricing across vendor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Liveness-Detection Specialist | Consolidates algorithm IP essential for EU AI Act compliance in banking terminals. |
| Foundry Capacity Reservation Agreement | Secures Taiwan-based 12-inch wafer allocation for ultrasound sensor yield stability. |
| NMPA Certification Dual-Tracking | Unlocks Chinese healthcare facial recognition procurement through streamlined regulatory pathway. |
| Algorithm Licensing Unbundling | Captures enterprise buyer preference for modular biometric procurement in North American financial services. |
| Automotive Cabin Biometric Integration | Positions iris and facial recognition for premium electric vehicle personalization feature sets. |
Study Parameters
Operator-level perspectives from biometric sensor procurement directors, semiconductor foundry account managers, OEM platform engineers, and banking terminal compliance officers anchored the qualitative base. Primary interview data combined with secondary validation against SEC 10-K filings, EU AI Act implementation guidance, NIST FRVT test results, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up module shipment estimates triangulated against top-down OEM device production forecasts across the analysis window.
Sensitivity analysis tested ultrasound penetration rates, foundry yield assumptions, and regulatory compliance timeline scenarios throughout the forecast period. The analytical framework modeled segmentation across product type, end user, integration level, and technology, with additional dimensioning by regional regulatory cluster and certification tier. CAGRs derived from installed base replacement cycles, smartphone refresh patterns, and banking terminal upgrade mandates, with cross-checks against secure-element silicon demand forecasts and neural processing unit attach rates.
Material uncertainties — Taiwan foundry capacity constraints, EU AI Act enforcement variance, and algorithmic bias audit outcome unpredictability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and semiconductor supply continuity that practitioners should keep alternative scenarios live as geopolitical conditions and standard-setting body rulings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Data Classification Market
Security Software
Cloud Intrusion Protection Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Information Rights Management Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Global Anti-Spam Software Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
US Evidence Management Market
Security Software
Asia-Pacific Fraud Detection & Prevention Market
Security Software
SSL Inspection Solution Market
Security Software
Cloud Security Software Market
Security Software
Spain Endpoint Detection and Response Market
Security Software
Antivirus Software Package Market
Security Software
Vsaas Market
Security Software
Consumer Endpoint Security Market