
 Employee Surveillance and Monitoring Software Market | 2026-2036
Employee Surveillance and Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Surveillance and Monitoring Software Market Intelligence
Asset-light SaaS subscription models are rewriting competitive economics in employee surveillance software, lowering barriers for mid-market vendors to challenge incumbents. Hubstaff leverages freemium-to-enterprise conversion funnels to capture distributed teams. ActivTrak anchors its position through native behavioral analytics that reduce false-positive alerts. Teramind specializes in insider-threat detection for regulated environments, commanding premium pricing.
Employee surveillance and monitoring software encompasses cloud-based and on-premises platforms that capture screen activity, keystroke patterns, application usage, and network behavior through agent-based endpoint instrumentation, then aggregate telemetry into managerial dashboards for workforce oversight. Cloud-based deployment leads volume adoption due to zero-infrastructure provisioning, while on-premises solutions retain dominance in financial services and legal offices where data residency requirements override cost considerations. Activity tracking and screen recording form the mature revenue core, though behavioral analytics and risk management use cases are expanding fastest as AI inference costs decline.
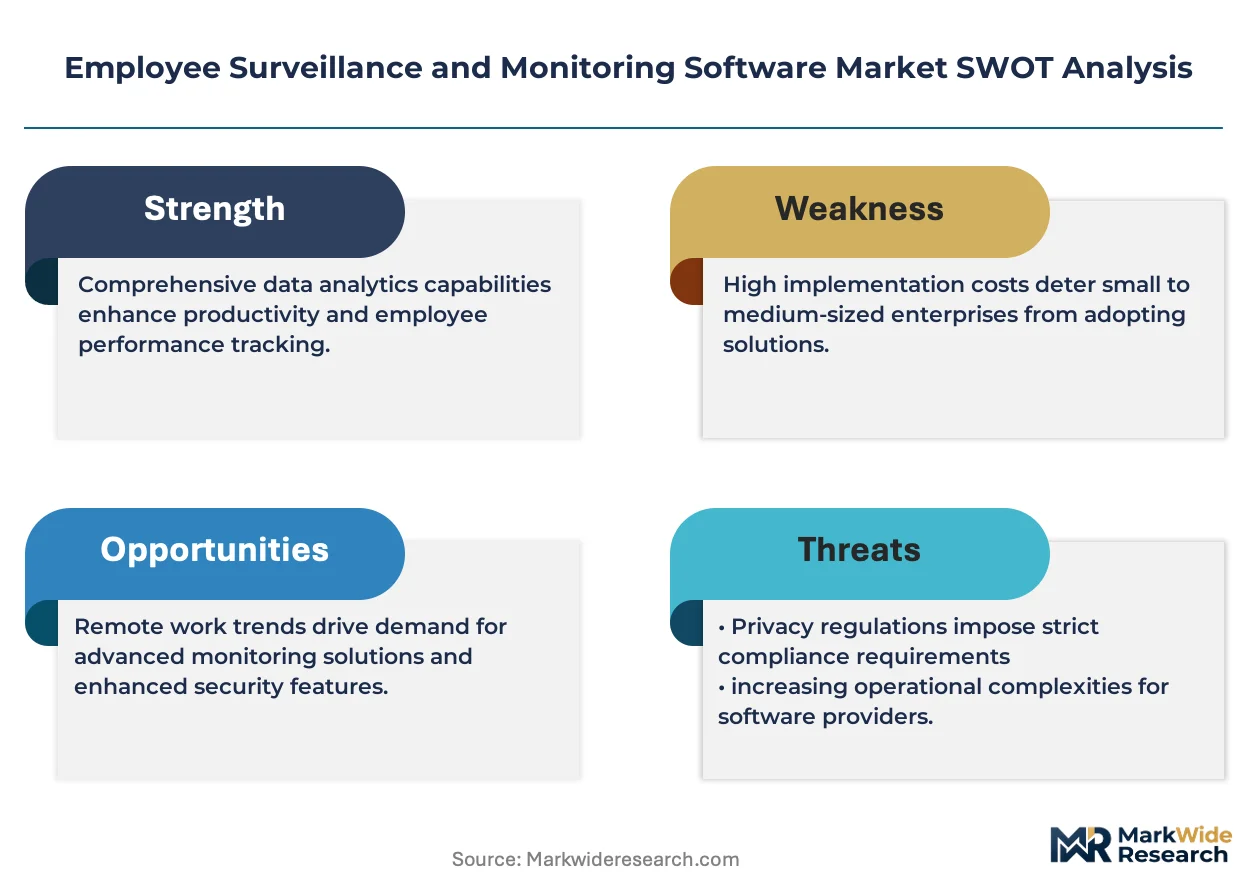
The EU AI Act classifies emotion-recognition workplace systems as high-risk, forcing vendors to document training data provenance and human oversight protocols before CE-marked deployment. The US lacks federal biometric privacy law, yet Illinois BIPA and emerging state statutes in California and Texas create a patchwork of consent requirements that fragment product roadmaps. Stakeholders must weigh regulatory divergence against standardization economics when allocating R&D between explainable monitoring algorithms and jurisdictional compliance modules.
Market Dynamics
Hybrid work normalization is forcing enterprises to rebuild managerial visibility through endpoint instrumentation rather than physical presence, compressing sales cycles for cloud-native platforms while exposing legacy on-premises architectures to displacement.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification of emotion-recognition systems creates documented procurement pathways for vendors with explainable algorithms and human oversight protocols, accelerating replacement of opaque legacy tools.
- Financial services compliance enforcement:Regulated institutions deploy activity tracking platforms to satisfy SEC and FINRA record-keeping requirements for remote trading floors and distributed advisory operations.
- Agentic AI integration:Autonomous reasoning engines embedded in monitoring dashboards reduce false-positive alert volumes by correlating behavioral telemetry across multiple data streams simultaneously.
Market Restraints
- GDPR Article 88 friction:Member-state variations in works-council consultation requirements create deployment delays and legal uncertainty for cross-border workforce monitoring implementations.
- Cloud infrastructure concentration:Dominance of AWS, Azure, and Google Cloud in SaaS hosting creates single-point-of-failure exposure and limits vendor negotiating leverage on compute pricing.
- Biometric consent patchwork:Illinois BIPA, California CCPA amendments, and emerging Texas statutes impose incompatible technical and procedural requirements that fragment product development roadmaps.
Strategic Opportunities
- India PLI scheme alignment:Domestic IT/ITES beneficiaries expanding global delivery centers require compliant monitoring infrastructure to satisfy client audit requirements in GDPR and HIPAA jurisdictions.
- Edge AI inference:On-device behavioral analysis without cloud data exfiltration addresses data residency constraints in Saudi Arabia, UAE, and other Middle Eastern financial centers.
- Outcome-based pricing models:Vendors tie subscription fees to measurable insider-threat incident reduction or compliance audit pass rates, expanding addressable market to risk-averse mid-market buyers.
Industry Challenges
- Algorithmic audit talent scarcity:Shortage of professionals capable of documenting training data provenance and bias testing for EU AI Act technical documentation delays CE-marked product launches.
- Legacy SIEM integration complexity:Enterprise security teams demand API-native telemetry feeds into existing Splunk, IBM QRadar, or Microsoft Sentinel deployments, requiring custom engineering for each incumbent environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Surveillance and Monitoring Software Market |
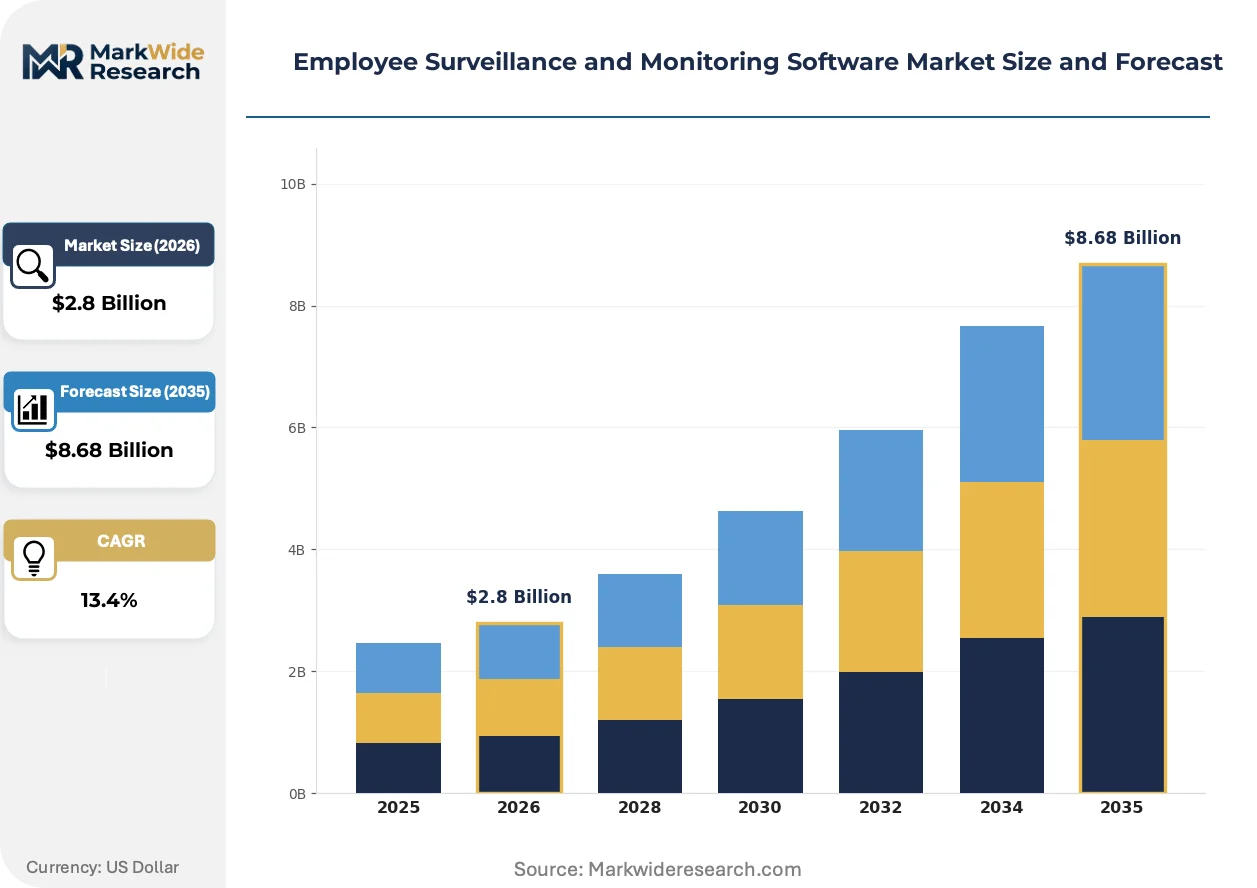
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.68 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Virtual Desktop Solution Type: Activity Tracking, Screen Recording, Keystroke Logging, Email Monitoring, Web Filtering Use Case: Productivity Analysis, Risk Management, Compliance Enforcement, Fraud Detection, Behavioral Analytics End User: IT Firms, Financial Services, Legal Offices, Manufacturing Plants, Education Institutions |
| Companies Covered | Hubstaff, WorkTime, WorkTrack, WebWork Time Tracker, Time Doctor, ActivTrak, Insightful, Kickidler, Teramind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Surveillance and Monitoring Software Market Strategic Shifts & Innovations
Behavioral inference engines are compressing the latency between data capture and managerial action, collapsing the traditional separation between monitoring infrastructure and workforce optimization software.
Containerized endpoint agents are virtualizing deployment topology for employee surveillance platforms. Large enterprises with distributed DevOps teams adopt Kubernetes-orchestrated monitoring daemons that auto-scale across hybrid cloud and on-premises footprints. This architecture is virtualizing the boundary between cloud-native and legacy infrastructure, enabling unified telemetry pipelines without forklift upgrades.
EU AI Act high-risk system obligations are mandating algorithmic transparency documentation before CE-marked deployment. Vendors must maintain version-controlled records of training data sources, model performance benchmarks, and human oversight protocols. Financial services and legal sector buyers in Germany, France, and Netherlands now require this documentation as standard procurement criteria, filtering out undercapitalized competitors.
Buyer committees are consolidating vendor selection authority into centralized procurement functions with dedicated privacy legal review. Distributed IT managers lose autonomous purchasing power as CISO and DPO sign-off becomes mandatory. This pattern concentrates contract values with fewer suppliers and extends sales cycles, with the shift most visible in US healthcare and European manufacturing verticals.
Employee Surveillance and Monitoring Software Market Segmentation
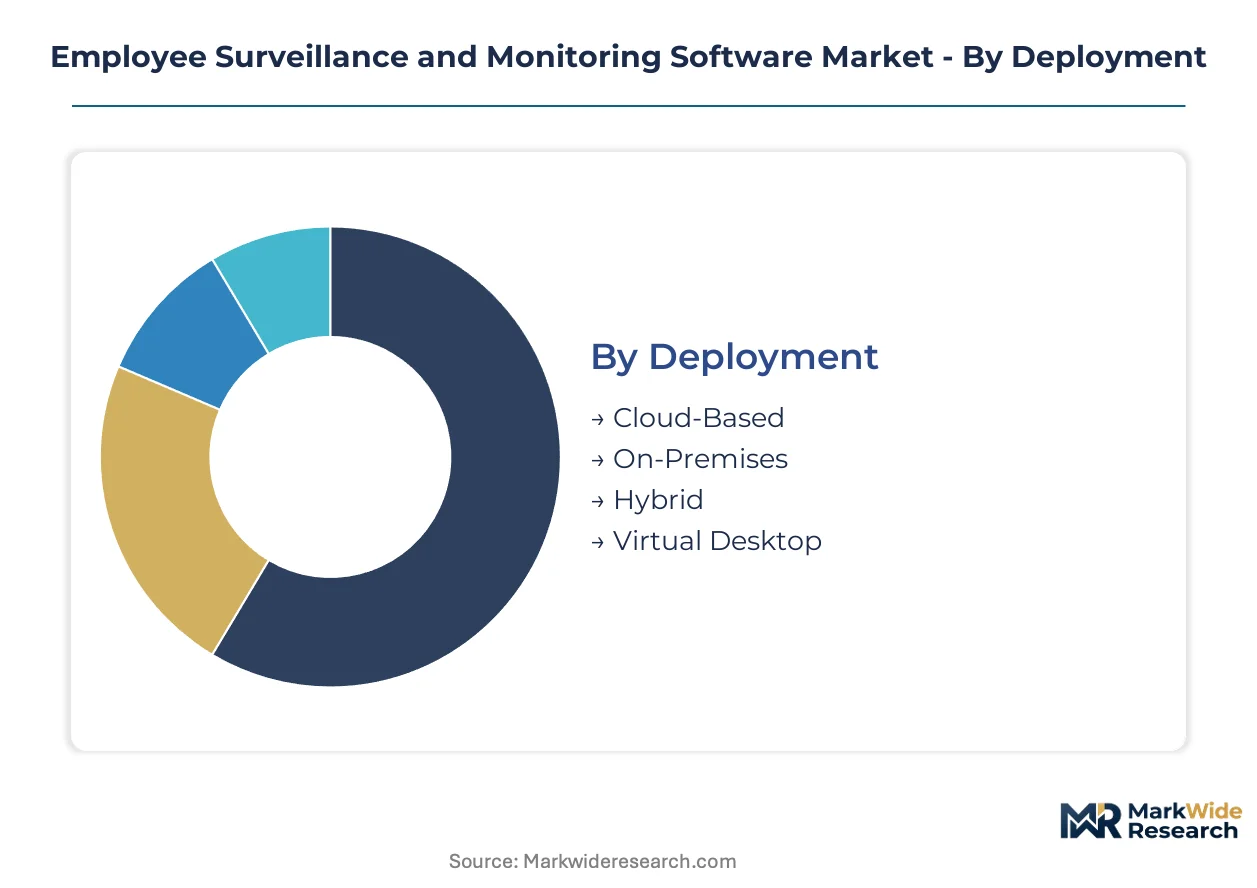
Segmentation in employee surveillance software reveals how deployment architecture, functional depth, and regulatory exposure shape vendor positioning and buyer procurement criteria. Understanding these dimensions clarifies why cloud-native platforms capture mid-market volume while on-premises solutions retain premium pricing in regulated verticals.
Deployment:
The use-case spectrum spans zero-infrastructure provisioning for distributed teams to air-gapped environments where data residency overrides operational convenience.
- Cloud-Based:SaaS delivery eliminates server procurement and reduces time-to-deployment to hours rather than weeks. Demand concentrates among US technology firms and professional services with dispersed workforces, driven by hybrid work policies that require immediate endpoint visibility without capital expenditure.
- On-Premises:Local server installation captures all telemetry within organizational firewalls, satisfying GDPR Article 44 data-localization requirements and HIPAA technical safeguards. Financial services firms in Frankfurt, London, and Zurich deploy these configurations to satisfy national banking regulators' audit requirements for trading floor surveillance.
- Hybrid:Split architectures process sensitive behavioral data locally while pushing aggregated analytics to cloud dashboards. Manufacturing plants with OT/IT convergence requirements favor this model to isolate production system telemetry from internet-facing infrastructure.
- Virtual Desktop:Agent deployment within VDI environments captures activity in centralized compute pools rather than distributed endpoints. Healthcare systems with thin-client clinical workstations use this approach to satisfy HIPAA access controls while enabling remote specialist consultations.
Established volume favors Cloud-Based; emerging adoption favors Hybrid as manufacturing and critical infrastructure buyers seek middle-ground architectures.
Solution Type:
Functional modules range from passive observation to active intervention, with pricing tiers reflecting inference sophistication rather than data capture volume alone.
- Activity Tracking:Application and URL logging forms the baseline capability, recording which software employees launch and how long sessions persist. Mid-market IT services firms in India deploy this module to satisfy client audit requirements for time-and-materials billing verification.
- Screen Recording:Continuous or triggered video capture of desktop activity provides evidentiary archives for dispute resolution and quality assurance. US insurance claims processors and legal discovery services mandate this capability for FINRA and state bar compliance documentation.
- Keystroke Logging:Character-level input capture enables forensic reconstruction of data entry sequences and unauthorized command execution. Demand clusters in financial services fraud investigation units where pattern analysis identifies insider trading precursor behaviors.
- Email Monitoring:Content inspection of internal and external communications flags policy violations, data exfiltration attempts, and harassment indicators. European multinationals deploy this module with GDPR Article 88 works-council consultation to satisfy CSRD whistleblower protection mandates.
- Web Filtering:Real-time traffic classification blocks malicious domains and productivity-draining categories at the network perimeter. Education institutions across Texas and California deploy this to satisfy CIPA compliance for E-rate funding eligibility.
Mature revenue concentrates in Activity Tracking; steepest expansion trajectory belongs to Screen Recording as remote work sustains demand for visual audit trails.
Use Case:
Application purpose determines algorithmic architecture, with predictive inference commanding premium pricing over retrospective reporting.
- Productivity Analysis:Time-allocation dashboards and focus-scoring algorithms translate telemetry into workforce optimization recommendations. Business process outsourcing firms in the Philippines and Poland deploy these tools to demonstrate operational efficiency to US and European clients.
- Risk Management:Behavioral baselining and anomaly detection identify insider threats before material damage occurs. US defense contractors and cleared facilities mandate this capability for CMMC 2.0 compliance, driving FedRAMP-authorized procurement pathways.
- Compliance Enforcement:Automated policy violation detection and audit trail generation satisfy sector-specific record-keeping mandates. Broker-dealers in New York and Chicago deploy this for SEC Rule 17a-4 electronic communications retention.
- Fraud Detection:Pattern recognition across multiple data streams identifies collusion, data theft, and financial manipulation precursor behaviors. Payment processors and cryptocurrency exchanges in Singapore and Estonia prioritize this capability for MAS and FI regulatory examinations.
- Behavioral Analytics:AI inference on aggregated telemetry predicts burnout, flight risk, and engagement degradation. Large enterprises with European works councils face GDPR Article 22 restrictions on automated decision-making, slowing deployment relative to US counterparts.
Current procurement concentrates in Compliance Enforcement; gaining share fastest is Behavioral Analytics as AI inference costs decline and HR technology budgets converge with security spending.
End User:
Vertical-specific regulatory exposure and workforce distribution patterns create distinct functional requirements and sales cycle lengths.
- IT Firms:Software development and technical consulting organizations prioritize integration with existing DevOps toolchains and agile project management platforms. These buyers favor API-native solutions that feed telemetry into Jira, Azure DevOps, and GitHub rather than standalone dashboards.
- Financial Services:Banks, broker-dealers, and asset managers face overlapping SEC, FINRA, and PCI-DSS mandates that prescribe specific retention periods and access controls. Vendors serving this vertical must maintain SOC 2 Type II and ISO 27001 certifications as table stakes.
- Legal Offices:Law firms and corporate legal departments require privileged communication protections and client confidentiality safeguards that limit monitoring scope. ABA Model Rule 1.6 compliance necessitates granular policy configuration capabilities absent in generic platforms.
- Manufacturing Plants:Industrial environments with shift-based production schedules prioritize attendance verification and safety compliance over productivity optimization. Integration with access control and SCADA systems distinguishes suitable vendors from office-centric alternatives.
- Education Institutions:K-12 districts and universities balance student safety monitoring against FERPA privacy protections and First Amendment considerations. CIPA compliance for E-rate funding drives web filtering procurement, while higher education research environments face IRB restrictions on human subjects surveillance.
Contract value concentrates in Financial Services; shortest sales cycles appear in IT Firms with pre-existing remote work infrastructure and limited procurement committee complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement committees concentrate authority in the United States, Germany, and India as hybrid work policies and compliance mandates reshape surveillance software demand. Financial services, IT services, and defense contractors drive contract values across these markets.
United States
Defense contractors and cleared facilities mandate FedRAMP-authorized monitoring platforms for CMMC 2.0 compliance, compressing vendor qualification timelines. SEC Rule 17a-4 enforcement drives broker-dealer adoption in New York and Chicago trading floors. Silicon Valley technology firms deploy cloud-native solutions for distributed engineering teams.
Germany
Works-council consultation requirements under GDPR Article 88 create deployment friction that favors vendors with documented human oversight protocols. Frankfurt banking regulators prescribe on-premises architectures for trading surveillance. Industrial manufacturers in Bavaria adopt hybrid deployments to isolate production telemetry from cloud infrastructure.
India
IT/ITES beneficiaries of the PLI scheme require compliant monitoring infrastructure to satisfy client audit requirements in GDPR and HIPAA jurisdictions. Business process outsourcing firms in Bangalore and Hyderabad deploy productivity analytics for US and European client demonstrations. Domestic software vendors compete on price against established SaaS platforms.
United Kingdom
Financial Conduct Authority record-keeping mandates accelerate replacement of legacy surveillance systems in the City of London. Legal sector buyers require granular policy configuration for ABA Model Rule 1.6 compliance. Manchester and Edinburgh technology clusters favor API-native solutions that integrate with existing DevOps toolchains.
Singapore
Monetary Authority of Singapore examinations drive payment processors and cryptocurrency exchanges toward behavioral analytics for fraud detection. Regional headquarters of multinational banks deploy compliant infrastructure to satisfy overlapping home-country and host-country requirements. Marina Bay financial district concentrates procurement authority for Southeast Asia operations.
Employee Surveillance and Monitoring Software Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered pricing bands. The market structure consolidates around three archetypes: freemium-to-enterprise converters, compliance-specialist vendors, and API-native platform providers. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into adjacent workforce optimization software.
Within the compliance-specialist tier, Teramind exemplifies premium positioning for regulated environments. Hubstaff and ActivTrak occupy positions across the freemium-to-enterprise conversion spectrum. These three anchors represent distinct strategic archetypes: insider-threat specialization, distributed team capture, and native behavioral analytics respectively.
| Leading Market Players |
|---|
| Hubstaff |
| WorkTime |
| WorkTrack |
| WebWork Time Tracker |
| Time Doctor |
| ActivTrak |
| Insightful |
| Kickidler |
| Teramind |
| Others |
Cost & Logistics Intelligence
Single-source dependency on AWS, Azure, and Google Cloud for SaaS hosting infrastructure determines both pricing tier spreads and supply chain shape, compressing vendor margins while concentrating procurement leverage among hyperscaler partners. Cloud infrastructure concentration forces mid-market vendors into cost-plus arrangements indexed to compute pricing indices, widening the gap between freemium entry points and enterprise premium tiers.
Pricing Analysis
Cost-plus contracts with hyperscaler indexation dominate SaaS delivery, tying subscription fees to underlying compute and storage unit economics. Pricing stratifies across FedRAMP-authorized premium tiers, SOC 2 Type II mid-market bands, and unstandardized economy offerings for small business buyers. Cost compression in the economy tier is intensifying because freemium conversion funnels subsidize user acquisition without guaranteed monetization. Financial services buyers demonstrate least price sensitivity due to compliance mandates, while education institutions and small IT services firms exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from enterprise buyers and supply-chain finance facilities anchor vendor working capital requirements, stretching cash conversion cycles for growth-stage competitors. Development talent concentrates in the United States, India, and Poland, while data center infrastructure draws from Ireland, Singapore, and Virginia. Single-source vulnerability to hyperscaler API changes and egress pricing revisions threatens margin stability. Distribution runs through direct enterprise sales teams, cloud marketplace listings, and value-added reseller networks serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security services and compliance documentation subscriptions expand faster than base platform licensing, transforming vendor economics toward recurring-revenue depth. Service-attach layers including EU AI Act technical documentation, algorithmic audit support, and insider-threat response retainers capture premium pricing beyond software subscriptions.
For Market Incumbents: Harden FedRAMP authorization portfolios against emerging CMMC 2.0 requirements, locking out unqualified competitors from defense contractor procurement pathways. Consolidate channel control through exclusive partnerships with hyperscaler marketplaces, capturing procurement flows from centralized IT governance functions. Vertical integration into on-device inference hardware addresses data residency constraints in Middle Eastern financial centers. For New Entrants and Emerging Players: Build out edge-AI behavioral analysis capabilities for manufacturing OT/IT convergence requirements, where incumbent platforms lack industrial protocol support. Target mid-market IT services firms in India requiring GDPR-compliant infrastructure for European client delivery, a segment underserved by premium-priced compliance specialists. Pursue API-native positioning that feeds telemetry directly into existing Splunk, IBM QRadar, or Microsoft Sentinel deployments. For Investors and Strategic Acquirers: Algorithmic audit boutiques with documented EU AI Act technical documentation capabilities represent the most defensible acquisition profile, given talent scarcity delays for CE-marked product launches. Long-term viability hinges on convergence between workforce optimization and security operations center spending, with behavioral analytics vendors capturing budget consolidation. Watch for insider-threat incident frequency acceleration in cleared facilities as the inflection indicator for premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Splunk, IBM QRadar, and Microsoft Sentinel API feeds satisfy enterprise security team procurement requirements. |
| Strategic Partnership | Hyperscaler marketplace exclusivity captures centralized IT governance procurement flows in US healthcare verticals. |
| Acquisition of Specialist Firm | Algorithmic audit boutiques with EU AI Act documentation capabilities accelerate CE-marked product launches. |
| Geographic Expansion | Edge-AI inference deployment in Saudi Arabia and UAE addresses data residency constraints for financial centers. |
| Product Launch | Outcome-based pricing tied to insider-threat incident reduction expands addressable market to risk-averse mid-market buyers. |
Research Approach
The analysis maps cloud-native deployment, on-premises configuration, hybrid architecture, and virtual desktop infrastructure segments, each validated through CISO interviews, DPO consultations, IT procurement officers, and channel partner discussions. Primary fieldwork combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, EU regulatory documentation, and healthcare GPO contract databases. Bottom-up telemetry platform deployment counts triangulate against top-down enterprise software spending estimates.
Assumptions around hybrid work policy persistence, EU AI Act enforcement timelines, and cloud infrastructure pricing trajectories were held fixed across modeling scenarios while varying regulatory divergence intensity and AI inference cost decline curves. Segmentation dimensions include deployment architecture, solution functional depth, use-case purpose, and vertical regulatory exposure. CAGRs were derived from installed base expansion rates and annual contract value growth patterns across the projection horizon, incorporating FedRAMP authorization pipeline visibility and works-council consultation friction indices.
Stress conditions across hyperscaler pricing volatility, GDPR Article 88 enforcement variance, and CMMC 2.0 rollout timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding compliance mandate adoption curves. Macroeconomic contraction in IT services outsourcing, regulatory fragmentation exceeding baseline scenarios, or breakthrough edge-AI cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Europe Enterprise Firewall Market
Security Software
Web Content Filtering Market
Security Software
Global Electronic Passports Market
Security Software
Website Monitoring Software Market
Security Software
Source Code Escrow Market
Security Software
Global SMS Firewall Market
Security Software
Global Advanced Authentication Market
Security Software
Global Digital Identity Solutions Market
Security Software
VPN Software Market
Security Software
Spam Blocking Software Market
Security Software
Cloud File Security Software Market
Security Software
Antivirus Software Market
Security Software
Secure Flash Drive Market
Security Software
Global Data Masking Market
Security Software
Extended Detection and Response Market
Security Software
Information Rights Management Market