
 Global Knowledge Process Outsourcing Market | 2026-2036
Global Knowledge Process Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Knowledge Process Outsourcing Market Foresight
India's KPO delivery infrastructure is expanding across tier-1 and tier-2 cities, deepening the talent pool for specialized analytics and legal services. WNS leverages domain-specific training academies to sustain margin quality in insurance and healthcare verticals. IBM anchors enterprise-scale engagements through its hybrid cloud delivery architecture. Accenture competes by embedding generative AI tools directly into client workflows, reducing manual research cycles.
Knowledge Process Outsourcing denotes the delegation of information-intensive business activities requiring advanced analytical and technical expertise, typically executed through secure digital workflows with SLA-governed turnaround parameters. Its primary commercial purpose centers on enabling client organizations to access specialized skills without maintaining permanent expert headcount. Research & Analytics services occupy the largest revenue share due to persistent demand from pharmaceutical sponsors for clinical trial data interpretation. Legal Process Outsourcing is accelerating fastest as law firms and corporates disaggregate document review and contract analytics to specialized providers. Cloud-based delivery models are capturing margin pools previously held by onsite arrangements, driven by security certification maturation and real-time collaboration tooling.
FDA oversight of clinical data integrity shapes pharmaceutical KPO demand, requiring providers to maintain 21 CFR Part 11 compliant systems and audit trails. EMA's evolving pharmacovigilance reporting standards and India's CDSCO alignment with ICH guidelines create compliance complexity that specialized KPO vendors convert into contracted service scope. GDPR constraints on cross-border data transfers force European-facing providers to architect region-specific processing environments. Stakeholders must monitor regulatory divergence between FDA, EMA, and emerging market agencies as a determinant of delivery center location strategy and certification investment.
Market Dynamics
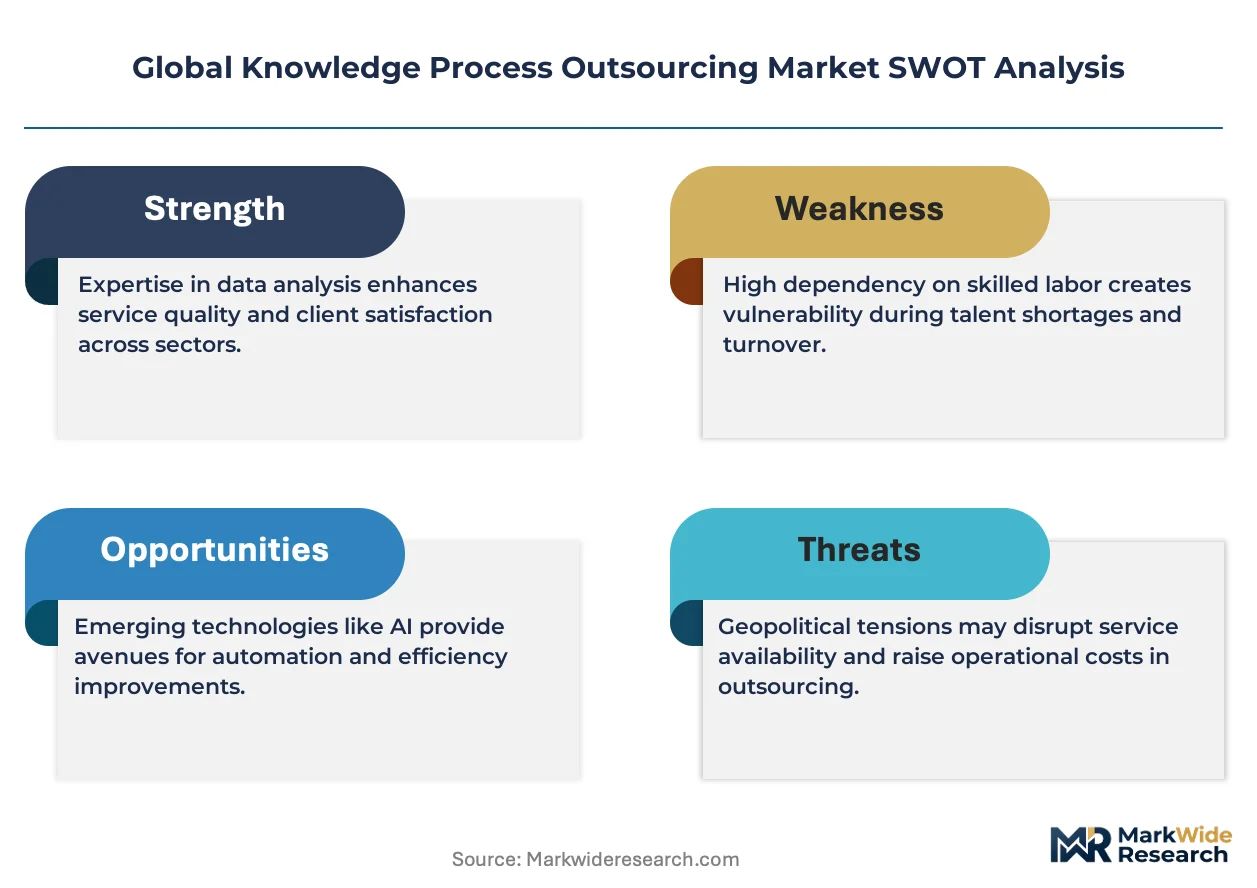
Generative AI deployment is compressing research cycle times and forcing KPO providers to reconfigure talent models around human-AI collaboration rather than pure labor arbitrage.
Growth Catalysts
- 21 CFR Part 11 Compliance:FDA mandates for electronic records and audit trails in clinical trials drive pharmaceutical sponsors toward specialized KPO vendors with validated quality management systems.
- Legal Process Outsourcing:Law firms in the United States and United Kingdom disaggregate document review, e-discovery, and contract analytics to access scalable expertise without permanent headcount.
- Cloud-Native Delivery:ISO 27001 and SOC 2 Type II certified platforms enable real-time collaboration across Bengaluru, Hyderabad, and Pune delivery centers serving North American and European clients.
Market Restraints
- Data Localization Mandates:GDPR constraints on cross-border transfers and Russia's data sovereignty laws force providers to maintain redundant infrastructure across jurisdictions, elevating fixed costs.
- Talent Concentration Risk:Deep expertise in pharmacovigilance, biostatistics, and patent law clusters in Mumbai, Delhi-NCR, and Chennai, creating wage inflation and attrition vulnerability.
- Automation Substitution:Large language models trained on legal corpora and medical literature threaten commoditization of entry-level research and document coding tasks.
Strategic Opportunities
- EU AI Act Alignment:European risk-based classification of AI systems in healthcare and legal applications creates demand for KPO providers offering compliance documentation and algorithmic auditing services.
- Environmental Data Analytics:Corporate sustainability reporting under CSRD and SEC climate disclosure rules opens new service lines in carbon accounting, supply chain traceability, and ESG data verification.
- Japan's Digital Transformation:METI's push for cloud-first government and enterprise operations generates demand for bilingual KPO services bridging Japanese regulatory complexity and offshore delivery scale.
Industry Challenges
- Domain-Specific Talent Scarcity:Shortage of professionals combining life sciences PhDs with regulatory affairs certification limits expansion in clinical data management and pharmacovigilance verticals.
- Client-Side Integration Complexity:Enterprise buyers demand API-based workflow embedding that requires KPO providers to maintain engineering teams capable of custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Knowledge Process Outsourcing Market |
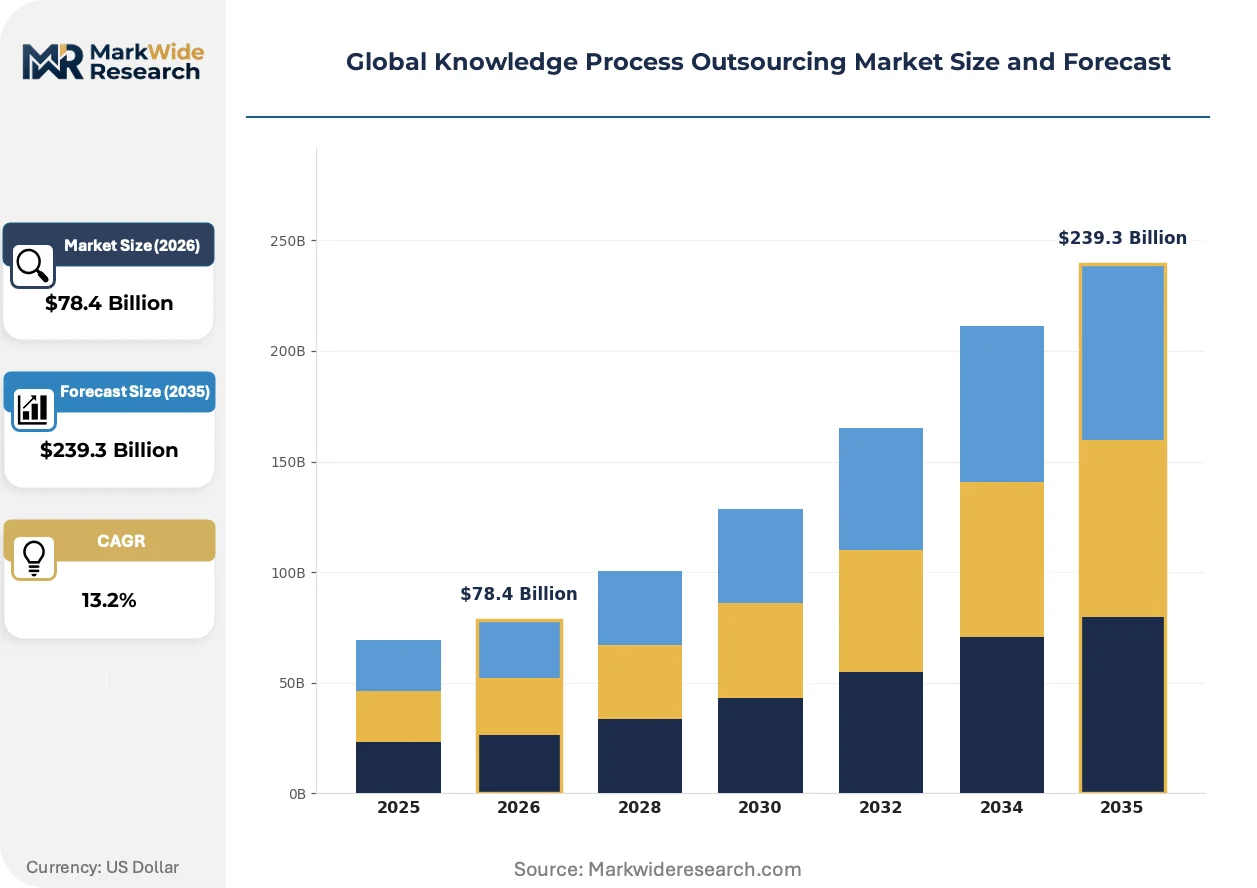
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $239.3 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Research & Analytics, Data Management, Content Development, Legal Process Outsourcing, Engineering Services, Market Intelligence Delivery Model: Onsite, Offshore, Nearshore, Hybrid, Cloud-based, Virtual End User Industry: Pharmaceutical, Telecom, Banking, Insurance, Manufacturing, Consumer Electronics Client Type: Startups, Small & Medium Enterprises, Large Enterprises, Government Agencies, Non-Profit Organizations, Educational Institutions |
| Companies Covered | WNS, Magellan Solutions, International Business Machines (IBM), Boston Analytics, Corpshore Solutions, Accenture, Cognizant, Eminenture, EXL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Knowledge Process Outsourcing Market Shifts & Advancements
Intelligent automation is unifying fragmented research workflows while regulatory complexity and buyer procurement sophistication are reshaping how specialized knowledge services are contracted and delivered.
Agentic AI systems orchestrating multi-step research tasks are unifying previously siloed data extraction, synthesis, and visualization capabilities. Pharmaceutical sponsors and private equity firms deploying these tools compress due diligence and competitive intelligence timelines from weeks to days. This unification is enabling KPO providers to shift pricing models from hourly rates to outcome-based engagement structures tied to deliverable quality.
EMA's strengthened pharmacovigilance reporting requirements under the EU Good Pharmacovigilance Practices mandate granular adverse event tracking across multi-country trials. KPO vendors serving European pharmaceutical sponsors must maintain validated case processing infrastructure capable of E2B(R3) electronic transmission standards. Contract scope is expanding to include signal detection and risk management plan authoring previously retained in-house.
Enterprise procurement functions now segment knowledge services by criticality tier rather than treating KPO as a monolithic cost center. Strategic categories involving regulatory submission support and IP litigation support command relationship-based vendor selection with multi-year frameworks. Tactical research and data processing engage competitive bidding through digital sourcing platforms, compressing vendor selection cycles and elevating price transparency.
Global Knowledge Process Outsourcing Market Segmentation
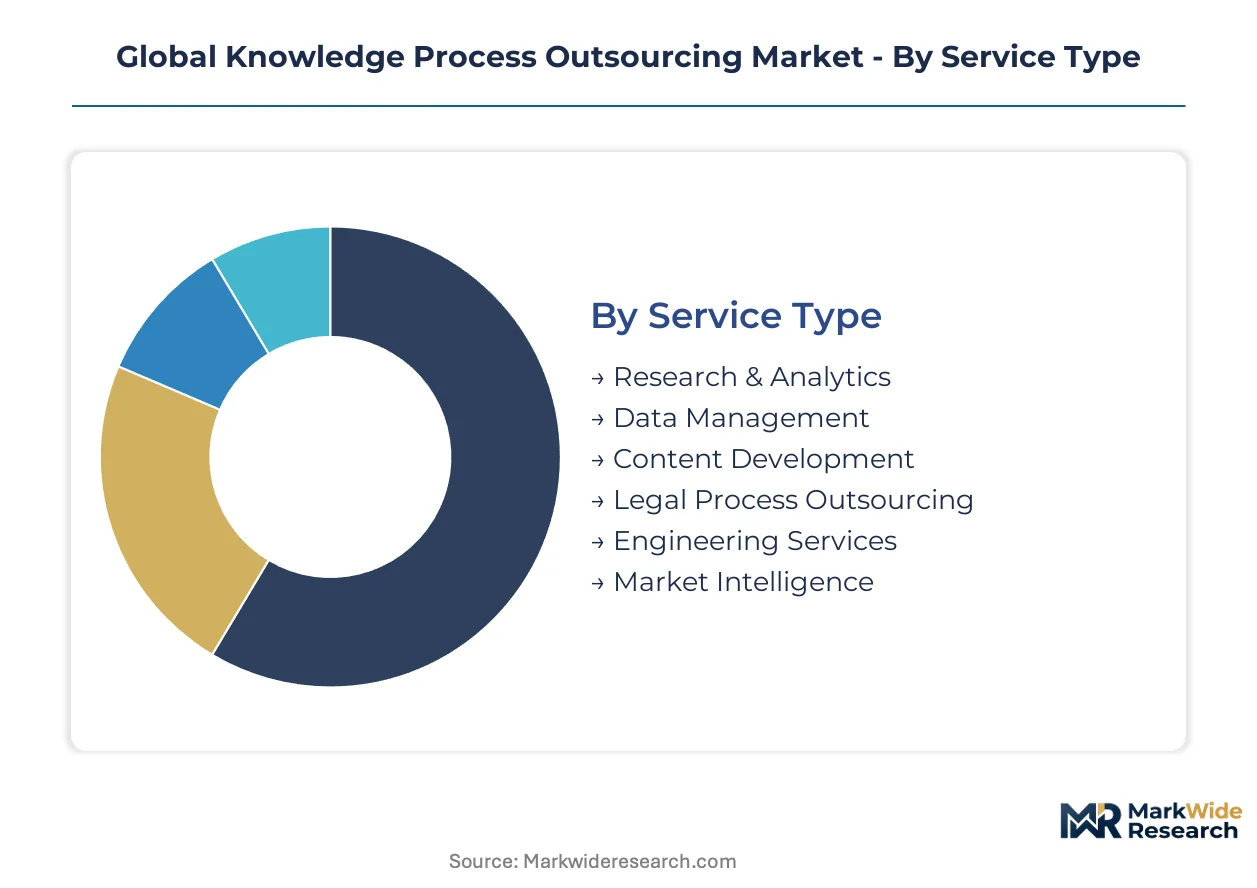
Knowledge Process Outsourcing providers configure service portfolios around integration depth, from standalone research deliverables to embedded workflow components. Segmentation reveals how delivery architecture and client scale reshape contract structures and margin capture across the value chain.
Service Type:
Standalone analytical services operate through discrete project engagements, while embedded knowledge layers integrate directly into client operational systems through API connections and continuous data feeds.
- Research & Analytics:Quantitative and qualitative investigation services spanning competitive intelligence, financial modeling, and primary fieldwork. Pharmaceutical sponsors in the United States and Germany drive contract volume for clinical trial data interpretation and regulatory submission support. FDA 21 CFR Part 11 compliance requirements elevate provider certification thresholds and extend contract duration.
- Legal Process Outsourcing:Document review, e-discovery processing, and contract analytics delivered through secure digital environments. United Kingdom and United States law firms disaggregate due diligence and litigation support to access scalable expertise without permanent headcount expansion. E-discovery platforms with predictive coding capabilities compress review timelines from months to weeks.
- Data Management:Structured and unstructured data processing, cleansing, and governance services.
- Content Development:Technical documentation, regulatory submission writing, and knowledge base creation.
- Engineering Services:CAD modeling, simulation analysis, and product design support.
- Market Intelligence:Sector monitoring, competitor tracking, and opportunity assessment.
Volume placements concentrate in Research & Analytics; the faster expansion belongs to Legal Process Outsourcing.
Delivery Model:
Cost tier stratification separates premium-certified engagements from standard delivery, with security certification and real-time collaboration tooling commanding 40-60 percent pricing premiums over baseline arrangements.
- Cloud-based:ISO 27001 and SOC 2 Type II certified platforms enabling real-time collaboration across distributed delivery centers. Bengaluru, Hyderabad, and Pune clusters serve North American and European clients through redundant infrastructure with sub-50 millisecond latency guarantees. GDPR-compliant data residency options force architectural investment in region-specific processing environments.
- Hybrid:Blended onsite-offshore teams combining domain proximity with cost-optimized execution. Large pharmaceutical sponsors in Switzerland and Japan retain clinical data scientists locally while delegating processing tasks to Indian delivery centers. This model captures margin pools previously held by pure onsite arrangements.
- Onsite:Embedded personnel operating from client premises with direct system access.
- Offshore:Dedicated delivery centers in lower-cost jurisdictions with standardized process frameworks.
- Nearshore:Proximity-based delivery within 3-4 time zones of client headquarters.
- Virtual:Fully distributed talent models without physical delivery center infrastructure.
Enterprise procurement is shifting toward Cloud-based and Hybrid models; Nearshore arrangements gain share fastest in European regulatory-intensive verticals.
End User Industry:
Application-specific compliance requirements segment demand, with life sciences and financial services imposing the most stringent validation and audit trail standards on provider operations.
- Pharmaceutical:Clinical data management, pharmacovigilance case processing, and regulatory submission support. EMA Good Pharmacovigilance Practices mandate granular adverse event tracking across multi-country trials, expanding contract scope to signal detection and risk management plan authoring. Indian CDSCO alignment with ICH guidelines creates compliance complexity that specialized vendors convert into contracted service scope.
- Insurance:Claims analytics, actuarial modeling, and policy administration support. WNS and similar providers maintain domain-specific training academies to sustain margin quality in this vertical. Underwriting automation is compressing turnaround times for risk assessment deliverables.
- Banking:Risk analytics, compliance monitoring, and customer due diligence.
- Telecom:Network optimization analytics and customer churn modeling.
- Manufacturing:Supply chain analytics and quality management system support.
- Consumer Electronics:Competitive benchmarking and pricing intelligence.
Contract value concentrates in Pharmaceutical; Insurance is climbing the fastest as carriers accelerate KPO adoption for actuarial and claims functions.
Client Type:
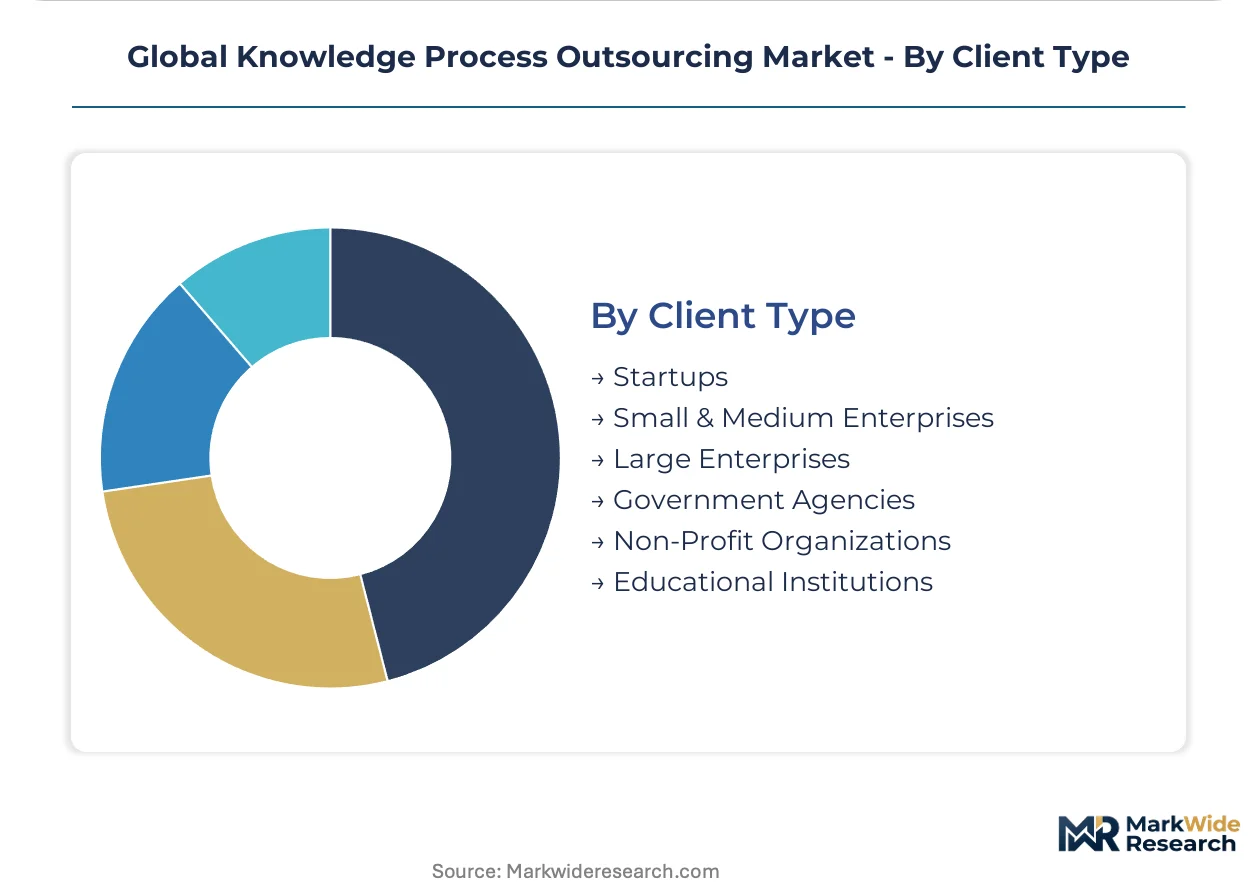
Customer scale determines engagement structure, with enterprise buyers demanding outcome-based pricing and API-based workflow embedding while smaller clients accept standardized service catalogs.
- Large Enterprises:Multi-year framework agreements with dedicated delivery teams and custom SLA architectures. Procurement functions segment knowledge services by criticality tier, with regulatory submission support commanding relationship-based vendor selection. API-based workflow embedding requires providers to maintain engineering teams capable of custom middleware development.
- Small & Medium Enterprises:Subscription-based access to standardized research platforms and on-demand expert networks. Digital sourcing platforms compress vendor selection cycles and elevate price transparency for tactical research categories. CSRD and SEC climate disclosure rules are opening new service lines in carbon accounting and ESG data verification.
- Startups:Flexible engagement models with minimal commitment thresholds.
- Government Agencies:Public procurement frameworks with stringent security clearance requirements.
- Non-Profit Organizations:Grant-funded research support with restricted overhead allowances.
- Educational Institutions:Bibliometric analysis and research administration services.
Revenue concentration sits with Large Enterprises; Small & Medium Enterprises represent the steepest expansion trajectory as self-service platforms democratize access to specialized analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's specialized talent clusters anchor the geography, with Bengaluru, Hyderabad, and Pune delivery centers processing clinical data and legal documents for pharmaceutical sponsors and law firms across North America and Europe.
United States
FDA 21 CFR Part 11 compliance mandates drive pharmaceutical sponsors toward specialized KPO vendors with validated quality management systems. The SEC's climate disclosure rules and evolving ESG reporting requirements open new service lines in carbon accounting and supply chain traceability. New Jersey and Massachusetts clusters concentrate clinical data management operations serving East Coast pharmaceutical headquarters.
Germany
EMA Good Pharmacovigilance Practices mandate granular adverse event tracking across multi-country trials, expanding contract scope to signal detection and risk management plan authoring. The EU AI Act's risk-based classification of AI systems in healthcare creates demand for compliance documentation and algorithmic auditing services. Frankfurt and Munich delivery centers serve continental pharmaceutical sponsors under strict GDPR data residency requirements.
United Kingdom
Law firms in London and regional commercial centers disaggregate document review, e-discovery, and contract analytics to access scalable expertise without permanent headcount expansion. The Solicitors Regulation Authority's evolving guidance on outsourcing legal work shapes provider selection criteria and audit protocols. E-discovery platforms with predictive coding capabilities compress review timelines from months to weeks.
Japan
METI's push for cloud-first government and enterprise operations generates demand for bilingual KPO services bridging Japanese regulatory complexity and offshore delivery scale. PMDA's alignment with ICH guidelines creates compliance complexity that specialized vendors convert into contracted service scope. Tokyo and Osaka clusters concentrate pharmaceutical regulatory affairs expertise serving domestic sponsors expanding into global markets.
Switzerland
Swissmedic's stringent oversight of clinical trial data integrity shapes pharmaceutical KPO demand, requiring providers to maintain validated quality management systems and audit trails. Large pharmaceutical sponsors in Basel and Zurich retain clinical data scientists locally while delegating processing tasks to Indian delivery centers. This hybrid model captures margin pools previously held by pure onsite arrangements.
Global Knowledge Process Outsourcing Market Competitive Landscape
Global majors compete with regional champions across certification depth and domain specialization, creating a tiered structure where scale-driven platforms, boutique specialists, and hybrid cloud integrators occupy distinct competitive positions. The vendor base clusters around three strategic archetypes: enterprise-scale consultancies with embedded AI tooling, India-centric delivery specialists with vertical academies, and technology-forward platforms with API-native architectures. Dominant competitive moves include M&A to acquire regulatory expertise and geographic expansion into tier-2 Indian cities to escape wage inflation.
Within the enterprise-scale tier, Accenture and IBM exemplify platform breadth, while WNS anchors the India-centric specialist position. Accenture's generative AI deployment compresses research cycle times for pharmaceutical and legal clients. IBM's hybrid cloud delivery architecture supports enterprise-scale engagements requiring validated infrastructure. WNS sustains margin quality in insurance and healthcare verticals through domain-specific training academies in Mumbai and Pune.
| Leading Market Players |
|---|
| WNS |
| Magellan Solutions |
| International Business Machines (IBM) |
| Boston Analytics |
| Corpshore Solutions |
| Accenture |
| Cognizant |
| Eminenture |
| EXL |
| Others |
Supply & Pricing Matrix
Enterprise procurement teams now mandate API-based workflow embedding and real-time collaboration tooling, forcing KPO providers to engineer custom middleware and maintain redundant certified infrastructure across jurisdictions. This specification creep elevates fixed cost bases and compresses margins for providers lacking scale, while buyers with multi-year frameworks extract pricing concessions through volume commitments and outcome-based contracting.
Pricing Analysis
Warranty and service bundling separates premium-certified engagements from unbundled transactional arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 27001/SOC 2 Type II certification status, with security-validated cloud platforms commanding 40-60 percent premiums over baseline offshore delivery. Cost compression in the standard tier is intensifying because large language models commoditize entry-level research and document coding tasks. Small and medium enterprises exhibit highest price sensitivity through digital sourcing platforms, while large pharmaceutical sponsors prioritize relationship continuity over rate competition for regulatory submission support.
Supply Chain Analysis
Workforce availability in Bengaluru, Hyderabad, and Pune anchors global KPO delivery, with secondary clusters emerging in Chennai and Delhi-NCR to escape wage inflation. Talent pipelines draw from Indian Institutes of Technology, National Law Universities, and specialized pharmacovigilance training academies, while technology infrastructure rests on AWS, Azure, and GCP hyperscaler regions with sub-50 millisecond latency guarantees. Single-source vulnerability concentrates in Mumbai for patent law expertise and biostatistics PhDs. Distribution runs through direct enterprise sales teams for large pharmaceutical and insurance clients, with self-service platforms and digital marketplaces capturing small and medium enterprise demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI is displacing legacy labor-arbitrage models, compressing research cycle times from weeks to days and forcing KPO providers to reconfigure talent architectures around human-AI collaboration.
For Market Incumbents: Anticipate margin erosion in standalone research and document coding segments as large language models trained on legal corpora and medical literature automate entry-level tasks. Defensive consolidation through acquisition of boutique regulatory affairs specialists in Switzerland and Japan preserves premium pricing power. Certification investment in EU AI Act compliance documentation and algorithmic auditing services creates differentiation against pure technology vendors. For New Entrants and Emerging Players: Begin with environmental data analytics under CSRD and SEC climate disclosure rules, where corporate sustainability reporting opens uncontested service lines in carbon accounting and supply chain traceability. Japan's cloud-first government and enterprise operations present the most penetrable geography, with bilingual capabilities bridging PMDA regulatory complexity and offshore delivery scale. Go-to-market through METI-registered system integrators accelerates trust formation with risk-averse Japanese pharmaceutical sponsors. For Investors and Strategic Acquirers: The window for entry favors India-centric delivery specialists with vertical academies and validated quality management systems serving FDA and EMA-regulated pharmaceutical sponsors. Long-term viability hinges on providers' capacity to shift pricing models from hourly rates to outcome-based structures tied to deliverable quality. Watch FDA enforcement actions on 21 CFR Part 11 compliance as inflection indicator for consolidation pressure among subscale vendors lacking validated infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Domain-Specific Training Academy Expansion | WNS-style vertical academies in Mumbai and Pune sustain margin quality in insurance and healthcare segments. |
| Hybrid Cloud Delivery Architecture Deployment | IBM-validated infrastructure supports enterprise-scale pharmaceutical engagements requiring 21 CFR Part 11 compliance. |
| Generative AI Tool Integration | Accenture's embedding of AI tools directly into client workflows reduces manual research cycles for legal and pharmaceutical clients. |
| Regional Data Residency Infrastructure | GDPR-compliant processing environments in Frankfurt and Munich enable European pharmacovigilance contract expansion. |
| Outcome-Based Pricing Model Transition | Agentic AI unification of research workflows enables pricing tied to deliverable quality rather than labor hours. |
Research Methodology
Document review covered FDA 21 CFR Part 11 guidance documents, EMA Good Pharmacovigilance Practices mandates, and ISO 27001/SOC 2 Type II certification standards, complemented by interviews with pharmaceutical regulatory affairs directors, insurance claims analytics executives, law firm managing partners, KPO delivery center heads, and enterprise procurement officers. Secondary validation drew from SEC climate disclosure filings, EU AI Act regulatory texts, ClinicalTrials.gov protocol registrations, and Indian CDSCO alignment notifications with ICH guidelines. Bottom-up service line sizing and top-down market triangulation reconciled variance across estimation approaches.
Cross-reference between historical contract value trajectories and expert panel input on automation substitution timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type integration depth, delivery model security certification tier, end-user industry compliance stringency, and client scale procurement sophistication. CAGRs derived from weighted average of trend extrapolation and scenario-adjusted growth assumptions, with pharmaceutical pipeline velocity and legal services outsourcing penetration serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical regulatory submission support and legal e-discovery carry tighter precision than emerging environmental data analytics. Forecasts reflect assumptions on AI adoption curves, regulatory enforcement intensity, and data localization mandate expansion. Material deviation in FDA inspection frequency, EMA pharmacovigilance reporting requirement changes, or GDPR cross-border transfer enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market