
 Europe Smart Doorbell Market | 2026-2036
Europe Smart Doorbell Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Doorbell Market Insights
Buyer concentration across European residential construction is broadening beyond single-family developers toward multi-unit housing consortia and social housing authorities. Amazon (Ring) leverages its logistics infrastructure to dominate direct-to-consumer channels across the United Kingdom and Germany. Netatmo (Legrand) anchors its position through backward integration into Legrand's electrical distribution networks, ensuring specifier access at the project-design stage. Bosch Security Systems competes on manufacturing scale, operating dedicated European production lines that reduce lead times for large commercial installations.
A smart doorbell integrates a camera, microphone, speaker, and network connectivity module into a door-mounted enclosure, typically operating on Wi-Fi or low-power wireless protocols with resolutions ranging from 1080p to 4K and field-of-view angles exceeding 160 degrees. Its primary purpose is to enable remote visual verification of visitors, two-way communication, and automated access logging for residential and commercial entry points. Wireless product variants lead volume shipments across Europe due to retrofit compatibility with masonry construction lacking structured wiring, while wired units command premium positioning in new-build segments where electricians specify integrated low-voltage infrastructure. Smart integration features represent the fastest-expanding margin pool, as consumers prioritize interoperability with existing Alexa, Google Home, or Apple HomeKit ecosystems over standalone hardware capabilities.
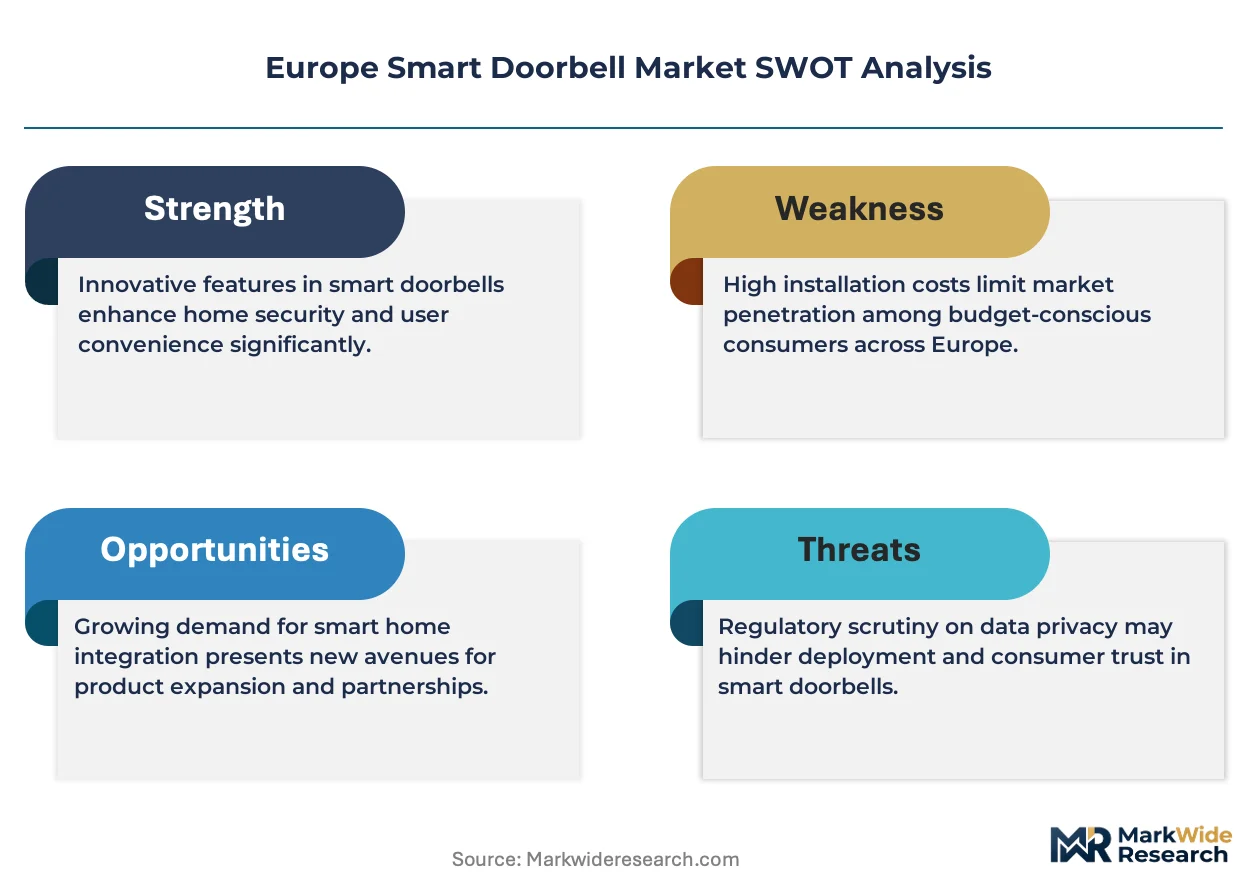
GDPR and the EU AI Act impose strict constraints on biometric data processing, compelling manufacturers to implement local edge analytics rather than cloud-dependent facial recognition pipelines. CE marking under the Radio Equipment Directive and cybersecurity requirements within the EU Cybersecurity Act further condition market access, with non-compliant products facing withdrawal from EEA distribution channels. Stakeholders must monitor evolving EN standards for IoT device resilience and determine whether to absorb compliance costs internally or pass them through premium positioning strategies.
Market Dynamics
Edge-processing architectures are displacing cloud-dependent biometric pipelines across European smart doorbell manufacturing, driven by GDPR Article 9 restrictions on special category data processing and the EU AI Act's risk-based classification system for biometric identification systems.
Growth Catalysts
- EU AI Act compliance mandates:Manufacturers redesign hardware to perform facial analytics locally, eliminating cross-border data transfers and accelerating certification timelines under CE marking requirements.
- Multi-family residential specification:German and French developers now embed video-enabled units into standard amenity packages, creating pull-through demand for interoperable smart home ecosystems.
- Utility-led retrofit subsidies:United Kingdom energy providers bundle smart doorbells into aging housing stock upgrade programs, reducing consumer acquisition costs for wireless retrofit variants.
Market Restraints
- Semiconductor supply concentration:Dependency on Taiwanese foundries for image signal processors creates lead time volatility for 4K resolution modules.
- GDPR enforcement variance:Divergent interpretations of lawful basis for processing across CNIL, ICO, and German DPA jurisdictions complicate pan-European product standardization.
- Masonry construction retrofit costs:Wireless battery-powered units face shorter operational lifespans in cold climates, elevating total cost of ownership versus wired alternatives.
Strategic Opportunities
- Social housing authority procurement:Underserved municipal segments in Italy and Spain seek bulk purchasing frameworks for security infrastructure modernization.
- Matter protocol convergence:Interoperability between Thread and Wi-Fi is unifying previously fragmented smart home ecosystems, reducing consumer switching barriers.
- CSRD-aligned ESG reporting:Corporate sustainability disclosure requirements create demand for supply chain transparency tools embedded in procurement platforms.
Industry Challenges
- Edge AI firmware engineering scarcity:Limited talent pools for on-device machine learning optimization constrain product development velocity.
- EN 303 645 cybersecurity certification:Extended testing timelines for IoT device resilience standards delay market entry for new hardware releases.
- Legacy intercom integration complexity:Retrofit compatibility with existing 2-wire analog systems requires custom protocol adapters, fragmenting installation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Doorbell Market |
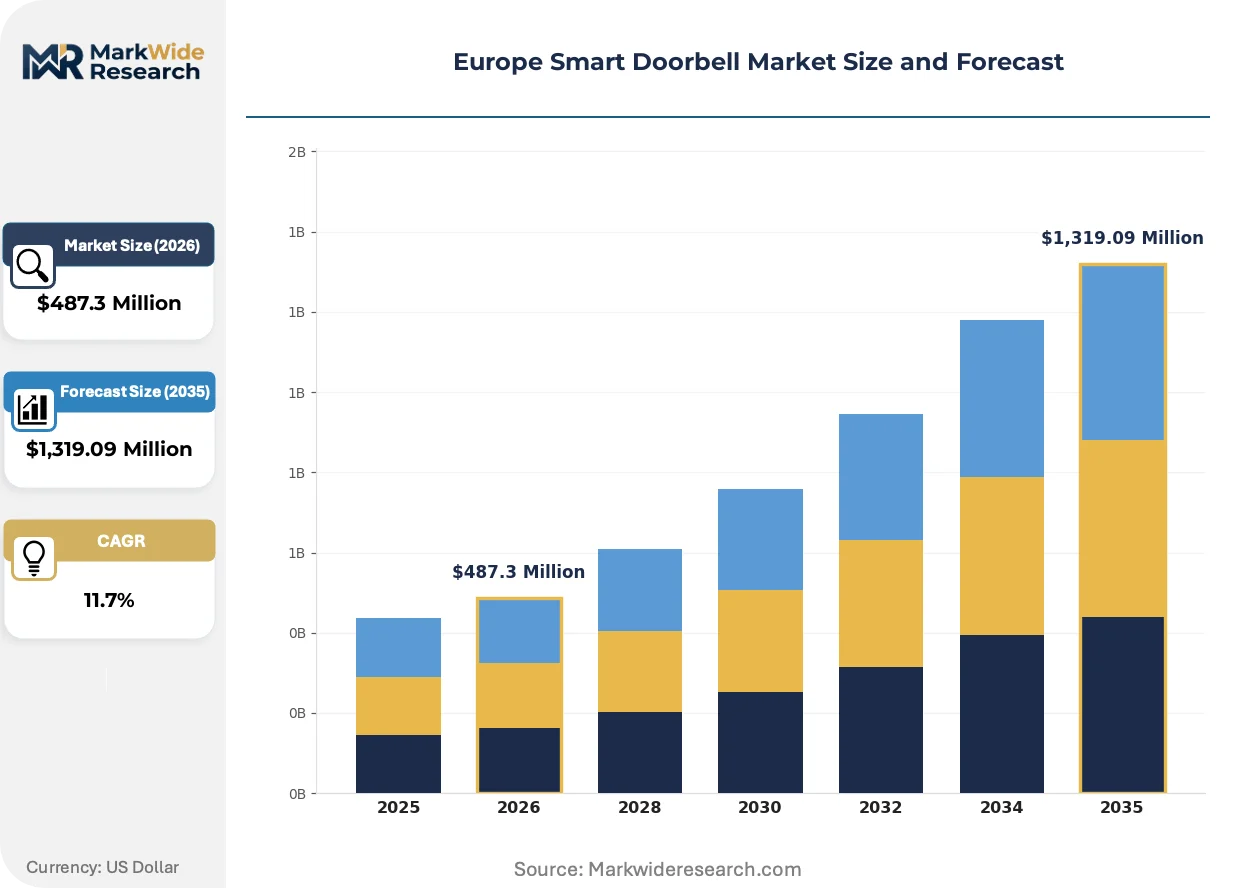
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Video, Audio Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave End User: Residential, Commercial, Institutional, Industrial Feature: Motion Detection, Two-Way Audio, Night Vision, Smart Integration |
| Companies Covered | Netatmo (Legrand), August Home (ASSA ABLOY), Amazon (Ring), Eufy Security (Anker Innovations), Honeywell International Inc., Google (Nest), Bosch Security Systems, ADT Inc., Arlo Technologies, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Doorbell Market Trends and Innovations
Architectural shifts toward on-device intelligence are compressing the competitive window for cloud-first vendors, while regulatory fragmentation accelerates hardware diversification across national markets.
Edge-based neural processing units are unifying video analytics, motion detection, and biometric verification within single-system-on-chip designs. German security integrators specify these modules for commercial installations requiring sub-100-millisecond response times. The technology is unifying previously separate hardware tiers into unified product lines, eroding premium positioning for standalone facial recognition accessories.
The EU AI Act's prohibited practices list for real-time remote biometric identification in publicly accessible spaces is forcing residential-focused manufacturers to decouple surveillance-grade features from consumer hardware. CE marking under the Radio Equipment Directive now requires explicit conformity assessments for AI-enabled functionalities. United Kingdom installers report extended pre-sales consultation periods as buyers navigate lawful use boundaries for visitor logging systems.
Social housing procurement consortia are consolidating specification authority previously dispersed among individual property managers. France's Union Sociale pour l'Habitat and comparable bodies in Belgium now issue framework agreements covering ten-thousand-plus unit deployments. This concentration is displacing direct-to-consumer channels for volume transactions, privileging vendors with dedicated public-sector sales infrastructure.
Europe Smart Doorbell Market Segmentation
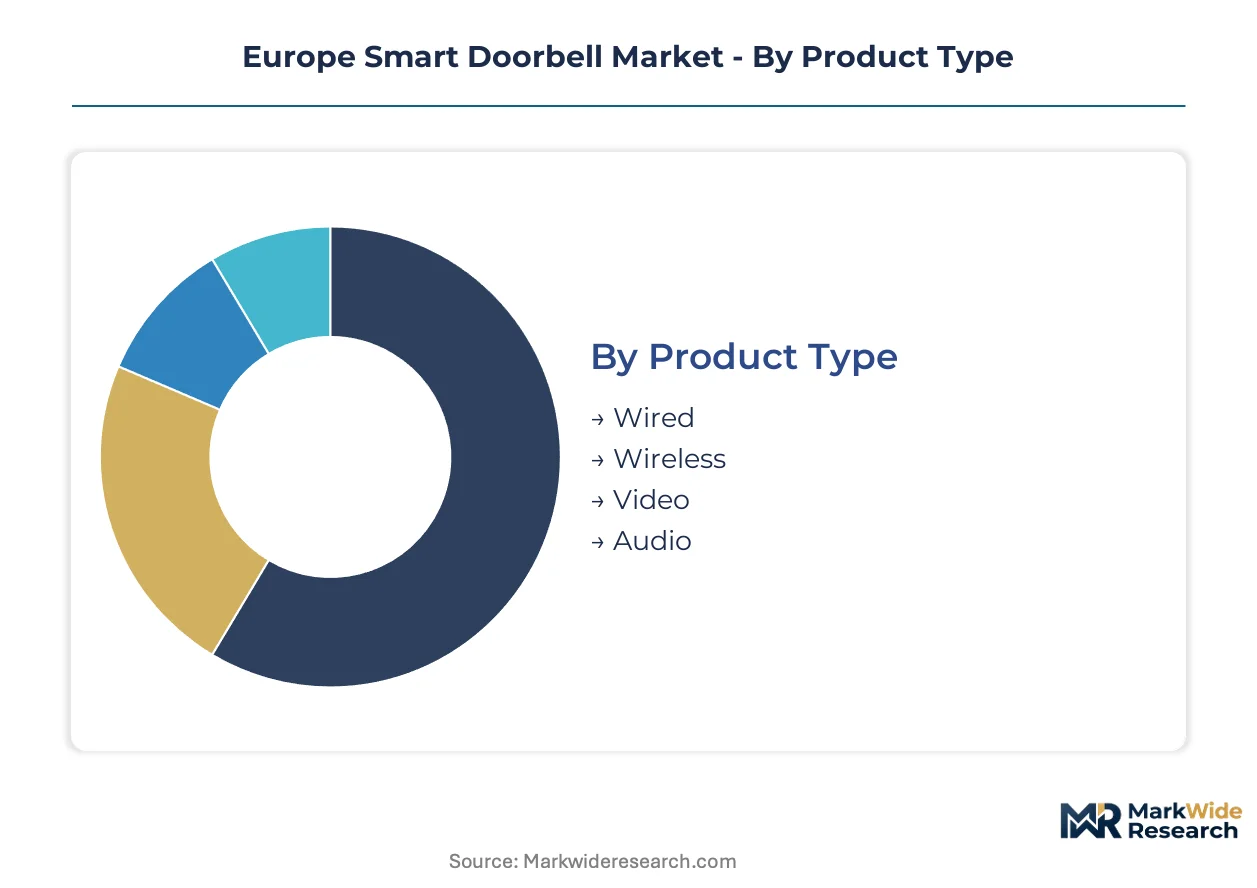
European smart doorbell procurement splits sharply between retrofit wireless installations in aging masonry housing and wired specifications in new multi-family construction. GDPR compliance requirements and the EU AI Act's biometric restrictions further differentiate product configurations across national markets.
Product Type:
Installation constraints and electrical infrastructure availability separate buyer preferences across European housing stock ages.
- Wired:Low-voltage power delivery enables continuous 4K streaming and eliminates battery maintenance cycles. German and French multi-family developers specify these units as standard amenities in new construction, pulling demand through electrical contractor channels.
- Wireless:Battery-powered enclosures clip onto existing door frames without masonry drilling. United Kingdom retrofit programs favor these variants for aging terraced housing where structured wiring is absent, though cold-weather battery degradation elevates replacement frequency.
- Video:1080p to 4K camera modules with 160-degree field-of-view dominate consumer expectations.
- Audio:Speaker-microphone arrays for visitor communication without visual verification serve price-sensitive segments.
Volume sits with Wireless; growth tilts toward Wired as new-build multi-family specifications expand.
Technology:
Protocol selection determines ecosystem lock-in and interoperability with existing smart home infrastructure.
- Wi-Fi:Ubiquitous router compatibility supports cloud-dependent architectures, though GDPR Article 9 restrictions now push manufacturers toward local edge processing to minimize cross-border data exposure.
- Bluetooth:Low-energy pairing enables smartphone proximity authentication for battery-constrained designs.
- Zigbee:Mesh networking protocols integrate with Thread-based Matter ecosystems unifying previously fragmented device categories.
- Z-Wave:Sub-GHz frequency penetration through masonry walls appeals to Central European retrofit applications.
Wi-Fi commands current volume; Zigbee climbs fastest as Matter protocol convergence accelerates.
End User:
Procurement authority and compliance obligations vary dramatically across ownership structures.
- Residential:Individual homeowners prioritize Alexa, Google Home, or Apple HomeKit interoperability over standalone capabilities. United Kingdom utility subsidy programs concentrate demand here for wireless retrofit variants.
- Commercial:Office landlords require centralized access logging and integration with building management systems. GDPR biometric restrictions under CNIL and ICO interpretations complicate pan-European standardization for facial recognition features.
- Institutional:Social housing authorities in France and Belgium issue framework agreements covering ten-thousand-plus unit deployments.
- Industrial:Manufacturing facilities demand ruggedized enclosures with extended temperature operating ranges.
Residential holds volume; Institutional expands steepest as municipal procurement consolidates.
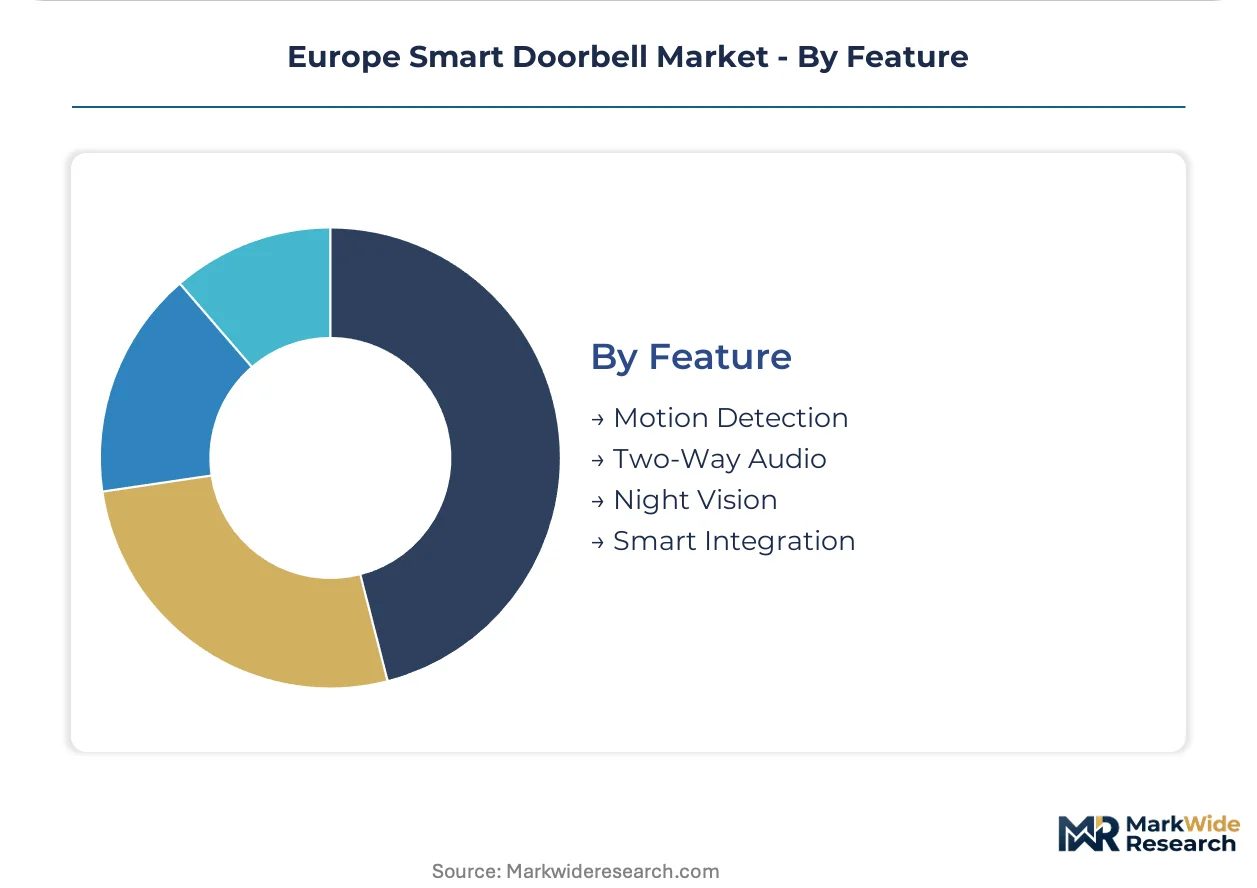
Feature:
Margin extraction concentrates where hardware differentiation intersects with regulatory-compliant software architectures.
- Motion Detection:Passive infrared and radar-based sensors trigger recording without continuous power draw. Edge-processing implementations satisfy GDPR minimization principles by eliminating cloud transmission of raw video streams.
- Two-Way Audio:Full-duplex speaker-microphone arrays enable real-time visitor conversation. German security integrators specify these for commercial installations requiring sub-100-millisecond response times.
- Night Vision:Infrared LED illumination extends operational hours for residential security applications.
- Smart Integration:API connectivity to third-party platforms represents the fastest-expanding margin pool as ecosystem interoperability overtakes hardware specifications in purchase decisions.
Motion Detection leads volume; Smart Integration gains share fastest as ecosystem lock-in deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom demand concentrates around utility-led retrofit programs targeting aging terraced housing stock. German and French multi-family developers embed video-enabled units as standard amenities, pulling specification authority toward electrical contractor channels. Southern European municipal procurement remains fragmented but consolidating.
United Kingdom
Energy providers bundle smart doorbells into aging housing stock upgrade schemes, reducing consumer acquisition costs for wireless retrofit variants. ICO guidance on biometric data processing under GDPR Article 9 shapes product configurations toward edge-processing architectures. London and Southeast England clusters concentrate installer networks serving dense Victorian-era housing stock.
Germany
North Rhine-Westphalia multi-family developers specify wired low-voltage units as standard amenities in new construction projects. KBA and German DPA interpretations of EU AI Act biometric restrictions accelerate local edge analytics adoption. Bavaria's security integrator networks drive commercial installation demand for sub-100-millisecond response time systems.
France
Union Sociale pour l'Habitat framework agreements consolidate procurement authority for ten-thousand-plus unit social housing deployments. CNIL enforcement of GDPR special category data rules pushes manufacturers toward on-device facial analytics. Île-de-France electrical distribution networks anchor specifier access at project-design stage through backward integration.
Italy
Municipal social housing authorities seek bulk purchasing frameworks for security infrastructure modernization in underserved segments. CE marking under Radio Equipment Directive conditions market access for Wi-Fi and Zigbee protocol variants. Lombardy and Veneto industrial clusters concentrate distribution partnerships for Matter protocol convergence.
Spain
Social housing procurement consortia consolidate specification authority previously dispersed among individual property managers. Spanish DPA interpretations of lawful basis for biometric processing complicate pan-European product standardization. Madrid and Catalonia metropolitan areas drive retrofit demand for wireless battery-powered units in masonry construction.
Europe Smart Doorbell Market Competitive Landscape
United States technology conglomerates anchor one tier through direct-to-consumer channels and ecosystem lock-in; European electrical equipment specialists hold project-specification influence through distribution network integration. The vendor base splits between cloud-first platform operators and edge-processing hardware architects. Two archetypes dominate: logistics-leveraged ecosystem players and backward-integrated electrical infrastructure vendors. Competitive moves concentrate on strategic partnerships with utility subsidy programs and portfolio diversification into Matter protocol interoperability.
Within the electrical infrastructure tier, Netatmo (Legrand) exemplifies backward integration into distribution networks, occupying a position where specifier access at project-design stage anchors volume. Amazon (Ring) represents logistics-leveraged ecosystem dominance, sitting within direct-to-consumer channels across the United Kingdom and Germany. Bosch Security Systems anchors the manufacturing scale archetype, with European production lines reducing lead times for large commercial installations.
| Leading Market Players |
|---|
| Netatmo (Legrand) |
| August Home (ASSA ABLOY) |
| Amazon (Ring) |
| Eufy Security (Anker Innovations) |
| Honeywell International Inc. |
| Google (Nest) |
| Bosch Security Systems |
| ADT Inc. |
| Arlo Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Edge AI firmware engineering scarcity in Germany and the Netherlands widens labor-cost differentials between premium wired systems and economy wireless variants, compressing mid-tier positioning as manufacturers absorb specialized talent premiums or sacrifice margin.
Pricing Analysis
Volume concentrates in wireless retrofit units while margins concentrate in wired new-build specifications with integrated low-voltage infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked edge-processing units from cloud-dependent imports from non-EEA manufacturers. Price differentiation hinges on GDPR compliance certification and Matter protocol interoperability, with cost compression in the standard tier intensifying due to Taiwanese foundry concentration for image signal processors. Social housing authorities exhibit highest price sensitivity; commercial security integrators show lowest sensitivity given project-bundled procurement.
Supply Chain Analysis
Image signal processor supply rests on Taiwanese foundry capacity, with secondary sourcing from South Korean and USA-based semiconductor fabricators for neural processing units. Critical component dependencies include CMOS sensors from Sony and Omnivision, lithium-ion cells from Chinese manufacturers, and RF modules from Nordic Semiconductor. Single-source vulnerability in advanced node fabrication for edge AI chips creates lead time volatility. Distribution runs through electrical contractor channels for new-build specifications and direct-to-consumer platforms for retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe smart doorbell market sits in a technology-transition phase where edge-processing architectures displace cloud-first legacy systems, with GDPR Article 9 and the EU AI Act accelerating hardware redesign cycles.
For Market Incumbents: Extend backward integration into Legrand-style electrical distribution networks to lock specifier access at project-design stage, and extend firmware engineering capacity through German and Dutch talent acquisition to defend against edge AI capability gaps. Cloud-first vendors face displacement risk as CE marking timelines favor local analytics architectures.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for edge-processing specialists to capture share from cloud-dependent incumbents facing compliance retrofit costs. Target Italian and Spanish social housing procurement consortia as the most penetrable institutional segment, and pursue Matter protocol certification as the primary go-to-market angle for ecosystem interoperability.
For Investors and Strategic Acquirers: Re-rating potential sits with edge-processing hardware architects given GDPR enforcement variance across CNIL, ICO, and German DPA jurisdictions favoring compliant local vendors. Long-term viability favors companies with captive firmware engineering and European production footprints. Watch EN 303 645 cybersecurity certification timelines as the signal for competitive window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Development | GDPR Article 9 compliance accelerates demand for on-device facial analytics capabilities. |
| Matter Protocol Certification | Thread and Wi-Fi interoperability reduces consumer switching barriers across fragmented ecosystems. |
| Social Housing Framework Agreements | France's Union Sociale pour l'Habitat consolidates procurement authority for ten-thousand-plus unit deployments. |
| European Production Footprint Expansion | Bosch-style regional manufacturing reduces lead times for large commercial installations. |
| Utility Subsidy Program Partnerships | United Kingdom energy provider bundling cuts consumer acquisition costs for wireless retrofit variants. |
Research Methodology
Independent corroboration across smart home platform developers, electrical contractor networks, and social housing procurement officers underwrites the qualitative findings. Primary interviews with security integrators, firmware engineering leads, and CE marking consultants combined with secondary validation from Radio Equipment Directive filings, EN standard development records, and customs trade data for Wi-Fi and Zigbee module imports. Bottom-up shipment estimates triangulate against top-down construction permit data for multi-family residential specifications.
Comparable-period anchoring to pre-COVID baseline volumes and post-subsidy program launch trajectories structures the forecast window. Segmentation dimensions span installation type, protocol technology, end-user ownership structure, and feature configuration across the projection horizon. CAGRs derive from logistic adoption curves fitted to smart home penetration benchmarks, with inputs including utility subsidy budget allocations and EU AI Act implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for cloud-to-edge migration would alter the outlook. Forecasts reflect assumptions about Matter protocol convergence speed and EN 303 645 certification timeline stability. Semiconductor supply normalization and GDPR enforcement harmonization represent revision triggers. A small set of regulatory and supply triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
BYOD Security Market
Security Software
Wi-Fi Based Home Camera Market
Security Software
Privileged Identity Management Market
Security Software
Security Software Market
Security Software
Quantum Key Distribution System Market
Security Software
Identity Verification Software Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Application Control Software Market
Security Software
Contactless Smart Card Market
Security Software
Global Automatic Number Plate Recognition (ANPR) System Market
Security Software
Internet Filter Software Market
Security Software
Online Background Check Market
Security Software
Data Privacy Software Market
Security Software
Managed Security Services Market
Security Software
Hardware OTP Token Authentication Market
Security Software
DC and PKI Market