
 Biometric POS Terminals Market | 2026-2036
Biometric POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric POS Terminals Market Analysis
The capability gap between integrated biometric sensor manufacturers and pure-play terminal assemblers is collapsing as semiconductor costs fall and fingerprint module sourcing democratizes. IDEMIA leverages its government identity contracts to anchor high-assurance payment terminal sales across European banking networks. Fujitsu Ltd. sustains dominance in palm vein authentication through proprietary vascular pattern algorithms that resist spoofing attacks. PAX Technology competes on manufacturing scale, shipping multi-biometric terminals from Shenzhen facilities that serve emerging market acquirers.
Biometric POS terminals combine fingerprint, iris, facial, or palm vein sensors with encrypted payment processing hardware to authenticate cardholders without PIN entry or signature verification. Optical and capacitive fingerprint modules typically operate at 500 dots per inch resolution with liveness detection algorithms that prevent synthetic finger presentation attacks. Fingerprint recognition leads terminal shipments due to mature sensor supply chains and sub-dollar unit costs at volume, while facial recognition grows fastest in hospitality deployments where hands-free checkout improves throughput. Cloud-based deployment architectures concentrate margin pools for software vendors managing biometric template vaults and tokenization services across merchant fleets.
FDA device classification for biometric health-linked payment systems, Europe's GDPR biometric data processing constraints, and India's RBI tokenization mandates collectively shape product design and market access requirements for terminal vendors. PCI SSC point-to-point encryption standards now incorporate biometric template protection protocols that add compliance cost but reduce breach liability for deployers. Stakeholders must monitor whether central bank digital currency pilots in major economies will mandate biometric verification at merchant acceptance points.
Market Dynamics
The biometric POS terminal market is undergoing structural compression as semiconductor cost deflation erodes the traditional moat between integrated sensor manufacturers and downstream hardware assemblers, collapsing historical capability gaps and redistributing margin pools toward software-defined authentication architectures.
Growth Catalysts
- PSD2 Strong Customer Authentication:Europe's EBA mandates under PSD2 compel banks to certify biometric payment hardware, creating institutional procurement pull across continental banking networks.
- Rural Banking Correspondent Networks:India's RBI-backed expansion of biometric-enabled merchant devices through UPI-linked rural banking channels concentrates demand generation in underserved territories.
- Fingerprint Module Democratization:Sub-dollar optical and capacitive sensor costs at volume enable tier-two assemblers to enter multi-biometric terminal production without captive semiconductor fabrication.
Market Restraints
- GDPR Biometric Data Processing Constraints:Europe's GDPR Article 9 classification of biometric data as special category data imposes consent architecture costs and breach liability exposure that slow merchant fleet deployment.
- Sensor Supply Concentration:Optical fingerprint module production clusters in Shenzhen and Hsinchu create geographic supply vulnerability for terminal assemblers lacking dual-source qualification.
- Template Protection Compliance Burden:PCI SSC point-to-point encryption standards incorporating biometric template protection protocols add certification cost layers that disproportionately burden smaller acquirers.
Strategic Opportunities
- Central Bank Digital Currency Pilots:Emerging economy CBDC programs in Southeast Asia and Latin America are exploring biometric verification mandates at merchant acceptance points, opening hardware specification windows.
- Palm Vein Hospitality Integration:Contactless vascular pattern authentication converges with property management systems in luxury hotel chains, creating premium deployment segments resistant to fingerprint commoditization.
- Cloud Template Vault Services:Software vendors managing encrypted biometric tokenization across distributed merchant fleets capture recurring revenue streams as hardware margins compress.
Industry Challenges
- Multi-Modal Sensor Integration Complexity:Engineering teams face firmware architecture challenges combining fingerprint, facial, and iris recognition modules with unified liveness detection pipelines.
- Certification Timeline Compression:Simultaneous PCI SSC, EMVCo, and national banking regulator approvals for multi-biometric terminals extend time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric POS Terminals Market |
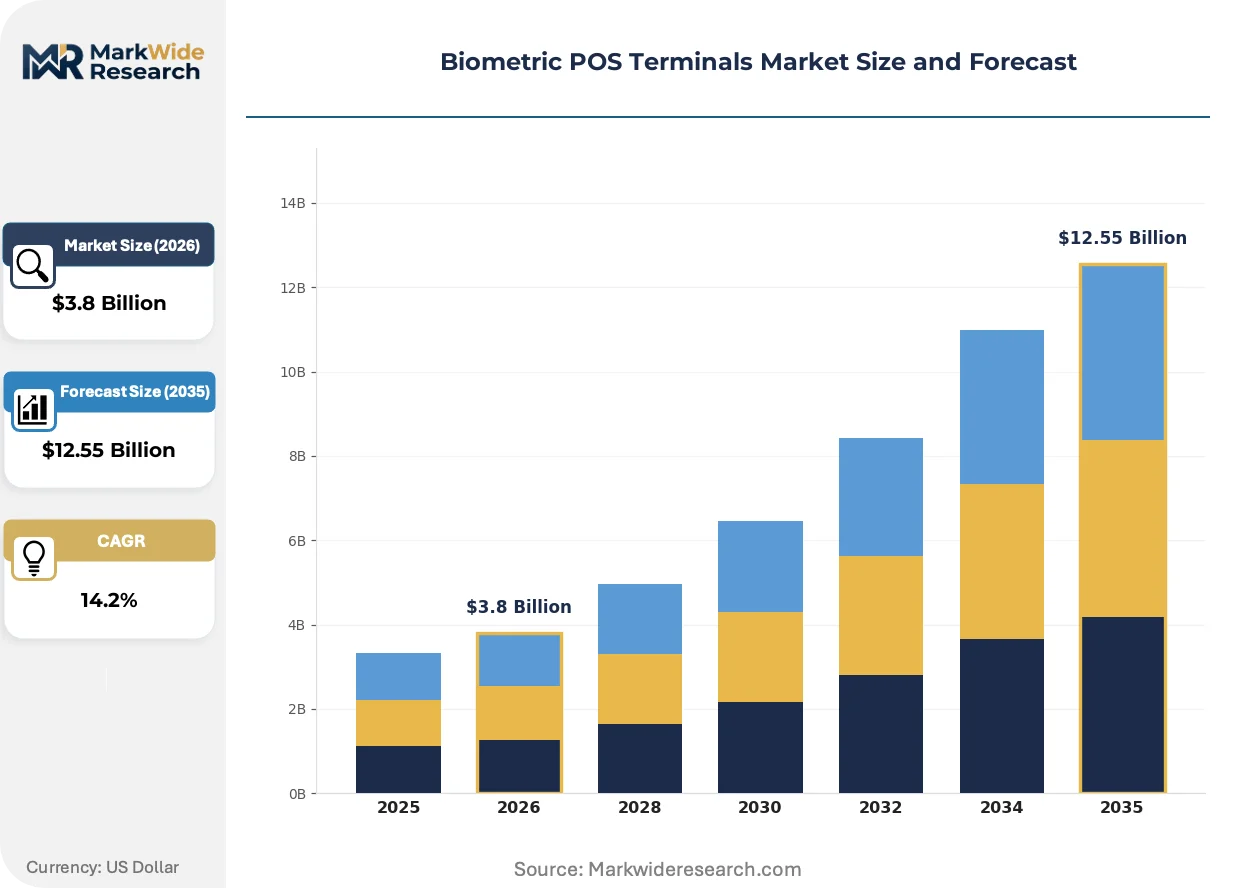
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprints, Iris Recognition, Facial Recognition, Palm Vein Technology: Optical, Capacitive, Ultrasound, Thermal End User: Retail, Hospitality, Banking, Healthcare Deployment: On-premise, Cloud-based, Hybrid, Mobile |
| Companies Covered | IDEMIA, Ingenico (Worldline), NEC Corporation, Fujitsu Ltd., Suprema Inc., Verifone, PAX Technology, Zwipe, DERMALOG Identification Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric POS Terminals Market Emerging Trajectories
Authentication modality selection is actively fragmenting across end-use verticals as merchants trade off transaction speed, spoofing resistance, and hardware cost in divergent ways. Three forces are reshaping terminal design priorities.
Multi-modal biometric fusion is bifurcating terminal architectures between cost-optimized single-sensor devices for retail and hardened multi-factor systems for high-value transactions. Quick-service restaurants and convenience chains are standardizing on fingerprint-only configurations to minimize per-unit hardware outlay. Financial institutions and luxury hospitality deployees are absorbing palm vein and facial recognition premiums to reduce synthetic biometric fraud exposure.
Europe's GDPR and India's RBI tokenization mandates are forcing template storage localization and encryption protocol upgrades across terminal firmware stacks. Vendors must maintain parallel software branches for jurisdictions with divergent data residency requirements. Banking network deployers in Germany and France are prioritizing terminals with on-device template matching to minimize cloud data exposure.
Merchant acquiring patterns are fragmenting between integrated payment providers bundling biometric hardware with processing services and independent software vendors unbundling authentication software from commodity terminal procurement. Large retail chains in Indonesia and Vietnam are shifting toward hardware-agnostic biometric middleware that operates across mixed terminal fleets. This decoupling concentrates negotiating leverage with acquirers while eroding terminal OEM direct sales margins.
Biometric POS Terminals Market Segmentation
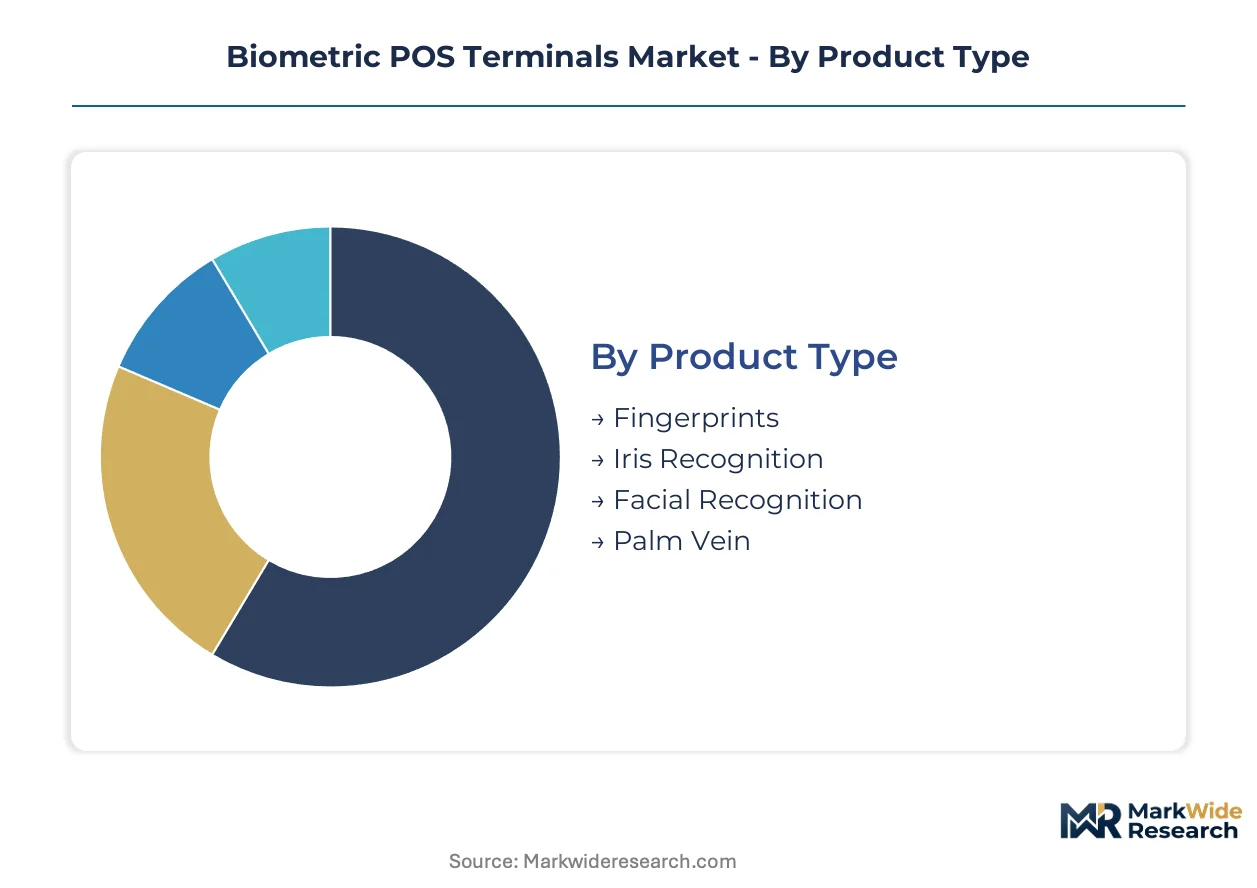
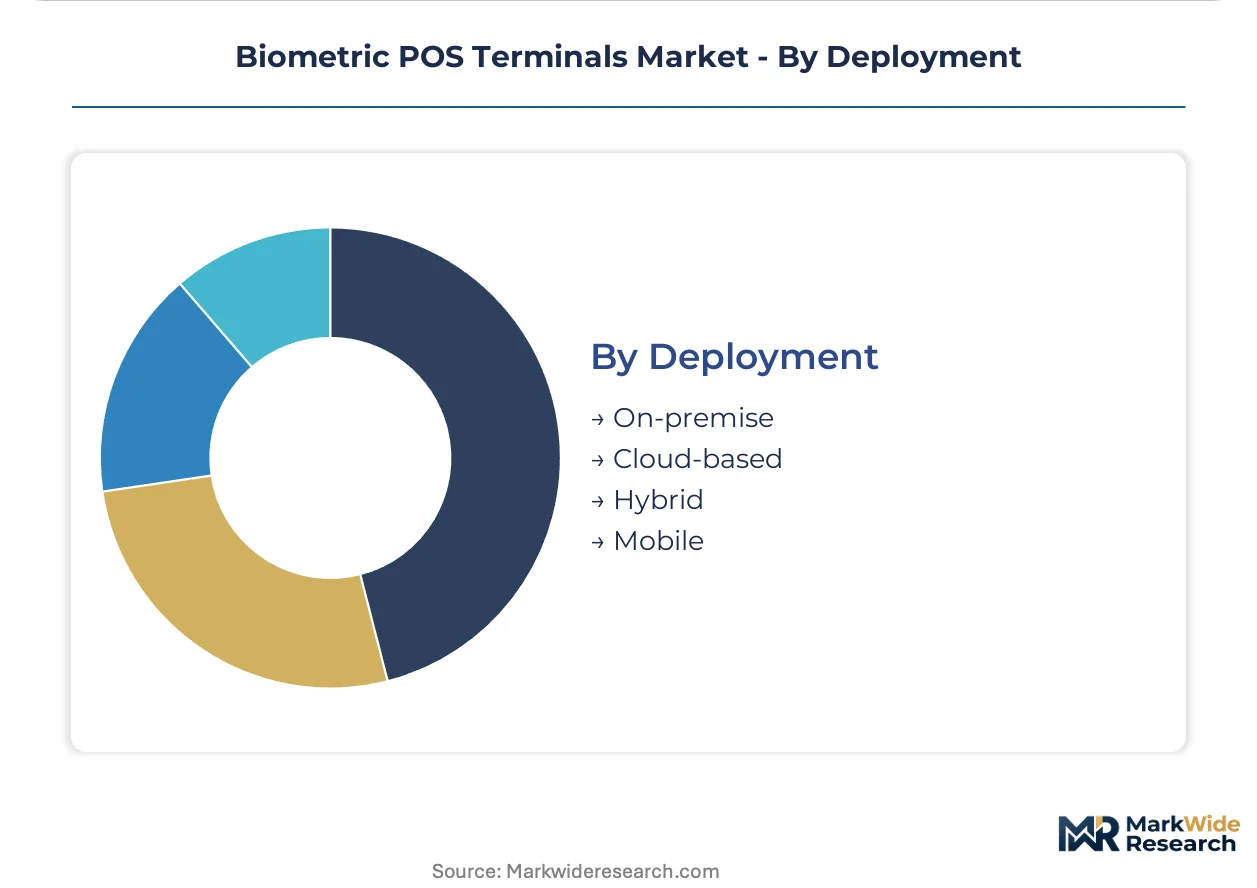
Biometric POS terminal purchasing fragments sharply across authentication modalities and deployment architectures, with substitution pressure from mobile wallets and smartphone-based biotics forcing hardware vendors to defend position through multi-modal integration and vertical-specific certification bundles.
Product Type:
Fingerprint modules face the steepest substitution pressure from facial recognition in hospitality and palm vein in high-value banking, while iris recognition remains protected by niche applications requiring contactless precision.
- Fingerprints:Optical and capacitive sensors operating at 500 dots per inch resolution with embedded liveness detection dominate retail checkout deployments across India's rural banking correspondent network. Transaction speed requirements at quick-service restaurants and convenience chains in Indonesia and Vietnam concentrate demand here, though spoofing vulnerability limits expansion into luxury segments.
- Facial Recognition:3D structured light and time-of-flight camera arrays enable hands-free authentication for hospitality throughput optimization. Deployment is accelerating in Southeast Asian hotel chains and European airport retail where hygiene concerns and speed premiums override hardware cost sensitivity.
- Iris Recognition:Near-infrared imaging systems deliver the highest resistance to presentation attacks for healthcare and high-security banking applications.
- Palm Vein:Fujitsu's proprietary vascular pattern algorithms anchor premium deployments in Japanese and European financial institutions where synthetic biometric fraud exposure drives authentication investment.
Fingerprint modules anchor the volume base while facial recognition gains share at the steepest rate across hospitality and transit retail deployments.
Technology:
Cost tier stratification separates mature optical and capacitive platforms from ultrasound and thermal alternatives, with manufacturing scale determining which sensor modalities achieve sub-dollar unit economics at volume.
- Optical:CMOS-based fingerprint imaging modules from Shenzhen and Hsinchu production clusters dominate cost-optimized terminal production for emerging market acquirers. India's UPI-linked biometric merchant device expansion concentrates procurement here, though supply concentration creates geographic vulnerability for terminal assemblers lacking dual-source qualification.
- Capacitive:Silicon wafer-based sensors deliver superior image quality and power efficiency for battery-powered mobile terminal deployments. European banking networks under EBA PSD2 mandates prioritize these modules for strong customer authentication compliance.
- Ultrasound:Piezoelectric transducer arrays penetrate subdermal tissue layers to defeat spoofing attempts through synthetic fingerprint presentation.
- Thermal:Temperature differential mapping captures fingerprint ridge patterns without optical components for harsh environment durability.
Optical technology captures the majority procurement volume while capacitive platforms expand most quickly in regulated European banking certification pipelines.
End User:
Application-specific compliance burdens and transaction value thresholds fragment terminal specifications, with banking and healthcare facing stricter biometric data protection requirements than retail and hospitality.
- Retail:High-throughput checkout environments in Southeast Asian chains drive standardization on fingerprint-only configurations to minimize per-unit hardware outlay. Indonesia and Vietnam's large retail networks are shifting toward hardware-agnostic biometric middleware that operates across mixed terminal fleets, eroding OEM direct sales margins.
- Banking:RBI tokenization mandates and Europe's GDPR Article 9 classification force template storage localization and encryption protocol upgrades. German and French banking network deployers prioritize on-device template matching to minimize cloud data exposure.
- Hospitality:Luxury hotel chains absorb palm vein and facial recognition premiums to reduce synthetic biometric fraud exposure while converging with property management systems.
- Healthcare:FDA device classification for biometric health-linked payment systems adds compliance layers that slow merchant fleet deployment.
Retail anchors terminal shipment volumes while banking drives the steepest authentication specification upgrades through regulatory mandate accumulation.
Deployment:
Customer type stratification between integrated payment providers and independent software vendors determines whether biometric authentication bundles with processing services or unbundles from commodity terminal procurement.
- Cloud-based:Software vendors managing encrypted biometric tokenization and template vaults across distributed merchant fleets capture recurring revenue streams as hardware margins compress. Margin pools concentrate here for authentication service providers operating PCI SSC-compliant point-to-point encryption with biometric template protection protocols.
- On-premise:Large retail chains and financial institutions with dedicated IT infrastructure maintain local template storage to satisfy GDPR data residency requirements and minimize breach liability exposure.
- Hybrid:Edge-computing architectures process authentication locally while synchronizing encrypted templates to centralized vaults for multi-location merchant operations.
- Mobile:Battery-powered biometric terminals serve India's rural banking correspondent expansion and temporary event commerce where fixed infrastructure is unavailable.
On-premise deployment retains the installed base while cloud-based architectures climb the fastest as software-defined authentication redistributes margin pools from hardware vendors to service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys biometric POS terminals predominantly through rural banking correspondent networks, while European banking networks prioritize on-device template matching for GDPR compliance, and Southeast Asian retail chains emphasize hospitality-focused facial recognition for throughput optimization.
India
Rural banking correspondent expansion and UPI-linked biometric merchant devices concentrate procurement demand across underserved territories. RBI tokenization mandates force template storage localization and encryption protocol upgrades in terminal firmware stacks. Manufacturing clusters in Bengaluru and Hyderabad assemble optical fingerprint modules for cost-optimized domestic deployment.
Germany
Banking networks under EBA PSD2 strong customer authentication mandates prioritize capacitive sensor modules for compliance certification pipelines. GDPR Article 9 classification of biometric data as special category data imposes consent architecture costs on merchant fleet operators. Frankfurt and Munich financial centers anchor high-assurance payment terminal procurement for continental banking networks.
Indonesia
Quick-service restaurant chains and convenience retail networks standardize on fingerprint-only configurations to minimize per-unit hardware outlay. Large retail networks shift toward hardware-agnostic biometric middleware operating across mixed terminal fleets. Jakarta and Surabaya commercial corridors concentrate acquirer procurement for emerging market deployment scale.
United States
FDA device classification for biometric health-linked payment systems adds compliance layers that slow merchant fleet deployment in healthcare-adjacent retail. PCI SSC point-to-point encryption standards incorporating biometric template protection protocols drive certification investments. Silicon Valley sensor developers and Atlanta payment processing hubs shape hardware specification requirements.
Japan
Luxury hospitality chains absorb palm vein authentication premiums to reduce synthetic biometric fraud exposure while converging with property management systems. METI industrial standards influence multi-modal terminal certification requirements for financial institution deployment. Tokyo and Osaka metropolitan banking networks anchor premium-tier biometric hardware procurement.
Biometric POS Terminals Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with semiconductor cost deflation collapsing historical capability gaps between sensor manufacturers and terminal assemblers. The vendor base stratifies into three archetypes: government identity contract holders leveraging high-assurance credentials, proprietary algorithm developers defending premium positioning through spoofing resistance, and Shenzhen-based scale manufacturers serving emerging market acquirers. Competitive moves concentrate on strategic partnerships with payment networks and portfolio diversification into cloud template vault services.
Within the integrated technology tier, Fujitsu Ltd. and NEC Corporation exemplify proprietary algorithm developers anchoring premium market positions through specialized biometric modalities. IDEMIA occupies a position bridging government identity infrastructure and banking network certification requirements. PAX Technology represents the scale-manufacturing archetype, with Shenzhen-based production facilities serving emerging market procurement volumes.
| Leading Market Players |
|---|
| IDEMIA |
| Ingenico (Worldline) |
| NEC Corporation |
| Fujitsu Ltd. |
| Suprema Inc. |
| Verifone |
| PAX Technology |
| Zwipe |
| DERMALOG Identification Systems |
| Others |
Supply Flow & Price Mechanics
PCI SSC point-to-point encryption standards incorporating biometric template protection protocols simultaneously gate supply qualification for terminal vendors and stratify price differentiation across certification tiers, compressing margins for uncertified assemblers while anchoring premium positioning for compliant hardware.
Pricing Analysis
Long-term offtake contracts with tier-one banking networks anchor pricing for high-assurance biometric terminals, while spot procurement dominates emerging market acquirer transactions. Three-tier pricing structure across premium, standard, and economy levels separates palm vein and multi-modal systems from fingerprint-only configurations and unbranded optical modules. Cost compression in economy-tier optical fingerprint terminals is intensifying because Shenzhen-based scale manufacturers are absorbing sensor deflation to maintain volume share. Quick-service restaurant chains in Southeast Asia exhibit the highest price sensitivity, while European financial institutions under EBA PSD2 mandates demonstrate the lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites logistics for optical fingerprint module shipments from Shenzhen and Hsinchu production clusters to terminal assemblers across Southeast Asia. CMOS sensor fabrication concentrates in Taiwan, South Korea, and China, with capacitive silicon wafers sourcing from Japan and Germany. Terminal assembly draws from plastic injection molding in Vietnam, precision metalwork in Thailand, and final integration in India and Indonesia. Single-source vulnerability in liveness detection algorithm licensing creates supply chain risk for tier-two assemblers lacking captive software development. Distribution runs through integrated payment providers bundling hardware with processing services and independent distributors serving unbanked merchant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric POS terminal demand is recovering from cyclical compression as semiconductor cost deflation triggers replacement cycles and central bank digital currency pilots create specification windows for hardware refresh.
For Market Incumbents: Fortify cloud template vault service offerings to capture recurring revenue as hardware margins compress, while deepening backward integration into optical sensor production to defend against Shenzhen-based scale entrants. Palm vein authentication patents and government identity contract relationships provide defensive moats against fingerprint commoditization.
For New Entrants and Emerging Players: Cloud-based biometric middleware for hardware-agnostic deployment across mixed terminal fleets represents the most penetrable service-layer gap, as large retail chains in Indonesia and Vietnam seek negotiating leverage with acquirers. Target rural banking correspondent networks in India through UPI-linked biometric merchant device partnerships with domestic assemblers in Bengaluru and Hyderabad.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed payment terminal OEMs that acquired hardware capabilities during prior consolidation waves but under-invested in software-defined authentication architectures. Long-term viability hinges on template vault service recurring revenue share. Watch central bank digital currency pilot biometric verification mandates as the inflection indicator for hardware specification windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Template Vault Expansion | PCI SSC-compliant encryption protocols enable recurring revenue capture from merchant fleet tokenization services. |
| Palm Vein Hospitality Integration | Fujitsu's proprietary vascular algorithms converge with property management systems in luxury hotel chains. |
| Backward Integration into Sensors | Captive optical module production defends margin position against Shenzhen-based scale manufacturers. |
| CBDC Pilot Specification Capture | Biometric verification mandates in Southeast Asian central bank digital currency programs open hardware windows. |
| Rural Banking Network Penetration | UPI-linked biometric merchant devices through India's RBI-backed correspondent expansion concentrate underserved demand. |
Methodological Framework
Desk research of PCI SSC certification databases, EMVCo product registries, and RBI circulars preceded structured interviews with terminal OEM product managers, payment network compliance officers, and rural banking correspondent network operators. Secondary validation drew from SEC filings of listed payment hardware vendors, customs import records for fingerprint module trade flows, and central bank digital currency pilot documentation. Bottom-up shipment estimates by authentication modality and deployment architecture triangulated against top-down banking network procurement disclosures.
Variance decomposition across the projection horizon isolates volume drivers by segment, with authentication modality mix, regulatory certification timelines, and cloud migration pace as primary dimensions. CAGRs derive from fitted growth curves incorporating hardware replacement cycles and software service attach rates. Forecast inputs include EMVCo terminal approval timelines, GDPR consent architecture deployment costs, and UPI transaction volume trajectories through rural correspondent channels.
Material uncertainties — central bank digital currency mandate scope, biometric data processing regulatory tightening, and semiconductor supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline compression and merchant fleet cloud migration adoption curves. Practitioners should keep alternative scenarios live as CBDC biometric verification requirements and GDPR enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Intrusion Detection System / Intrusion Prevention System (IDS / IPS) Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Quantum Key Distribution System Market
Security Software
Identity and Access Management (IAM) Market
Security Software
Europe Encryption Software Market
Security Software
Parental Monitoring Software Market
Security Software
Europe Enterprise Firewall Market
Security Software
United States Lawful Interception Market
Security Software
Website Monitoring Software Market
Security Software
Global Email Verification Tools Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Communication Encryption Software Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Global Data Breach Notification Software Market
Security Software
Network Security Appliance Market
Security Software
Cloud Security Software Market