
 Decentralized Identity Software Market | 2026-2036
Decentralized Identity Software Market Size, Share, and Industry Trends Forecast 2026-2036
Decentralized Identity Software Market Insights
Self-sovereign identity architecture is fragmenting the traditional identity-provider stack away from centralized credential stores toward user-controlled verification. Microsoft anchors enterprise-grade deployments through its Entra Verified ID platform, while IBM leverages Hyperledger Fabric integrations to sustain institutional trust frameworks. ConsenSys competes in the Ethereum-native layer with wallet-centric identity tooling.
Decentralized identity software enables entities to create, manage, and verify credentials without relying on a central authority, typically employing blockchain-anchored identifiers with W3C DID standards and verifiable credential cryptography. The technology serves commercial purposes ranging from streamlined KYC workflows to passwordless enterprise access control. Credential Management solutions occupy the mature revenue pool among product type segments, while Zero-Knowledge Proofs within the technology dimension represent the fastest-growing structural layer due to privacy-preserving compliance demands. Financial Institutions dominate end user uptake, though Healthcare Providers are expanding pilot budgets for patient-controlled medical records.
Regulators across multiple geographies are tightening identity frameworks: the EU AI Act imposes risk-classification requirements on automated verification systems, while GDPR mandates data minimization that favors zero-disclosure architectures. The US lacks unified federal identity law, though NIST guidelines and state-level biometric privacy statutes create fragmented compliance terrain. Stakeholders must monitor whether emerging liability rules for identity breaches shift procurement criteria toward auditable open-source implementations.
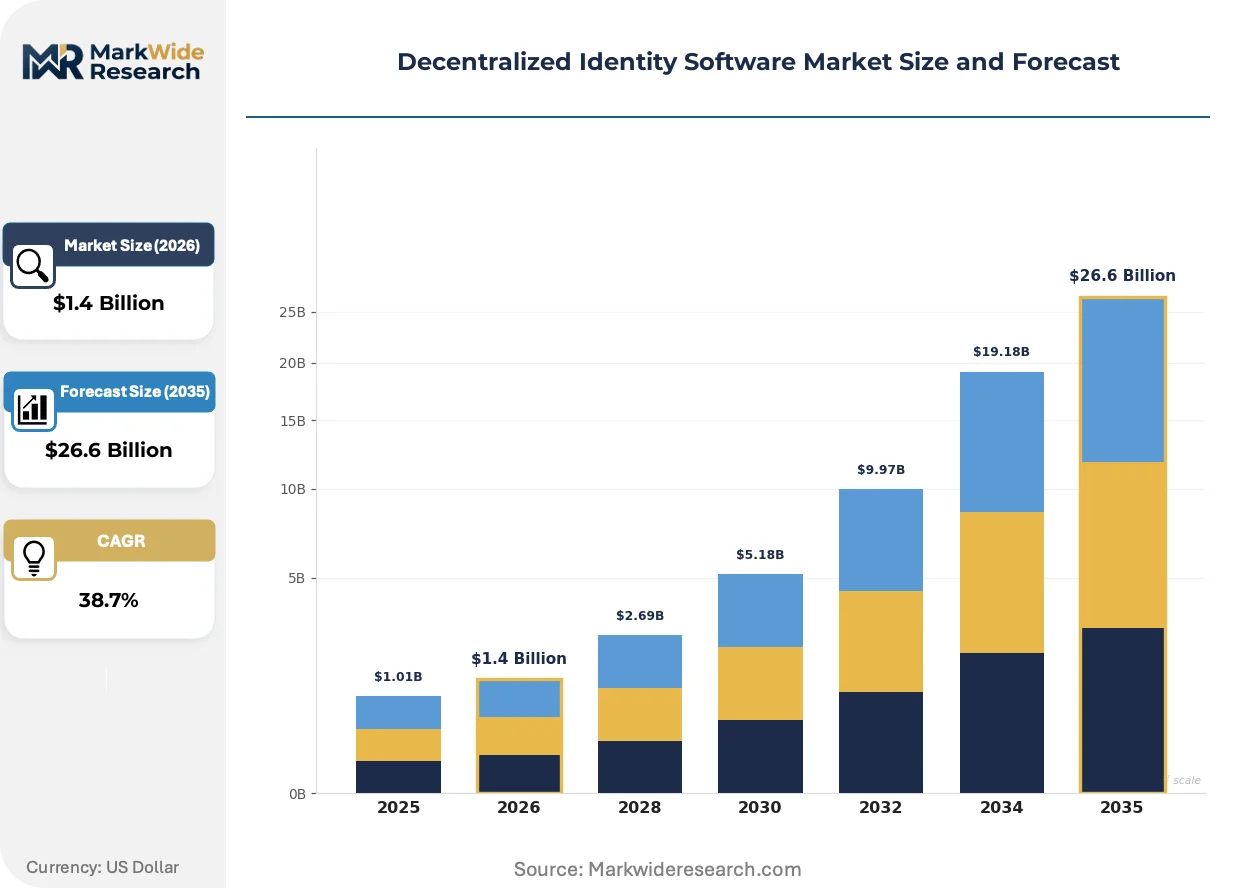
Market Dynamics
Zero-knowledge proof architectures are compressing the traditional identity verification stack by eliminating centralized credential repositories and shifting liability toward user-controlled cryptographic verification. This structural reconfiguration is redrawing competitive boundaries between legacy identity providers and blockchain-native infrastructure vendors.
Growth Catalysts
- GDPR Data Minimization Mandates:The EU's regulatory pressure on personal data collection is accelerating enterprise migration toward zero-disclosure authentication protocols that satisfy Article 5 principles without centralized storage.
- Financial Services KYC Modernization:Banks and payment processors are deploying self-sovereign identity to streamline customer onboarding while reducing compliance overhead for repetitive verification workflows.
- German Enterprise Pilot Expansion:Industrial consortia in Bavaria and Baden-Württemberg are operationalizing verifiable credential networks for supply chain partner authentication.
Market Restraints
- Interoperability Protocol Fragmentation:Competing DID method specifications across Hyperledger Indy, Ethereum ERC-725, and Bitcoin-based implementations create integration friction for multi-platform deployments.
- Specialized Cryptography Talent Scarcity:The shallow labor pool for zero-knowledge circuit engineering and verifiable credential schema design extends implementation timelines and inflates professional services costs.
- Legacy IAM Contract Lock-In:Enterprises maintain multi-year agreements with centralized identity providers like Okta and Ping Identity, creating switching friction and deferred procurement cycles.
Strategic Opportunities
- Patient-Controlled Health Records:Healthcare networks in the Netherlands and Estonia are piloting verifiable credential systems for cross-border medical data portability under the European Health Data Space framework.
- Cross-Border Digital Identity Corridors:The EU Digital Identity Wallet regulation creates a harmonized addressable market for interoperable credential verification across member state borders.
- Convergence of Biometric Liveness Detection with ZK Proofs:Integration of facial recognition anti-spoofing with privacy-preserving credential issuance opens new authentication tiers for high-assurance financial transactions.
Industry Challenges
- W3C DID Standard Implementation Gaps:Inconsistent resolver infrastructure and method-specific security assumptions create deployment complexity for enterprise architects.
- Revocation Registry Scalability:Maintaining real-time credential status verification without revealing holder identity strains current blockchain anchoring throughput and cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decentralized Identity Software Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $26.6 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Sovereign Identity, Credential Management, Authentication Solutions, Digital Wallets Technology: Blockchain, Distributed Ledger Technology, Zero-Knowledge Proofs, Public Key Infrastructure Use Case: Access Control, Identity Verification, Digital Signatures, Secure Transactions End User: Government, Financial Institutions, Healthcare Providers, Enterprises |
| Companies Covered | Blockchain Helix, Trinsic, Microsoft, 1Kosmos, CREDEBL, Evernym, AU10TIX, ConsenSys, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decentralized Identity Software Market Trends and Innovations
Cryptographic verification methods are actively displacing knowledge-based authentication across enterprise security stacks. Three concurrent developments are restructuring how identity infrastructure is procured, regulated, and consumed across financial services and healthcare verticals.
Zero-knowledge proof circuits are collapsing the distinction between identity verification and data privacy by enabling credential validation without attribute disclosure. Financial institutions in Singapore and Switzerland are deploying zk-SNARK-based age verification and income attestation for lending decisions. This compression eliminates the data breach liability exposure that plagues centralized credential databases.
The EU AI Act's risk classification framework is imposing mandatory human oversight requirements on automated identity verification systems. High-risk biometric deployments must maintain audit trails and algorithmic transparency documentation. German automotive suppliers and French banking consortia are restructuring procurement specifications to prioritize explainable AI components in their identity stacks.
Enterprise buyers are consolidating vendor relationships around integrated identity platforms that bundle credential issuance, wallet management, and verification services. Systems integrators are displacing point-solution vendors in RFP processes for Fortune 500 identity modernization programs. This concentration is most visible in US healthcare networks seeking unified patient identity spanning EHR systems and payer portals.
Decentralized Identity Software Market Segmentation
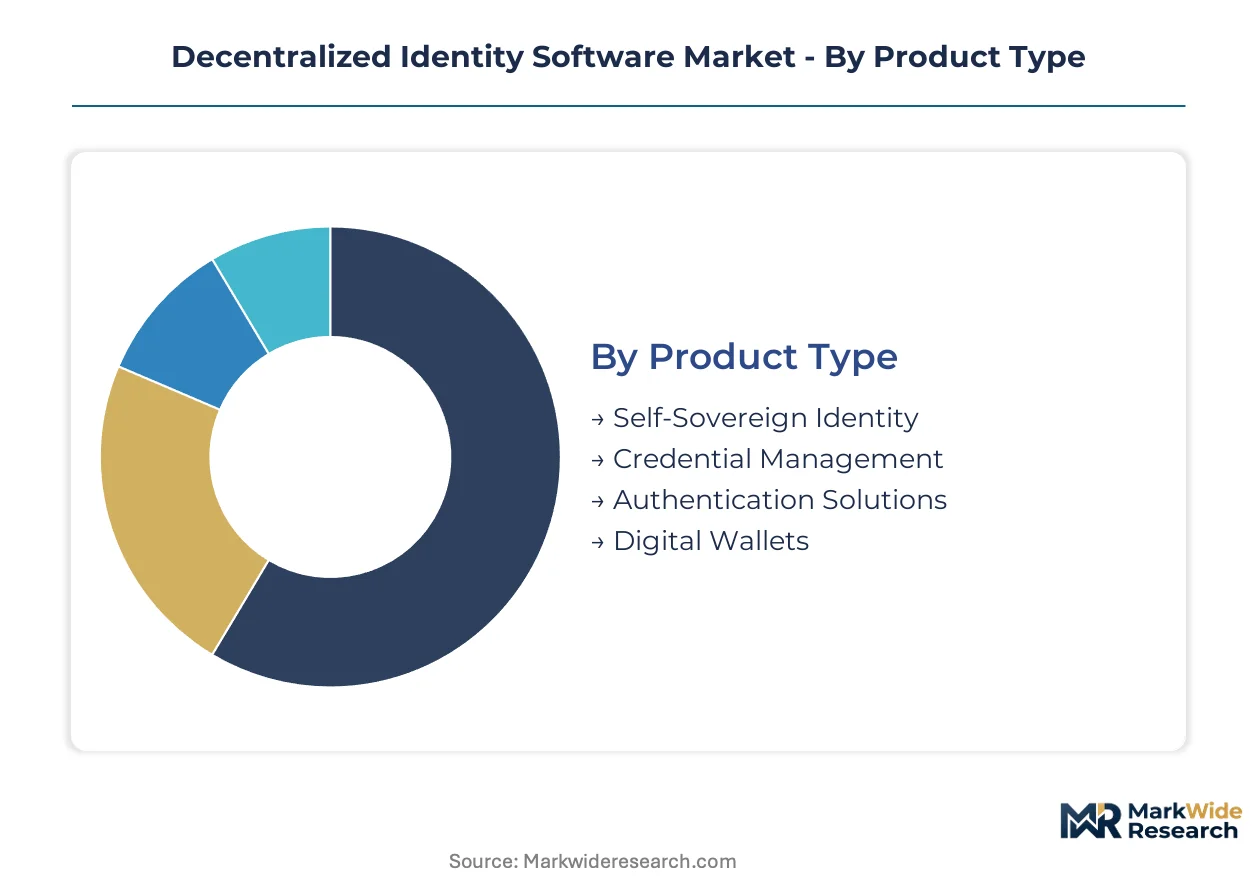
Segmentation in decentralized identity software reveals how architectural choices determine procurement priorities. Buyers select across credential control models, cryptographic foundations, and compliance postures rather than feature checklists alone.
Product Type:
Mature revenue pools sit alongside emerging deployment models, with enterprise buyers weighing operational stability against self-sovereign flexibility.
- Self-Sovereign Identity:User-controlled identifier architectures eliminate centralized credential stores through blockchain-anchored DIDs. German automotive suppliers and Dutch healthcare networks are piloting SSI frameworks for cross-organizational partner authentication under GDPR data minimization mandates.
- Credential Management:Enterprise-grade issuance, revocation, and lifecycle tooling for verifiable credentials dominates current procurement volumes. Financial institutions in Singapore leverage these systems for streamlined KYC workflows that reduce repetitive customer verification overhead.
- Authentication Solutions:Passwordless access control systems employing cryptographic key pairs rather than shared secrets. Bavarian industrial consortia are operationalizing these for supply chain facility access.
- Digital Wallets:Credential storage and selective disclosure interfaces for end-user devices. The EU Digital Identity Wallet regulation is accelerating standardization requirements across member states.
Credential Management handles the majority of throughput; Self-Sovereign Identity is gaining share fastest as regulatory pressure on data centralization intensifies.
Technology:
Cost-to-implementation ratios vary sharply across cryptographic layers, with zero-knowledge circuits commanding premium professional services fees.
- Blockchain:Immutable transaction logs anchor credential issuance and status registries. Ethereum-compatible implementations dominate startup ecosystems, while Hyperledger Fabric sustains institutional trust frameworks in banking consortia.
- Distributed Ledger Technology:Permissioned networks without proof-of-work overhead, preferred by enterprises requiring throughput predictability. Swiss financial infrastructure providers are deploying DLT-based identity verification for cross-border wealth management compliance.
- Zero-Knowledge Proofs:Privacy-preserving credential validation without attribute disclosure. zk-SNARK-based age and income attestation are expanding in Singaporean lending decisions and French banking pilot programs.
- Public Key Infrastructure:Certificate-based authentication with established audit trails and regulatory acceptance. PKI remains the default for healthcare providers in Estonia seeking interoperability with legacy EHR systems.
Public Key Infrastructure carries the installed base; Zero-Knowledge Proofs are climbing the fastest as privacy regulations tighten across jurisdictions.
Use Case:
Application intensity maps directly to regulatory enforcement timelines, with identity verification deployments accelerating ahead of access control refresh cycles.
- Identity Verification:Automated credential validation for customer onboarding and compliance screening. The EU AI Act's risk classification framework is restructuring procurement specifications to prioritize explainable AI components in biometric verification stacks.
- Access Control:Credential-gated resource authorization for enterprise systems and physical facilities. German enterprise pilots in Baden-Württemberg are operationalizing verifiable credential networks for supplier facility entry.
- Digital Signatures:Cryptographically non-repudiable document execution. Healthcare networks in the Netherlands are piloting patient-controlled signature workflows for cross-border medical consent under the European Health Data Space framework.
- Secure Transactions:Transaction authorization with cryptographic proof of credential validity. Financial institutions are converging biometric liveness detection with ZK proofs for high-assurance payment authentication tiers.
Identity Verification absorbs the largest implementation budgets; Secure Transactions is expanding most quickly as payment infrastructure modernizes.
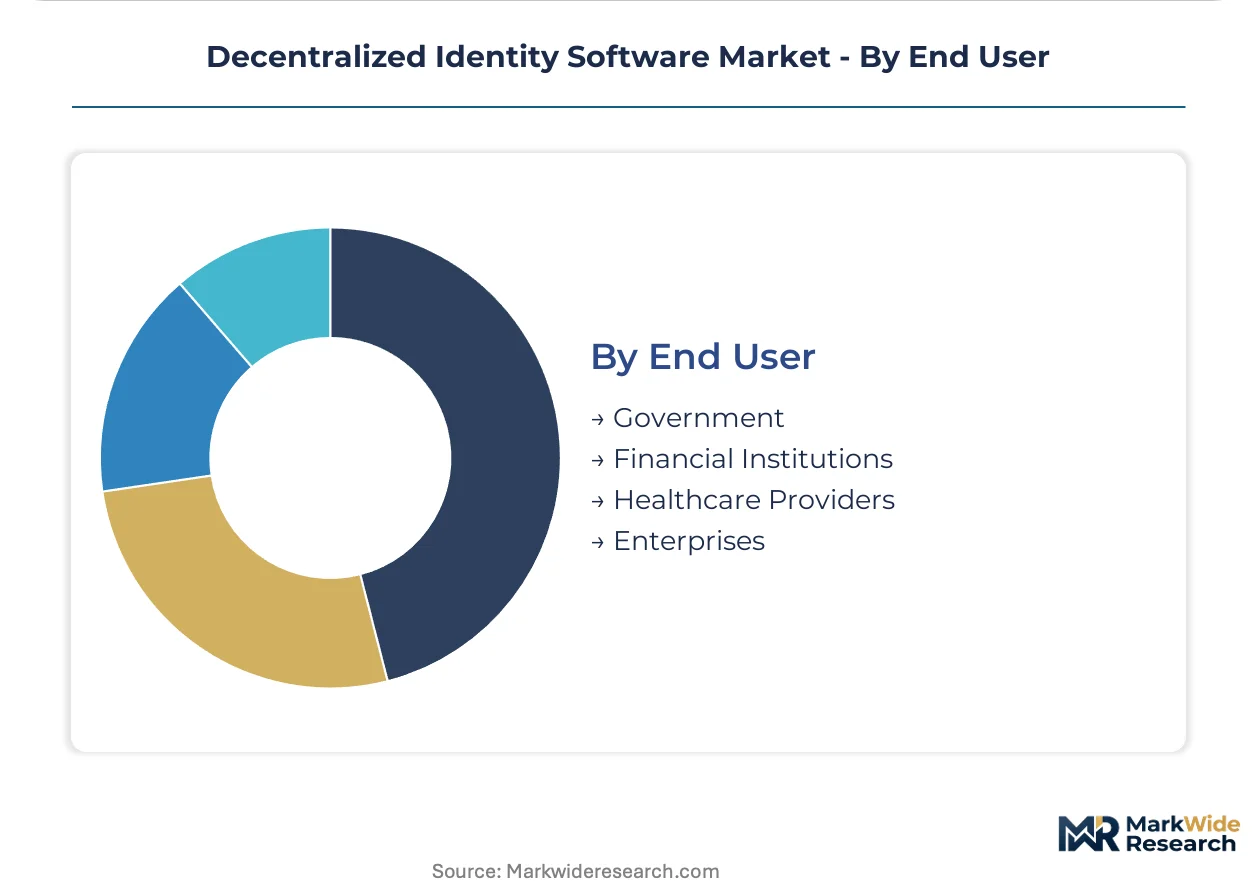
End User:
Customer type determines compliance burden and integration complexity, with financial services procurement cycles running shorter than government tender timelines.
- Financial Institutions:Banks, payment processors, and insurance carriers deploying KYC modernization and fraud prevention. These buyers are consolidating vendor relationships around integrated platforms bundling issuance, wallet management, and verification services.
- Government:National identity programs and cross-border credential recognition systems. The EU Digital Identity Wallet regulation creates harmonized procurement specifications across member state border control and public service delivery.
- Healthcare Providers:Hospital networks and payer organizations piloting patient-controlled medical records. US healthcare systems are seeking unified patient identity spanning EHR systems and payer portals.
- Enterprises:Non-financial corporations implementing workforce and supply chain identity. Industrial consortia are driving demand for zero-knowledge proof authentication to satisfy GDPR Article 5 data minimization principles.
Financial Institutions command the dominant share of current deployment; Healthcare Providers are showing the steepest expansion trajectory as patient data portability regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in decentralized identity software favor jurisdictions with harmonized regulatory frameworks. The United States generates substantial outbound licensing revenue through enterprise SaaS platforms. Germany and Singapore import cryptographic engineering talent while exporting compliance-certified verification protocols to neighboring markets.
United States
Financial institutions in New York and California drive demand for zero-knowledge proof authentication systems. NIST guidelines on digital identity create baseline procurement specifications for federal contractors. The San Francisco Bay Area concentrates venture-funded wallet infrastructure startups competing for enterprise pilot contracts.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg operationalize verifiable credential networks for supply chain partner verification. The EU AI Act's risk classification framework mandates human oversight for automated biometric systems deployed by Frankfurt banking consortia. Berlin hosts emerging SSI infrastructure vendors serving GDPR-compliant enterprise deployments.
Singapore
Lending institutions deploy zk-SNARK-based income attestation for credit decisions without centralized data pooling. The Monetary Authority of Singapore's digital banking licenses accelerate procurement of self-sovereign onboarding platforms. The city-state's fintech corridor attracts wallet infrastructure providers targeting Southeast Asian cross-border remittance verification.
Switzerland
Wealth management firms in Zurich and Geneva implement DLT-based identity verification for cross-border compliance screening. FINMA guidelines on blockchain financial infrastructure provide regulatory clarity for credential issuance services. The Crypto Valley cluster in Zug anchors Ethereum-native identity tooling development for institutional clients.
Netherlands
Healthcare networks pilot patient-controlled medical records under the European Health Data Space framework. The Dutch Authority for Personal Data enforces GDPR Article 5 data minimization principles that favor zero-disclosure architectures. Eindhoven's digital identity consortia test interoperable credential verification for cross-border care portability.
Decentralized Identity Software Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platforms that bundle issuance, wallet management, and verification services. Enterprise procurement teams favor unified vendor relationships over point-solution fragmentation. Three strategic archetypes dominate: cloud-native infrastructure providers, blockchain-native tooling vendors, and legacy identity platform extenders. Competitive moves center on strategic partnerships with systems integrators and geographic expansion through regulatory sandbox participation.
Within the cloud-native infrastructure tier, Microsoft and IBM exemplify enterprise-grade deployment archetypes, with Microsoft anchoring Entra Verified ID implementations and IBM sustaining institutional trust frameworks through Hyperledger Fabric integrations. ConsenSys occupies the Ethereum-native specialist position, representing wallet-centric identity tooling development for financial services clients seeking programmable credential logic.
| Leading Market Players |
|---|
| Blockchain Helix |
| Trinsic |
| Microsoft |
| 1Kosmos |
| CREDEBL |
| Evernym |
| AU10TIX |
| ConsenSys |
| IBM |
| Others |
Pricing and Supply Chain Analysis
Specialized zero-knowledge circuit engineering talent concentrates in Zurich, Singapore, and Berlin, anchoring premium professional services fees that migrate downstream toward enterprise credential management platforms. This upstream scarcity funnels margin pools toward cryptographic implementation layers rather than commoditized wallet interfaces.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command substantial markups for EU AI Act-compliant explainable AI components and GDPR-certified data minimization architectures. Price differentiation hinges on certification level—GDPR Article 5 compliance tiers separate offerings—and vertical integration depth in cryptographic core development. Pricing pressure stems from open-source DID resolver alternatives commoditizing baseline verification services. Financial institutions show lowest price sensitivity for high-assurance biometric-ZK proof bundles, while mid-market enterprises resist premium tiers without guaranteed interoperability guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware security module dependencies. Geographic supply concentration centers on Germany for automotive-grade credential issuance systems, Switzerland for wealth management compliance tooling, and Singapore for fintech wallet infrastructure. Raw material dependencies include specialized FPGA chips for ZK circuit acceleration, cryptographic accelerator hardware, and blockchain node hosting capacity. Single-source vulnerability persists for zero-knowledge proving key generation services. Distribution runs through systems integrators displacing direct vendor relationships in Fortune 500 procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. Switching costs escalate once enterprises embed verifiable credential networks across multi-party workflows.
For Market Incumbents: Entrench position through exclusive systems integrator partnerships that foreclose competitor access to healthcare and financial services RFP processes. Deepen vertical integration into zero-knowledge circuit design capabilities to capture professional services margin pools migrating from implementation partners. The emerging threat of wallet-native fintech disruptors demands preemptive platform bundling of issuance, verification, and credential lifecycle management. For New Entrants and Emerging Players: Establish a beachhead in patient-controlled health records where Dutch and Estonian pilot budgets expand under European Health Data Space frameworks. Target mid-tier German automotive suppliers seeking GDPR-compliant supplier authentication without legacy IAM contract burdens. A channel partnership-first go-to-market angle with national health IT integrators accelerates credential network effects. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed credential management platforms possessing entrenched financial services customer bases. Long-term viability across the analysis window favors vendors with regulatory sandbox participation spanning multiple EU member states. The signal to watch is EU Digital Identity Wallet standardization timelines as inflection indicators for interoperability premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Entra bundling with Azure AD displaces point-solution vendors in healthcare procurement cycles. |
| Strategic Partnership | ConsenSys alliances with Swiss wealth managers anchor Ethereum-native tooling in cross-border compliance screening. |
| Regulatory Sandbox Participation | Singapore MAS digital banking licenses accelerate self-sovereign onboarding platform validation for Southeast Asian remittance corridors. |
| Acquisition of Specialist Firm | IBM Hyperledger Fabric integrations with acquired ZK circuit engineering teams sustain institutional trust framework differentiation. |
| Geographic Expansion | German SSI infrastructure vendors leverage Bavarian automotive pilot networks to penetrate Baden-Württemberg supplier ecosystems. |
Research Methodology
Desk research of W3C DID specification repositories, EU regulatory filings, and blockchain protocol documentation preceded structured interviews with CTOs at financial institutions, IT procurement officers in German automotive suppliers, platform engineers at wallet infrastructure vendors, and integration specialists serving healthcare networks. Primary fieldwork combined with secondary validation against SEC filings from publicly traded identity vendors, venture capital disclosure databases, and hyperscaler cloud service expansion announcements. Bottom-up credential issuance volume estimates triangulated against top-down enterprise IT spending allocations across the analysis window.
Assumptions held fixed include sustained GDPR enforcement intensity and EU AI Act implementation timelines, while cryptocurrency market volatility and federated identity standard adoption rates were varied across sensitivity scenarios. The analytical framework modeled deployment model, organization size, vertical sector, integration complexity, and regional regulatory cluster segmentation dimensions. CAGRs derived from cohort-based adoption curves incorporating pilot-to-production conversion rates and credential network effect thresholds. Industry-specific forecast inputs included zero-knowledge proof circuit maturation trajectories and cross-border digital identity corridor harmonization progress.
Sensitivities concentrate around EU Digital Identity Wallet standardization delays, zero-knowledge cryptography talent pool expansion rates, and legacy IAM contract renewal cycles extending procurement deferrals. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity shifts or breakthroughs in post-quantum cryptographic verification methods. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Online Background Check Market
Security Software
Certification Authority Market
Security Software
Enterprise Rights Management Solution Market
Security Software
Website Monitoring Software Market
Security Software
US Hardware Encryption Market
Security Software
Automotive Endpoint Authentication Market
Security Software
E Passport Market
Security Software
Security Software Market
Security Software
Employee Computer Monitoring Software Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Key Management Service Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Video Intercom Devices Market
Security Software
Global Electronic Passports Market
Security Software
Hardware Encryption Market
Security Software
United States Consumer Identity and Access Management Market