
 Mobile Data Protection Solutions and Services Market | 2026-2036
Mobile Data Protection Solutions and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Data Protection Solutions and Services Market Foresight
The mobile data protection market is recalibrating around a widening capability gap between premium zero-trust architectures and commodity endpoint encryption. Microsoft Corporation leverages its cloud-native security stack to dominate enterprise SaaS deployment, while Palo Alto Networks differentiates through AI-powered threat detection across mobile attack surfaces. Sophos anchors mid-market positioning with consolidated endpoint and mobile data protection licensing.
Mobile data protection solutions and services encompass software and managed services that secure data across smartphones, tablets, and portable endpoints through encryption, containerization, remote wipe capabilities, and continuous authentication protocols. These systems enforce data residency, prevent unauthorized exfiltration, and maintain operational continuity for distributed workforces accessing corporate resources. Cloud-based deployment is outpacing on-premises alternatives as enterprises prioritize elastic capacity and reduced infrastructure overhead. Data Loss Prevention services command premium pricing due to complex regulatory mapping requirements across GDPR, HIPAA, and PCI DSS frameworks. Backup services remain mature with slower growth but generate recurring revenue stability through long-term retention contracts.
The US FDA and HIPAA shape healthcare mobile data mandates, while the EU GDPR and forthcoming EU AI Act impose algorithmic accountability on automated threat detection systems. Japan's METI guidelines and China's GB standards add compliance layers for multinational device fleets. Stakeholders must weigh quantum-resistant encryption roadmaps against near-term interoperability costs as regulatory timelines tighten.
Market Dynamics
Post-quantum cryptography migration is compressing vendor roadmaps while GDPR enforcement tightens data residency mandates across distributed workforces. This dual pressure is forcing enterprises to rebuild mobile security stacks around zero-trust architectures rather than perimeter-based models.
Growth Catalysts
- EU AI Act algorithmic accountability:Automated threat detection systems now require documented decision logic, driving demand for explainable AI security platforms in European financial services.
- Hybrid work persistence:Enterprise device fleets operating outside traditional perimeters necessitate continuous authentication protocols and containerized data separation.
- Containerization technology maturation:Work profile isolation on BYOD devices enables granular policy enforcement without full device control, accelerating adoption in healthcare and legal sectors.
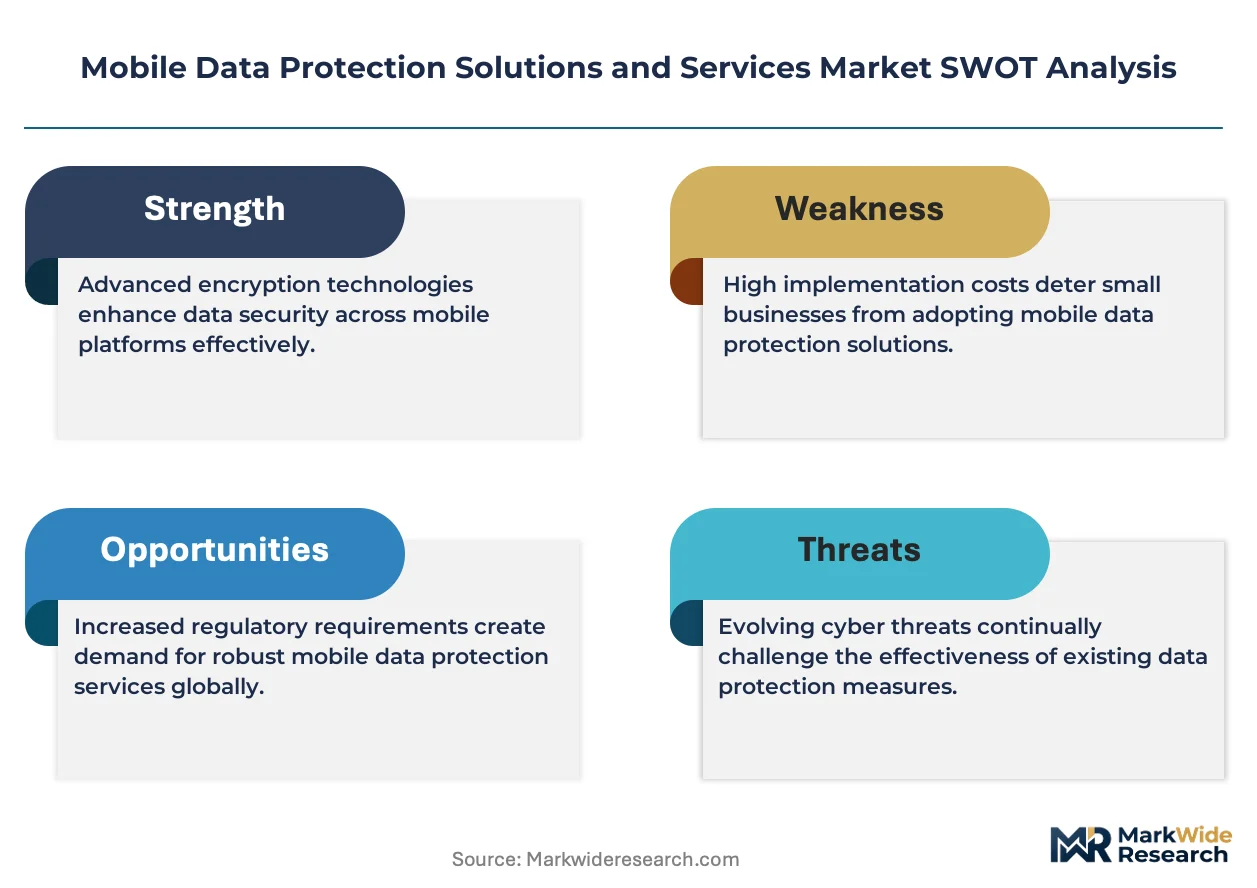
Market Restraints
- Quantum-resistant algorithm licensing costs:NIST-approved post-quantum cryptographic libraries carry per-device royalty structures that inflate deployment budgets.
- Certificate authority supply concentration:Mobile device management ecosystems depend on a narrow base of root certificate providers, creating single-point-of-failure exposure.
- Legacy endpoint encryption interoperability:Existing AES-256 implementations lack forward compatibility with lattice-based protocols, forcing parallel system maintenance.
Strategic Opportunities
- Germany data sovereignty enforcement:Bundesdatenschutzgesetz amendments create procurement preference for EU-hosted encryption key management services.
- 5G network slicing integration:Convergence of mobile data protection with network-isolated slices enables carrier-grade security guarantees for industrial IoT deployments.
- Outcome-based managed detection contracts:Financial services buyers in the United Kingdom are shifting from seat-based to incident-response-guaranteed pricing models.
Industry Challenges
- Post-quantum cryptography talent scarcity:Lattice-based implementation expertise remains concentrated among academic cryptographers and national laboratory researchers.
- Cross-border key escrow complexity:Multinational enterprises face conflicting data localization requirements when recovering encrypted mobile backups across jurisdictions.
- Legacy MDM integration friction:Existing mobile device management platforms lack API depth for continuous authentication protocols, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Data Protection Solutions and Services Market |
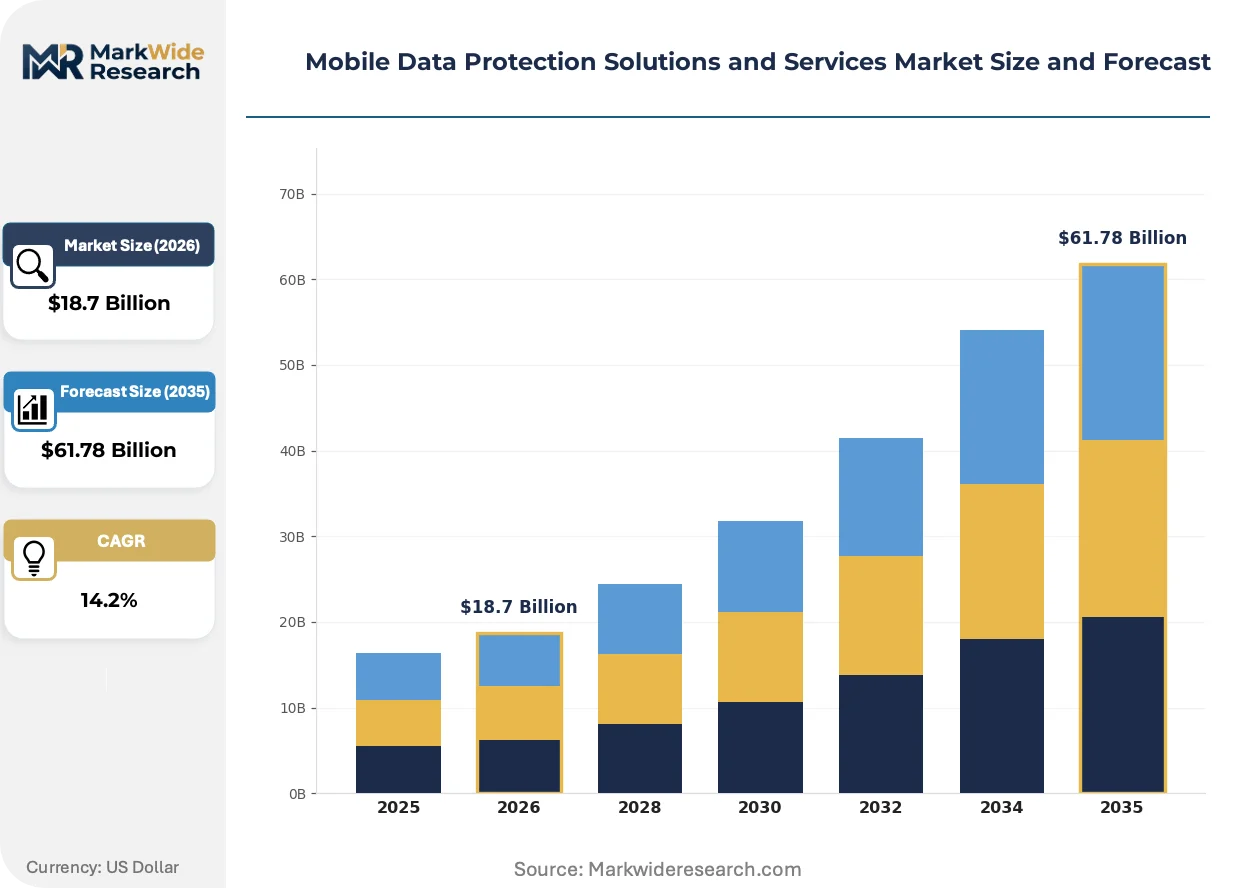
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Backup, Encryption, Firewall, Data Loss Prevention Deployment Model: On-premises, Cloud-based, Hybrid, SaaS End User: SMEs, Large Enterprises, Government, Healthcare Compliance Framework: GDPR, HIPAA, PCI DSS, ISO 27001 |
| Companies Covered | Dell Technologies Inc., Microsoft Corporation, Broadcom Inc., Hewlett Packard Enterprise Company, Trend Micro Incorporated, Cisco Systems, Palo Alto Networks, Sophos, Veritas Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Data Protection Solutions and Services Market Shifts & Advancements
Zero-trust mobile architectures are displacing VPN-centric access models as continuous verification becomes technically feasible at scale. This structural shift is redrawing competitive boundaries between endpoint security vendors and cloud-native platform providers.
Confidential computing enclaves are converging with mobile threat defense platforms to enable processing of sensitive data within hardware-isolated execution environments on consumer-grade smartphones. Financial services institutions in Switzerland and Singapore are piloting these integrations for trading applications. The technology is converging with existing endpoint detection and response workflows, compressing the traditional separation between device security and data protection layers.
Japan's METI cybersecurity guidelines now mandate incident reporting timelines for mobile breaches affecting critical infrastructure operators, tightening accountability beyond voluntary disclosure frameworks. Industrial manufacturers with connected workforce devices face compressed response windows and elevated documentation burdens. Automotive suppliers with German parent companies are extending these requirements to their Japanese subsidiaries through internal compliance matrices.
Healthcare procurement committees are unbundling mobile data protection from bundled EHR security contracts, creating direct vendor relationships for specialized encryption services. This pattern displaces the historical dominance of electronic health record vendors in peripheral security decisions. Hospital systems in the United States are most advanced in this separation, with integrated delivery networks negotiating standalone mobile security service level agreements.
Mobile Data Protection Solutions and Services Market Segmentation
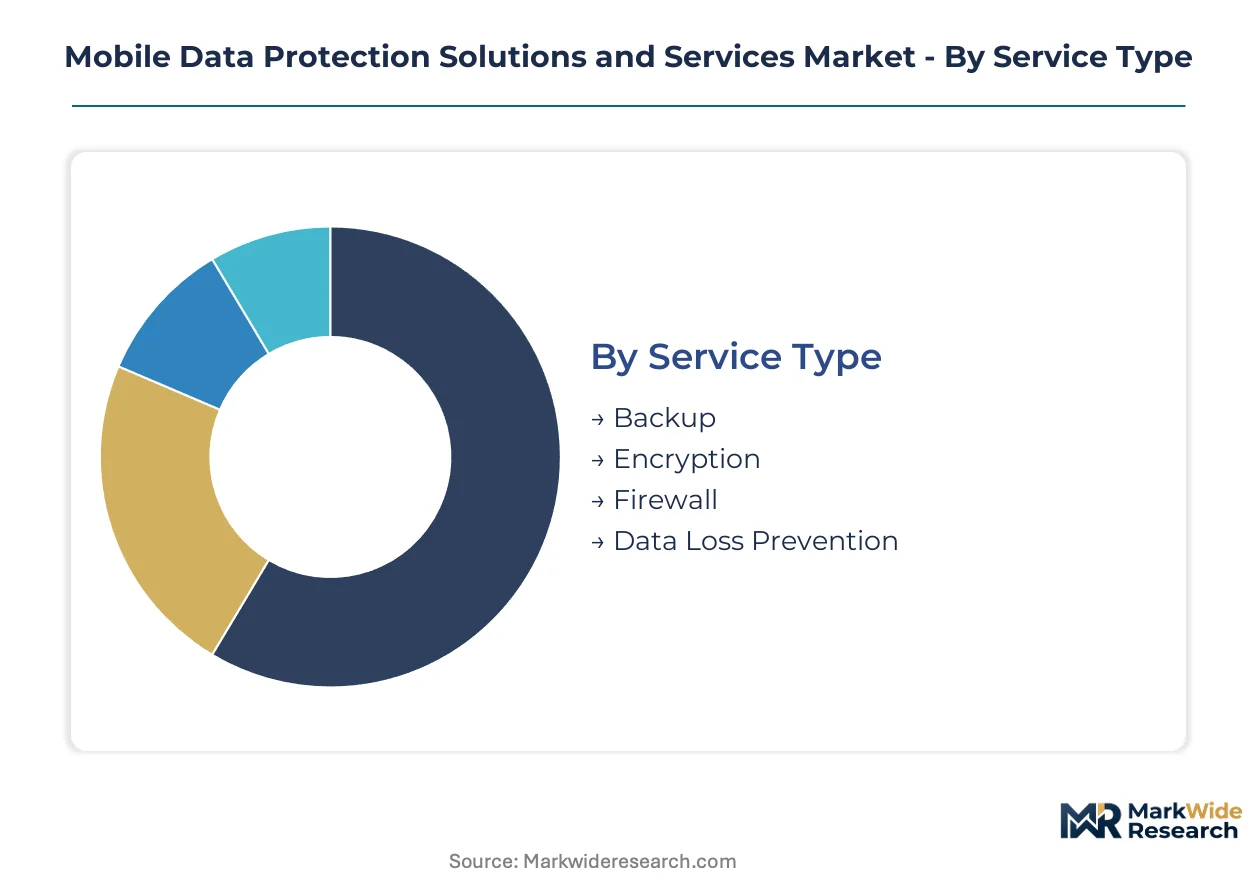
Mobile data protection procurement splits across four structural dimensions that determine pricing tiers, integration complexity, and vendor selection criteria. Each segmentation axis reflects distinct capital deployment patterns and compliance obligations.
Service Type:
Encryption commands the heaviest upfront investment due to algorithm licensing fees and hardware security module integration.
- Encryption:Lattice-based and AES-256 implementations secure data at rest and in transit across device fleets. Financial services in Germany and Switzerland drive demand for quantum-resistant key management systems amid Bundesdatenschutzgesetz amendments.
- Data Loss Prevention:Content inspection and policy enforcement engines monitor data exfiltration across messaging and cloud sync channels. Healthcare systems in the United States prioritize DLP for HIPAA compliance, with procurement committees now negotiating standalone contracts outside EHR bundles.
- Backup:Immutable snapshot retention with cross-jurisdictional key escrow addresses ransomware recovery requirements.
- Firewall:Application-layer traffic filtering on mobile endpoints integrates with zero-trust network access architectures.
Most installed capacity flows through Encryption. Expansion is steepest in Data Loss Prevention.
Deployment Model:
Cloud-based deployments concentrate volume in mid-market enterprises seeking elastic capacity without infrastructure overhead.
- Cloud-based:Managed encryption services with EU-hosted key storage satisfy data sovereignty mandates. Germany, the United Kingdom, and Japan capture disproportionate demand as hybrid work persists and GDPR enforcement tightens residency requirements.
- SaaS:Native integration with productivity suites enables seamless policy enforcement across BYOD fleets. Large enterprises favor this model for reduced operational burden and continuous feature updates.
- On-premises:Air-gapped key management systems serve defense contractors and critical infrastructure operators with classified data requirements.
- Hybrid:Split architectures maintain sensitive operations on-premises while offloading routine backup to cloud tiers.
Cloud-based deployments hold the largest active footprint. SaaS is climbing the fastest among multinational enterprises.
End User:
Large enterprises absorb the steepest per-seat costs due to custom integration requirements and dedicated support tiers.
- Large Enterprises:Global device fleets spanning multiple jurisdictions require centralized policy orchestration with localized key storage. These buyers negotiate outcome-based managed detection contracts with incident-response guarantees.
- Healthcare:HIPAA mandates and FDA guidance on mobile medical applications drive specialized procurement for encryption and access logging. Hospital systems unbundle mobile security from EHR vendor contracts to establish direct vendor relationships.
- Government:Classified mobility programs demand FIPS 140-2 validated modules and domestic supply chain verification.
- SMEs:Consolidated endpoint and mobile data protection licensing reduces vendor sprawl and administrative overhead.
Healthcare and government segments together anchor specialized solution development. Large enterprises represent the steepest expansion trajectory for premium zero-trust architectures.
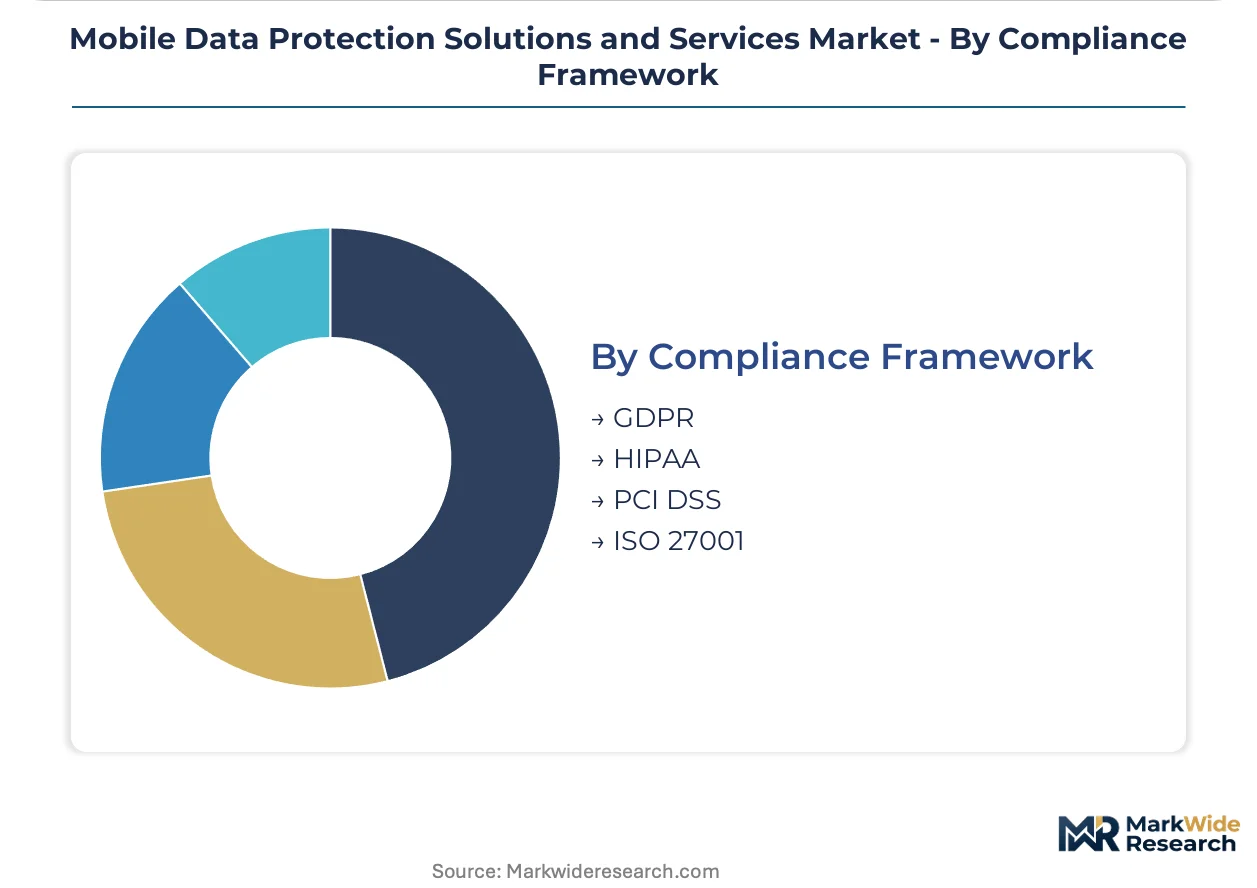
Compliance Framework:
GDPR-aligned solutions command pricing premiums due to algorithmic accountability requirements under the EU AI Act.
- GDPR:Automated threat detection systems require documented decision logic for explainable AI compliance. European financial services institutions prioritize platforms with built-in audit trails and data residency controls.
- HIPAA:Access logging, encryption at rest, and breach notification protocols shape healthcare mobile security procurement. The US FDA co-regulates mobile medical applications with data protection implications.
- PCI DSS:Cardholder data environment segmentation on mobile point-of-sale devices drives containerization adoption.
- ISO 27001:Certification-aligned solutions appeal to enterprises seeking auditor-recognized security management frameworks.
GDPR and HIPAA together dominate vendor certification roadmaps. PCI DSS is gaining share fastest among retail and hospitality mobile payment deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cybersecurity talent clusters in the United States, Germany, and Japan anchor mobile data protection demand, with hybrid workforces and quantum-resistant cryptography mandates driving procurement across these concentrated markets.
United States
Healthcare systems and financial services firms dominate enterprise procurement, with HIPAA and FDA mobile medical application guidance tightening encryption requirements. Hospital networks in Boston and New York Metro negotiate standalone mobile security service level agreements outside EHR vendor bundles. Federal agencies demand FIPS 140-2 validated modules for classified mobility programs.
Germany
Bundesdatenschutzgesetz amendments create procurement preference for EU-hosted encryption key management services. Automotive suppliers in Baden-Württemberg extend German parent company compliance matrices to Japanese subsidiaries. Munich and Frankfurt financial institutions prioritize quantum-resistant key management systems amid data sovereignty enforcement.
United Kingdom
Financial services buyers shift from seat-based to incident-response-guaranteed pricing models for managed detection contracts. London's fintech cluster drives demand for explainable AI security platforms under EU AI Act algorithmic accountability requirements. GDPR enforcement tightens data residency mandates across distributed workforces.
Japan
METI cybersecurity guidelines mandate incident reporting timelines for mobile breaches affecting critical infrastructure operators. Automotive suppliers and industrial manufacturers in Nagoya and Osaka face compressed response windows. 5G network slicing integration enables carrier-grade security guarantees for industrial IoT deployments in the Tokyo-Yokohama corridor.
Switzerland
Confidential computing enclave pilots for trading applications concentrate in Zurich and Geneva financial services institutions. Banking secrecy traditions align with hardware-isolated execution environments on consumer-grade smartphones. Swissmedic regulatory frameworks influence healthcare mobile data protection procurement for pharmaceutical field forces.
Mobile Data Protection Solutions and Services Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light cloud-native platform providers across deployment models, with the market consolidating around three tiers. Premium zero-trust architects command enterprise budgets through continuous authentication protocols. Mid-market consolidators bundle endpoint and mobile licensing for administrative efficiency. Open-source cryptographic library distributors undercut proprietary algorithm pricing. Dominant competitive moves include strategic partnerships for 5G network slicing integration and geographic expansion into data sovereignty-sensitive jurisdictions.
Within the cloud-native platform tier, Microsoft Corporation and Palo Alto Networks exemplify divergent positioning strategies. Microsoft leverages its productivity suite integration to anchor enterprise SaaS deployment, while Palo Alto Networks occupies a position emphasizing AI-powered threat detection across mobile attack surfaces. Sophos represents the mid-market consolidation archetype, with its licensing model reducing vendor sprawl for distributed workforces. These three anchors illustrate how vendor selection increasingly hinges on existing infrastructure alignment rather than standalone capability evaluation.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| Microsoft Corporation |
| Broadcom Inc. |
| Hewlett Packard Enterprise Company |
| Trend Micro Incorporated |
| Cisco Systems |
| Palo Alto Networks |
| Sophos |
| Veritas Technologies |
| Others |
Supply & Pricing Matrix
Zero-trust architecture premiums versus commodity endpoint encryption creates a stark bifurcation in both supplier margins and procurement patterns, with German financial institutions paying substantial uplifts for quantum-resistant key management while mid-market buyers consolidate around bundled SaaS tiers. This divergence compresses pricing power for undifferentiated encryption vendors while rewarding suppliers with NIST-validated post-quantum libraries and EU-hosted infrastructure.
Pricing Analysis
Bundled endpoint-mobile security suites compete against unbundled specialized encryption services, with SaaS-tiered subscription models dominating cloud deployments and per-device royalty structures governing post-quantum cryptographic implementations. Price differentiation hinges on certification grade—FIPS 140-2 validation commands substantial premiums over standard AES-256 offerings—and geographic delivery cost for EU data residency compliance. Pricing pressure stems from open-source cryptographic library availability eroding proprietary algorithm margins. Healthcare procurement committees demonstrate highest price sensitivity as they unbundle from EHR vendor contracts, while classified government mobility programs show lowest sensitivity due to domestic supply chain mandates.
Supply Chain Analysis
Certification and qualification gating concentrates supply among vendors with NIST validation and FIPS 140-2 accreditation, creating barriers for emerging cryptographic providers. Hardware security module production centers on the United States, Germany, and Taiwan, with lattice-based algorithm implementation expertise concentrated among academic and national laboratory researchers in the United States and Switzerland. Raw material dependencies include specialized semiconductor substrates for secure enclaves, rare earth elements for hardware tamper resistance, and qualified fab capacity for cryptographic processors. Single-source vulnerability runs through narrow root certificate authority bases. Distribution runs through direct enterprise sales for large deployments and MSP channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in quantum-resistant service tiers and outcome-based managed detection contracts, with cost-down pressure easing as post-quantum standardization reduces parallel system maintenance burdens.
For Market Incumbents: Anchor defensive positioning through backward integration into hardware security module manufacturing and exclusive partnerships with NIST-approved post-quantum algorithm licensors. Consolidate mid-market share by acquiring regional MSPs with healthcare and legal sector specialization. Threat from open-source cryptographic libraries demands certification investment as differentiation lever. For New Entrants and Emerging Players: EU AI Act algorithmic accountability requirements in Germany and the United Kingdom open a window for explainable AI security platforms with built-in audit trail capabilities. Target healthcare systems in the United States unbundling mobile security from EHR contracts, and Japanese industrial manufacturers facing METI-mandated incident reporting timelines. Go-to-market angle: containerized work profile solutions for BYOD-heavy professional services firms. For Investors and Strategic Acquirers: Consolidation pressure builds where post-quantum cryptography talent scarcity intersects with regulatory compliance deadlines. Long-term viability favors vendors with hybrid cloud-on-premises orchestration capabilities and established relationships with certificate authorities. Acquisition target archetype: mid-tier endpoint security vendors with healthcare sector penetration but lacking zero-trust architecture depth. Signal to watch: Bundesdatenschutzgesetz enforcement actions triggering procurement preference shifts toward EU-hosted key management.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Microsoft 365 embedding captures enterprise SaaS procurement committees. |
| Strategic Partnership | 5G carrier slicing alliances enable industrial IoT security guarantees in Japan. |
| Acquisition of Specialist Firm | Lattice-based cryptography boutiques address talent scarcity in post-quantum migration. |
| Geographic Expansion | EU-hosted key management services satisfy German data sovereignty enforcement. |
| Product Launch | Confidential computing enclaves for consumer smartphones target Swiss financial services pilots. |
Research Methodology
Multiple input streams—primary interviews with CISOs and IT procurement officers, technical discussions with platform engineers and channel partners, and secondary validation against SEC filings and hyperscaler security capex disclosures—were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed security vendor executives, healthcare system biomedical engineers, and financial services regulatory compliance leads. Secondary sources included FDA mobile medical application guidance documents, EU AI Act draft provisions, METI cybersecurity guideline releases, and hospital GPO contract databases.
Cross-referencing historical deployment patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment model, organization size, vertical industry, compliance framework alignment, and regional regulatory cluster. CAGRs were derived from installation base growth rates and average revenue per user trajectories. Industry-specific forecast inputs included post-quantum cryptography standardization timelines and data sovereignty enforcement intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated quantum computing breakthroughs or sudden certificate authority consolidation. Forecasts reflect documented assumptions regarding hybrid work persistence and regulatory timeline adherence. A model refresh is warranted upon material change in NIST post-quantum algorithm adoption schedules or EU AI Act final implementation dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Remote Access Management Market
Security Software
North America Video Management System Market
Security Software
Sound Masking Systems Market
Security Software
Device Vulnerability Management Market
Security Software
Global Mobile Identification Market
Security Software
Door Phone Market
Security Software
Video Intercom Devices Market
Security Software
Source Code Escrow Market
Security Software
Global Secure Access Service Edge Market
Security Software
Decentralized Identity Software Market
Security Software
Confidential Computing Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
VPN Software Market
Security Software
Global Data Masking Market
Security Software
Global IMSI Catcher Market