
 Mobile Identity Management Market | 2026-2036
Mobile Identity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Identity Management Market Insights
Enterprise demand is rotating from large financial institutions toward mid-market retailers and healthcare providers seeking cloud-native identity platforms. Okta leverages extensive API integrations to anchor its position among SaaS-native enterprises. IBM Corporation sustains credibility in regulated sectors through deep mainframe security heritage and hybrid deployment expertise. Ping Identity differentiates via passwordless authentication specialization for developer-centric organizations.
Mobile identity management encompasses the technologies, policies, and processes that authenticate, authorize, and administer digital identities across smartphones, tablets, and wearable endpoints, typically incorporating cryptographic key storage, secure enclaves, and FIDO2/WebAuthn protocols to bind credentials to hardware-backed trust anchors. Its primary commercial purpose is to eliminate password-dependent breaches while enabling seamless, phishing-resistant user access across distributed cloud applications. Biometric authentication commands the dominant share of technology spending as facial and fingerprint recognition mature into default mobile operating system capabilities. Cloud-based deployment is expanding fastest among segments as organizations abandon capital-intensive on-premises identity infrastructure for elastic consumption models. Identity verification solutions capture concentrated margin pools due to document liveness detection complexity and regulatory Know Your Customer mandates.
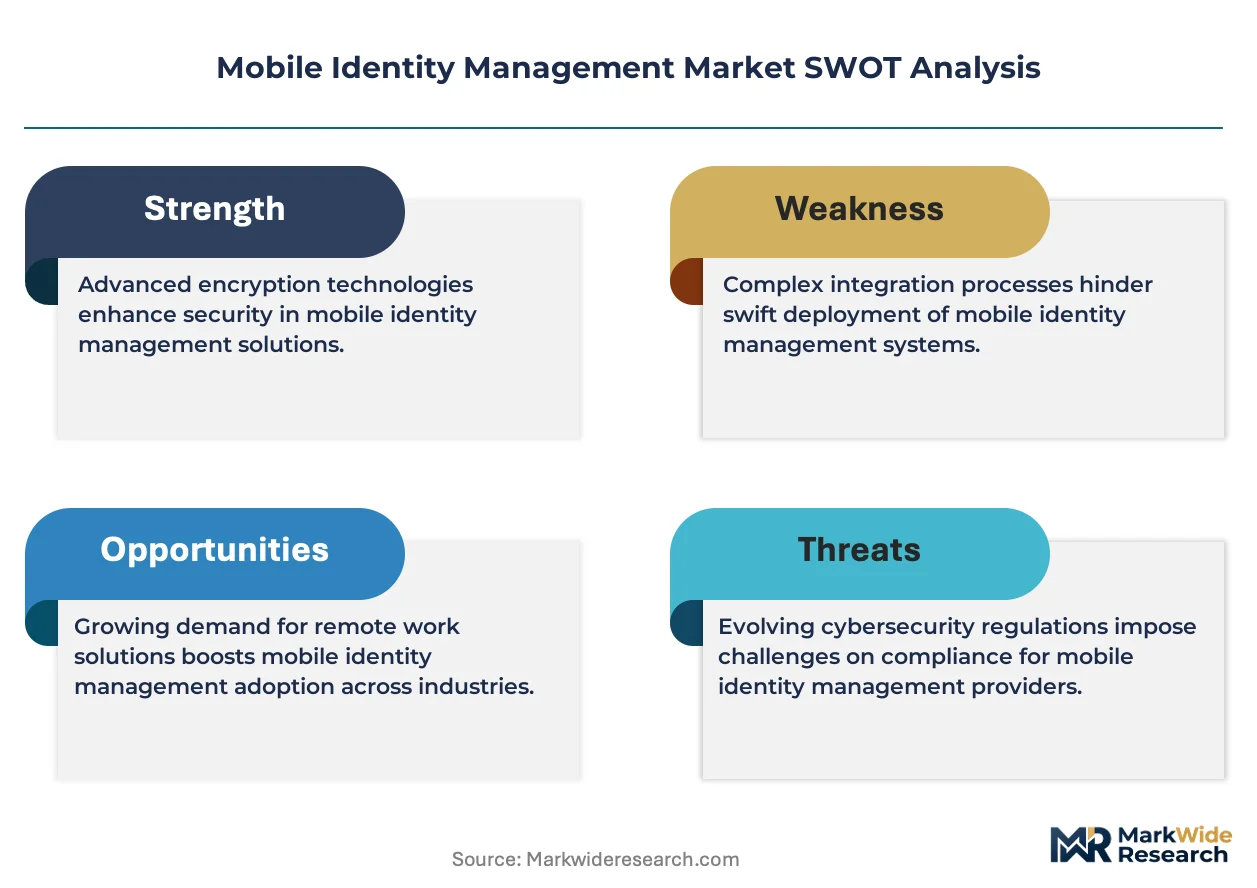
The EU AI Act imposes strict conformity requirements on automated biometric identification systems, compelling vendors to redesign algorithmic transparency and human oversight mechanisms. EMA guidelines on digital health credentials and GDPR data minimization principles further constrain how mobile identity data traverses third-party processors. ISO/IEC 30107 presentation attack detection standards and FIDO Alliance certifications shape product interoperability benchmarks across European procurement frameworks. Stakeholders must monitor convergence between decentralized identity standards and central bank digital currency authentication requirements as wallet architectures reshape vendor competitive boundaries.
Market Dynamics
Financial institutions are abandoning password-dependent authentication architectures in favor of biometric-bound cryptographic credentials, compressing procurement cycles for FIDO2-compliant infrastructure across retail banking and wealth management segments.
Growth Catalysts
- EU AI Act Conformity Mandates:Automated biometric identification systems must embed algorithmic transparency and human oversight mechanisms, compelling financial services firms to upgrade legacy identity stacks.
- Cloud-Native Identity Platforms:Mid-market retailers and healthcare providers are abandoning capital-intensive on-premises infrastructure for elastic consumption models that scale with transaction volumes.
- Document Liveness Detection:Regulatory Know Your Customer mandates in Germany, France, and the United Kingdom are concentrating margin pools in identity verification solutions with advanced presentation attack detection.
Market Restraints
- GDPR Data Minimization Friction:Stringent constraints on how mobile identity data traverses third-party processors increase architectural complexity and vendor liability exposure.
- ISO/IEC 30107 Certification Bottlenecks:Presentation attack detection standards create extended validation timelines that delay product commercialization.
- Biometric Algorithm Supply Concentration:Specialized facial and fingerprint recognition modules depend on concentrated semiconductor foundry capacity in East Asian manufacturing hubs.
Strategic Opportunities
- Decentralized Identity-Wallet Convergence:Central bank digital currency authentication requirements are reshaping competitive boundaries for vendors with hardware-backed trust anchor expertise.
- Healthcare Digital Credential Expansion:EMA guidelines on digital health credentials create compliant demand for privacy-preserving verification architectures in clinical settings.
- FIDO Alliance Certification Arbitrage:European procurement frameworks increasingly mandate FIDO2/WebAuthn interoperability, advantaging early-certified vendors in public sector tenders.
Industry Challenges
- Cryptographic Key Management Talent Scarcity:Secure enclave engineering and hardware security module integration require specialized skills that outpace available workforce supply.
- Hybrid Deployment Integration Complexity:Mainframe heritage systems in regulated sectors resist seamless connection with cloud-native identity platforms, extending implementation timelines.
- Cross-Border Regulatory Fragmentation:Divergent national implementations of GDPR and EU AI Act create compliance overhead for vendors serving multiple European jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Identity Management Market |
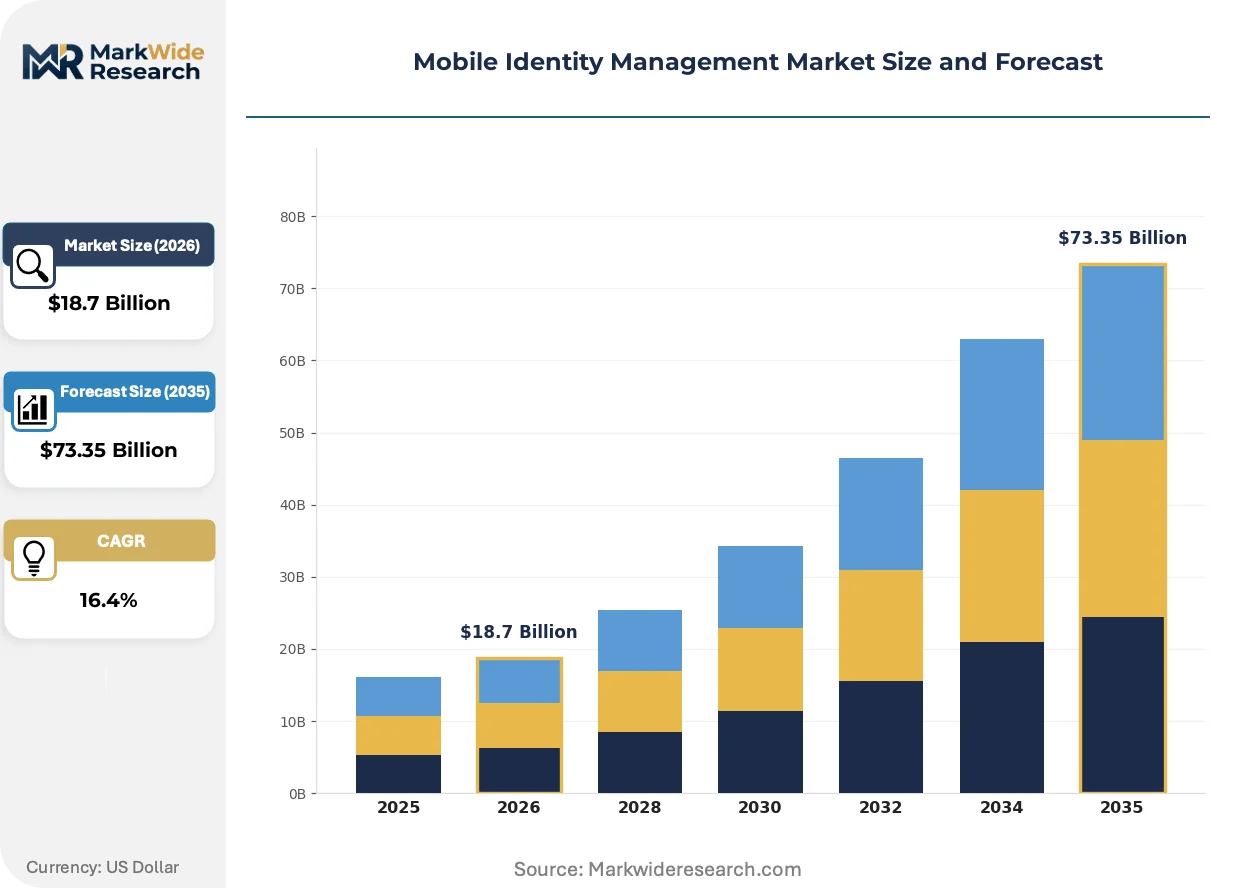
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric Authentication, Password Management, Multi-Factor Authentication, Blockchain-Based Solutions Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services End User: Financial Institutions, Retailers, Government Agencies, Healthcare Providers Solution: Access Control, Identity Verification, Risk Management, User Provisioning |
| Companies Covered | Okta, IBM Corporation, Microsoft Corporation, Ping Identity, Oracle, Thales Group, IDEMIA, OneLogin, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Identity Management Market Trends and Innovations
Passwordless authentication architectures are displacing legacy credential systems across enterprise mobility deployments, with biometric-bound FIDO2 protocols now standard in mobile operating system roadmaps.
Passkey implementations are displacing SMS-based one-time passwords and hardware token dependencies in consumer-facing financial applications. Major retail banks in Germany and the United Kingdom are mandating passkey enrollment for high-value transaction authorization. This displacement is compressing revenue for legacy multi-factor authentication vendors while expanding margin capture for platform-native biometric providers.
EMA guidelines on digital health credentials are forcing healthcare identity vendors to redesign data architectures for GDPR-compliant patient consent management. Clinical trial sponsors must now demonstrate cryptographic provenance for participant identity verification. Pharmaceutical companies operating across France, Germany, and Switzerland are consolidating vendor relationships to reduce cross-border compliance fragmentation.
Buyer procurement patterns are rotating from perpetual license models toward consumption-based identity verification pricing. Mid-market retailers in the United Kingdom are unbundling after-sales implementation services from core platform subscriptions. This behavioral shift is most visible in grocery and pharmacy chains seeking elastic capacity for seasonal customer onboarding spikes without committed infrastructure spend.
Mobile Identity Management Market Segmentation
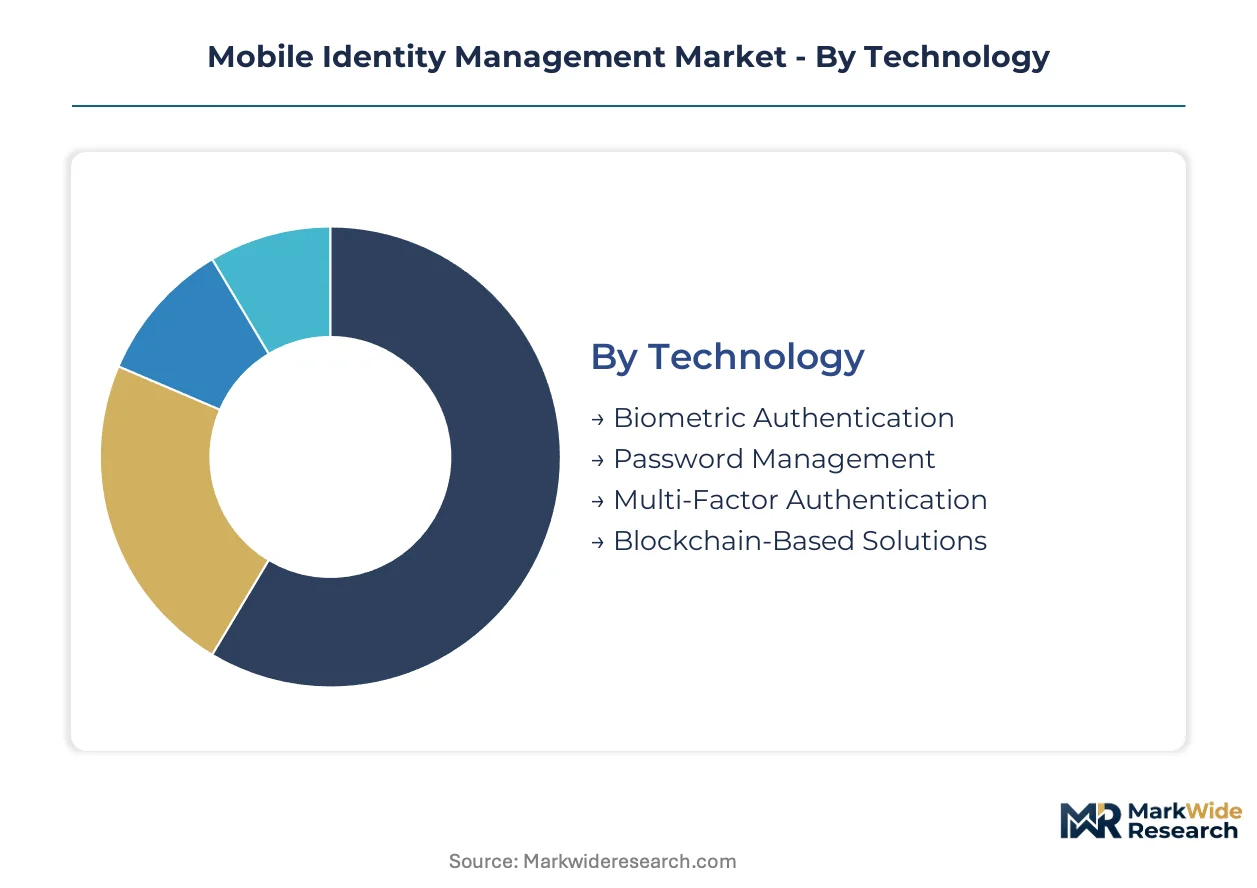
Mobile identity management architectures diverge sharply across deployment topologies and regulatory exposure profiles. Technology selection determines cryptographic trust anchor implementation, while end-user verticals impose distinct compliance burdens that reshape vendor competitive boundaries.
Technology:
Biometric authentication dominates domestic procurement across German and French banking sectors, while blockchain-based solutions concentrate in cross-border digital credential pilots.
- Biometric Authentication:Facial and fingerprint recognition modules leverage hardware-backed secure enclaves in iOS and Android operating systems. Demand concentrates in German retail banking and UK wealth management segments driven by FIDO2 compliance mandates and PSD2 strong customer authentication requirements.
- Password Management:Enterprise credential vaults with automated rotation policies address legacy system interoperability in hybrid deployments. French government agencies and UK National Health Service trusts prioritize these solutions for workforce access consolidation amid civil service digitization programs.
- Multi-Factor Authentication:TOTP and push notification systems bridge transitional architectures for mid-market retailers.
- Blockchain-Based Solutions:Self-sovereign identity frameworks pilot across EMA digital health credential programs and ECB central bank digital currency wallet trials.
Biometric authentication holds the largest share; momentum sits with blockchain-based solutions.
Deployment:
Cost tier stratification separates capital-intensive on-premises estates from consumption-elastic cloud alternatives, with hybrid configurations commanding premium pricing for regulated workloads.
- On-Premises:Dedicated identity infrastructure within enterprise data centers satisfies GDPR data residency requirements for sensitive biometric templates. Swiss private banks and German automotive manufacturers maintain these deployments for air-gapped cryptographic key generation and hardware security module integration.
- Cloud-Based:Elastic identity platforms scale transaction volumes without committed infrastructure spend. UK grocery chains and French pharmacy networks adopt these models for seasonal customer onboarding spikes, paying per verification event rather than provisioning peak capacity.
- Hybrid Solutions:Split architectures anchor credential roots on-premises while federating authentication to cloud edge nodes.
- Managed Services:Outsourced identity operations reduce specialist staffing burdens for mid-market healthcare providers.
Cloud-based deployment is climbing fastest; on-premises retains the revenue base among Tier-1 financial institutions.
End User:
Application intensity varies by sector breach exposure and regulatory fine schedules, with financial services and healthcare commanding disproportionate technology investment per employee.
- Financial Institutions:Retail banks, wealth managers, and insurance carriers deploy FIDO2-bound biometric credentials to eliminate phishing vectors. German Sparkassen and UK building societies compress procurement cycles for passwordless authentication as the EU AI Act conformity deadlines approach.
- Healthcare Providers:Hospital systems and clinical trial sponsors implement privacy-preserving verification for EMA digital health credential compliance. Pharmaceutical companies operating across France, Germany, and Switzerland consolidate vendor relationships to reduce cross-border data governance fragmentation.
- Retailers:Mid-market chains seek elastic identity verification for seasonal transaction spikes.
- Government Agencies:National identity schemes and tax authorities mandate highest-assurance authentication for citizen service portals.
Financial institutions contribute the dominant revenue share; healthcare providers are expanding most quickly.
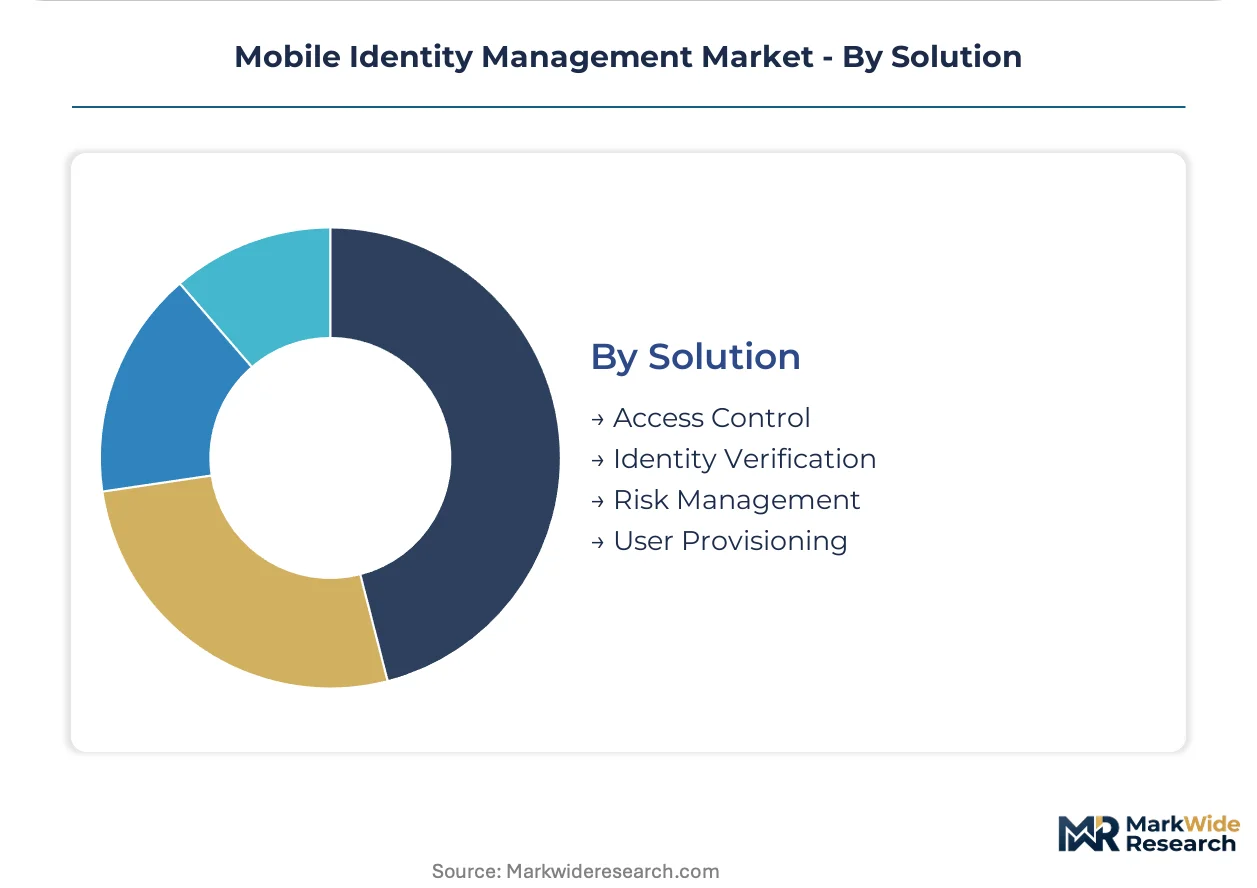
Solution:
Margin concentration aligns with technical complexity, where identity verification solutions with document liveness detection capture premium pricing against commoditized access control modules.
- Identity Verification:Document-centric onboarding with presentation attack detection satisfies Know Your Customer mandates. UK fintechs and German neobanks concentrate procurement here, driven by BaFin and FCA regulatory enforcement against synthetic identity fraud.
- Access Control:Policy enforcement engines govern resource authorization across cloud and on-premises applications. French energy utilities and German industrial conglomerates prioritize these solutions for operational technology segmentation and critical infrastructure protection.
- Risk Management:Behavioral biometrics and transaction anomaly detection reduce account takeover losses.
- User Provisioning:Automated lifecycle management accelerates workforce onboarding and offboarding workflows.
Identity verification commands the steepest margin expansion; access control provides the installed base volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mobile identity vendors export FIDO2-compliant authentication infrastructure to financial institutions across France and the United Kingdom, establishing the Rhine-Ruhr corridor as Europe's primary trade-flow hub for biometric security systems.
Germany
BaFin enforcement against synthetic identity fraud drives demand for document liveness detection among Sparkassen and neobanks. The EU AI Act mandates algorithmic transparency in automated biometric systems, compelling vendors to embed human oversight mechanisms. Frankfurt's fintech cluster concentrates procurement cycles for passwordless authentication platforms as conformity deadlines approach.
France
ANSM guidelines on digital health credentials accelerate privacy-preserving verification architectures for pharmaceutical clinical trials. CNIL interprets GDPR data minimization principles strictly for mobile identity data traversing third-party processors. Paris-based hospital systems and Lyon pharmaceutical sponsors consolidate vendor relationships to reduce cross-border compliance fragmentation.
United Kingdom
FCA regulatory pressure against account takeover losses compresses procurement timelines for biometric-bound credentials at retail banks and building societies. The UK National Health Service digitization programs prioritize workforce access consolidation through enterprise credential vaults. London fintechs and Manchester grocery chains adopt consumption-based pricing for seasonal customer onboarding spikes.
Switzerland
Swissmedic requirements for cryptographic provenance in clinical trial participant verification reshape vendor selection criteria for pharmaceutical sponsors. FINMA guidance on digital banking authentication elevates hardware security module integration standards. Zurich private banks and Basel pharmaceutical headquarters maintain air-gapped deployments for biometric template data residency compliance.
Netherlands
Dutch central bank digital currency pilot programs create demand for hardware-backed trust anchor expertise in wallet architectures. The country's national data protection authority enforces strict cross-border data governance for mobile identity processors. Amsterdam's fintech ecosystem and Eindhoven semiconductor design clusters attract decentralized identity standardization initiatives.
Mobile Identity Management Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native and mainframe-anchored deployment vectors, producing a tiered structure where scale advantages concentrate in platform ecosystems while niche expertise captures regulated vertical premiums. Strategic archetypes include SaaS-native identity platforms, hybrid infrastructure specialists, and hardware security module integrators. Dominant competitive moves encompass API ecosystem expansion and FIDO Alliance certification arbitrage in European public sector tenders.
Within the SaaS-native platform tier, Okta and Ping Identity exemplify archetypes differentiated by developer-centric tooling and passwordless authentication specialization. IBM Corporation occupies a position among hybrid infrastructure specialists leveraging mainframe security heritage for regulated financial services deployments. These three anchors illustrate how vendor competitive boundaries reshape around decentralized identity-wallet convergence and central bank digital currency authentication requirements.
| Leading Market Players |
|---|
| Okta |
| IBM Corporation |
| Microsoft Corporation |
| Ping Identity |
| Oracle |
| Thales Group |
| IDEMIA |
| OneLogin |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
Semiconductor foundry scale economies in East Asian manufacturing hubs concentrate biometric algorithm production among three dominant suppliers, compressing margins for identity verification vendors while elevating price floors for FIDO2-certified hardware security modules. This supply concentration enables tier-one cloud providers to extract volume discounts that mid-market competitors cannot match, forcing pricing stratification across deployment scales.
Pricing Analysis
Next-generation passkey implementations command premium positioning against legacy multi-factor authentication tiers, with FIDO2-certified biometric modules pricing at multiples of TOTP-based transitional systems. Three-tier pricing structure across premium, standard, and economy levels separates hardware-backed secure enclave deployments from software-only authentication and basic password management vaults. Cost compression in mid-market SaaS tiers is intensifying because consumption-based identity verification pricing eliminates committed infrastructure spend. Mid-market retailers and healthcare providers exhibit highest price sensitivity, while Swiss private banks and German automotive manufacturers absorb premium pricing for air-gapped biometric template residency.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for specialized facial recognition semiconductors and hardware security module components. Manufacturing concentration centers on Taiwan, South Korea, and China for secure enclave processors and presentation attack detection sensors. Component dependencies include cryptographic co-processors, biometric sensor arrays, and FIDO2-compliant firmware stacks. Single-source vulnerability in advanced node semiconductor foundry capacity exposes vendors to allocation prioritization by hyperscale cloud customers. Distribution runs through Frankfurt's fintech cluster for European financial institutions and direct OEM integration for cloud-native platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU AI Act conformity deadlines splinter procurement cycles, creating specialized niches for algorithmic transparency tooling and human oversight mechanism integration that incumbent platforms cannot address uniformly.
For Market Incumbents: Compound API ecosystem density to anchor SaaS-native enterprise relationships before decentralized identity standards reshape competitive boundaries. Invest in ISO/IEC 30107 certification acceleration to defend public sector tender positioning against emerging biometric specialists. Vertical integration into hardware security module design mitigates semiconductor foundry allocation risk from cloud hyperscalers. For New Entrants and Emerging Players: FIDO Alliance certification fast-track enables penetration of UK grocery and French pharmacy mid-market segments where consumption-based pricing models displace incumbent perpetual licenses. Target identity verification solutions with document liveness detection for German neobank and UK fintech procurement cycles driven by BaFin and FCA synthetic identity enforcement. Channel partnership with cloud-native platform integrators accelerates enterprise credential vault displacement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native identity platforms serving mid-market healthcare providers with EMA digital health credential compliance requirements. Long-term viability over the coming decade favors vendors with hardware-backed trust anchor expertise positioned for central bank digital currency wallet authentication convergence. Monitor FIDO2 passkey enrollment mandates at major retail banks as inflection indicator for passwordless authentication market tipping.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO Alliance Certification Acceleration | EU AI Act mandates algorithmic transparency for automated biometric identification systems in German banking procurement. |
| Cloud-Native Platform Integration | Mid-market retailers abandon on-premises infrastructure for elastic consumption models scaling with seasonal verification volumes. |
| Hardware Security Module Partnership | Swiss private banks require air-gapped biometric template residency compliant with FINMA digital authentication guidance. |
| Decentralized Identity Standard Development | ECB central bank digital currency pilots reshape competitive boundaries for wallet architecture authentication requirements. |
| Healthcare Credential Compliance Specialization | EMA guidelines on digital health credentials force privacy-preserving verification redesign for pharmaceutical clinical trials. |
Research Methodology
A standing panel of chief information security officers, identity platform engineers, regulatory compliance leads at financial institutions, and healthcare IT procurement managers provided ongoing calibration against secondary validation from FIDO Alliance certification databases, EU AI Act implementation guidance documents, EMA digital health credential frameworks, and SEC filings of listed identity vendors. This primary fieldwork combined with bottom-up and top-down triangulation across deployment model adoption rates and end-user vertical spending patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across technology type, deployment topology, end-user vertical, and solution complexity. CAGRs were derived from annualized growth rate reconciliation between demand-side procurement cycle analysis and supply-side capacity expansion disclosures. Forecast inputs incorporated FIDO2 protocol adoption curves and EU AI Act conformity deadline impacts on replacement demand.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or semiconductor supply normalization would require recalibration. Forecasts reflect documented assumptions regarding biometric algorithm maturation and cloud infrastructure cost trajectories. Specific risks that could revise projections include cross-border regulatory fragmentation diverging from GDPR harmonization and cryptographic key management talent scarcity constraining implementation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Web Content Filtering Market
Security Software
Digital Risk Protection Software Market
Security Software
Europe User Provisioning Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Quantum Key Distribution System Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
US Hardware Encryption Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Global SMS Firewall Market
Security Software
Identity Verification Software Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Global Background Check Software Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Information Rights Management Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
United States Consumer Identity and Access Management Market