
 Data Privacy Software Market | 2026-2036
Data Privacy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Data Privacy Software Market Analysis
Subscription-based financing and usage-metered licensing is reshaping competitive entry in data privacy software, lowering upfront barriers for mid-market buyers. OneTrust leverages extensive pre-built regulatory templates to anchor enterprise deployments across multinational footprints. Securiti specializes in autonomous data intelligence, using AI-driven discovery to differentiate its platform from rules-based competitors. BigID sustains R&D intensity in identity-centric privacy, competing through deep integration with cloud data warehouses.
Data privacy software encompasses consent management, data mapping, subject rights automation, and breach response orchestration delivered through policy engines that enforce legal frameworks at the data-layer level. Its primary purpose is to operationalize legal obligations into technical controls that prevent unauthorized processing, enable audit trails, and reduce regulatory liability. Cloud-based solutions occupy the largest revenue pool as enterprises migrate from on-premises data governance to API-native architectures, while SaaS platforms represent the fastest-expanding segment due to rapid deployment cycles and embedded AI functionality. Hybrid solutions are gaining traction among financial institutions requiring jurisdictional data residency without sacrificing cloud scalability.
The Federal Trade Commission and state attorneys general in the United States, alongside the European Data Protection Board and national supervisory authorities under GDPR, are intensifying enforcement against automated decision-making and cross-border transfers. These regulatory pressures directly expand demand for software that embeds privacy-by-design principles and generates defensible documentation. Stakeholders must monitor whether emerging sector-specific requirements in health AI and financial services create divergent compliance specifications that favor modular, configurable platforms over monolithic suites.
Market Dynamics
The EU AI Act and state-level privacy statutes in the United States are forcing enterprises to automate compliance workflows, compressing deployment cycles and favoring API-native architectures over legacy on-premises systems.
Growth Catalysts
- GDPR Article 35 enforcement:European supervisory authorities mandate data protection impact assessments for high-risk processing, driving demand for automated assessment engines.
- Healthcare AI adoption:Health systems deploy consent management and de-identification tools to operationalize patient data governance at scale.
- Germany's industrial data spaces:Automotive supply chain requirements for sovereign data processing infrastructure concentrate investment in localized privacy stacks.
Market Restraints
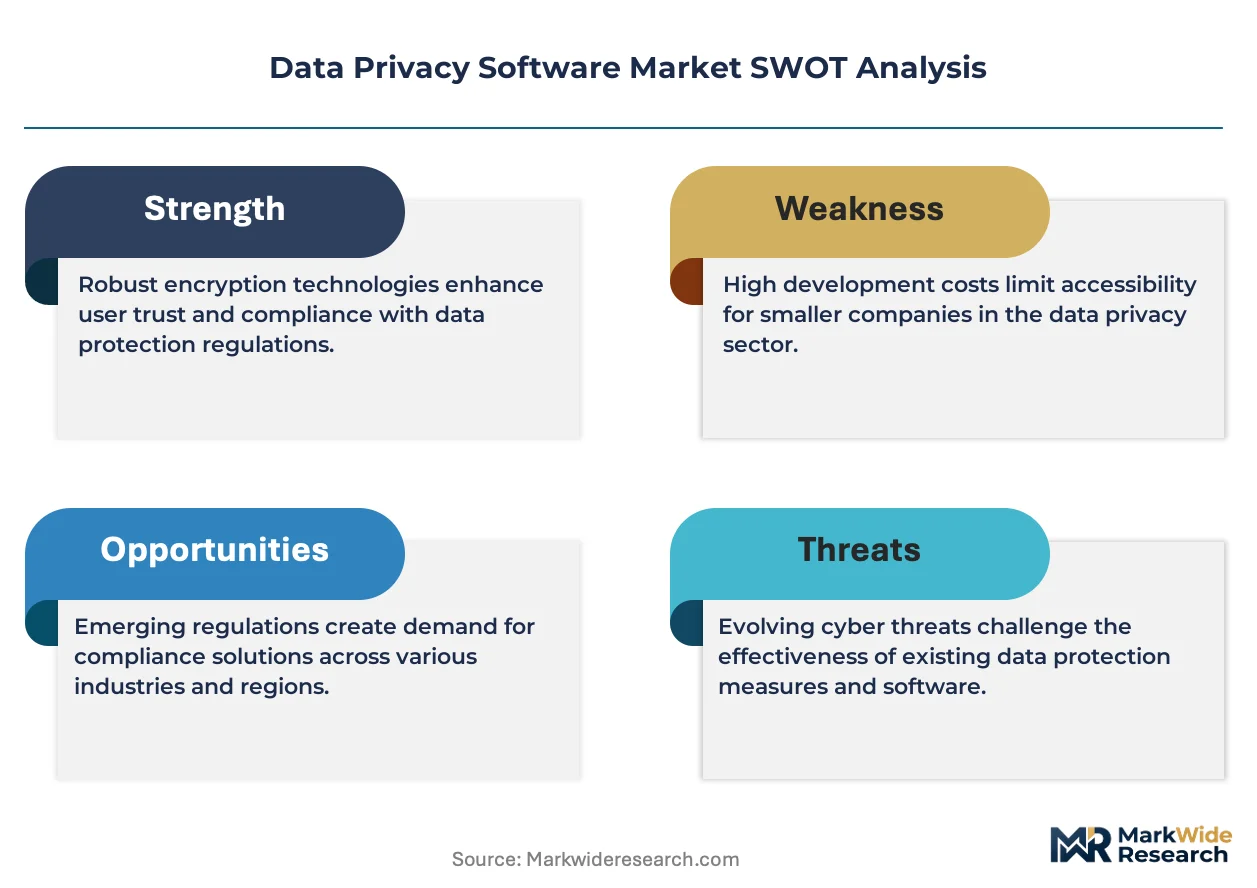
- Cloud infrastructure concentration:Hyperscaler dominance in compute and storage creates vendor lock-in risk for privacy software deployments.
- Cross-border transfer friction:Schrems II invalidation of Privacy Shield mechanisms forces costly contractual and technical safeguards for EU-US data flows.
- Technical debt in legacy systems:Mainframe and on-premise data warehouses resist API-native privacy control integration without substantial middleware investment.
Strategic Opportunities
- Mid-market penetration:Subscription-based financing and usage-metered licensing lower upfront barriers for buyers outside the Fortune 500.
- Embedded AI functionality:Convergence of autonomous data discovery with natural language processing enables real-time policy enforcement without rules-based configuration.
- Sector-specific modules:Financial services institutions seek hybrid solutions balancing jurisdictional data residency with cloud scalability.
Industry Challenges
- Privacy engineering talent scarcity:Shortage of professionals combining legal framework expertise with data architecture skills constrains implementation velocity.
- Multi-jurisdictional compliance complexity:Divergent specifications between health AI and financial services regulations favor modular platforms but increase integration overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Privacy Software Market |
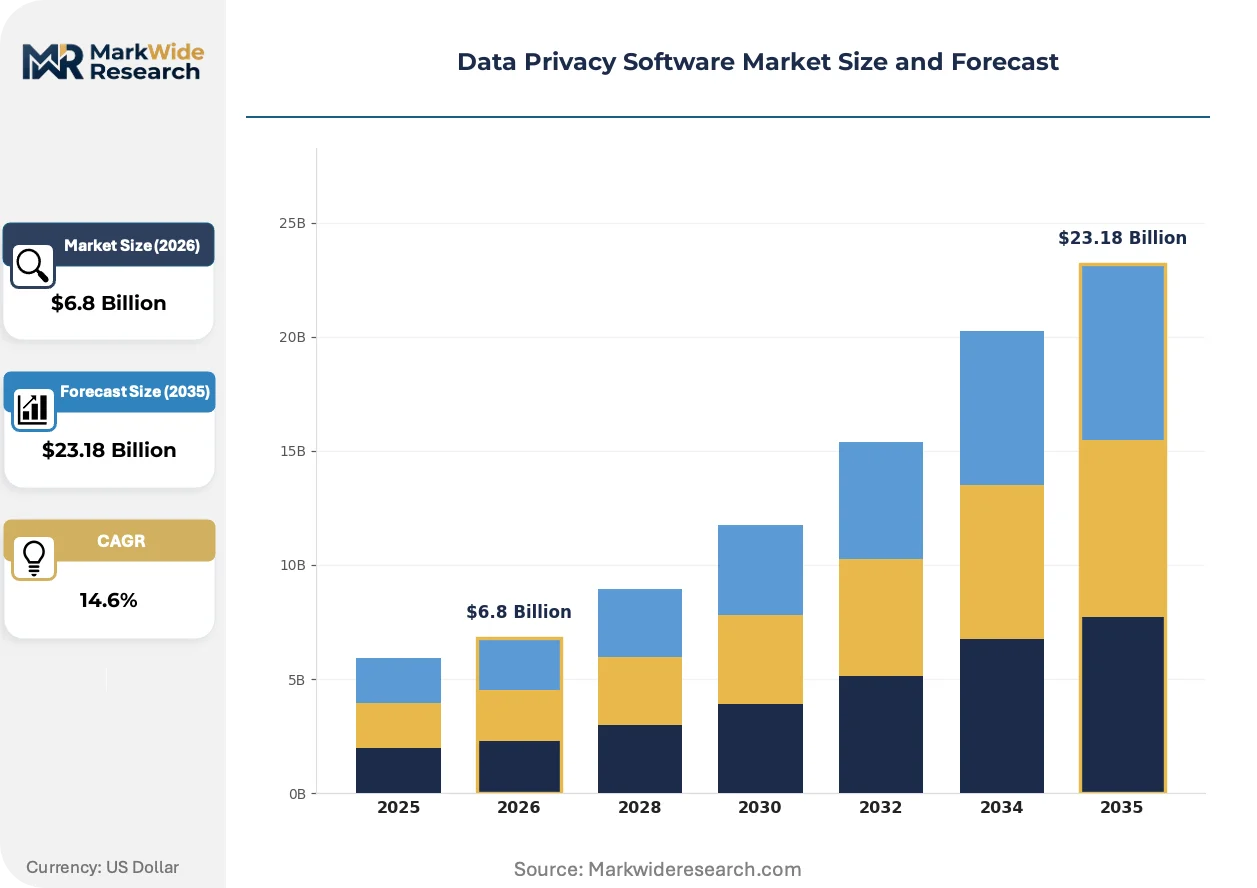
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, SaaS Platforms End User: Healthcare Organizations, Financial Institutions, E-Commerce Platforms, Government Agencies Deployment Model: Public Cloud, Private Cloud, Multi-Cloud Environment, Community Cloud Compliance Focus: GDPR Compliance, HIPAA Compliance, CCPA Compliance, ISO Standards |
| Companies Covered | OneTrust, Securiti, BigID, TrustArc, AvePoint, Exterro, SAP, Osano, Experian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Privacy Software Market Emerging Trajectories
Artificial intelligence is digitizing core privacy functions, regulatory enforcement is hardening technical requirements, and buyer procurement patterns are favoring composable over monolithic platforms.
Autonomous data intelligence is digitizing discovery and classification workflows previously dependent on manual data steward intervention. Financial services and healthcare organizations deploy these systems to map shadow data across multi-cloud environments. The technology is digitizing compliance documentation, collapsing audit preparation from quarterly cycles to continuous monitoring.
The EU AI Act's risk-based classification system mandates algorithmic transparency and human oversight for high-risk automated decision-making. European Data Protection Board guidance extends these obligations to profiling and scoring systems. Germany's automotive sector responds by embedding privacy-by-design principles into supply chain data exchange protocols.
Enterprise buyers now unbundle privacy suites, procuring consent management, subject rights automation, and breach response as separate best-of-breed components. Systems integrators and cloud marketplaces displace direct vendor relationships as primary acquisition channels. This pattern concentrates in the United States, where mid-market buyers prioritize rapid deployment over comprehensive feature coverage.
Data Privacy Software Market Segmentation
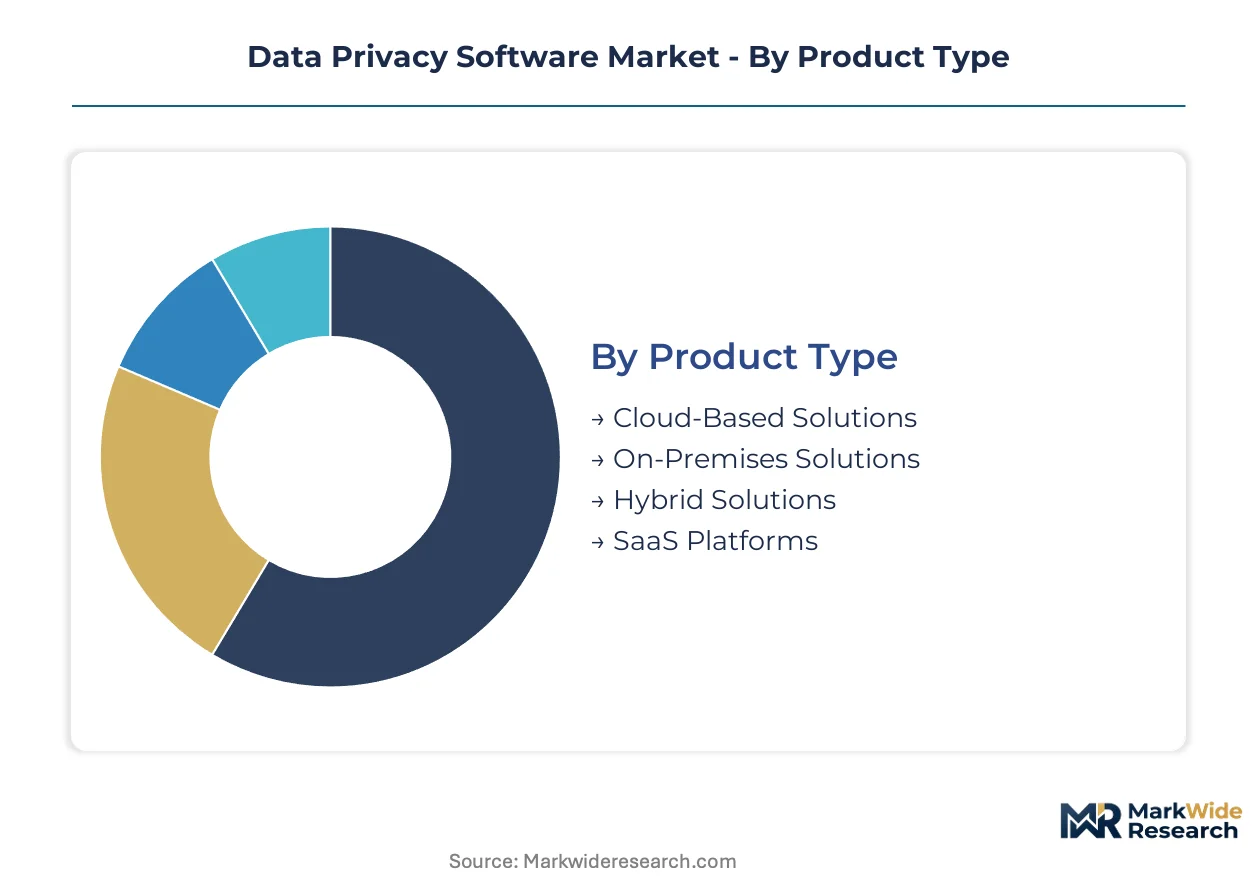
Data privacy software vendors compete across four distinct segmentation axes that determine procurement patterns, implementation complexity, and renewal economics. Deployment architecture and compliance scope drive the longest sales cycles, while end-user verticals and product formats shape pricing power and expansion velocity.
Product Type:
SaaS platforms turn over fastest with monthly subscription adjustments, while on-premises solutions lock in multi-year refresh cycles due to capital approval processes and infrastructure dependencies.
- Cloud-Based Solutions:API-native architectures enable rapid provisioning across distributed data estates. Demand concentrates among multinational enterprises in Germany and France seeking centralized policy enforcement without regional infrastructure buildout.
- SaaS Platforms:Embedded AI functionality accelerates deployment timelines from quarters to weeks. Mid-market buyers in the United States and United Kingdom favor metered licensing that scales with data volume rather than fixed enterprise contracts.
- Hybrid Solutions:Financial institutions in Switzerland and Singapore deploy these to satisfy jurisdictional residency mandates while retaining cloud elasticity for non-sensitive workloads.
- On-Premises Solutions:Legacy data centers in regulated industries resist migration due to mainframe integration requirements and internal security certification protocols.
Cloud-based solutions dominate installed base. SaaS platforms are where expansion concentrates.
End User:
Healthcare organizations and financial institutions anchor premium pricing tiers due to breach liability exposure, while government agencies and e-commerce platforms operate under tighter procurement constraints.
- Healthcare Organizations:Consent management and de-identification tools operationalize patient data governance at scale. United States health systems under HIPAA and emerging state health AI statutes drive fastest segment expansion.
- Financial Institutions:Subject rights automation and audit trail generation satisfy SEC and ECB supervisory expectations. Swiss and German banks invest heavily in hybrid deployments balancing BaFin guidance with cloud efficiency.
- E-Commerce Platforms:Cross-border transaction volumes force real-time consent orchestration across GDPR, LGPD, and PIPEDA jurisdictions.
- Government Agencies:Sovereign data processing requirements in France, Germany, and India favor on-premises or community cloud architectures with domestic encryption key custody.
Financial institutions dominate installed base. Healthcare organizations are where expansion concentrates.
Deployment Model:
Public cloud deployments compress implementation timelines to weeks, while private and community cloud configurations extend provisioning cycles due to security accreditation and dedicated infrastructure commissioning.
- Public Cloud:Shared infrastructure economics enable rapid scaling for mid-market buyers without dedicated security teams. United States and United Kingdom enterprises lead adoption despite Schrems II transfer complexity.
- Multi-Cloud Environment:Distributed policy enforcement across AWS, Azure, and GCP prevents vendor lock-in. German automotive supply chains deploy these architectures to satisfy industrial data space requirements.
- Private Cloud:Dedicated tenancy satisfies financial services regulators in Switzerland and Singapore demanding audit access to physical infrastructure.
- Community Cloud:Sector-specific instances serve healthcare consortiums in the Netherlands and government federations in France with shared compliance certification.
Public cloud dominates installed base. Multi-cloud environment is where expansion concentrates.
Compliance Focus:
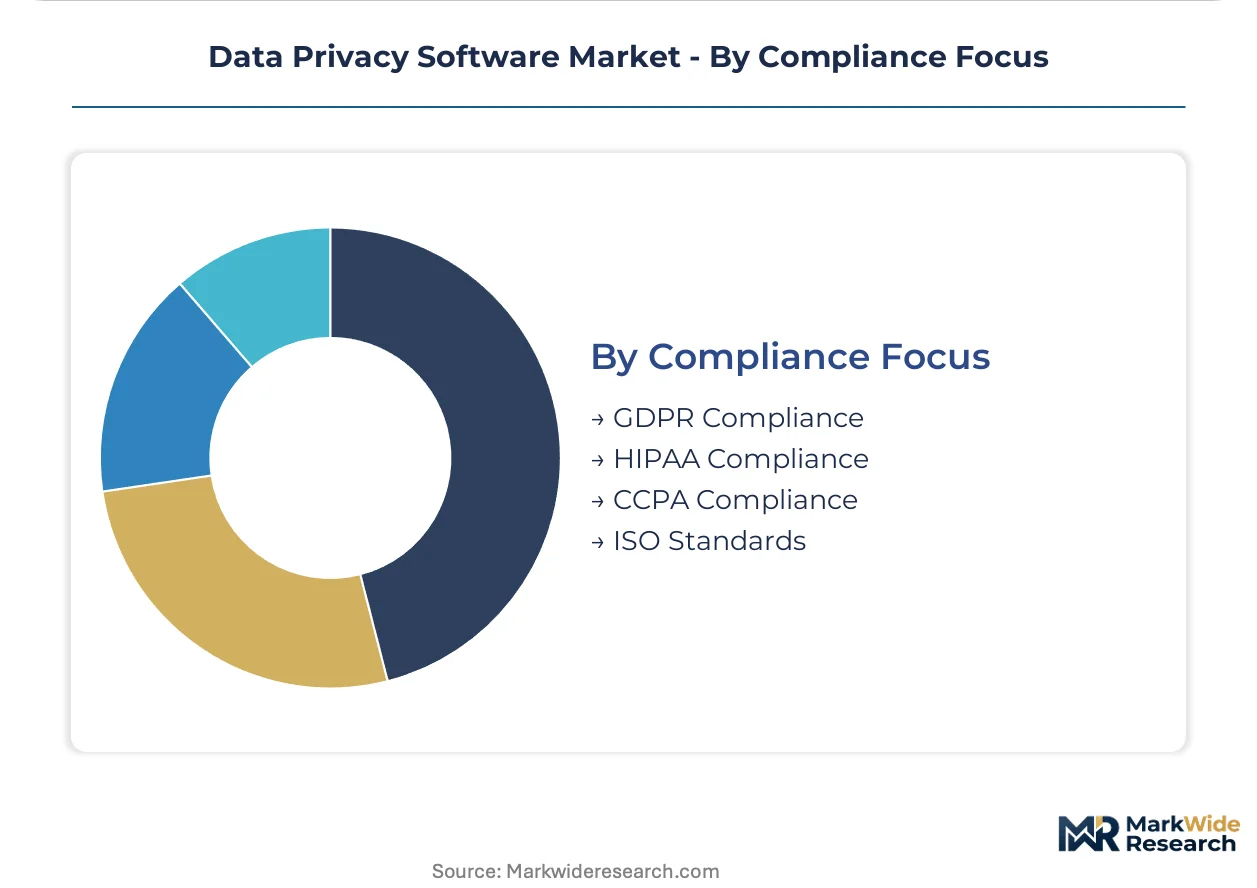
GDPR and HIPAA mandates drive the largest compliance software budgets due to supervisory authority enforcement intensity, while CCPA and ISO standards serve faster-growing but smaller addressable markets.
- GDPR Compliance:Article 35 data protection impact assessment automation and cross-border transfer documentation anchor enterprise procurement. European Data Protection Board enforcement against automated decision-making sustains demand.
- HIPAA Compliance:Minimum necessary standard enforcement and breach notification automation dominate United States health system purchasing. OCR audit frequency drives continuous monitoring investment.
- CCPA Compliance:Consumer rights automation and opt-out preference signaling serve California-headquartered enterprises with national customer bases.
- ISO Standards:ISO 27001 and 27701 certification support supplies multinational B2B vendors demonstrating baseline security and privacy management maturity.
GDPR compliance dominates installed base. HIPAA compliance is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors where sovereign data mandates inflate deployment budgets, while mid-market buyers in the United States compress vendor margins through metered SaaS procurement.
United States
Healthcare systems and financial institutions anchor enterprise demand for consent automation and breach response orchestration. State attorneys general under emerging privacy statutes intensify enforcement against cross-border data flows. Silicon Valley clusters and New York financial centers concentrate procurement of API-native architectures.
Germany
Automotive supply chains and industrial data spaces drive investment in localized privacy infrastructure with domestic encryption custody. BaFin guidance and EU AI Act risk classifications mandate algorithmic transparency for high-risk automated decision-making. Stuttgart and Munich engineering corridors embed privacy-by-design into supplier data exchange protocols.
United Kingdom
Mid-market enterprises favor rapid-deployment SaaS platforms with embedded AI functionality over comprehensive feature suites. Information Commissioner's Office enforcement against automated profiling sustains demand for assessment engines. London fintech clusters procure subject rights automation to satisfy cross-border transaction requirements.
France
Government agencies and healthcare consortiums deploy community cloud architectures with shared compliance certification. CNIL enforcement extends GDPR Article 35 obligations to AI-driven scoring systems. Paris and Lyon public sector hubs commission sovereign data processing infrastructure with domestic key management.
Switzerland
Private banking and wealth management institutions invest in hybrid deployments balancing FINMA audit expectations with cloud elasticity. Swissmedic and federal data protection authority guidance demands physical infrastructure inspection rights. Zurich and Geneva financial centers sustain premium pricing for dedicated tenancy solutions.
Data Privacy Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional depth but faster deployment cycles. The vendor base stratifies between comprehensive suite providers and best-of-breed point solutions. Three archetypes dominate: template-heavy enterprise anchors, AI-native discovery engines, and identity-centric warehouse integrators. Competitive moves concentrate on API ecosystem partnerships and sector-specific module development.
Within the enterprise platform tier, OneTrust and Securiti occupy positions defined by divergent technical architectures. OneTrust exemplifies the template-driven archetype with extensive pre-built regulatory libraries. Securiti represents autonomous data intelligence specialization, anchoring the AI-native discovery segment. BigID sits within the identity-centric tier, competing through deep cloud warehouse integration rather than breadth of compliance coverage.
| Leading Market Players |
|---|
| OneTrust |
| Securiti |
| BigID |
| TrustArc |
| AvePoint |
| Exterro |
| SAP |
| Osano |
| Experian |
| Others |
Supply Flow & Price Mechanics
Frankfurt-Dubai data corridor freight costs transmit directly into deployment pricing for German automotive suppliers requiring sovereign infrastructure, compressing margins for configured-to-order privacy stacks while amplifying differentiation premiums for standard SaaS tiers.
Pricing Analysis
The customization-premium spread in data privacy software spans three-to-five-fold between standard metered SaaS subscriptions and configured hybrid deployments with jurisdictional key custody. Subscription-based licensing with embedded AI functionality dominates mid-market procurement in the United States and United Kingdom, while project-based implementation fees anchor enterprise deployments in Germany and Switzerland. Price differentiation rests on certification depth—ISO 27701 and EU Cloud Code of Conduct compliance command substantial premiums—and vertical integration of autonomous discovery engines. Pricing pressure stems from hyperscaler marketplace bundling that commoditizes baseline consent management. Mid-market buyers exhibit highest price sensitivity, prioritizing rapid deployment over comprehensive feature coverage; financial institutions in Switzerland and Germany demonstrate lowest sensitivity due to FINMA and BaFin audit exposure.
Supply Chain Analysis
Upstream feedstock for data privacy software concentrates in cloud compute infrastructure provisioned across the United States, Germany, and Ireland, with API-native architecture components sourced from specialized Israeli and Estonian cybersecurity development clusters. Core dependencies include hyperscaler compute instances, encryption key management hardware, and natural language processing training datasets. Single-source vulnerability concentrates in AWS, Azure, and GCP infrastructure layers where privacy software deployments anchor. Distribution runs through cloud marketplaces and systems integrators rather than direct vendor relationships, with channel partners in London, New York, and Singapore capturing substantial implementation margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data privacy software constitutes a high-growth disruption propelled by EU AI Act enforcement mandating algorithmic transparency infrastructure that legacy compliance architectures cannot retrofit.
For Market Incumbents: Entrench enterprise relationships through vertical integration of autonomous data discovery capabilities and exclusive certification partnerships with national supervisory authorities. Defend against best-of-breed unbundling by embedding consent management, subject rights automation, and breach response into unified policy engines with pre-built GDPR and HIPAA templates. Prioritize capacity addition in German industrial corridors where sovereign data mandates inflate deployment budgets and lock in multi-year contracts. For New Entrants and Emerging Players: Mid-market healthcare organizations in the United States under emerging state health AI statutes represent the most penetrable entry point, with OCR audit frequency creating urgent demand for automated assessment engines underserved by template-heavy suites. API-native consent orchestration for cross-border e-commerce transactions across GDPR, LGPD, and PIPEDA jurisdictions offers secondary white-space. Go-to-market through cloud marketplace listings with metered licensing that scales with data volume rather than fixed enterprise contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive compliance software divisions lacking autonomous AI functionality—automotive supply chain privacy tools and healthcare de-identification modules present specific divestiture candidates. Long-term viability favors platforms with modular architectures capable of absorbing divergent sector-specific requirements without comprehensive rewrites. Watch EU AI Act implementation timelines and national supervisory authority staffing levels as inflection indicators for enforcement intensity and procurement urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified policy engines embedding consent, subject rights, and breach response reduce procurement friction for multinational enterprises under GDPR Article 35. |
| Acquisition of Specialist Firm | Autonomous data discovery capabilities from Israeli NLP clusters accelerate time-to-value for healthcare AI governance deployments. |
| Geographic Expansion | German industrial data spaces and automotive supply chain requirements concentrate premium pricing for localized privacy infrastructure. |
| Strategic Partnership | Hyperscaler marketplace listings displace direct sales channels for mid-market buyers prioritizing rapid provisioning. |
| Product Launch | Sector-specific modules for financial services hybrid deployments address FINMA and BaFin jurisdictional residency mandates. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Chief Privacy Officers, IT procurement officers at health systems and banks, platform engineers, and systems integrators; and secondary validation through SEC filings, hyperscaler capex disclosures, EDPB enforcement decisions, and hospital procurement databases. Bottom-up sizing of vendor-reported deployments triangulated against top-down regulatory mandate expansion models across the analysis window.
Forecast inputs incorporated deployment architecture preferences, compliance scope expansion, and end-user vertical adoption curves across the projection horizon. Segmentation dimensions modeled include product type, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derived from historical penetration rates adjusted for enforcement intensity inflections and AI Act implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in enterprise software spending cycles and cloud infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions regarding supervisory authority staffing and cross-border transfer mechanism stability. Cross-checking against EDPB enforcement statistics and vendor booking disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
Stalkerware Market
Security Software
Data Masking Technology Market
Security Software
Europe Encryption Software Market
Security Software
Parental Monitoring Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Global Digital Signature Software Market
Security Software
Global Reputation Protection Software Market
Security Software
Europe Lawful Interception Market
Security Software
Secure Digital Card Market
Security Software
US Evidence Management Market
Security Software
Facial Recognition Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Keystroke Dynamics Market