
 Battery-Powered Doorbell Camera Market | 2026-2036
Battery-Powered Doorbell Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Battery-Powered Doorbell Camera Market Insights
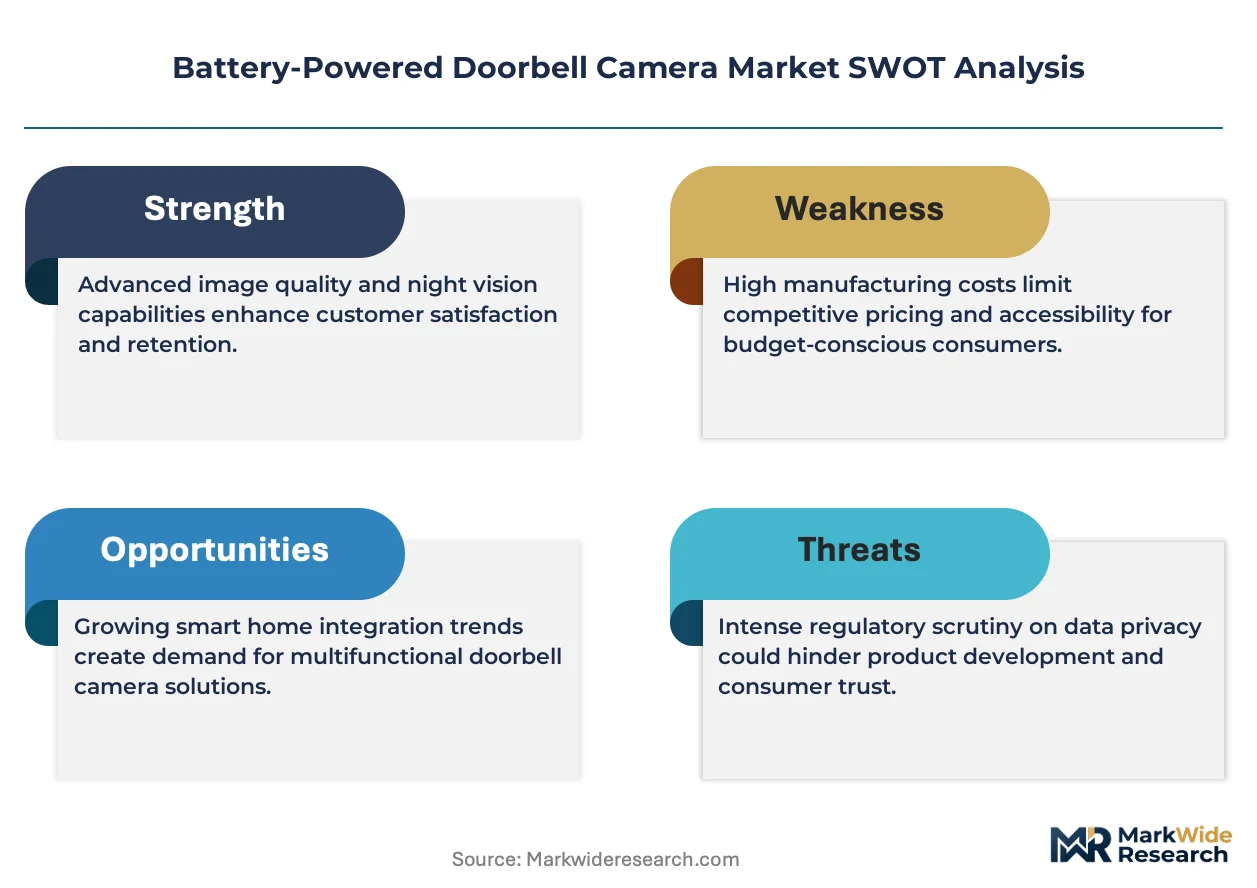
The EU Green Deal is shifting procurement criteria across European consumer electronics retail chains toward energy-efficient connected home devices. Amazon (Ring) leverages its subscription ecosystem to sustain recurring revenue attachment rates on hardware sales. Eufy (Anker) differentiates through local storage architectures that reduce cloud dependency and appeal to privacy-conscious buyers. Arlo Technologies anchors its position in the premium segment through advanced AI-powered motion detection capabilities.
A battery-powered doorbell camera is a self-contained video capture and communication device operating on rechargeable or replaceable battery cells, typically featuring Wi-Fi connectivity, 1080p or higher resolution sensors, passive infrared motion detection, and two-way audio streaming for remote visitor interaction. These units eliminate hardwired installation requirements, enabling deployment on rental properties and structures lacking existing doorbell transformer infrastructure. The wireless product type leads unit shipments due to frictionless DIY installation, while smart variants command margin premiums through AI analytics and third-party home automation platform integration. HD technology dominates the specification baseline, though motion detection capabilities increasingly determine upgrade cycles and replacement demand across homeowner and property manager segments.
The Federal Communications Commission shapes radio frequency certification requirements for Wi-Fi and proprietary wireless protocols used in these devices, while the EU AI Act imposes transparency obligations on automated facial recognition and behavioral analytics features. The Consumer Product Safety Commission oversees lithium-ion battery thermal safety standards that directly impact product design and recall exposure. Stakeholders must monitor evolving cybersecurity labeling mandates from multiple regulators, as firmware vulnerability disclosure requirements become a determinant of market access rather than merely a competitive differentiator.
Market Dynamics
The EU Green Deal's low-power IoT device standards are redirecting R&D budgets toward energy-efficient chipset architectures, compressing development timelines for battery optimization while elevating compliance costs for manufacturers serving European distribution channels.
Growth Catalysts
- Suburban Homeownership Transitions:Rental-to-ownership accelerations in single-family markets are generating first-time smart home purchases without existing doorbell transformer infrastructure, favoring wireless installations.
- REACH Compliance-Driven Design:European chemical substance restrictions are forcing component substitutions that coincidentally reduce power consumption, extending operational intervals between battery charges.
- Local Storage Architectures:Edge-computing video processing eliminates continuous cloud uplink requirements, reducing bandwidth costs and appealing to privacy-sensitive consumer segments.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode material processing clusters in East Asian manufacturing hubs create input cost volatility and geopolitical exposure for battery cell procurement.
- FCC Certification Friction:Radio frequency testing protocols for Wi-Fi and proprietary wireless stacks extend product launch timelines by four to eight months for new market entrants.
- Hardwired Substitute Competition:Existing doorbell transformer infrastructure in pre-2010 housing stock sustains demand for wired alternatives with superior video resolution and no charging maintenance.
Strategic Opportunities
- German Market Premium Positioning:Consumer willingness to pay for subscription-integrated hardware outpaces other European markets, supporting margin capture through bundled service offerings.
- GDPR-Aligned Privacy Marketing:Data localization features and transparent processing disclosures convert regulatory compliance into competitive differentiation against cloud-dependent rivals.
- AI-Edge Convergence:On-device neural processing unit integration enables real-time facial recognition and package detection without latency-heavy server roundtrips.
Industry Challenges
- Firmware Security Talent Scarcity:Embedded systems engineering expertise for over-the-air update architectures and vulnerability patch management commands premium compensation in competitive labor markets.
- Multi-Regulatory Certification Overlap:Simultaneous FCC, CE marking, and EU AI Act compliance requirements create documentation burdens and testing redundancy that strain mid-tier manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery-Powered Doorbell Camera Market |
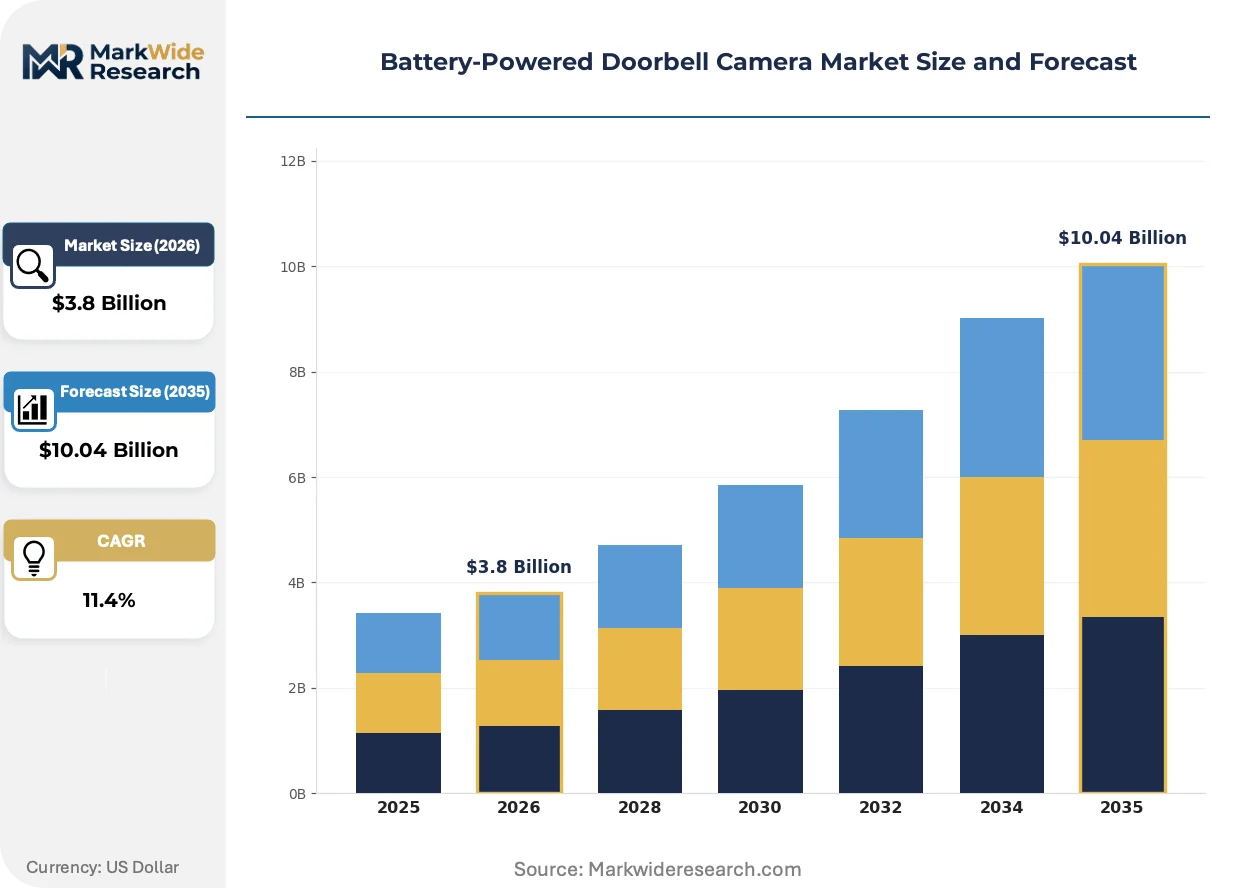
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless, Wired, Smart, Standard Technology: HD, Infrared, Two-Way Audio, Motion Detection End User: Homeowners, Renters, Property Managers, Builders Installation: DIY, Professional, Remote, Home Automation |
| Companies Covered | Amazon (Ring), Google (Nest), Arlo Technologies, Eufy (Anker), ADT, Wyze, TP-Link, Blink, Reolink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery-Powered Doorbell Camera Market Trends and Innovations
Energy harvesting and on-device intelligence are compressing the traditional trade-off between wireless convenience and performance capabilities, enabling feature parity with hardwired alternatives.
Silicon-carbide power management integrated circuits are consolidating discrete voltage regulation components into single-chip solutions. Mid-tier manufacturers are adopting these architectures fastest as they seek to reduce bill-of-materials complexity without sacrificing battery life. The structural consequence is that premium-tier feature sets are consolidating into standard product configurations, eroding historical price stratification.
The EU AI Act's transparency obligations for automated biometric identification are forcing disclosure redesigns in companion mobile applications. Device manufacturers must now embed explicit consent workflows and algorithmic explanation interfaces before facial recognition activation. German retailers are demanding pre-certified compliance documentation before listing products, shifting certification timelines earlier in development cycles.
Subscription unbundling from hardware purchases is accelerating among privacy-conscious buyer segments who reject recurring cloud storage fees. Direct-to-consumer channels and specialty security retailers are capturing this demand with local-storage-first positioning. This pattern concentrates most visibly in suburban markets where technical sophistication and data sovereignty concerns overlap.
Battery-Powered Doorbell Camera Market Segmentation
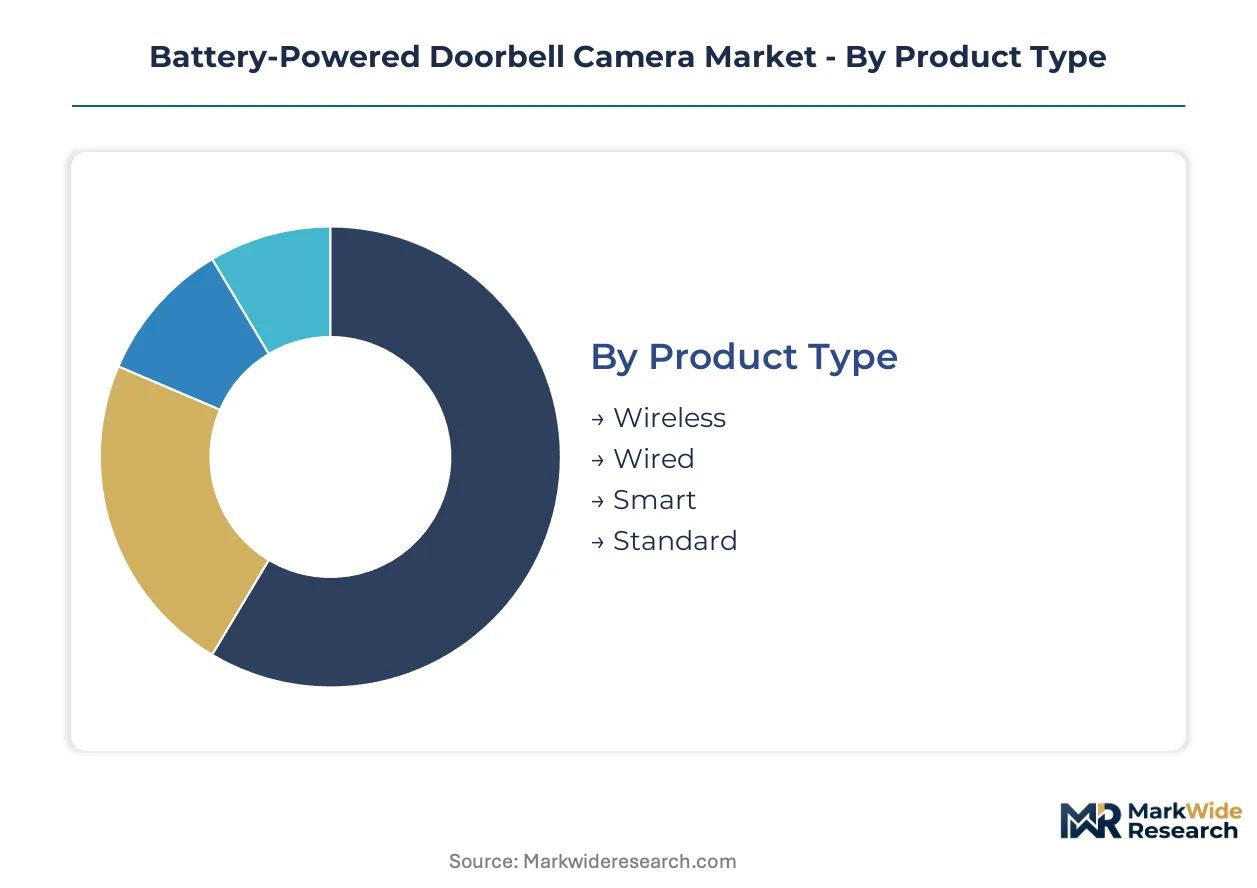
Segmentation in battery-powered doorbell cameras reveals distinct procurement patterns across installation constraints, technical sophistication, and ownership structures. Each dimension carries different margin profiles and regulatory exposure, shaping how manufacturers configure product portfolios.
Product Type:
Buyer differentiation centers on infrastructure availability and willingness to accept recurring subscription costs versus upfront hardware premiums.
- Wireless:Self-contained units operate on rechargeable or replaceable battery cells without doorbell transformer dependency. Demand concentrates among renters and suburban first-time homeowners lacking existing low-voltage wiring, driven by frictionless DIY installation and portability between residences.
- Smart:AI-enabled variants integrate on-device neural processing for facial recognition, package detection, and third-party home automation platform connectivity. German consumers demonstrate the strongest willingness to pay subscription-integrated hardware premiums, supporting margin capture through bundled cloud analytics.
- Wired:Battery-assisted units supplement existing doorbell transformer infrastructure for enhanced video resolution and continuous power. Property managers of pre-2010 housing stock favor these for reduced maintenance overhead.
- Standard:Entry-tier products deliver core video capture and two-way audio without AI analytics or advanced motion zones. Price-sensitive segments in rental markets drive volume here.
Wireless leads volumes today; Smart is gaining share fastest.
Technology:
Specification hierarchies determine replacement cycles and upgrade propensity across homeowner and commercial segments.
- HD:1080p resolution sensors establish the baseline specification across all price tiers. German retailers now require minimum HD certification for shelf placement, compressing sub-HD inventory.
- Motion Detection:Passive infrared and radar-based systems trigger recording and mobile alerts. Advanced variants with customizable activity zones command upgrade premiums from security-conscious suburban homeowners.
- Two-Way Audio:Full-duplex voice streaming enables remote visitor interaction. Package delivery coordination drives adoption among e-commerce-intensive households.
- Infrared:Night vision capabilities using near-infrared LED arrays maintain visibility in zero-light conditions. Standard inclusion across mid-tier and above eliminates standalone positioning.
HD dominates installed base; Motion Detection is climbing the fastest.
End User:
Ownership tenure and decision-making authority create divergent purchasing behaviors around installation complexity and data control.
- Homeowners:Single-family owner-occupiers prioritize local storage architectures and privacy controls. Suburban markets experiencing rental-to-ownership transitions generate first-time smart home purchases without existing infrastructure.
- Property Managers:Multi-unit operators standardize on remote management platforms and bulk procurement contracts. FCC certification documentation requirements extend vendor qualification timelines.
- Renters:Transient residents demand portable, lease-compliant installations without structural modifications. Wireless products satisfy this constraint exclusively.
- Builders:New construction developers pre-specify devices during framing for competitive differentiation. EU Green Deal low-power standards increasingly influence RFP criteria.
Homeowners anchor current demand; Property Managers show steepest expansion trajectory.
Installation:
Technical capability and integration ambition separate self-service adopters from ecosystem-dependent buyers.
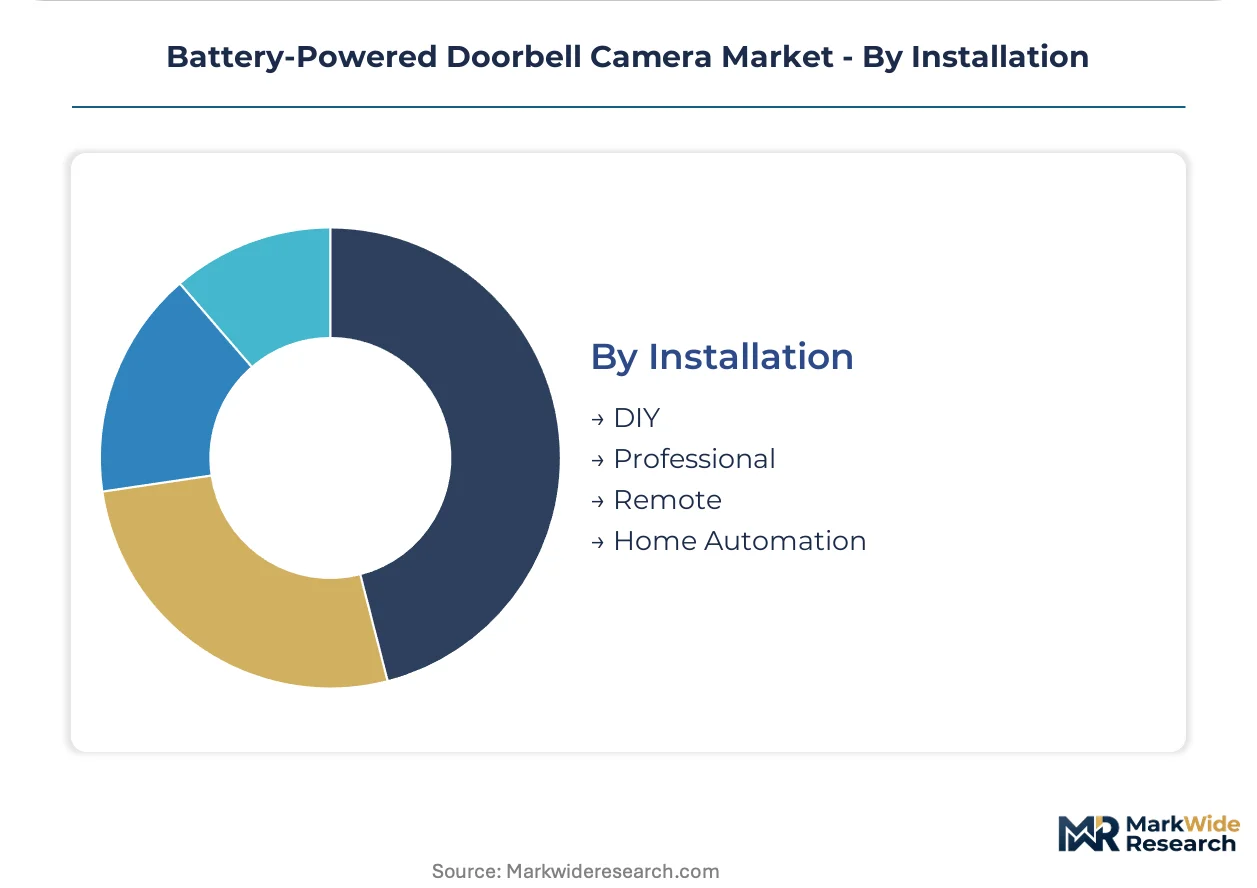
- DIY:Consumer self-installation via adhesive mounts or screw-fixed brackets dominates unit shipments. Wireless product compatibility enables this channel.
- Home Automation:Deep integration with platforms like Amazon Alexa, Google Home, or Apple HomeKit requires technical configuration. Privacy-conscious buyers favor local-control architectures over cloud-dependent alternatives.
- Professional:Certified installer deployment ensures optimal positioning and network configuration. Premium segment buyers absorb labor costs for guaranteed performance.
- Remote:Managed service providers handle configuration, monitoring, and maintenance. Commercial multi-site deployments utilize this model.
DIY commands volume leadership; Home Automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The battery-powered doorbell camera industry traces its commercial scaling to Silicon Valley's consumer electronics ecosystem, where Wi-Fi-enabled home security devices first achieved mass-market distribution through e-commerce channels before expanding into European and Asian markets.
United States
Suburban homeownership transitions and rental-to-ownership migrations in Sun Belt metros drive first-time smart home purchases without existing doorbell transformer infrastructure. The FCC shapes radio frequency certification requirements for Wi-Fi and proprietary wireless protocols, extending product launch timelines for new entrants. Austin and Seattle host dense clusters of IoT hardware engineering talent developing edge-computing video processing architectures.
Germany
Consumer willingness to pay for subscription-integrated hardware outpaces other European markets, supporting margin capture through bundled service offerings. The EU Green Deal's low-power IoT device standards redirect R&D budgets toward energy-efficient chipset architectures for manufacturers serving German distribution channels. Berlin and Munich concentrate smart home retail chains demanding pre-certified EU AI Act compliance documentation before product listings.
China
Component manufacturing clusters in Shenzhen and Dongguan dominate lithium-ion battery cell assembly and silicon-carbide power management integrated circuit production. MIIT oversees national standards for wireless transmission protocols and cybersecurity labeling mandates that increasingly determine market access. The Yangtze River Delta region anchors OEM/ODM production capacity serving global brand customers with compressed development timelines.
United Kingdom
GDPR-aligned privacy marketing converts data localization features into competitive differentiation against cloud-dependent rivals in London and Southeast England residential markets. The UK Information Commissioner's Office enforces transparency obligations on automated biometric identification that shape companion mobile application designs. Cambridge hosts edge-AI semiconductor design firms supplying neural processing units for on-device facial recognition capabilities.
Japan
Apartment-dwelling consumers in Tokyo and Osaka prioritize compact, lease-compliant installations without structural modifications, favoring wireless product configurations. METI promotes interoperability standards for home automation platform integration that reduce vendor lock-in. Nagoya's industrial corridor supplies precision motion detection sensors and infrared LED arrays for night vision capabilities.
Battery-Powered Doorbell Camera Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the battery-powered doorbell camera landscape. The vendor base organizes into three tiers: vertically integrated platform operators with subscription ecosystems, specialist hardware manufacturers with local storage differentiation, and value-oriented OEMs serving price-sensitive channels. Strategic moves concentrate on M&A for AI talent acquisition and geographic expansion into German retail networks.
Among platform-integrated operators, Amazon (Ring) and Google (Nest) occupy positions defined by cloud-service attachment and home automation ecosystem control. Arlo Technologies exemplifies the premium-tier specialist archetype, while Eufy (Anker) represents local-storage-first positioning that reduces cloud dependency. Wyze anchors the value-tier segment through direct-to-consumer distribution models.
| Leading Market Players |
|---|
| Amazon (Ring) |
| Google (Nest) |
| Arlo Technologies |
| Eufy (Anker) |
| ADT |
| Wyze |
| TP-Link |
| Blink |
| Reolink |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot pricing volatility cascades through battery cell procurement contracts into tiered hardware pricing, compressing margins for mid-tier manufacturers while amplifying subscription bundling premiums for platform operators with captive cloud revenue streams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled smart variants with neural processing units from HD-baseline wireless units and entry-tier standard configurations lacking motion analytics. Certification grade differentiation—particularly FCC and EU AI Act pre-certification—commands shelf placement premiums at German retail chains. Cost compression in the economy tier is intensifying because silicon-carbide power management integrated circuit adoption consolidates discrete components, eroding historical feature stratification. Renters and first-time suburban homeowners exhibit highest price sensitivity, while German owner-occupiers demonstrate lowest sensitivity to subscription-integrated hardware premiums.
Supply Chain Analysis
Single-source vulnerability sits with cathode material processing clusters in China, South Korea, and Japan that dominate lithium-ion battery cell assembly for downstream OEM integration. Silicon-carbide substrates and neural processing units draw from Taiwan semiconductor foundries and Yangtze River Delta packaging facilities. Tariff exposure on Chinese-origin battery components threatens input cost stability for manufacturers lacking diversified sourcing. Distribution runs through Amazon and direct-to-consumer channels for volume leadership, with German specialty security retailers capturing privacy-conscious segments through local-storage-first positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery-powered doorbell camera market reads as a late-cycle quality story where upgrade cycles increasingly hinge on on-device AI capabilities rather than resolution specifications alone.
For Market Incumbents: Deepen vertical integration into edge-AI semiconductor design through acquisition of Cambridge-based neural processing unit specialists, insulating against talent scarcity in firmware security engineering. Fortify German retail channel control by pre-certifying EU AI Act compliance documentation before competitor submission windows. Cloud-dependent platform operators face displacement risk from local-storage-first entrants capturing privacy-conscious suburban homeowners. For New Entrants and Emerging Players: Begin with GDPR-aligned privacy marketing in UK and German suburban markets where data sovereignty concerns overlap with technical sophistication, converting regulatory compliance into competitive differentiation. Target property manager segments with remote management platform integration and bulk procurement contracting, a white-space application underserved by consumer-focused incumbents. Pursue direct-to-consumer distribution with transparent algorithmic explanation interfaces. For Investors and Strategic Acquirers: Asymmetric upside sits with local-storage-first hardware specialists possessing edge-computing video processing architectures and reduced cloud dependency. Five-to-ten year viability hinges on energy harvesting integration and on-device intelligence consolidation eroding wireless-hardwired performance gaps. Monitor FCC certification timeline compression as signal of regulatory arbitrage opportunity for agile entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Semiconductor Acquisition | Captures scarce neural processing unit design talent before labor cost inflation accelerates. |
| EU AI Act Pre-Certification Investment | Secures German retail shelf placement ahead of Berlin and Munich listing requirements. |
| Local-Storage-First Product Repositioning | Converts GDPR compliance into subscription unbundling appeal for privacy-sensitive buyers. |
| Silicon-Carbide Power Management Integration | Reduces bill-of-materials complexity while extending battery operational intervals. |
| Property Manager Channel Development | Captures bulk procurement contracts with multi-unit operators standardizing remote management platforms. |
Research Methodology
Multiple input streams — primary interviews with IoT hardware engineering directors, smart home retail category buyers, and property management procurement leads; secondary validation through FCC certification databases, EU regulatory filings, and lithium carbonate pricing benchmarks; plus customs trade data on battery component flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment volumes were cross-referenced against panel input from semiconductor foundry capacity planners and edge-AI chip design firms across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user ownership structure, and installation complexity. CAGRs were derived from fitted growth curves incorporating EU Green Deal low-power standard adoption curves and suburban homeownership transition rates.
Caveats apply where lithium-ion supply concentration, FCC certification timeline extensions, or AI Act disclosure redesign requirements could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Europe Enterprise Firewall Market
Security Software
Banking Encryption Software Market
Security Software
Stalkerware Market
Security Software
Information Rights Management Market
Security Software
Global Network Encryption Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Security Testing Market
Security Software
Personal Data Recovery Software Market
Security Software
United States Lawful Interception Market
Security Software
Security Information and Event Management Software Market
Security Software
Global Cloud IAM Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Global User Activity Monitoring Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Global Network Security Software Market
Security Software
Key Management Service Market